
 Latex Agglutination Test Market | 2026-2036
Latex Agglutination Test Market Size, Share, and Industry Trends Forecast 2026-2036
Latex Agglutination Test Market Outlook
European reagent manufacturers is repositioning toward automated latex agglutination workflows to reduce manual processing costs. Thermo Fisher Scientific leverages its diagnostic reagent infrastructure to sustain kit standardization across hospital networks. bioMérieux S.A. anchors its competitive stance through specialized pathogen detection panels that integrate with existing laboratory information systems.
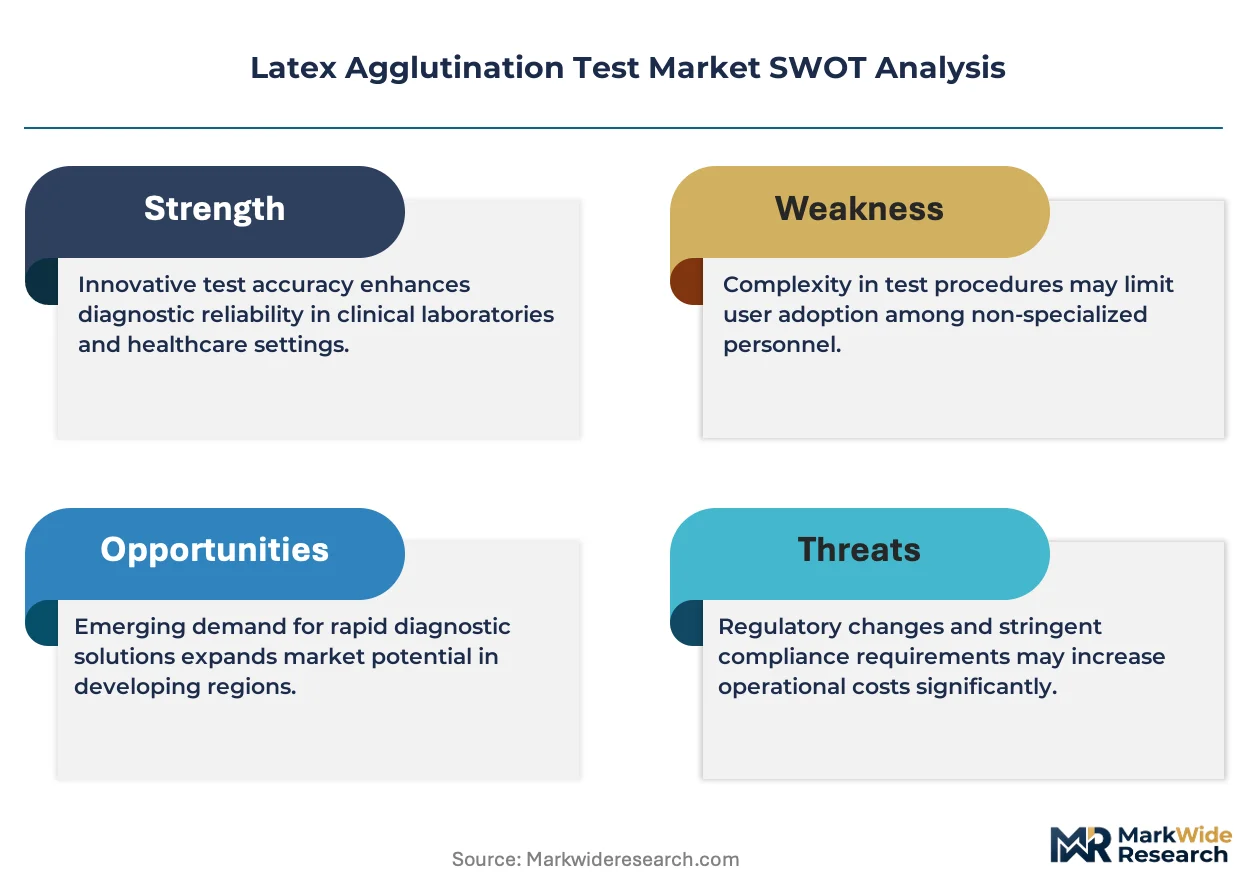
Latex agglutination tests employ antibody-coated polystyrene particles that cross-link in the presence of target antigens, producing visible clumping within 2-15 minutes for qualitative or semi-quantitative analysis. The technology serves primarily as a cost-effective screening tool for infectious disease serology and blood typing in moderate-complexity laboratory settings. Diagnostic kits command the largest revenue share due to bundled reagent consumption and recurring purchase contracts, while flow cytometry-enhanced variants represent the fastest-expanding technology segment as laboratories seek objective particle counting. Research institutes occupy a narrower but higher-margin niche where custom antigen coatings support assay development.
FDA clearance pathways and CLIA complexity categorization determine which laboratories can operate specific latex agglutination platforms, directly constraining addressable end-user expansion. The EU In Vitro Diagnostic Regulation (IVDR) is elevating clinical evidence requirements for legacy assays, forcing manufacturers to rebalance product portfolios between regulated and research-use-only channels. Stakeholders must monitor how decentralized diagnostic authorization frameworks reshape competitive access across hospital and reference laboratory procurement hierarchies.
Market Dynamics
Laboratory automation mandates and CLIA complexity reclassification are compressing manual testing margins while elevating capital requirements for diagnostic platforms. Manufacturers face pressure to consolidate reagent portfolios around scalable, instrument-compatible formats.
Growth Catalysts
- CLIA Moderate-Complexity Expansion:The FDA's streamlined 510(k) pathways for serology platforms enable hospital laboratories to bring infectious disease screening in-house, reducing send-out volumes to reference labs.
- Polystyrene Microsphere Refinement:Uniform particle synthesis advances are improving test reproducibility and reducing lot-to-lot variability that previously required extensive validation.
- Blood Bank Consolidation:Centralized transfusion service networks in the United States are standardizing immunohematology protocols, creating recurring demand for high-throughput agglutination systems.
Market Restraints
- Antibody Raw Material Concentration:Polyclonal antibody production concentrates among a limited set of contract manufacturers, exposing kit producers to yield variability and lead time extension.
- EU IVDR Technical Documentation Burden:Legacy latex agglutination assays face elevated clinical evidence requirements for CE marking renewal, forcing portfolio rationalization toward higher-volume SKUs.
- Molecular Nucleic Acid Amplification Substitution:PCR and isothermal amplification methods are capturing share in infectious disease confirmation testing where pathogen identification specificity outweighs cost sensitivity.
Strategic Opportunities
- Decentralized Testing Authorization:FDA emergency use authorization frameworks established during respiratory virus surges create precedent for point-of-care latex agglutination deployment in pharmacy and urgent care settings.
- Veterinary Diagnostic Crossover:Companion animal serology panels for vector-borne pathogens represent an underdeveloped channel with lower regulatory barriers and premium pricing tolerance.
- Flow Cytometry Convergence:Objective particle enumeration systems are integrating with traditional slide agglutination workflows, enabling quantitative titer reporting that satisfies laboratory information system integration requirements.
Industry Challenges
- ASCP-Certified Medical Laboratory Scientist Scarcity:Personnel shortages in clinical laboratory science programs constrain operational scaling for moderate-complexity testing sites.
- LIS Middleware Integration Complexity:Proprietary instrument communication protocols require custom interface development, extending implementation timelines and elevating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex Agglutination Test Market |
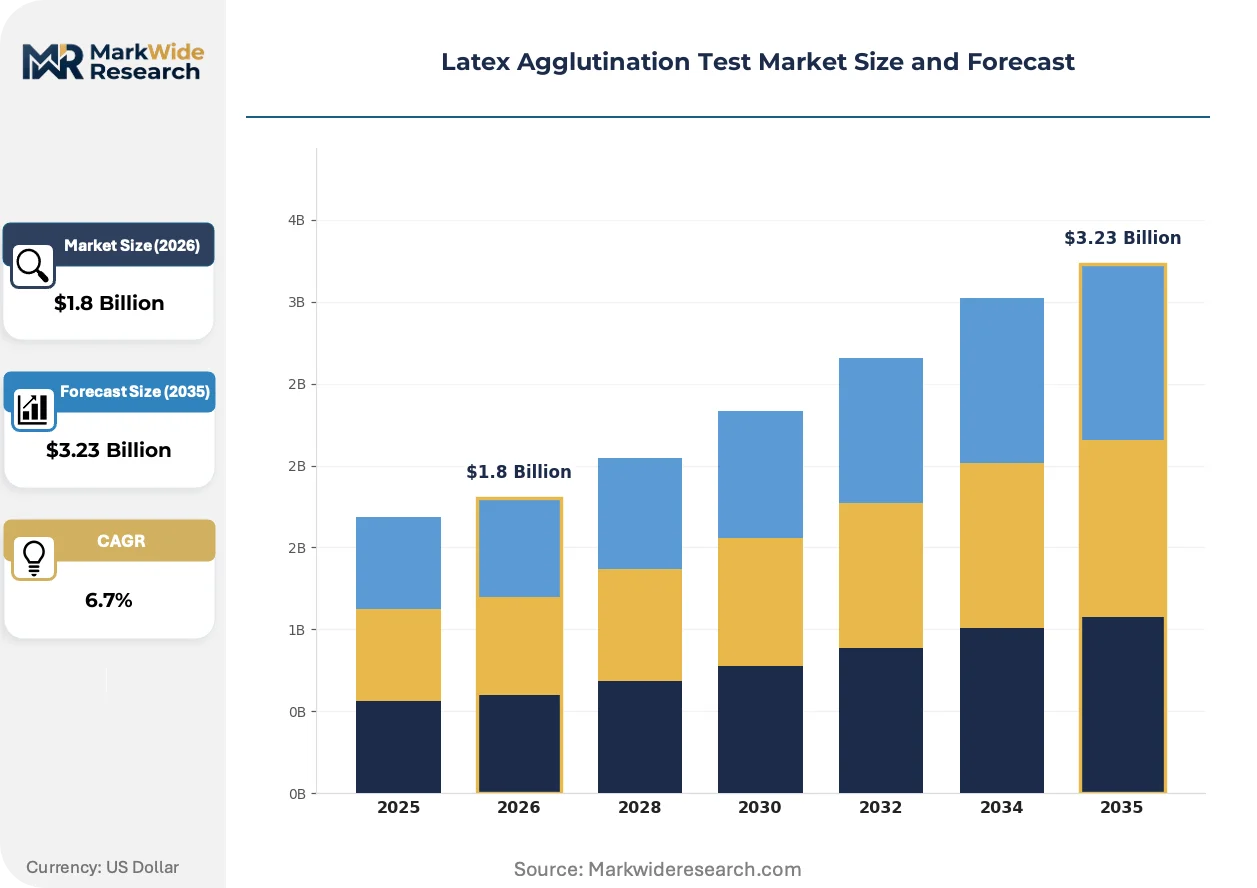
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Reagents, Control Materials, Others Application: Infectious Diseases, Autoimmune Disorders, Blood Typing, Allergy Testing End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutes Technology: Microscopy, Flow Cytometry, Chemiluminescence, Enzyme Immunoassay |
| Companies Covered | Thermo Fisher Scientific Inc., bioMérieux S.A., Atlas Medical GmbH, Cardinal Health, Bio-Rad Laboratories, Inc., HiMedia Laboratories, Eurofins Abraxis, BioLegend Inc., Hardy Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex Agglutination Test Market Strategic Shifts
Automation architecture and objective readout technologies are displacing visual interpretation methods that have defined latex agglutination for decades. These shifts compress processing time while elevating data integrity standards for regulatory compliance.
Digital imaging systems with machine learning classification algorithms are integrating into slide agglutination platforms to eliminate operator-dependent result interpretation. Reference laboratories in the United States are adopting these systems to support high-volume infectious disease serology menus. The technology is integrating quality control traceability directly into laboratory information system workflows, reducing manual documentation overhead.
The EU In Vitro Diagnostic Regulation is elevating performance evaluation requirements for legacy qualitative assays, compelling manufacturers to generate clinical evidence from retrospective sample banks. Diagnostic kit producers are responding by narrowing product portfolios to focus resources on high-throughput platforms with defendable clinical utility. Blood banking applications face particular scrutiny given the critical nature of transfusion compatibility determinations.
Hospital laboratory purchasing is consolidating through group purchasing organizations and integrated delivery network procurement committees, compressing vendor negotiation cycles and standardizing reagent specifications. Independent reference laboratories are losing share to hospital-affiliated testing sites with captive patient volumes. The United States exhibits the most pronounced concentration, where health system mergers have reduced the number of independent purchasing decision points by half over the past decade.
Latex Agglutination Test Market Segmentation
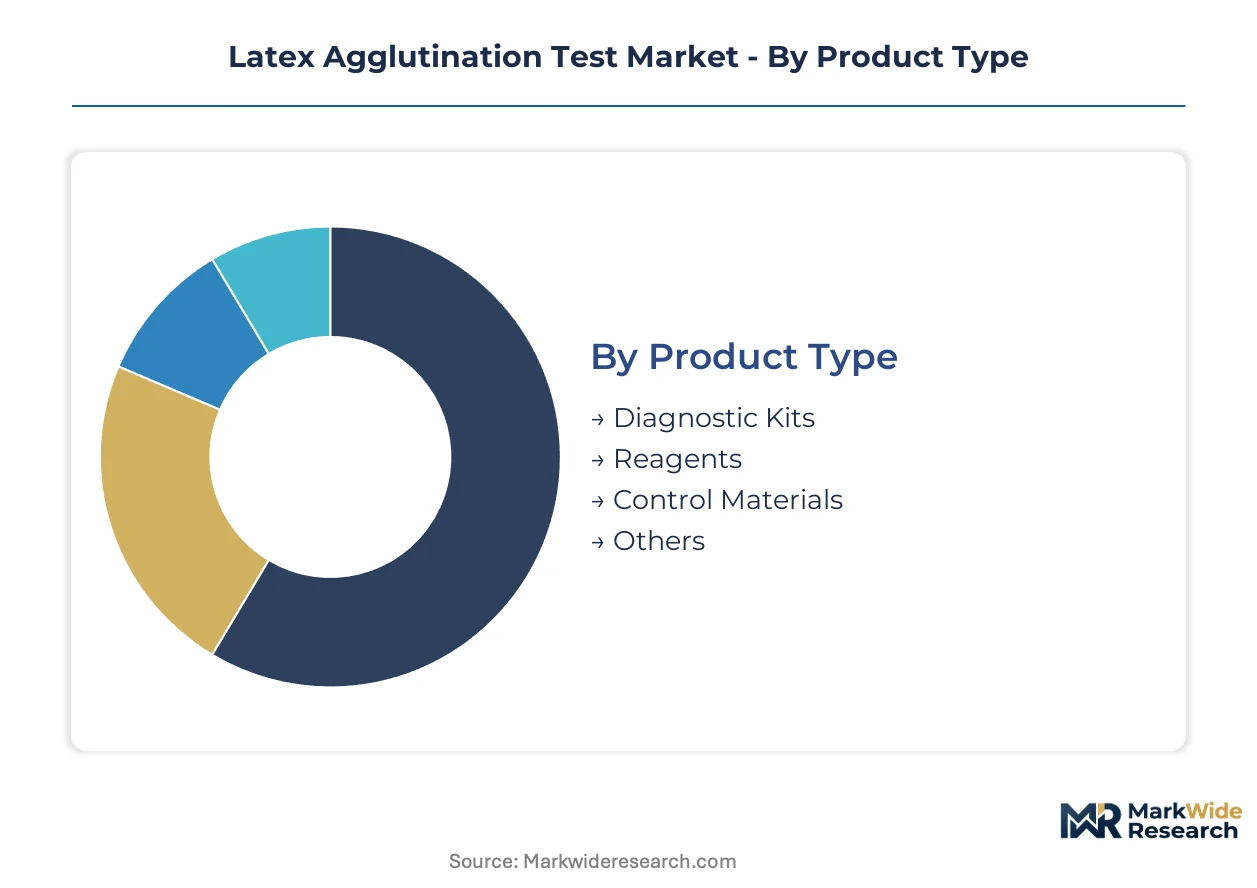
Latex agglutination test segmentation reveals distinct regulatory pathways and margin structures across product formats and end-use environments. Each category carries specific CLIA complexity classifications and IVDR technical documentation burdens that shape manufacturer portfolio strategies.
Product Type:
FDA 510(k) clearance requirements and IVDR clinical evidence thresholds vary sharply across product formats, with bundled reagent systems facing the most stringent post-market surveillance obligations.
- Diagnostic Kits:Pre-configured antibody-coated particle systems with standardized buffers and reaction matrices. Hospital laboratories in the United States concentrate procurement through group purchasing organizations, driving volume discounts and multi-year supply agreements that lock in reagent consumption.
- Reagents:Bulk antisera and particle suspensions requiring in-house validation and quality control protocols. Moderate-complexity CLIA laboratories favor these for cost flexibility, though polyclonal antibody yield variability from contract manufacturers extends lead times unpredictably.
- Control Materials:Validated positive and negative reference standards for assay calibration. Reference laboratories in Europe demand these under IVDR performance evaluation mandates for legacy assay maintenance.
- Others:Ancillary consumables including reaction cards, pipette tips, and dilution buffers. These capture thinner margins but secure recurring attachment revenue.
Leading the category by volume: Diagnostic Kits. Growing fastest: Reagents.
Application:
Application-specific demand concentrates where serology screening offers cost advantages over nucleic acid amplification methods, with blood banking protocols commanding the most rigid standardization requirements.
- Infectious Diseases:Serological screening for bacterial and viral pathogens using antibody detection or antigen capture formats. Hospital-affiliated laboratories in the United States are expanding in-house menus under streamlined 510(k) pathways, reducing send-out volumes to reference facilities.
- Autoimmune Disorders:Rheumatoid factor and antinuclear antibody panels employing latex-enhanced turbidimetry. Specialty reference laboratories maintain higher margins here due to complex interpretation requirements and lower test frequency.
- Blood Typing:Immunohematology protocols for transfusion compatibility determination. Centralized transfusion service networks standardize on high-throughput agglutination systems with objective readout capabilities.
- Allergy Testing:Specific IgE detection against environmental and food allergens. This segment occupies a narrower niche where allergist office laboratories seek waived or moderate-complexity alternatives to serum IgE quantification.
Infectious Diseases generates the largest absolute volume. Blood Typing maintains the most stable procurement cycles. Autoimmune Disorders climbs fastest as rheumatology panels expand.
End User:
End-user categories separate by capital intensity and regulatory authorization scope, with hospital consolidation reshaping purchasing hierarchies across all segments.
- Hospitals:Integrated delivery networks with captive patient volumes and centralized laboratory operations. These sites command preferred pricing through multi-hospital contracts and are displacing independent reference laboratories in the United States.
- Laboratories:Independent clinical and reference facilities performing moderate-complexity testing under CLIA certification. Personnel shortages in medical laboratory science programs constrain operational scaling for this channel.
- Diagnostic Centers:Outpatient-focused facilities emphasizing rapid turnaround and walk-in accessibility. Pharmacy and urgent care settings are emerging as decentralized testing sites under emergency use authorization precedents.
- Research Institutes:Academic and commercial R&D operations requiring custom antigen coatings and assay development support. This niche commands premium pricing with lower regulatory barriers but smaller absolute volumes.
Hospitals lead procurement volume. Diagnostic Centers expand most quickly. Research Institutes defend the highest margins per test.
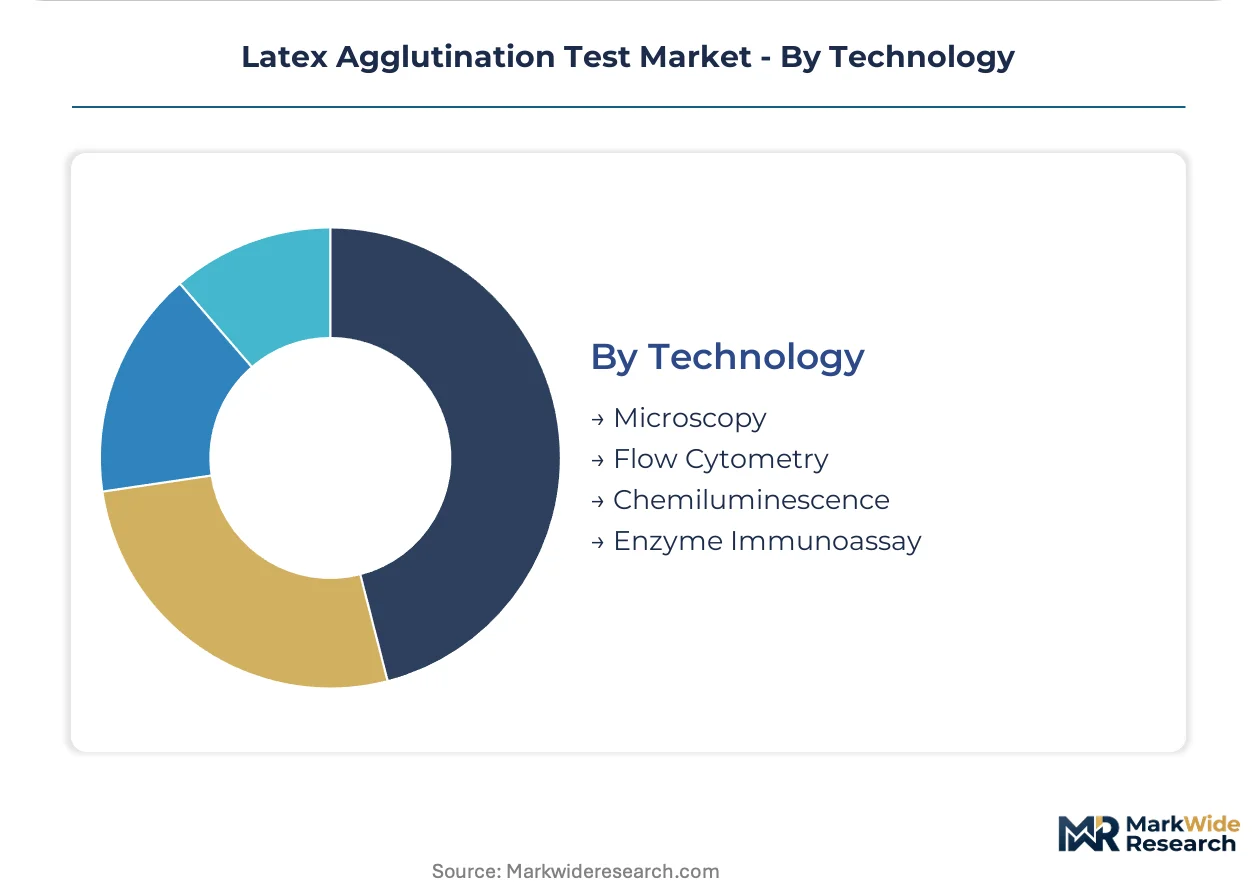
Technology:
Technology selection determines objective readout capability and laboratory information system integration depth, with automated platforms displacing manual interpretation methods.
- Microscopy:Visual slide agglutination assessment requiring trained operator interpretation. Moderate-complexity sites retain this for low-volume or STAT testing where capital investment in automation is unjustified.
- Flow Cytometry:Objective particle enumeration with quantitative titer reporting and digital traceability. Reference laboratories in the United States adopt these systems to satisfy laboratory information system middleware requirements and reduce documentation overhead.
- Chemiluminescence:Signal amplification through luminescent substrate detection. This hybrid approach bridges traditional agglutination with automated immunoassay platforms in high-throughput hospital laboratories.
- Enzyme Immunoassay:Colorimetric endpoint detection with plate-based throughput. Blood banking networks standardize on these for batch processing efficiency in transfusion service operations.
Microscopy retains the largest installed base. Flow Cytometry gains share fastest. Chemiluminescence occupies the middle tier for upgrade pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polystyrene microsphere production concentrates in the United States and Germany, anchoring reagent supply chains for diagnostic manufacturers. Hospital consolidation and regulatory divergence are reshaping procurement patterns across major laboratory markets.
United States
Hospital-affiliated laboratories expand infectious disease screening menus under streamlined FDA 510(k) pathways, reducing reference lab send-out volumes. CLIA moderate-complexity certification requirements constrain which facilities can operate specific agglutination platforms. The Research Triangle Park cluster in North Carolina hosts contract manufacturers supplying antibody-coated particles to kit producers nationwide.
Germany
Centralized transfusion service networks standardize immunohematology protocols, creating stable demand for high-throughput agglutination systems. The EU IVDR elevates clinical evidence requirements for legacy assay CE marking renewal, forcing portfolio rationalization. The Rhine-Main metropolitan region around Frankfurt maintains dense concentrations of diagnostic reagent distributors serving hospital networks across Central Europe.
Japan
PMDA regulatory frameworks emphasize post-market surveillance for in-vitro diagnostic reagents, extending product registration timelines. Academic medical centers in Tokyo and Osaka prefectures drive adoption of automated slide agglutination platforms with digital imaging readouts. The Kansai region's chemical manufacturing base supplies specialized polystyrene particle formulations for research-use-only applications.
India
CDSCO import licensing requirements for diagnostic kits create localization incentives for multinational manufacturers establishing reagent finishing operations. Moderate-complexity testing sites in Maharashtra and Karnataka states face personnel shortages in medical laboratory science programs. The Hyderabad-Genome Valley cluster supports contract research organizations developing custom antigen coatings for assay development.
United Kingdom
NHS procurement frameworks consolidate laboratory purchasing through regional pathology networks, compressing vendor negotiation cycles. MHRA guidance on IVD performance standards aligns with IVDR technical documentation expectations for CE-UKNI dual marking. The Cambridge-Oxford-London triangle concentrates research institutes requiring specialized latex agglutination reagents for assay development projects.
Latex Agglutination Test Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue veterinary diagnostic and point-of-care authorization pathways. The vendor base stratifies around three archetypes: diversified life science conglomerates with diagnostic reagent infrastructure, specialized microbiology-focused manufacturers, and regional kit assemblers serving moderate-complexity CLIA sites. Consolidation pressures intensify as hospital purchasing centralizes through group buying organizations and integrated delivery networks.
Among diversified conglomerates, Thermo Fisher Scientific Inc. represents the scale-driven archetype with diagnostic reagent standardization capabilities across hospital networks. bioMérieux S.A. occupies the specialized pathogen detection position, anchoring competitive stance through integrated laboratory information system compatibility. Atlas Medical GmbH exemplifies the regional European manufacturer archetype, positioned within German-speaking diagnostic markets. These three entities illustrate how competitive positioning diverges between global standardization, specialized panel depth, and regional regulatory proximity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| bioMérieux S.A. |
| Atlas Medical GmbH |
| Cardinal Health |
| Bio-Rad Laboratories, Inc. |
| HiMedia Laboratories |
| Eurofins Abraxis |
| BioLegend Inc. |
| Hardy Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Automated slide agglutination platforms with digital imaging readouts are compressing per-test economics while concentrating procurement leverage among hospital-affiliated laboratories in the United States. This technology transition simultaneously elevates capital requirements for moderate-complexity testing sites and reshapes supplier pricing power toward instrument-reagent bundled contracts.
Pricing Analysis
Service bundling separates premium-tier contracts with comprehensive LIS middleware integration and validation support from unbundled reagent-only purchases common in independent reference laboratories. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 510(k)-cleared kits commanding substantial premiums over research-use-only alternatives. Cost compression in the standard tier is intensifying because hospital group purchasing organizations leverage multi-hospital contract volumes to extract reagent discounts. Independent diagnostic centers exhibit the highest price sensitivity due to constrained capital budgets, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Domestic-content mandates under India's CDSCO import licensing framework are compelling multinational manufacturers to establish local reagent finishing operations, fragmenting traditional supply concentration. Polystyrene microsphere production draws from specialized chemical manufacturing bases in the United States, Germany, and Japan, with antibody raw material sourcing anchored in contract manufacturing clusters in North Carolina and the Rhine-Main region. Single-source vulnerability concentrates in polyclonal antibody yield from limited contract manufacturers, exposing kit producers to unpredictable lead time extensions. Distribution runs through diagnostic reagent distributors serving hospital networks and group purchasing organization procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow cytometry-enhanced latex agglutination systems are displacing manual microscopy methods, compressing the window for legacy platform defenders to execute technology-transition strategies before objective readout capabilities become table stakes.
For Market Incumbents: Deploy backward integration into polystyrene microsphere synthesis to secure particle supply against yield variability from contract manufacturers. Consolidate reagent portfolios around scalable, instrument-compatible formats that satisfy CLIA moderate-complexity laboratory automation mandates, while defending installed base relationships against molecular nucleic acid amplification substitution in infectious disease confirmation testing. For New Entrants and Emerging Players: Capture veterinary diagnostic crossover opportunities for companion animal serology panels, where lower regulatory barriers and premium pricing tolerance create accessible white space. Target decentralized testing authorization pathways in pharmacy and urgent care settings under FDA emergency use authorization precedents, pursuing point-of-care latex agglutination deployment with simplified workflow designs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking diagnostic reagent infrastructure scale. Long-term viability hinges on regulatory navigation capabilities across FDA 510(k) and EU IVDR frameworks. The signal to watch is IVDR technical documentation burden progression, as legacy assay portfolio rationalization will separate defensible high-throughput platforms from stranded research-use-only conversions.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Development | Flow cytometry integration satisfies LIS middleware requirements in hospital-affiliated laboratories. |
| CE Marking Renewal Investment | EU IVDR clinical evidence generation defends legacy assay market access against portfolio rationalization. |
| Veterinary Diagnostic Panel Launch | Companion animal serology accesses premium pricing with reduced regulatory barriers compared to human diagnostics. |
| Group Purchasing Organization Contracting | Multi-hospital supply agreements lock in recurring reagent consumption and displace independent reference laboratory share. |
| Point-of-Care Authorization Pursuit | Decentralized testing deployment in pharmacy settings expands addressable market beyond traditional laboratory environments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with diagnostic reagent procurement managers, CLIA laboratory directors, biomedical engineers, and group purchasing organization contracts specialists. FDA 510(k) clearance databases, EU IVDR technical documentation repositories, hospital procurement databases, and GPO contract records provided quantitative foundation. Bottom-up test volume modeling and top-down market sizing triangulated segment-level estimates.
Reconciliation of instrument installation data, reagent consumption patterns, and capital expenditure disclosures across the projection horizon enabled cross-validation. Segmentation dimensions modeled include product format, application category, end-user environment, and technology platform. CAGRs derived from regression analysis against macro healthcare expenditure indicators and laboratory automation investment cycles. Antibody raw material yield variability and CLIA personnel shortage constraints informed scenario-weighted projections.
The model holds under stable regulatory authorization frameworks; deviation in EU IVDR enforcement intensity or FDA complexity reclassification would shift competitive access patterns. Forecasts reflect documented assumptions regarding hospital consolidation velocity and molecular substitution rates in infectious disease testing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Antibody Testing Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
In-Vitro Diagnostics Enzymes Market