
 Rapid Oral Fluid Screening Device Market | 2026-2036
Rapid Oral Fluid Screening Device Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Oral Fluid Screening Device Market Outlook
Workplace testing procurement among North American employers is consolidating, with large occupational health networks and third-party administrators driving standardized device selection. Abbott Laboratories leverages its diagnostics infrastructure to sustain institutional contracts across hospital and laboratory channels. Guangzhou Wondfo Biotech Co., Ltd anchors cost-competitive manufacturing for point-of-care deployments in price-sensitive segments. Drägerwerk AG & Co. KGaA specializes in forensic-grade precision, differentiating its offerings for law enforcement and judicial applications.
A rapid oral fluid screening device detects analytes in saliva samples through lateral flow or instrumented assay formats, typically delivering results within five to fifteen minutes without venipuncture. Immunoassay technology dominates current installed bases due to established sensitivity thresholds and regulatory familiarity, though microfluidics platforms represent the fastest-growing segment as manufacturers miniaturize multiplex detection capabilities. Point-of-care end users command expanding volume share as decentralized testing models displace centralized laboratory workflows, while drug testing applications maintain the largest revenue pool across criminal justice, employment, and clinical toxicology settings.
FDA 510(k) premarket notification requirements and CLIA-waived categorization under CMS oversight determine commercial viability and reimbursement access for United States manufacturers. The country's national transportation regulator mandates oral fluid testing protocols for safety-sensitive positions, directly shaping product specification demands and validation standards. Stakeholders must monitor evolving SAMHSA guidelines for federally regulated testing programs and state-level cannabis legalization impacts on employer screening policies to anticipate demand shifts and compliance investments.
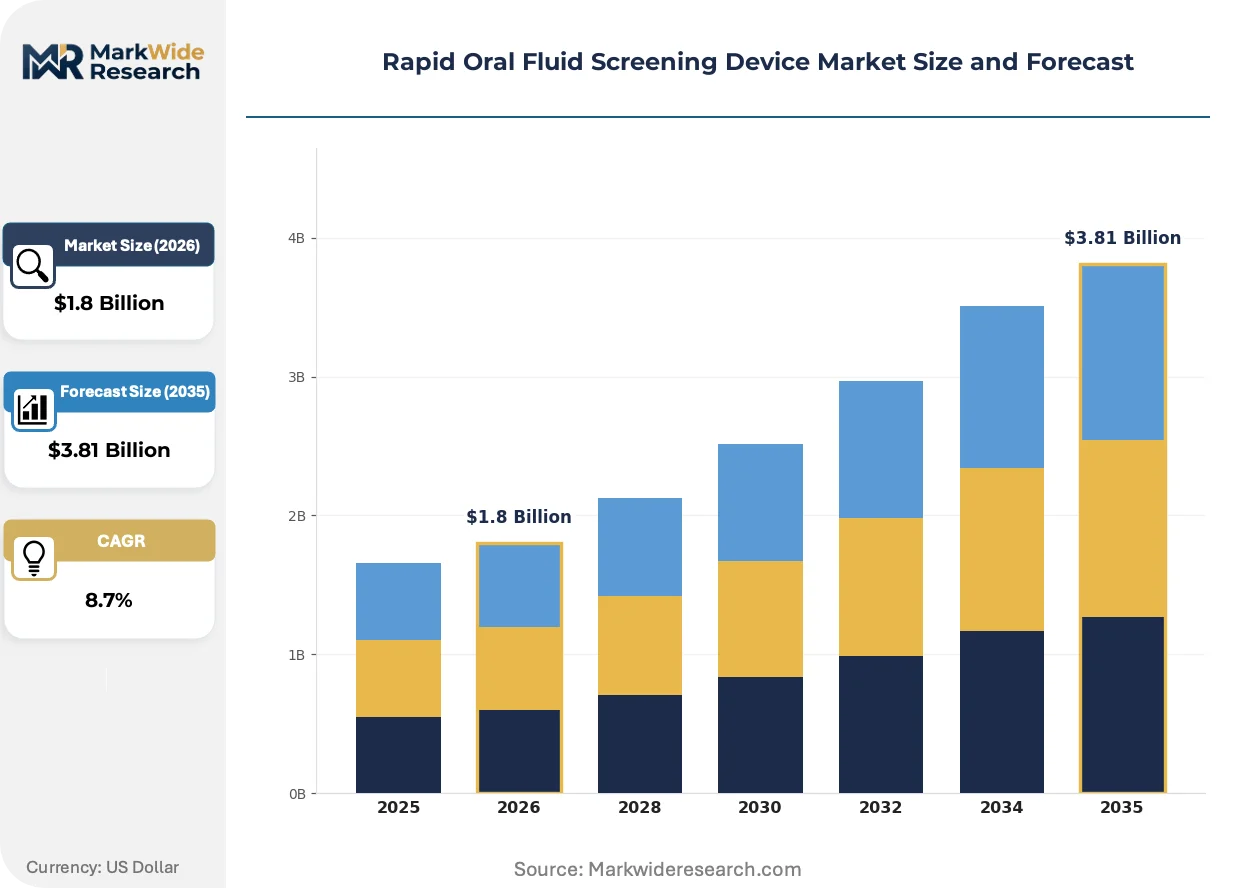
Market Dynamics
Workplace drug testing mandates and point-of-care decentralization are compressing testing timelines, forcing manufacturers to optimize for speed without sacrificing forensic reliability. CLIA-waived certification under CMS oversight now determines which devices capture institutional procurement contracts.
Growth Catalysts
- Federal transportation mandates:The Department of Transportation's oral fluid testing protocols for safety-sensitive positions create baseline demand specifications that ripple through private-sector procurement standards.
- Point-of-care workflow migration:Decentralized testing models are displacing centralized laboratory processing, expanding addressable volume for rapid-result formats.
- Immunoassay sensitivity thresholds:Established detection limits for common drug panels reduce validation barriers for new market entrants.
Market Restraints
- Forensic-grade precision requirements:Law enforcement and judicial applications demand instrumented assays with documented chain-of-custody protocols, limiting lateral flow penetration.
- Single-source component dependencies:Specialized monoclonal antibody suppliers concentrate in select manufacturing clusters, creating input vulnerability.
- State-level cannabis policy fragmentation:Inconsistent employer screening permissions across jurisdictions complicate national testing program design.
Strategic Opportunities
- Multiplex microfluidics convergence:Miniaturized detection platforms combining immunoassay specificity with digital readout capabilities open clinical toxicology applications.
- Third-party administrator channel expansion:Occupational health networks consolidating purchasing decisions create standardized device specification pathways.
- SAMHSA guideline evolution:Anticipated updates to federally regulated testing programs will validate new analyte panels and sample matrices.
Industry Challenges
- 510(k) clearance timeline compression:FDA premarket notification requirements for novel detection technologies extend development cycles and capital lockup periods.
- Cross-platform integration complexity:Laboratory information system compatibility and electronic health record connectivity demand specialized software engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Oral Fluid Screening Device Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tests, Analyzers, Reagents, Kits Technology: Immunoassay, Chromatography, Microfluidics, Biosensors End User: Hospitals, Laboratories, Clinics, Point-of-Care Application: Drug Testing, Disease Diagnosis, Forensic Analysis, Screening Programs |
| Companies Covered | OraSure Technologies, Inc., Abbott Laboratories, Guangzhou Wondfo Biotech Co., Ltd, Oranoxis Inc., Securetec Detektions-Systeme AG, UCP Biosciences, Inc., Drägerwerk AG & Co. KGaA, MEDACX Ltd., Premier Biotech, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Oral Fluid Screening Device Market Strategic Shifts
Digital integration and multiplexing capabilities are redefining competitive differentiation, while regulatory clarity around new sample matrices is accelerating format experimentation.
Microfluidics-based instrumented assays are rewriting the speed-precision tradeoff that has historically segmented the market. Hospital emergency departments and occupational health clinics are adopting these platforms for simultaneous multi-drug detection within ten-minute windows. The technology is compressing the performance gap between point-of-care convenience and laboratory-grade evidentiary standards.
FDA's evolving stance on CLIA-waived categorization for oral fluid devices is reshaping reimbursement access pathways. Manufacturers pursuing waived status must demonstrate operational simplicity for non-laboratory personnel, raising design constraints on user interfaces and quality control protocols. Point-of-care end users in the United States are prioritizing waived devices to minimize staffing credential requirements.
Buyer concentration among large occupational health networks is consolidating procurement decisions previously fragmented across individual employers. Third-party administrators now specify device performance standards and validation documentation requirements, displacing direct manufacturer relationships with smaller accounts. This pattern is most visible in the United States, where national staffing firms and managed care organizations coordinate testing programs across distributed workforces.
Rapid Oral Fluid Screening Device Market Segmentation
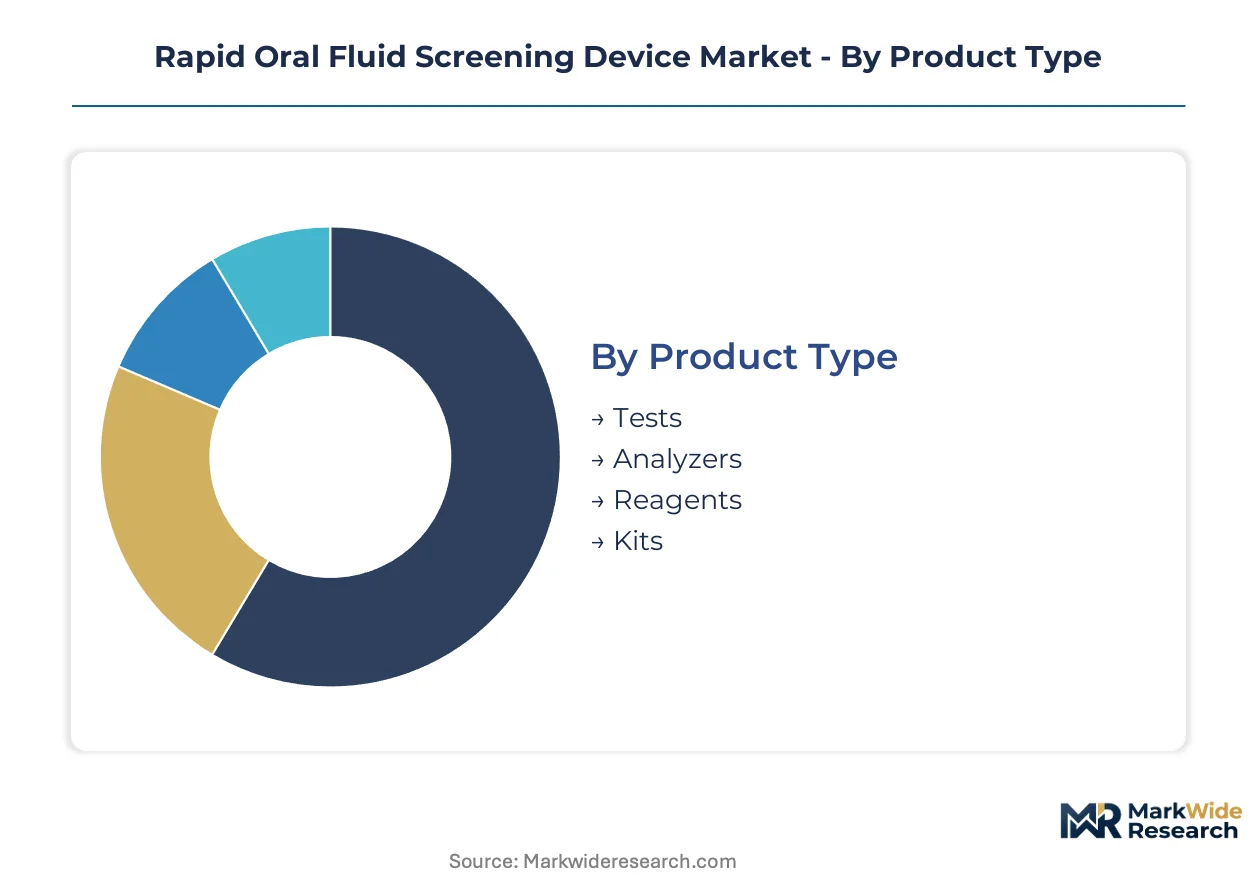
Device selection in this market hinges on validation status, workflow integration, and procurement channel concentration. Segmentation reveals how technology choices cascade through regulatory pathways, end-use requirements, and application-specific performance thresholds.
Product Type:
Procurement decisions prioritize CLIA-waived status and supply chain reliability over unit economics alone.
- Tests:Single-use lateral flow cassettes deliver qualitative results within ten minutes for workplace and roadside applications. United States occupational health networks specify these for high-frequency screening programs where waived status eliminates laboratory personnel requirements.
- Analyzers:Benchtop instrumented systems combine optical readers with automated result interpretation, serving forensic laboratories and hospital toxicology units that demand quantitative output and chain-of-custody documentation.
- Reagents:Antibody-conjugated detection chemistry sourced from specialized monoclonal suppliers concentrates manufacturing risk for device assemblers.
- Kits:Bundled collection-and-test configurations simplify logistics for decentralized deployment in mobile testing units and remote workplace sites.
Tests lead on scale; analyzers lead on momentum.
Technology:
Speed-precision tradeoffs and regulatory familiarity determine technology selection across end-use segments.
- Immunoassay:Competitive and sandwich format antibody-antigen reactions dominate installed bases through established sensitivity thresholds for common drug panels. FDA 510(k) clearance pathways are well-characterized for this modality, reducing validation timelines for new entrants.
- Microfluidics:Miniaturized fluidic channels integrate sample preparation, reaction, and detection in disposable cartridges, enabling multiplex detection within instrumented platforms. Point-of-care clinics and emergency departments are adopting these for simultaneous multi-analyte screening.
- Chromatography:Liquid chromatography-mass spectrometry configurations serve confirmatory testing roles where definitive identification supersedes speed requirements.
- Biosensors:Electrochemical and optical transducer approaches are gaining traction in research-phase devices targeting continuous monitoring applications.
Immunoassay leads on scale; microfluidics leads on momentum.
End User:
Credential requirements and reimbursement access create sharp segmentation in procurement authority.
- Point-of-Care:Non-laboratory settings including occupational health clinics and mobile testing units prioritize waived devices that minimize staffing costs and expand testing access beyond traditional laboratory infrastructure.
- Laboratories:Centralized processing facilities specify high-throughput analyzers with laboratory information system connectivity and documented quality control protocols for forensic defensibility.
- Hospitals:Emergency departments and clinical toxicology services demand rapid turnaround for patient management decisions, driving adoption of instrumented platforms with quantitative output.
- Clinics:Federally qualified health centers and community health clinics balance cost constraints with CLIA complexity requirements in device selection.
Point-of-Care leads on scale; laboratories lead on momentum.
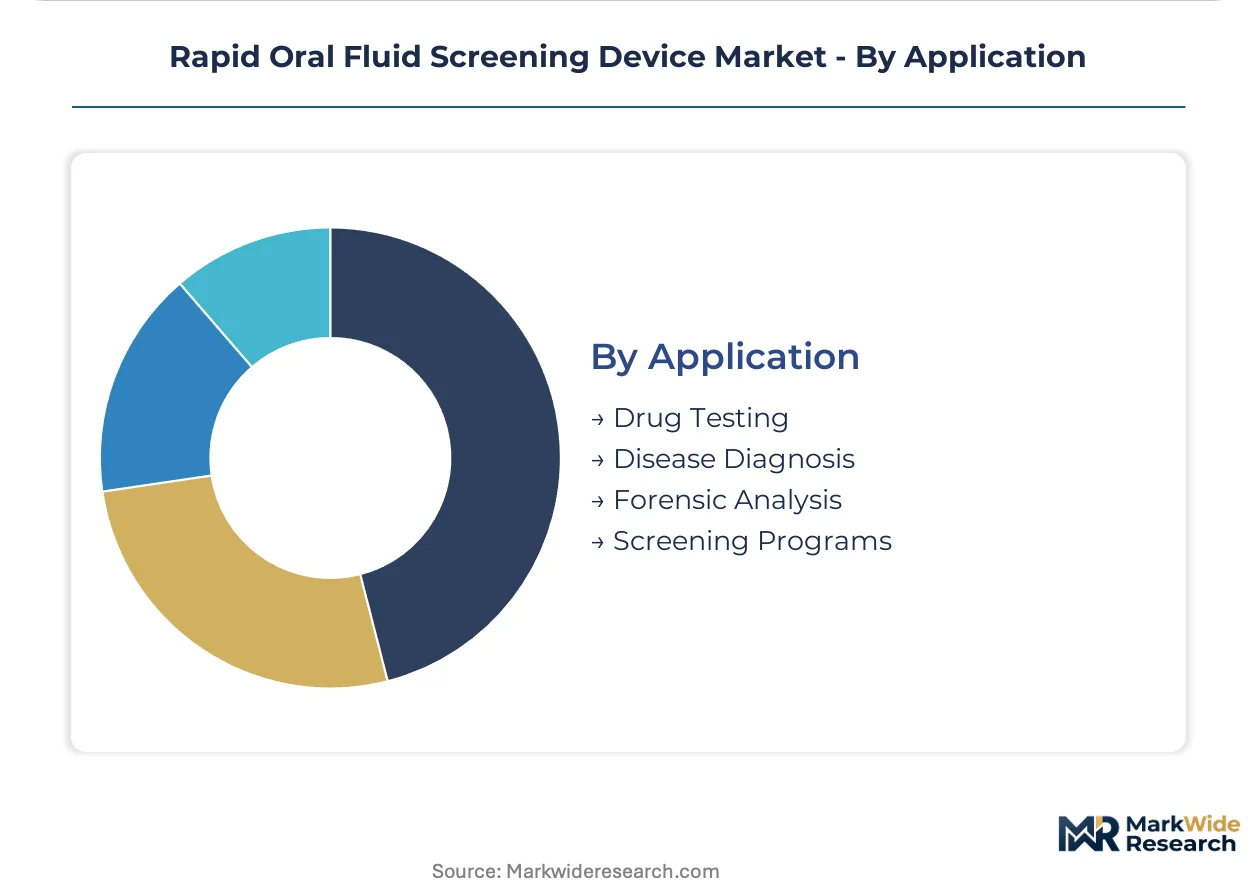
Application:
Evidentiary standards and regulatory oversight intensity segment demand by use case.
- Drug Testing:Employment screening, criminal justice, and substance use treatment programs constitute the largest revenue pool, with SAMHSA guidelines shaping panel specifications and cutoff concentrations for federally regulated programs.
- Disease Diagnosis:Infectious disease and hormonal marker detection in oral fluid represents an emerging application as manufacturers validate assays for HIV, hepatitis, and cortisol monitoring.
- Forensic Analysis:Judicial proceedings demand instrumented assays with documented chain-of-custody and analytical specificity that lateral flow devices cannot satisfy.
- Screening Programs:Public health surveillance and epidemiological studies utilize oral fluid collection for population-level monitoring where non-invasive sampling improves participation rates.
Drug Testing leads on scale; Disease Diagnosis leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands procurement volume through federal transportation mandates, while Germany anchors European demand via workplace safety protocols and forensic laboratory standards.
United States
Department of Transportation oral fluid testing protocols for safety-sensitive positions create baseline demand specifications that ripple through private-sector procurement. FDA 510(k) clearance pathways and CLIA-waived categorization under CMS oversight determine commercial viability and reimbursement access. Abbott Laboratories leverages its diagnostics infrastructure to sustain institutional contracts across hospital and laboratory channels in the Northeast and California corridors.
Germany
Workplace safety regulations and judicial forensic standards drive adoption of instrumented analyzers with documented chain-of-custody protocols. Drägerwerk AG & Co. KGaA specializes in forensic-grade precision from its Lübeck base, differentiating offerings for law enforcement applications. The country's national pharmaceutical regulator maintains stringent validation requirements that shape product development trajectories for EU market entry.
China
Point-of-care decentralization and occupational health network expansion accelerate procurement of cost-competitive lateral flow devices. Guangzhou Wondfo Biotech Co., Ltd anchors manufacturing for price-sensitive segments from its Pearl River Delta facilities. The national medical products regulator oversees domestic device registration while manufacturers target export markets with CE-marked alternatives.
United Kingdom
Employment screening program consolidation among third-party administrators standardizes device specifications across distributed workforces. MEDACX Ltd. occupies a position within the specialist tier serving occupational health networks. The country's national pharmaceutical regulator aligns with EU MDR transitional provisions for in vitro diagnostic device market access.
Canada
Federal transportation safety mandates and provincial workplace insurance protocols create dual-layer procurement requirements. Health Canada oversees premarket licensing for oral fluid screening devices while provincial health authorities determine point-of-care deployment permissions. Toronto and Vancouver clusters concentrate distribution infrastructure for North American market access.
Rapid Oral Fluid Screening Device Market Competitive Environment
United States producers anchor one tier through institutional diagnostics infrastructure; European specialists hold forensic-grade precision positioning. The vendor base arranges across three tiers: multinational conglomerates with broad diagnostics portfolios, mid-scale manufacturers with regional cost advantages, and niche specialists targeting judicial evidentiary standards. Strategic moves concentrate on CLIA-waived certification pursuit and third-party administrator channel capture.
Within the multinational tier, Abbott Laboratories represents institutional contract consolidation across hospital and laboratory channels. Guangzhou Wondfo Biotech Co., Ltd exemplifies cost-competitive manufacturing archetypes serving price-sensitive point-of-care deployments. Drägerwerk AG & Co. KGaA anchors forensic-grade specialization for law enforcement and judicial applications.
| Leading Market Players |
|---|
| OraSure Technologies, Inc. |
| Abbott Laboratories |
| Guangzhou Wondfo Biotech Co., Ltd |
| Oranoxis Inc. |
| Securetec Detektions-Systeme AG |
| UCP Biosciences, Inc. |
| Drägerwerk AG & Co. KGaA |
| MEDACX Ltd. |
| Premier Biotech, Inc |
| Others |
Value Chain & Pricing Dynamics
Forensic-grade precision certification against CLIA-waived commodity formats bifurcates pricing power and supply chain complexity across this market. Instrumented analyzers with documented chain-of-custody protocols command premium positioning through specialized monoclonal antibody sourcing and FDA 510(k) validation investments, while lateral flow cassettes compete on manufacturing scale from Pearl River Delta contract producers.
Pricing Analysis
Capacity additions in China are reshaping price floors for lateral flow devices as Guangzhou Wondfo Biotech Co., Ltd and domestic competitors expand automated cassette production. Three-tier pricing structure across forensic-grade analyzers, CLIA-waived instrumented platforms, and commodity lateral flow cassettes reflects certification burden and detection specificity. Cost compression in waived-status segments intensifies as occupational health networks consolidate procurement volume and demand standardized panel configurations. Third-party administrators exhibit highest price sensitivity through consolidated tender processes, while forensic laboratories prioritize analytical defensibility over unit economics.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Singapore coordinate hub-and-spoke patterns for temperature-sensitive antibody reagents and finished devices. Manufacturing concentrates in China for cost-competitive lateral flow assembly, Germany for precision instrument fabrication, and the United States for CLIA-waived device final packaging and regulatory compliance. Specialized monoclonal antibody production rests on single-source suppliers in Massachusetts and Bavaria, creating input vulnerability for multiplex assay developers. Tariff exposure on Chinese-manufactured cassettes threatens margin structures for price-sensitive point-of-care deployments. Distribution runs through third-party administrator networks and occupational health service consolidators rather than direct employer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as workplace drug testing programs migrate toward forensic-evidentiary standards and away from screening-only formats. Procurement consolidation among national occupational health networks rewards manufacturers with validated CLIA-waived portfolios and documented SAMHSA alignment.
For Market Incumbents: Extend CLIA-waived certification coverage across expanded analyte panels to capture third-party administrator standard-setting influence. Defend institutional contracts through backward integration into monoclonal antibody production, reducing single-source supplier vulnerability. Capacity additions in Southeast Asia for lateral flow manufacturing counter cost pressure from Chinese competitors. Channel control through exclusive partnerships with consolidating occupational health networks protects margin position against emerging microfluidics entrants. For New Entrants and Emerging Players: Mobile testing units serving distributed construction and logistics workforces represent an underserved buyer archetype with limited incumbent penetration. White-space targets include cannabis compliance panels for state-legal markets with fragmented employer screening permissions, and infectious disease oral fluid assays for federally qualified health centers. The most penetrable segment combines waived-status simplicity with instrumented quantitative output for emergency department toxicology. Go-to-market positioning emphasizes software integration with electronic health record systems and laboratory information platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 510(k) clearance timelines extend capital lockup periods beyond venture-scale runway capacity. Long-term viability favors manufacturers with dual capability in waived lateral flow and instrumented microfluidics formats, capturing workflow migration across analysis windows. Acquisition target archetypes include CLIA-waived device specialists with validated SAMHSA panels and established third-party administrator relationships. Signal to watch: SAMHSA guideline updates validating new oral fluid matrices or analyte thresholds, which would trigger procurement refresh cycles among federally regulated testing programs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Expanded Panels | CLIA-waived status unlocks third-party administrator procurement consolidation in United States occupational health networks. |
| Microfluidics Platform Development | Multiplex detection capabilities compress the speed-precision tradeoff for emergency department and forensic laboratory adoption. |
| Monoclonal Antibody Supply Agreement | Specialized detection chemistry sourcing from Massachusetts and Bavaria clusters reduces single-source vulnerability for assay manufacturers. |
| Hospital System Partnership | Laboratory information system integration and electronic health record connectivity secure institutional toxicology service contracts. |
| Reimbursement Strategy | CMS coverage determination alignment for oral fluid testing protocols shapes commercial viability for point-of-care deployments. |
Study Parameters
Bottom-up point-of-care and laboratory modeling reconciled against top-down device shipment and regulatory filing tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at diagnostic manufacturers, occupational health network procurement directors, third-party administrator clinical directors, hospital biomedical engineers, and SAMHSA program administrators combined with secondary validation from FDA 510(k) clearance databases, CMS CLIA waiver listings, DOT oral fluid testing protocol amendments, and occupational health service contract disclosures. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of device approvals, procurement contract awards, and testing program expansions established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user credential requirements, and application evidentiary standards, with cross-cutting analysis of regional regulatory framework variations. CAGRs derived from fitted trend projections adjusted for policy inflection points including anticipated SAMHSA guideline updates and state-level cannabis policy evolution. Industry-specific forecast inputs incorporated DOT-mandated testing volume specifications and CLIA complexity classification migration patterns.
Inputs from FDA premarket notification databases and occupational health network contract registries were available through the study window; gaps in real-time procurement transaction data introduce uncertainty bands around third-party administrator channel share estimates. Forecasts reflect documented assumptions regarding regulatory timeline trajectories and workplace screening policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fungal Antigens Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Malaria Diagnostics Market