
 Railway System Market | 2026-2036
Railway System Market Size, Share, and Industry Trends Forecast 2026-2036
Railway System Market Intelligence
Chinese rolling stock manufacturing is pivoting toward higher-speed platforms and integrated digital systems. CRRC Corporation leverages domestic supply chain density to anchor production scale across Asia. Alstom competes through European signaling specialization and cross-border corridor technology. Siemens Mobility extends its position in automated train operation and power grid integration for rail electrification.
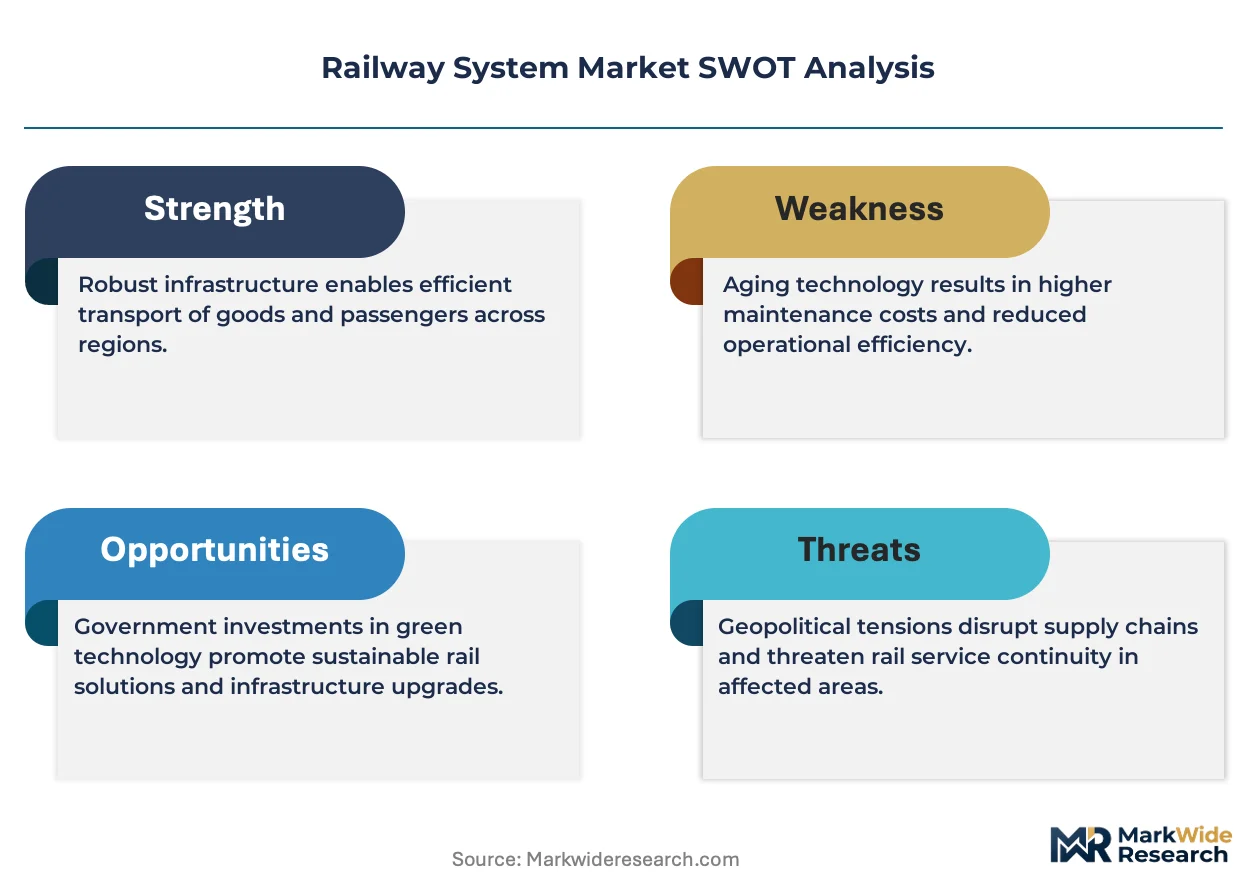
Railway systems encompass electrified and diesel-powered networks with track gauges ranging from standard 1,435 mm to broad 1,676 mm configurations, designed for passenger mobility and freight logistics across intercity and urban corridors. Electrification technology leads capital deployment as operators phase out diesel traction, while high-speed trains command premium engineering margins due to aerodynamic and power-system complexity. Signaling systems represent the fastest-growing technology segment as ETCS Level 3 deployment accelerates, and maintenance services capture recurring revenue pools amid aging infrastructure in North America and Western Europe.
The EU Green Deal and F-Gas Regulation shape European procurement by mandating carbon-intensity reductions in rolling stock and infrastructure materials. India's CEA and BIS enforce electrification standards and rolling stock safety certification under expanding PLI scheme allocations for domestic manufacturing. China's MIIT and GB standards govern high-speed train performance thresholds and signaling interoperability. Stakeholders must monitor regulatory divergence between European decarbonization timelines and Asian state-backed capacity buildouts to align R&D and partnership priorities.
Market Dynamics
Electrification mandates across major economies are forcing capital reallocation from diesel traction toward grid-integrated rail networks, compressing supplier transition timelines and reshaping procurement specifications for rolling stock and infrastructure components.
Growth Catalysts
- EU Green Deal Decarbonization:Binding carbon-intensity targets for transport corridors are accelerating fleet replacement cycles across Germany, France, and Italy. Operators must retire diesel locomotives before end-of-life to meet 2030 interim thresholds.
- Urban Mass Transit Expansion:Metro authorities in China, India, and Southeast Asia are procuring rolling stock at scale to relieve congestion in megacities. Delhi Metro and Shanghai Metro anchor fleet growth with combined annual orders exceeding regional peers.
- ETCS Level 3 Deployment:Moving-block signaling technology is displacing fixed-block systems on high-density European corridors. This upgrade path creates bundled demand for onboard units, trackside equipment, and maintenance services.
Market Restraints
- Copper and Rare Earth Input Volatility:Traction motors and power electronics depend on copper windings and neodymium magnets. Price swings in these commodities compress manufacturing margins and complicate long-term contract pricing.
- Supply Concentration in China:CRRC Corporation controls dominant share of global rolling stock output. European and North American buyers face limited alternative sourcing for complete trainsets and critical subsystems.
- Extended Certification Timelines:New rolling stock platforms require multi-year validation against EN 15227 crashworthiness and UIC interoperability standards. These procedural delays extend payback periods for OEM development investments.
Strategic Opportunities
- Dedicated Freight Corridors in India:The Eastern and Western DFC projects are creating demand for heavy-haul locomotives and automatic freight management systems. These greenfield routes bypass legacy infrastructure constraints.
- Battery-Electric Multiple Units:Lithium-titanium-oxide chemistry paired with regenerative braking is modularizing traction architecture for non-electrified branch lines. This convergence opens service to routes previously dependent on diesel.
- Digital Twin Integration:Predictive maintenance platforms using real-time sensor feeds are creating new revenue pools in aftermarket services. Operators in Japan and South Korea are piloting these systems for aging Shinkansen and KTX fleets.
Industry Challenges
- Signaling Engineer Scarcity:ETCS and CBTC deployment outpaces trained workforce supply in Europe and Asia-Pacific. Railway engineering programs require multi-year expansion to close this competency gap.
- Legacy System Interoperability:New digital signaling must coexist with century-old mechanical interlockings on many routes. This interface complexity inflates project costs and extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway System Market |
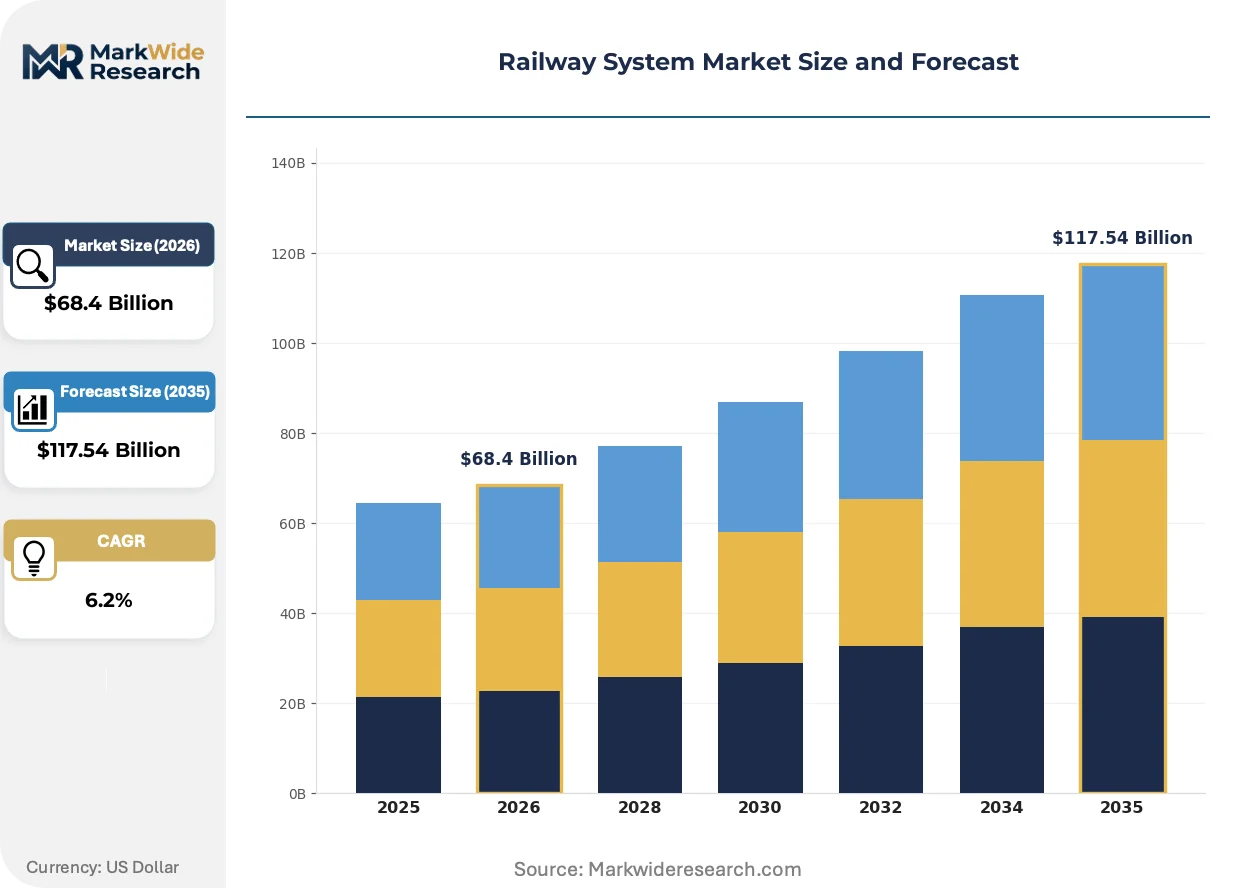
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrification, Signaling, Communication Systems, Train Control Service Type: Passenger Services, Freight Services, Maintenance Services, Consultancy Infrastructure Type: Rail Tracks, Stations, Bridges, Tunnels Rolling Stock: Locomotives, Passenger Coaches, Freight Cars, High-Speed Trains |
| Companies Covered | Siemens Mobility, Alstom, CRRC Corporation, Hitachi Rail, Stadler Rail, Wabtec Corporation, Thales Group, CAF, Knorr-Bremse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway System Market Strategic Shifts & Innovations
Digitization of rail operations is compressing maintenance cycles and enabling predictive asset management, while powertrain electrification is modularizing vehicle architecture and opening new route categories to electric service.
Traction battery systems using solid-state electrolyte designs are modularizing energy storage placement within trainsets. Japanese and South Korean operators are piloting these configurations for non-electrified regional services. This shift is modularizing platform design by decoupling power source from carbody structure, enabling faster variant development.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in rail HVAC systems, forcing refrigerant transitions toward CO2 and hydrocarbon alternatives. Rolling stock OEMs must redesign thermal management systems to maintain cooling capacity under tighter leakage standards. This regulatory pressure concentrates most acutely on cross-border corridor fleets where interoperability certification spans multiple national safety authorities.
Performance-based maintenance contracts are displacing traditional time-based service agreements among European freight operators. Deutsche Bahn Cargo and SNCF Fret are unbundling component-level service responsibility from asset ownership, transferring operational risk to OEM service divisions. This model is most visible in Germany and France where fleet age and utilization intensity justify outcome-based pricing structures.
Railway System Market Segmentation
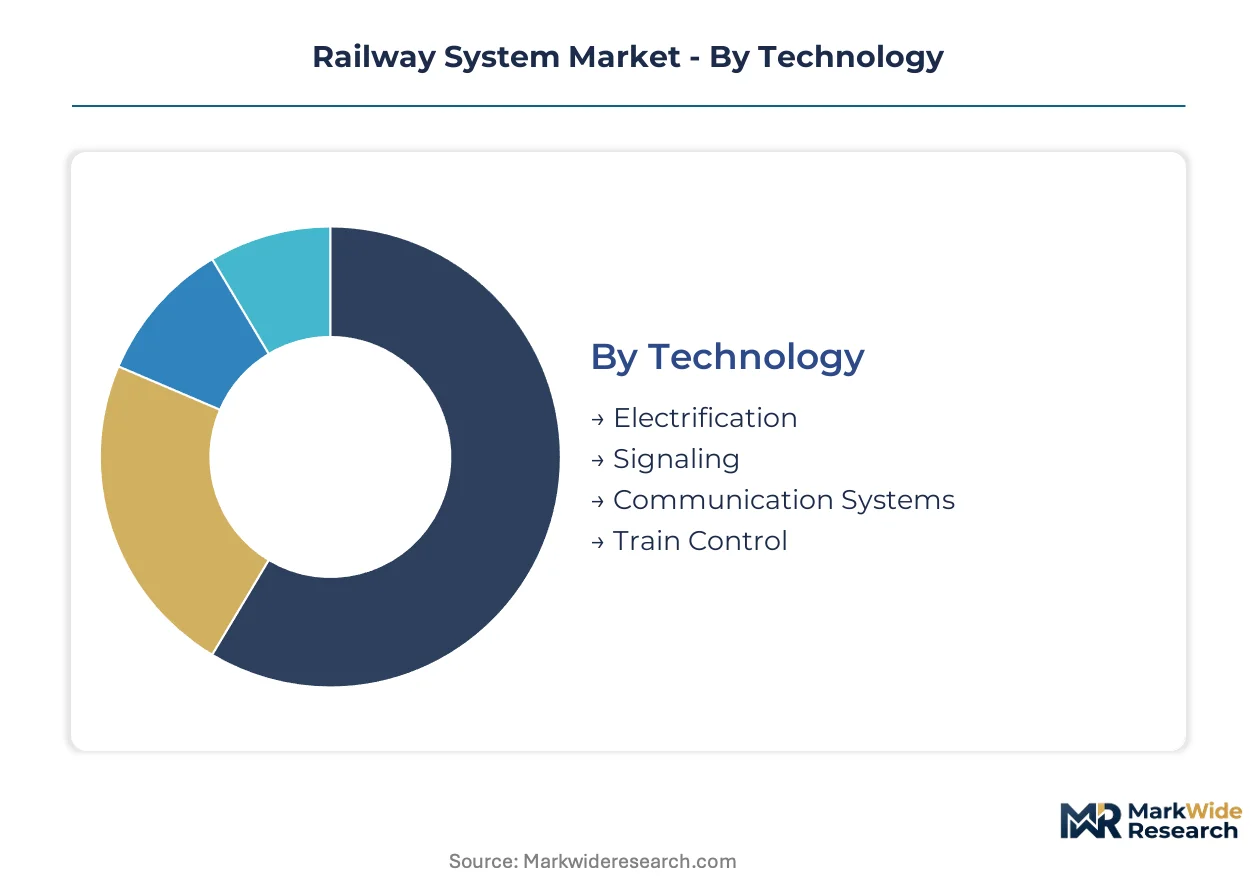
Railway system procurement splits across operational technology, service delivery models, fixed infrastructure, and mobile assets. Each dimension carries distinct buyer decision criteria, contract structures, and supplier ecosystems that shape competitive positioning.
Technology:
Capital allocation intensity drives technology selection, with electrification commanding the largest share of infrastructure budgets and signaling delivering the highest engineering margins.
- Electrification:Overhead catenary and third-rail systems power traction motors through grid-connected substations. China's high-speed network and India's Dedicated Freight Corridors anchor demand as both countries extend electrified route-kilometers under state-backed investment programs.
- Signaling:ETCS and CBTC platforms govern train spacing and route authority through trackside beacons and onboard control units. European corridors under EU Green Deal mandates are displacing legacy fixed-block systems with moving-block architectures, compressing commissioning timelines for suppliers.
- Communication Systems:GSM-R and LTE-M networks transmit voice and data between control centers and trainsets.
- Train Control:Automatic train operation modules manage acceleration, braking, and station docking without driver intervention.
Volume sits with Electrification; growth tilts toward Signaling.
Service Type:
Revenue predictability separates service categories, with maintenance contracts offering recurring cash flows against the project-based nature of new infrastructure deployment.
- Passenger Services:Urban metro and intercity operators monetize seat-kilometers through fare-box recovery and government subsidy mechanisms. Delhi Metro and Shanghai Metro anchor fleet procurement volumes as Asian megacities expand network coverage.
- Freight Services:Heavy-haul and intermodal operators optimize wagon utilization and terminal throughput. India's Eastern and Western Dedicated Freight Corridors are creating demand for automated freight management systems on greenfield routes bypassing legacy constraints.
- Maintenance Services:Component overhaul and predictive analytics contracts transfer operational risk from asset owners to OEM service divisions.
- Consultancy:Engineering advisory supports route planning, safety certification, and interoperability compliance.
Passenger Services capture the largest revenue pool; Freight Services are expanding most quickly.
Infrastructure Type:
Asset life cycles and maintenance burdens vary sharply across fixed infrastructure categories, with tunnels and bridges requiring specialized construction capabilities that limit supplier pools.
- Rail Tracks:Ballasted and slab track configurations support axle loads from 22.5 tonnes on conventional lines to 32.5 tonnes on heavy-haul corridors. China's high-speed network and India's freight corridors are driving demand for continuously welded rail and concrete sleeper systems.
- Stations:Passenger terminals integrate platform screen doors, ticketing systems, and commercial retail space.
- Bridges:Viaducts and river crossings carry alignment continuity across topographic obstacles.
- Tunnels:Bored and cut-and-cover passages penetrate mountainous terrain and urban subsoil.
Rail Tracks absorb the greatest capital share; Tunnels command the steepest expansion trajectory in mountainous corridors.
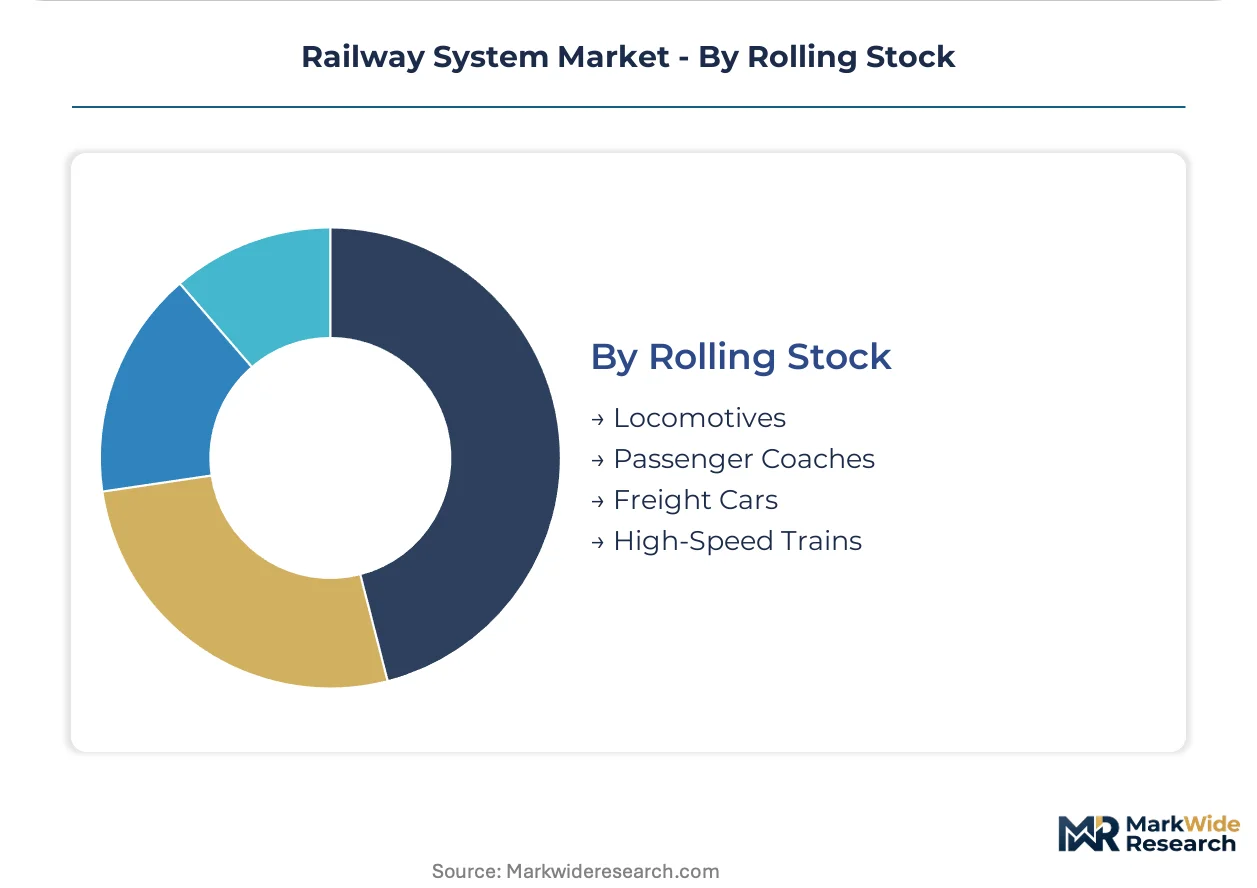
Rolling Stock:
Platform complexity and certification requirements segment rolling stock procurement, with high-speed trains requiring multi-year validation against crashworthiness and aerodynamic performance standards.
- Locomotives:Diesel-electric and electric traction units haul passenger coaches and freight wagons across non-electrified and electrified routes. India's Dedicated Freight Corridors are procuring heavy-haul electric locomotives rated for 9,000 horsepower and 25-tonne axle loads.
- High-Speed Trains:Multiple-unit configurations with distributed traction achieve operating speeds above 250 km/h on dedicated passenger corridors. China's expanding network and European cross-border services concentrate demand for platforms meeting UIC interoperability specifications.
- Passenger Coaches:Single-deck and double-deck carriages provide seated and sleeper accommodation on conventional lines.
- Freight Cars:Hopper, tank, and flatcar designs accommodate bulk commodities and intermodal containers.
Locomotives dominate unit volumes; High-Speed Trains deliver the highest per-unit engineering margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper deposits in Chile and rare earth mining in China anchor raw material supply chains for traction motors and power electronics across railway manufacturing networks worldwide.
China
High-speed rail network expansion and urban metro procurement drive rolling stock demand under MIIT industrial policy guidance. GB standards govern train performance thresholds and signaling interoperability across the national grid. CRRC Corporation anchors production in Changchun and Qingdao, supplying trainsets for domestic routes and export corridors into Southeast Asia.
Germany
ETCS Level 3 deployment on cross-border freight corridors and ICE fleet modernization shape capital allocation. EU Green Deal mandates under KBA supervision force diesel phase-out timelines by 2030. Siemens Mobility and Alstom maintain engineering clusters in Munich and Berlin, specializing in automated train operation and signaling systems.
India
Eastern and Western Dedicated Freight Corridors generate demand for 9,000-horsepower electric locomotives and automated freight management. CEA electrification standards and BIS safety certification apply under PLI scheme allocations for domestic manufacturing. Production concentrates in Bihar and Tamil Nadu as state-owned workshops expand capacity for heavy-haul equipment.
Japan
Shinkansen fleet renewal and battery-electric multiple unit pilots for regional branch lines absorb technology investment. METI drives solid-state traction battery development through national R&D consortia. Hitachi Rail and Kawasaki Heavy Industries operate manufacturing bases in Kobe and Hyogo, exporting high-speed platforms to Taiwan and India.
United States
Amtrak Northeast Corridor electrification studies and commuter rail fleet replacement programs command federal infrastructure funding. FRA safety regulations and Buy America provisions structure procurement for rolling stock and signaling upgrades. Wabtec Corporation manufactures locomotives in Erie, Pennsylvania, while transit authorities in New York and Chicago anchor demand for passenger equipment.
Railway System Market Key Industry Players
Global majors compete with regional champions across technology specialization and geographic footprint. The supplier base consolidates around three tiers: integrated rolling stock OEMs, signaling and subsystem specialists, and component-tier suppliers for brakes and HVAC. Strategic archetypes include state-backed national champions, European engineering specialists, and diversified industrial conglomerates. Competitive moves concentrate on signaling technology licensing and service contract bundling to capture recurring revenue streams.
Within the integrated OEM tier, CRRC Corporation, Siemens Mobility, and Alstom occupy positions spanning complete trainset production and infrastructure systems. CRRC represents the scale-driven archetype with domestic supply chain density across Asia. Siemens Mobility exemplifies the technology-licensing model through European corridor automation. Alstom anchors the cross-border interoperability specialization required for EU network integration. These three entities exemplify how competitive positioning splits between geographic coverage depth and technical subsystem dominance.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom |
| CRRC Corporation |
| Hitachi Rail |
| Stadler Rail |
| Wabtec Corporation |
| Thales Group |
| CAF |
| Knorr-Bremse |
| Others |
Cost & Logistics Intelligence
State-backed rolling stock manufacturers anchor production scale across Asia, compressing margin structures for European and North American suppliers while concentrating pricing power in procurement negotiations with transit authorities. Sovereign financing of rail infrastructure in China and India reinforces volume-based contracting that favors domestic supply chains and extends payback periods for foreign entrants seeking market access.
Pricing Analysis
Warranty and service-bundling arrangements separate rolling stock procurement into comprehensive lifecycle contracts versus equipment-only transactions. Project-based pricing dominates complete trainset orders, with differentiation driven by ETCS certification tier and geographic delivery complexity. Cost compression in standard-gauge locomotive segments is intensifying as CRRC leverages domestic supply chain density to underbid European rivals on export corridors. Freight operators in India exhibit the highest price sensitivity due to state-mandated cost recovery targets, while high-speed rail authorities in China prioritize performance specifications over unit economics.
Supply Chain Analysis
EN 15227 crashworthiness and UIC interoperability certifications gate supplier participation in European corridors, filtering component sourcing toward qualified sub-tier manufacturers. Production gravity centers on China for complete trainsets, Germany for signaling systems, and Japan for traction battery development. Traction motors draw from copper windings and neodymium magnets, with rare earth processing concentrated in Chinese refining operations. Single-source vulnerability in permanent magnet supply creates exposure to export restriction risk. Distribution runs through state procurement authorities in Asia and consolidated fleet operators in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway system manufacturing is consolidating around integrated technology platforms, with electrification mandates and signaling complexity forcing subscale component suppliers into acquisition targets for national champions.
For Market Incumbents: Cement market position through captive control over ETCS Level 3 onboard unit production and predictive maintenance software stacks. Alstom and Siemens Mobility should expand service contract bundling to capture recurring revenue from Deutsche Bahn and SNCF Fret fleets, defending against CRRC's emerging signaling exports into Southeast Asia. Backward integration into traction battery cell production hedges rare earth supply volatility. For New Entrants and Emerging Players: Regional freight operators on India's Dedicated Freight Corridors represent an underserved buyer archetype seeking modular battery-electric multiple units for non-electrified branch lines. Battery system specialists should prioritize lithium-titanium-oxide chemistry pilots with Japanese and South Korean regional railways. A licensing partnership with established signaling vendors accelerates certification timelines against multi-year EN validation requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed European subsystem suppliers with ETCS implementation expertise and stranded order books from delayed corridor projects. Long-term viability hinges on exposure to greenfield electrification programs in Asia rather than replacement demand in saturated European networks. Monitor Indian PLI scheme allocation announcements as inflection indicators for domestic manufacturing capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| ETCS Level 3 Certification Investment | Unlocks moving-block signaling contracts on EU Green Deal-mandated corridors in Germany and France. |
| Battery-Electric Multiple Unit Platform Launch | Opens non-electrified regional routes in Japan and India to zero-emission service. |
| Predictive Maintenance Service Contract | Captures recurring revenue from aging Shinkansen and KTX fleets in Japan and South Korea. |
| Dedicated Freight Corridor Joint Venture | Secures heavy-haul locomotive orders on India's Eastern and Western DFC greenfield routes. |
| Rare Earth Magnet Supply Agreement | Tethers traction motor production to Chinese refining capacity amid export restriction risk. |
Research Approach
Independent corroboration across rolling stock procurement databases, national rail authority capital expenditure disclosures, and OEM order backlog filings underwrites the qualitative findings in this study. Primary interviews with fleet procurement directors at European freight operators, signaling engineering leads at corridor infrastructure managers, and plant managers at Chinese rolling stock workshops combined with secondary validation from UIC interoperability standards documentation, EU Green Deal implementation progress reports, and Indian Railway Board tender announcements. Bottom-up unit demand modeling and top-down infrastructure budget triangulation anchored volume estimates.
Rate-of-change decomposition across electrification route-kilometers, ETCS deployment timelines, and rolling stock replacement cycles structured the analytical framework over the projection horizon. Segmentation dimensions modeled include technology type, service delivery model, infrastructure category, and rolling stock platform complexity alongside regional regulatory cluster. CAGRs were derived from installed base growth and technology substitution curves, with forecast inputs incorporating copper price volatility assumptions and rare earth supply constraint scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU diesel phase-out enforcement timing and Chinese high-speed rail export financing availability. Forecasts reflect documented assumptions regarding infrastructure budget continuity and certification timeline norms. A model refresh is warranted upon material change in EU Green Deal transport corridor funding allocations or Indian PLI scheme domestic content requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Window Market
Railway
Railway Automated Inspection Equipment Market
Railway
Railway Rolling Stock Market
Railway
Locomotive Radiator Fan Market
Railway
Train Exterior Lighting Market
Railway
Bullet Train Market
Railway
Rolling Stock Management Market
Railway
Check Rails Market
Railway
Solar Train Market
Railway
Smart Railways Market
Railway
Railway Bearing Market
Railway
Latin America Connected Rail Market
Railway
Global Train Brake Market
Railway
France Rail Freight Transport Market
Railway
Railway Buffer Stops Market
Railway
Global Hyperloop Train Market