
 Railway Rolling Stock Market | 2026-2036
Railway Rolling Stock Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Rolling Stock Market Analytics
Aluminum is rebalancing body-shell economics against traditional carbon steel in passenger coaches and high-speed trains. CRRC Corporation Limited leverages its captive aluminum forging capacity and integrated supply chain to dominate domestic electric multiple-unit output. Alstom anchors European market access through its hydrogen train platform and established certification pathways with national safety boards. Siemens Mobility competes on digital rail services, extending its position from rolling stock into signaling and predictive maintenance software.
Railway rolling stock comprises self-propelled or hauled rail vehicles—including locomotives, passenger coaches, freight wagons, and maintenance-of-way equipment—built to gauge-specific wheelsets with axle loads typically ranging from 18 to 25 tonnes and crashworthiness compliant with EN 15227 or equivalent structural integrity standards. These vehicles move passengers and cargo over fixed guideways, forming the capital-intensive core of rail transport infrastructure. Electric locomotives and multiple units now lead order books across intercity services and urban systems, while diesel technology retreats to unelectrified freight corridors and remote regional lines where infrastructure investment lags. Maintenance-of-way equipment represents a mature margin pool tied to track renewal cycles, whereas hybrid technology in passenger coaches captures growing interest where full electrification remains uneconomical.
The EU Green Deal and F-Gas Regulation constrain refrigerant and propulsion choices for rolling stock sold across Europe, while China's MIIT enforces domestic new-energy rail vehicle quotas and GB standards for electromagnetic compatibility. The US Federal Railroad Administration governs crashworthiness and track safety standards that dictate design margins for any equipment entering North American service. Stakeholders must monitor how diverging carbon-accounting rules across these jurisdictions alter total-cost-of-ownership calculations for fleet procurement.
Market Dynamics
Aluminum body-shell fabrication is consolidating procurement power among suppliers with captive smelting and extrusion capacity, compressing margins for carbon steel-dependent coach builders and redrawing competitive boundaries across passenger rolling stock segments.
Growth Catalysts
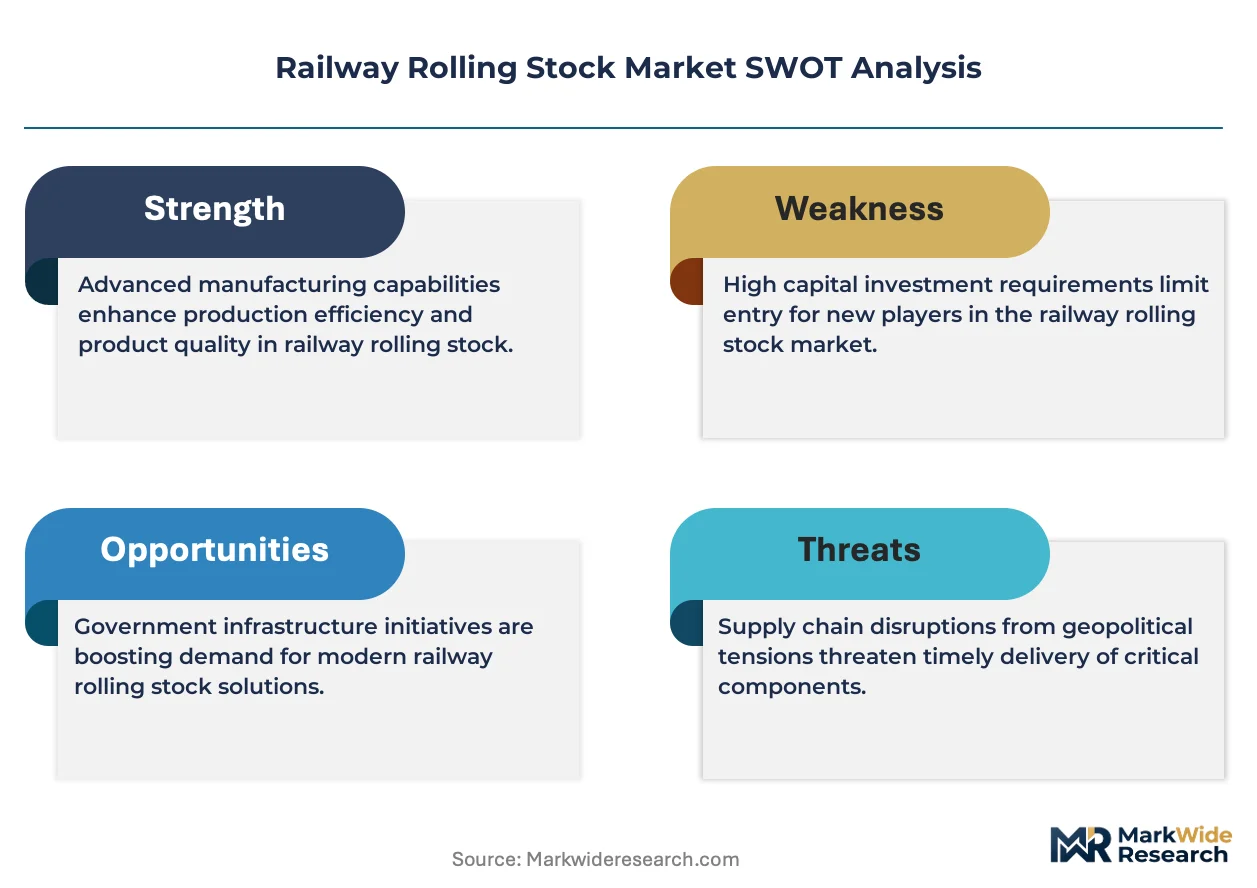
- EU Green Deal phase-out mandates:Stringent emissions ceilings under the F-Gas Regulation and complementary national frameworks are compelling fleet operators to accelerate diesel locomotive retirement and electrify unelectrified corridors.
- Cross-border freight corridors:State-backed rail modernization in China and Central Asian transit routes sustain procurement volumes for heavy-haul electric locomotives and specialized flat wagons.
- Urban transit expansion:Megacity authorities in India, Brazil, and Southeast Asia are tendering metro and commuter multiple-units to relieve road congestion and meet air quality targets.
Market Restraints
- Aluminum ingot price volatility:Body-shell economics hinge on London Metal Exchange pricing swings that erode fixed-price contract margins for coach manufacturers without backward integration into primary metal production.
- Electrification infrastructure gaps:Remote regional lines and unelectrified freight corridors in Russia, Canada, and Australia strand diesel-dependent operators between stranded asset risk and prohibitive catenary capex.
- Crashworthiness certification divergence:EN 15227, FRA Tier I/II, and China's GB standards impose non-harmonized testing protocols that fragment design tooling and delay type approval for export-bound equipment.
Strategic Opportunities
- Hydrogen fuel-cell regional trains:Germany's KBA certification pathway and comparable frameworks in the Netherlands create first-mover positioning for zero-emission traction on non-electrified secondary lines.
- Predictive maintenance software bundles:Digital rail services that integrate sensor telemetry with axle-load monitoring enable recurring revenue streams beyond hardware delivery.
- Maintenance-of-way equipment leasing:Track renewal cycles in Poland, Turkey, and Mexico favor asset-light procurement models for tampers, ballast regulators, and rail grinders.
Industry Challenges
- Electromagnetic compatibility testing backlog:China's MIIT quota enforcement and GB/T 24338 radiated emission requirements create bottlenecks at certified laboratories, stretching product launch timelines.
- Legacy signaling integration:ETCS Level 2 deployment on brownfield networks demands bespoke interface engineering with national ATP systems, inflating project risk and warranty exposure.
- Welding technician scarcity:Aluminum friction-stir and automated MIG processes require certified specialists that outpace vocational pipeline output in Eastern European manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Rolling Stock Market |
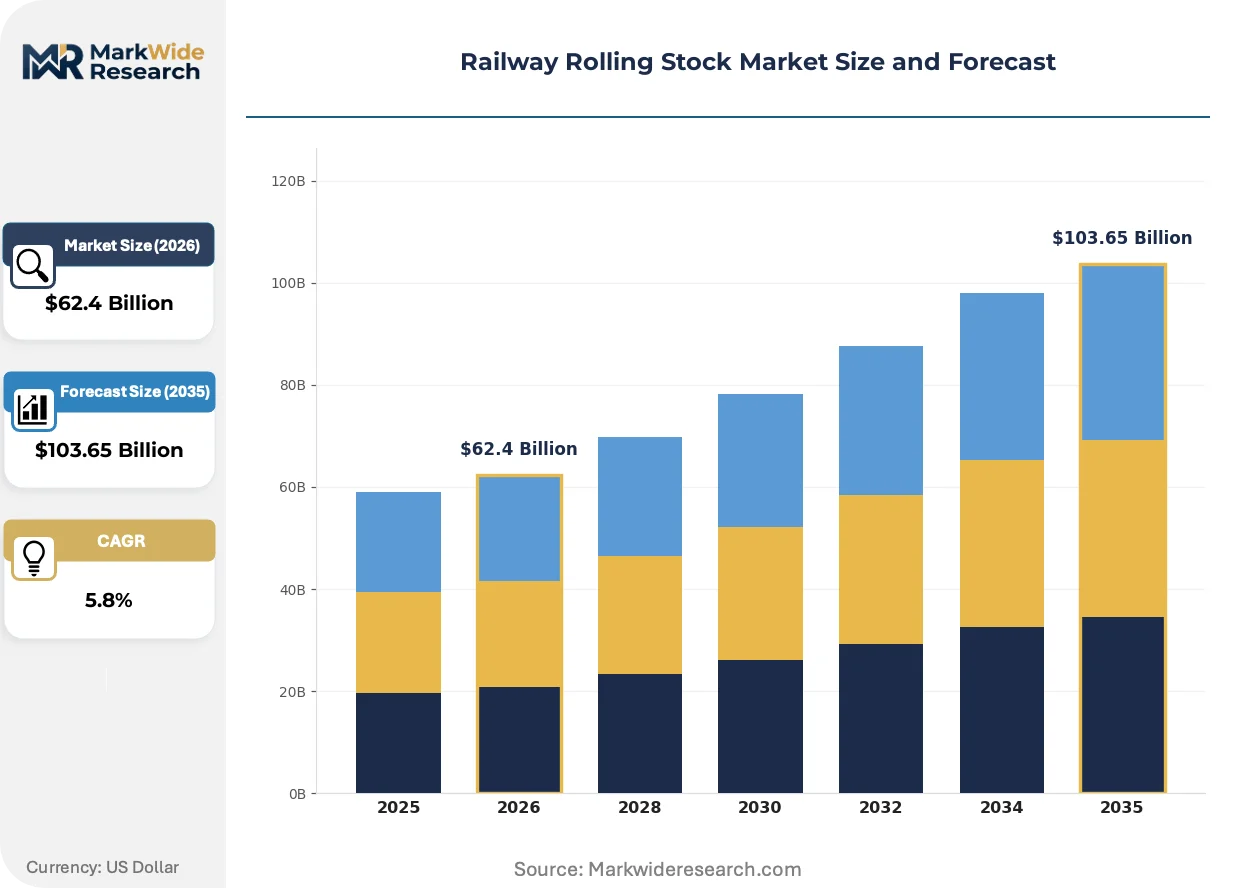
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locomotives, Passenger Coaches, Freight Wagons, Maintenance-of-Way Equipment Technology: Conventional, Electric, Diesel, Hybrid End User: Freight Operators, Passenger Carriers, Urban Transit Authorities, Rail Infrastructure Managers Deployment: Urban Systems, Intercity Services, Freight Corridors, Regional Transport |
| Companies Covered | CRRC Corporation Limited, Alstom, Siemens Mobility, Stadler Rail AG, Wabtec Corporation, Hitachi Rail, CAF, Hyundai Rotem, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Rolling Stock Market Evolving Landscape
Active material substitution and digital service layering are compressing traditional equipment margins while opening adjacent revenue pools in fleet analytics and energy management.
Aluminum extrusion-intensive body structures are consolidating supplier tiers in passenger coach manufacturing. High-speed train and metro operators in Spain, South Korea, and Turkey specify hollow-section extruded sidewalls and roof modules to achieve 12-15% mass reduction versus carbon steel equivalents. This material transition is consolidating procurement leverage with smelter-integrated fabricators who control billet supply and tempering sequences.
The EU F-Gas Regulation and national bans on hydrofluorocarbon refrigerants are mandating CO2 heat pumps and propane-based HVAC in new-build rolling stock. Coach builders serving Deutsche Bahn, SNCF, and Trenitalia must redesign climate systems around flammable refrigerant containment and leak detection. The retrofit opportunity across existing diesel multiple-units in Poland, Romania, and the Czech Republic is compressing replacement timelines for end-of-life vapor-compression equipment.
Power-purchase agreements and energy-as-a-service models are displacing capital-heavy electrification decisions for regional operators. Transit authorities in Texas, Queensland, and South Africa are procuring battery-electric multiple-units with charging infrastructure bundled under availability-based contracts rather than owning traction substations outright. This financial engineering is visible most acutely in sunbelt geographies where solar-plus-storage arrays can anchor depot-based charging at lower levelized cost than grid extension.
Railway Rolling Stock Market Segmentation
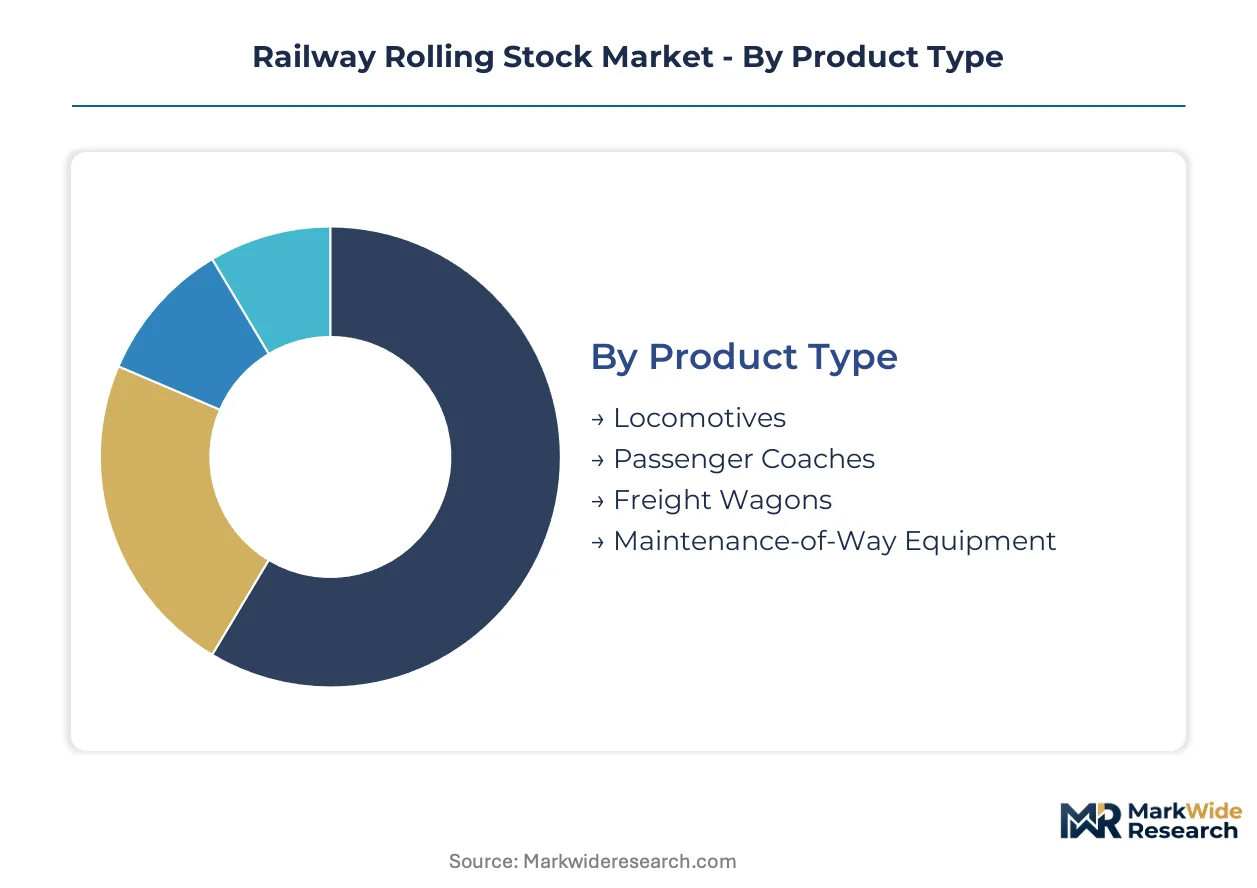
Rolling stock procurement follows distinct replacement cycles across vehicle categories, with electrification mandates and urbanization patterns reshaping fleet composition. Segment boundaries increasingly blur as hybrid architectures penetrate traditional diesel strongholds and digital service bundles attach to hardware sales.
Product Type:
Upgrade cycles vary sharply by asset class, with passenger equipment turning over fastest under emissions deadlines while freight wagons endure decades of service extension.
- Locomotives:Traction units rated from 2,000 kW for regional service to 9,000 kW for heavy-haul freight dominate capital deployment. China's state rail procurement and India's diesel-to-electric conversion programs concentrate demand for electric variants with regenerative braking and IGBT power electronics.
- Passenger Coaches:Aluminum-intensive body shells with EN 15227 crashworthiness compliance now displace carbon steel construction for intercity and high-speed applications. European operators under F-Gas Regulation deadlines are retrofitting HVAC systems and accelerating coach replacement timelines.
- Freight Wagons:Specialized flat cars for containerized intermodal traffic and hopper wagons for bulk commodities sustain manufacturing volumes. Procurement concentrates in China-Europe corridor expansion and Australian iron ore export routes.
- Maintenance-of-Way Equipment:Tampers, ballast regulators, and rail grinders follow track renewal cycles rather than fleet expansion. Leasing models are gaining traction in Poland, Turkey, and Mexico where infrastructure managers prioritize capital flexibility.
Locomotives sit at the top of the volume ranking, with passenger coaches climbing the fastest as urban transit authorities tender metro and commuter fleets.
Technology:
Cost tiers separate mature propulsion architectures from emerging platforms still seeking scale economies in manufacturing and aftermarket support.
- Conventional:Unpowered rolling stock including passive coaches and non-motorized wagons relies on separate locomotive traction. Demand persists in heritage railway tourism and developing markets where electrification infrastructure remains sparse.
- Electric:Catenary-fed multiple units and locomotives with AC induction or permanent-magnet synchronous motors now dominate intercity order books. Germany's KBA certification pathway and China's MIIT quotas are accelerating electric platform deployment across regional networks.
- Diesel:Compression-ignition engines with Tier 4/Stage V emission compliance retreat to unelectrified freight corridors and remote regional lines. Russia, Canada, and Australia represent residual demand centers where catenary capex remains prohibitive.
- Hybrid:Battery-diesel and hydrogen fuel-cell architectures capture growing interest for non-electrified secondary lines. Netherlands and Germany are certifying hydrogen regional trains under national safety board frameworks.
Electric traction commands the revenue concentration, with hybrid platforms gaining share fastest as operators seek zero-emission alternatives without full infrastructure commitment.
End User:
Customer type determines procurement sophistication, with integrated national carriers leveraging scale against fragmented infrastructure managers purchasing specialized equipment.
- Freight Operators:Heavy-haul and intermodal carriers prioritize axle-load ratings and energy efficiency metrics in locomotive tenders. Cross-border corridor operators in Central Asia and Europe specify multi-system electric locomotives compatible with varying catenary voltages.
- Passenger Carriers:Intercity and long-distance operators balance seat density against amenity specifications in coach procurement. SNCF, Deutsche Bahn, and Trenitalia drive aluminum body-shell adoption through technical specifications.
- Urban Transit Authorities:Megacity operators in India, Brazil, and Southeast Asia tender metro and commuter multiple-units with platform-screen door compatibility and high-acceleration traction. Air quality targets accelerate fleet replacement timelines.
- Rail Infrastructure Managers:Track-owning entities procure maintenance-of-way equipment through availability-based contracts rather than capital purchase. Poland and Turkey favor leasing structures for tampers and rail grinders.
Freight operators anchor the installed base, with urban transit authorities expanding most quickly as metropolitan congestion drives rail investment.
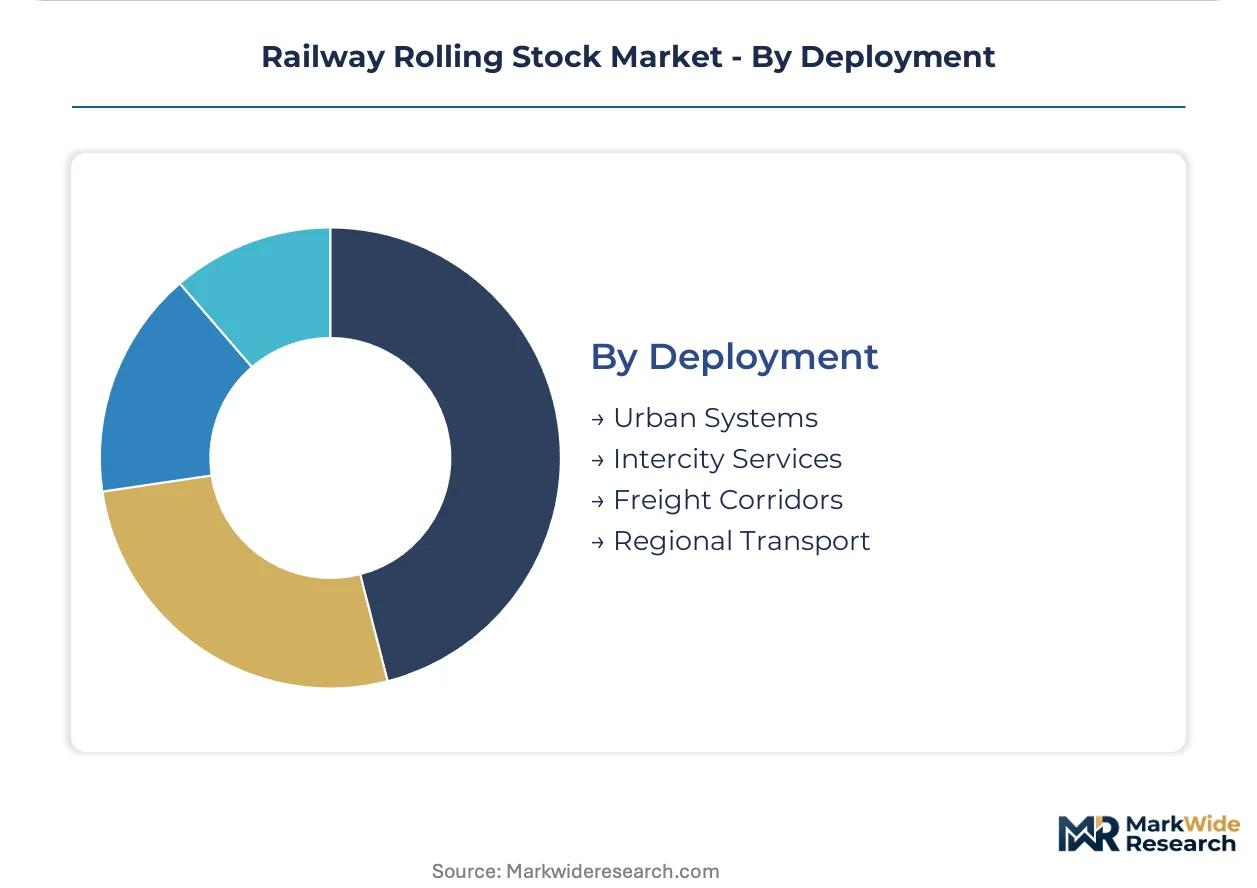
Deployment:
Application context dictates design margins, with urban systems prioritizing acceleration and freight corridors optimizing for continuous high-speed operation.
- Urban Systems:Metro, light rail, and commuter networks demand high-floor or low-floor multiple units with rapid acceleration profiles. Procurement concentrates in India, Brazil, and Southeast Asian megacities.
- Intercity Services:High-speed and conventional intercity operations specify crashworthy coaches with pressure-sealed bodies for tunnel transit. European operators under EU Green Deal mandates are retiring diesel multiple-units.
- Freight Corridors:Heavy-haul and intermodal routes require locomotives with high continuous power ratings and specialized wagons for container, bulk, and automotive traffic. China-Europe land bridge expansion sustains procurement.
- Regional Transport:Secondary and rural lines without electrification infrastructure favor diesel or emerging hydrogen traction. Germany and the Netherlands are piloting fuel-cell multiple units on non-electrified branches.
Freight corridors generate the heaviest equipment throughput, with urban systems showing the steepest expansion trajectory as metropolitan rail networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed rail modernization and cross-border freight corridors sustain the dominant procurement volumes in this market. India and Germany follow as critical demand centers driven by urban transit expansion and emissions mandates. Brazil and Australia round out the geographic footprint with specialized freight and regional transport requirements.
China
Cross-border freight corridors along Central Asian transit routes drive heavy-haul electric locomotive demand. MIIT enforces domestic new-energy rail vehicle quotas and GB standards for electromagnetic compatibility. CRRC Corporation leverages captive aluminum forging capacity in Changchun and Qingdao to dominate electric multiple-unit output.
Germany
Hydrogen fuel-cell regional trains gain traction on non-electrified secondary lines through KBA certification pathways. The EU Green Deal and F-Gas Regulation compel Deutsche Bahn to accelerate diesel locomotive retirement. Siemens Mobility anchors digital rail services development in Munich and Berlin.
India
Megacity authorities in Mumbai, Delhi, and Bangalore tender metro and commuter fleets to relieve road congestion. The CEA mandates electrification targets that reshape locomotive procurement priorities. Integral Coach Factory in Chennai and Rail Coach Factory in Kapurthala concentrate aluminum body-shell fabrication capacity.
Brazil
Urban transit authorities in São Paulo and Rio de Janeiro expand commuter networks amid air quality targets. ANVISA-equivalent rail safety frameworks govern crashworthiness standards for imported equipment. Hyundai Rotem and CAF compete for metropolitan multiple-unit contracts in southeastern manufacturing clusters.
Australia
Iron ore export routes in Western Australia sustain specialized hopper wagon and heavy-haul locomotive demand. Remote regional lines without electrification infrastructure strand operators between diesel asset risk and prohibitive catenary investment. Perth and Brisbane anchor maintenance-of-way equipment leasing activity for track renewal cycles.
Railway Rolling Stock Market Competitive Landscape
Capacity expansion dominates the current landscape as aluminum body-shell fabrication consolidates procurement power among smelter-integrated suppliers. The vendor base separates into three strategic archetypes: state-backed national champions with captive metal supply, European system integrators with hydrogen and digital platforms, and Asian specialists competing on cost-engineered commuter equipment. M&A activity and strategic partnerships represent the dominant competitive moves, with technology licensing agreements accelerating hydrogen fuel-cell deployment.
Among state-backed fabricators, CRRC Corporation Limited exemplifies the vertically integrated archetype through its captive aluminum supply chain. Alstom and Siemens Mobility occupy positions within the European system-integrator tier, anchoring market access through established certification pathways with national safety boards. These three entities represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom |
| Siemens Mobility |
| Stadler Rail AG |
| Wabtec Corporation |
| Hitachi Rail |
| CAF |
| Hyundai Rotem |
| Kawasaki Heavy Industries |
| Others |
Value Network & Pricing Analysis
Captive aluminum forging capacity among state-backed fabricators anchors both supply security and pricing power in passenger rolling stock procurement. This backward integration into primary metal production insulates dominant suppliers from London Metal Exchange volatility while compressing margins for carbon steel-dependent competitors.
Pricing Analysis
Aluminum ingot cost pass-through dominates contract structures for body-shell fabrication, with fixed-price agreements eroding profitability when LME prices spike. Three-tier pricing structure across premium certified, standard compliance, and economy-grade equipment reflects EN 15227 crashworthiness tiering and after-sales service bundling. Cost compression in standard-tier passenger coaches is intensifying because carbon steel-dependent builders lack billet supply control. Freight operators exhibit highest price sensitivity due to volume procurement cycles, while urban transit authorities prioritize availability-based contracts over unit economics.
Supply Chain Analysis
EN 15227, FRA Tier I/II, and China's GB/T 24338 certification requirements gate supplier participation and fragment tooling investments across export markets. Manufacturing concentrates in China, Germany, and India, with Changchun, Qingdao, and Chennai anchoring aluminum extrusion capacity. Production draws from primary aluminum billets, IGBT power electronics, and specialized friction-stir welding equipment. Single-source vulnerability in permanent-magnet synchronous motor supply creates exposure to rare-earth processing concentration. Distribution runs through national rail procurement authorities and infrastructure managers with long-cycle tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway rolling stock procurement has shifted toward late-cycle quality specifications as operators prioritize aluminum-intensive crashworthiness and digital service bundles over base hardware economics.
For Market Incumbents: Extend digital rail service portfolios into predictive maintenance software to capture recurring revenue beyond rolling stock delivery. Deepen captive aluminum supply control through tempering sequence investments that lock in body-shell procurement leverage against carbon steel competitors. Hydrogen fuel-cell platform certification with Germany's KBA and Netherlands safety boards creates defensive moats as diesel phase-out accelerates under EU Green Deal mandates. For New Entrants and Emerging Players: Begin with maintenance-of-way equipment leasing in Poland, Turkey, and Mexico where infrastructure managers prioritize capital flexibility over ownership. Battery-electric multiple-unit availability contracts in sunbelt geographies with solar-plus-storage depot charging represent the most penetrable entry point. Partner with regional transit authorities on charging-infrastructure-as-a-service to bypass heavy electrification capex requirements. For Investors and Strategic Acquirers: Roll-up economics work for aluminum-extrusion specialists with EN 15227 certification pathways because body-shell consolidation is compressing supplier tiers and concentrating procurement leverage. Target mid-cap fabricators with captive billet supply and established national safety board relationships. Watch hydrogen fuel-cell type approval velocity in Germany and Netherlands as inflection indicator for zero-emission traction market formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captive billet supply insulates CRRC and Alstom from LME price volatility in body-shell contracts. |
| Hydrogen Fuel-Cell Platform Certification | KBA pathway in Germany creates first-mover positioning for zero-emission regional train deployment. |
| Predictive Maintenance Software Bundling | Siemens Mobility extends digital rail services from hardware into recurring sensor-telemetry revenue streams. |
| Availability-Based Leasing Models | Track renewal cycles in Poland and Turkey favor asset-light procurement for tampers and rail grinders. |
| Cross-Border Freight Corridor Expansion | China-Europe land bridge sustains heavy-haul electric locomotive demand across Central Asian transit routes. |
Research Methodology
Coverage spans China, Germany, India, Brazil, and Australia, with primary inputs from each market combining executive interviews with rolling stock procurement directors, rail infrastructure managers, aluminum extrusion plant engineers, and national safety board certification leads. Secondary validation draws from MIIT quota filings, KBA type approval registers, EU F-Gas Regulation implementation reports, and customs trade data on aluminum billet flows. Bottom-up fleet replacement cycle analysis triangulates with top-down infrastructure investment forecasts across the projection horizon.
Rate-of-change decomposition separates volume growth from mix-shift effects across vehicle type, propulsion technology, end-user segment, and deployment context. Segmentation modeling incorporates locomotive power rating tiers, body-shell material specifications, and regional regulatory cluster variations. CAGRs derive from replacement cycle timing, electrification mandate enforcement trajectories, and aluminum price scenario stress-testing. Forecast inputs include urban transit authority tender pipelines, cross-border freight corridor investment commitments, and hydrogen fuel-cell certification velocity.
Several conditions sit outside the modeled scope, including unannounced infrastructure stimulus programs, sudden rare-earth export restrictions affecting permanent-magnet motor supply, and non-harmonized crashworthiness standard convergence. Forecasts reflect documented assumptions regarding electrification infrastructure buildout pace and aluminum ingot price band stability. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or China's MIIT quota acceleration timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Smart Locomotive Market
Railway
Railway Window Market
Railway
Locomotive Maintenance Market
Railway
Freight Cars Market
Railway
Global Hyperloop Train Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railway Automated Inspection Equipment Market
Railway
South Africa Rail Freight Transport Market
Railway
Train Locomotive Suspension Market
Railway
Light Rail Market
Railway
Railway Buffer Stops Market
Railway
Railway Pantograph Market
Railway
Railway Braking System Market
Railway
Global Train Control and Management Systems Market
Railway
Locomotive Doors Market
Railway
Rail Composites Market