
 Hopper Car Market | 2026-2036
Hopper Car Market Size, Share, and Industry Trends Forecast 2026-2036
Hopper Car Market Analysis
Aluminum is pivoting toward broader use in hopper car construction as rail operators seek weight reduction and fuel efficiency on long-haul grain routes. TrinityRail leverages in-house extrusion capabilities to control aluminum supply costs across its manufacturing network. The Greenbrier Companies sustains competitive position through specialized grain car designs that dominate Pacific Northwest export corridors. American Railcar Industries anchors its order book with steel hopper variants serving Powder River Basin coal shippers.
A hopper car is a self-unloading railroad freight car with sloped floor panels and bottom discharge doors, typically constructed with 100-ton to 286,000-pound gross rail load ratings, designed for efficient gravity-fed unloading of dry bulk commodities. Grain hopper configurations incorporate aerated sidewalls and temperature-monitoring systems to preserve crop quality during multi-day transit from interior elevators to coastal terminals. Steel material categories retain volume leadership in coal and ore applications where abrasion resistance governs specification, while aluminum segments capture margin pools in premium agricultural service where tare weight directly determines revenue tonnage per train. High-capacity units represent the fastest-growing segment as Class I railroads optimize unit-train economics with 110-car configurations between single-origin loaders and port terminals.
The Federal Railroad Administration enforces tank and hopper car safety standards under 49 CFR Part 215, while the Association of American Railroads (AAR) administers interchange rules that effectively gate market access for non-compliant builders. Transport Canada and the FRA coordinate on harmonized brake system certifications that shape cross-border fleet interoperability. Stakeholders must monitor evolving EPA locomotive emission standards that indirectly pressure rail economics and capital allocation toward lighter, higher-capacity rolling stock.
Market Dynamics
Precision-loading sensor arrays and automated weight-distribution systems are compressing loading times at country elevators while cutting grain spoilage rates, forcing fleet operators to retire legacy mechanical-door cars ahead of standard depreciation cycles.
Growth Catalysts
- FRA Coupler Modernization Mandates:The Federal Railroad Administration's updated crashworthiness standards for Type E couplers are accelerating replacement schedules across US Class I railroads.
- Aluminum Extrusion Advances:In-house billet casting capabilities at major fabricators are trimming tare weight premiums versus steel to under fifteen percent in standard grain service configurations.
- Midwest Elevator Consolidation:Super-elevator construction along the Illinois River corridor is generating unit-train demand for 110-car dedicated fleets with rapid-cycle unloading systems.
Market Restraints
- Steel Scrap Volatility:Abrasion-resistant plate pricing swings are compressing margin visibility for coal-service builders committed to multi-year lease structures.
- Foundry Concentration:Ductile iron casting capacity for outlet gate mechanisms concentrates in two US manufacturing clusters, creating single-source vulnerability.
- Coal Volume Collapse:Powder River Basin thermal coal loadings are displacing steel hopper demand faster than agricultural uptake can backfill production slots.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Manitoba pulse crop exports through Vancouver terminals are outpacing existing covered hopper availability.
- EPA Locomotive Tier 4 Compliance:Heavier emission-control equipment on new road locomotives is amplifying the fuel-economy payoff from lighter aluminum car bodies.
- Sensor-as-a-Service Models:Grain-quality monitoring hardware is migrating from capital purchase to per-mile subscription pricing, opening fleet access for mid-size agricultural cooperatives.
Industry Challenges
- Welding Certification Bottlenecks:Aluminum MIG and friction-stir welding qualifications for pressure-rated hopper seams are extending production ramp timelines at converted steel facilities.
- AAR Interchange Rule Lags:Proposed revisions to Plate C dimensional clearances for high-capacity units remain in committee, freezing design finalization for next-generation 286k GRL cars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hopper Car Market |
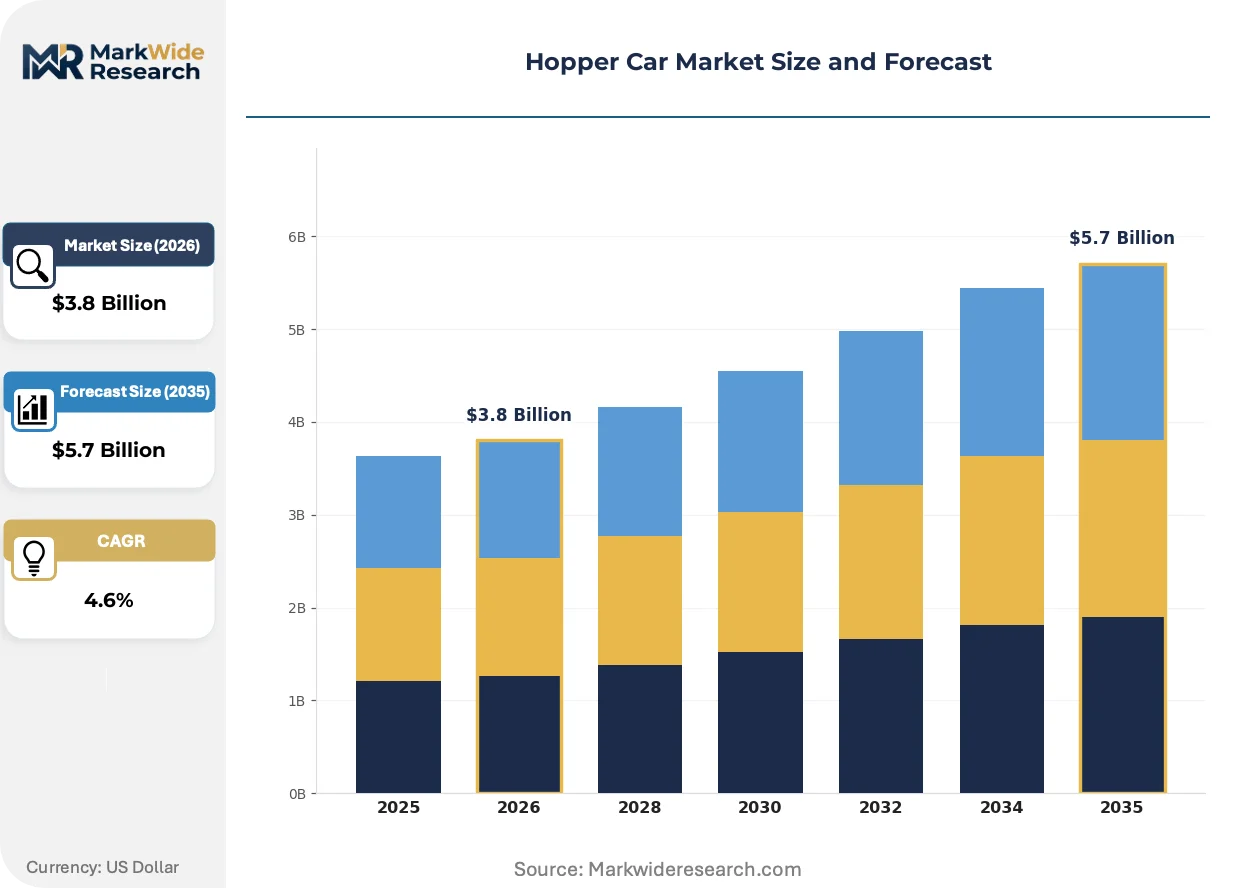
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal Hopper, Grain Hopper, Ballast Hopper, Ore Hopper Material: Steel, Aluminum, Composite, Plastic End User: Mining Industry, Agricultural Sector, Transportation Services, Construction Firms Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | American Railcar Industries, Kawasaki, The Greenbrier Companies, Novatec, PIOVAN S.p.A., TrinityRail, National Steel Car, Maguire Products Inc., FreightCar America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hopper Car Market Emerging Trajectories
Digital payload management and predictive unloading systems are compressing terminal dwell times while enabling real-time commodity tracking from interior loader to coastal discharge point.
Electrified bottom-door actuation systems are replacing pneumatic and manual discharge mechanisms on new-build grain hoppers. Major agricultural shippers in the US corn belt are specifying these units for unit-train commitments exceeding five hundred annual cycles. This shift is electrifying competitive differentiation around unloading speed rather than pure capacity metrics.
The Association of American Railroads is tightening enforcement of Manual of Standards and Recommended Practices Section C-III for brake system interoperability. Builders must now certify dual-mode compatibility between conventional pneumatic and emerging electronically controlled pneumatic configurations. High-frequency shuttle operators on the Columbia River export corridor are first movers in retrofitting existing fleets to preempt interchange rejection.
Buyers are consolidating procurement authority at the holding-company level, displacing decentralized elevator-level fleet decisions. Large grain merchants are negotiating master lease agreements directly with railcar lessors, stripping equipment specification control from individual facility managers. This concentration is most visible across the US Gulf export complex, where three merchants now control access to over sixty percent of dedicated hopper capacity.
Hopper Car Market Segmentation
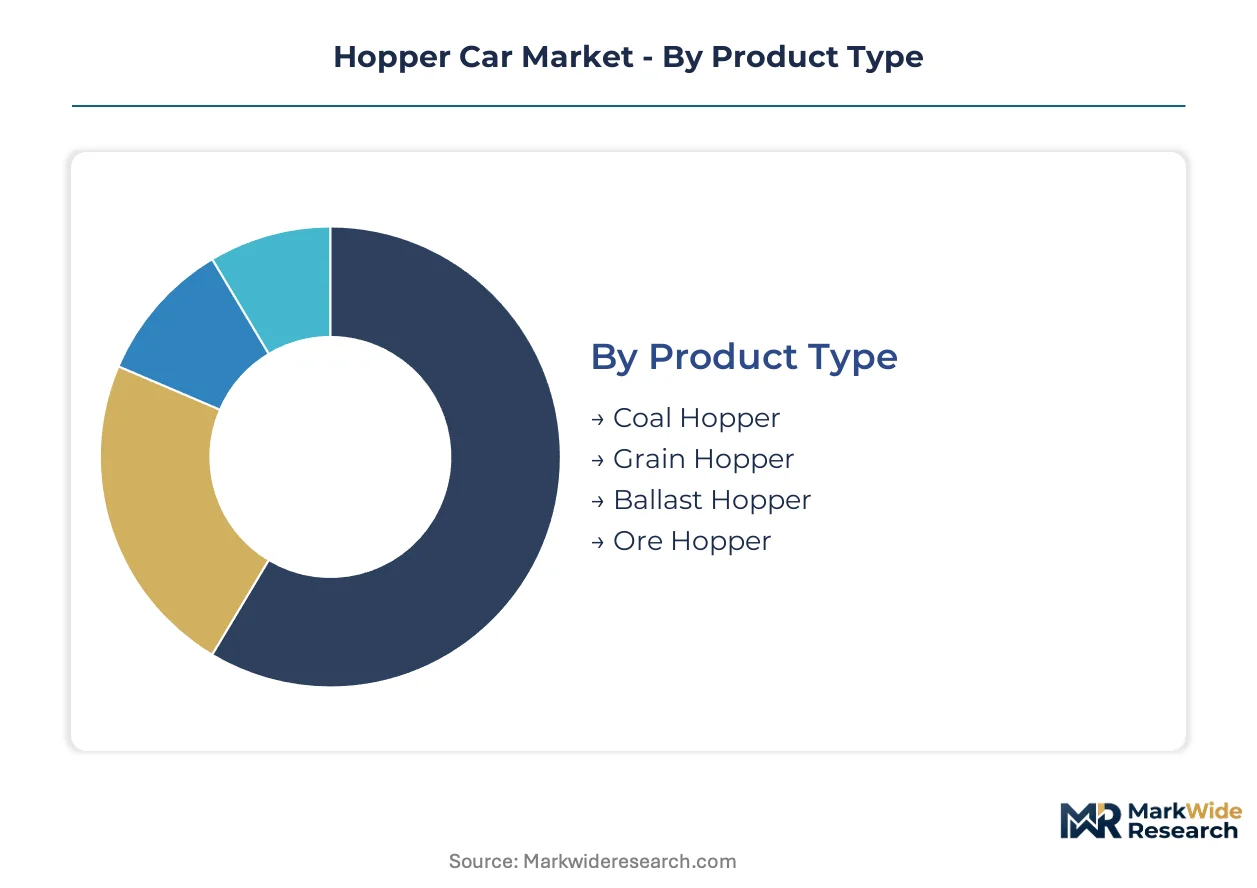
Hopper car procurement diverges sharply across commodity types and operating economics. Buyers prioritize abrasion resistance for mineral service, tare weight for grain revenue tonnage, and discharge speed for high-frequency shuttle circuits.
Product Type:
Grain shippers prioritize spoilage prevention and rapid unloading; coal operators demand impact resistance and volume density.
- Coal Hopper:Reinforced steel bodies with 286,000-pound gross rail load ratings withstand high-impact loading at surface mines. Powder River Basin thermal coal displacement is forcing builders to retool production lines toward agricultural variants faster than order backfill permits.
- Grain Hopper:Aerated sidewalls and temperature-monitoring systems preserve crop quality during multi-day transit from interior elevators to coastal terminals. Midwest elevator-to-port unit trains dominate procurement, with 110-car configurations now standard for Illinois River corridor movements.
- Ballast Hopper:Open-top designs with manual discharge gates serve track maintenance-of-way contractors on scheduled infrastructure renewal programs.
- Ore Hopper:Extreme-duty steel construction with reinforced discharge chutes handles iron ore and taconite movements from Lake Superior mines to Great Lakes ports.
Grain hoppers lead volumes today; coal hoppers are losing share fastest.
Material:
Cost structure and commodity economics determine material selection more than upfront capital outlay.
- Steel:Abrasion-resistant plate grades dominate coal and ore applications where impact damage governs lifecycle economics. Scrap price volatility compresses margin visibility for builders committed to multi-year lease structures.
- Aluminum:Extruded panel construction reduces tare weight by fifteen percent versus steel equivalents, directly increasing revenue tonnage per train on long-haul grain routes. In-house billet casting capabilities at major fabricators are narrowing cost premiums.
- Composite:Glass-reinforced polymer panels in prototype testing for corrosive chemical service where metallic fatigue accelerates.
- Plastic:Limited deployment in lightweight, low-abrasion specialty applications with minimal structural load requirements.
Steel retains installed base dominance; aluminum is climbing the fastest.
End User:
Fleet ownership models separate capital-rich merchants from equipment-leasing-dependent operators.
- Mining Industry:Integrated producers with captive rail operations specify heavy-duty steel configurations for 24-hour loading cycles at remote extraction sites.
- Agricultural Sector:Elevator cooperatives and grain merchants are consolidating procurement authority at holding-company level, negotiating master lease agreements directly with railcar lessors.
- Transportation Services:Third-party logistics providers and short-line railroads acquire mixed fleets through operating leases with maintenance-inclusive terms.
- Construction Firms:Project-based aggregate shippers demand flexible lease durations aligned with infrastructure contract timelines.
Agricultural sector leads order intake; transportation services are expanding most quickly.
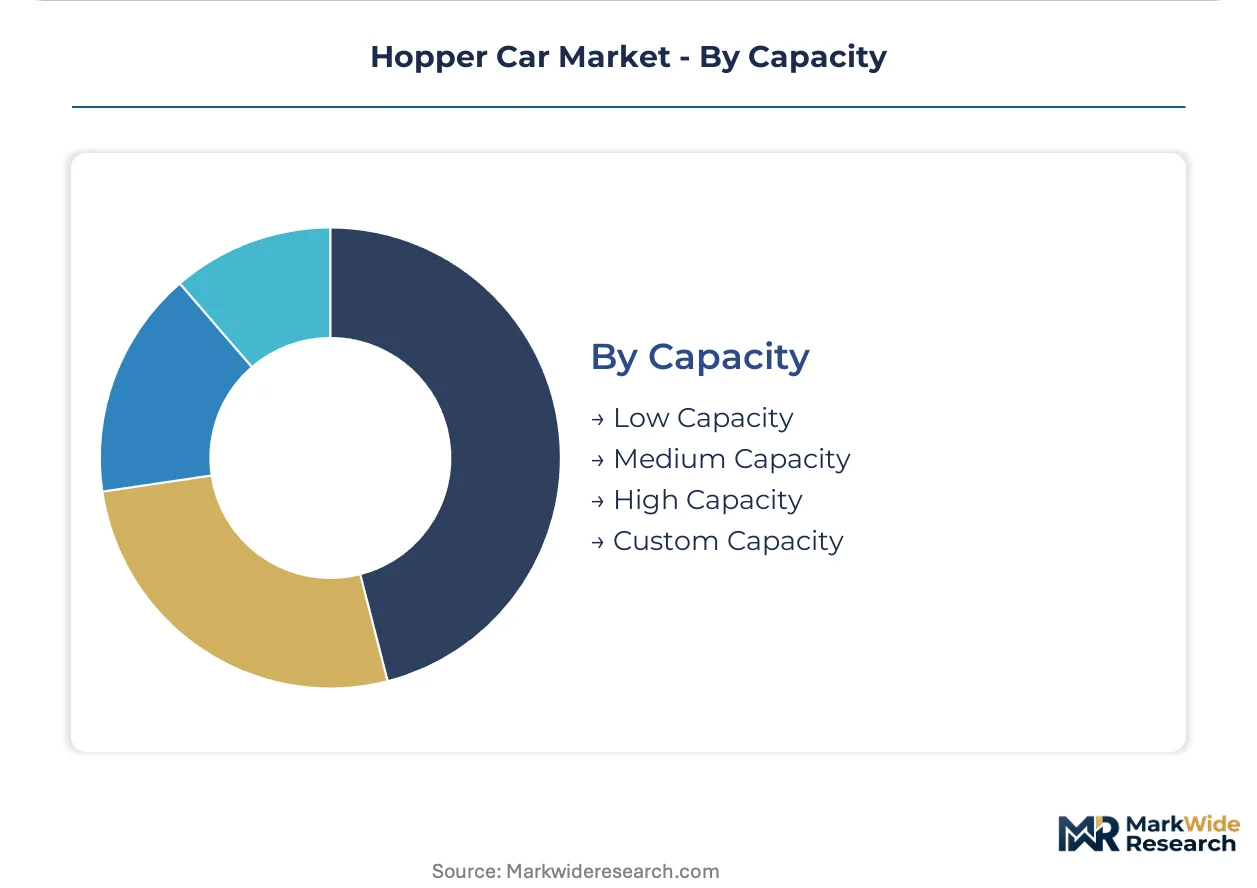
Capacity:
Unit-train economics favor maximum allowable gross rail load within track and bridge constraints.
- Low Capacity:Legacy 100-ton designs on regional short lines with restricted infrastructure clearances.
- Medium Capacity:Standard 263,000-pound configurations serving diversified commodity shippers without dedicated train operations.
- High Capacity:286,000-pound gross rail load units with 110-car unit-train optimization between single-origin loaders and port terminals. Class I railroads specify these for Illinois River-to-Gulf and Pacific Northwest export corridors.
- Custom Capacity:Engineering modifications for specialized density commodities or restricted clearance routes.
High capacity dominates new-build investment; custom capacity shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Midwest grain corridor concentrates the densest procurement activity for covered hoppers, with Illinois River super-elevators driving 110-car unit-train specifications. Fleet renewal cycles diverge sharply by commodity basin and regulatory jurisdiction.
United States
The Federal Railroad Administration mandates Type E coupler upgrades under 49 CFR Part 215, forcing accelerated retirement of legacy mechanical-door cars. Precision-loading sensor arrays at Iowa and Illinois country elevators are compressing loading cycles while cutting spoilage rates. TrinityRail and Greenbrier anchor manufacturing capacity in Texas and Oregon to serve Gulf and Pacific Northwest export corridors.
Canada
Saskatchewan and Manitoba pulse crop exports through Vancouver terminals are outpacing existing covered hopper availability. Transport Canada coordinates brake system certifications with the FRA under harmonized cross-border standards that govern fleet interoperability. National Steel Car maintains Ontario-based production lines serving Prairie elevator cooperatives and Vancouver-bound unit trains.
Mexico
Kansas City Southern and Ferromex shuttle networks are expanding dedicated grain service from Sinaloa and Sonora agricultural zones to Lázaro Cárdenas port terminals. The Secretariat of Infrastructure, Communications and Transportation (SICT) enforces rolling stock safety standards aligned with AAR interchange protocols. Guadalajara-based maintenance clusters are retrofitting US-originated fleets for tropical climate operations.
Brazil
Mato Grosso soybean and corn movements to Santos and Paranaguá ports are straining existing hopper availability on the Ferrovia Norte-Sul corridor. ANTT, the national land transport regulator, oversees freight car certification under CONTRAN safety resolutions. Campo Grande logistics terminals are consolidating procurement authority for 80-car unit-train commitments directly with international lessors.
Australia
GrainCorp and CBH Group are renewing fleets for wheat and barley exports from Western Australia and South Australia to Middle Eastern and Asian markets. The Office of the National Rail Safety Regulator (ONRSR) mandates compliance with Rail Industry Safety and Standards Board (RISSB) rolling stock codes. Adelaide and Perth maintenance depots are specializing in high-cycle aluminum body repairs for long-haul interstate routes.
Hopper Car Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and commodity specialization. The vendor base clusters around three strategic tiers: integrated railcar builders with captive component supply, specialized agricultural equipment fabricators, and diversified industrial conglomerates with rail divisions. Dominant competitive moves center on backward integration into aluminum extrusion and strategic partnerships with Class I railroads for dedicated fleet commitments.
Among North American integrated builders, TrinityRail, The Greenbrier Companies, and American Railcar Industries exemplify distinct archetypes within the market structure. TrinityRail represents the vertically integrated model with in-house billet casting capabilities. Greenbrier occupies a position focused on specialized grain car designs for export corridors. American Railcar Industries anchors the steel-variant segment serving mineral shippers. These three entities collectively illustrate how material specialization and geographic focus stratify competitive positioning across commodity-specific demand pools.
| Leading Market Players |
|---|
| American Railcar Industries |
| Kawasaki |
| The Greenbrier Companies |
| Novatec |
| PIOVAN S.p.A. |
| TrinityRail |
| National Steel Car |
| Maguire Products Inc. |
| FreightCar America |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between AAR-compliant builders and non-certified fabricators splits pricing power and procurement access across North American fleet operators. This divergence concentrates premium pricing with integrated manufacturers holding captive aluminum extrusion while commodity steel variants compete on scrap-cost pass-through volatility.
Pricing Analysis
Input-cost pass-through from steel scrap and aluminum billet markets governs contract structures for multi-year lease commitments. Three-tier pricing structure across premium aluminum grain service, standard steel agricultural configurations, and economy-grade coal variants reflects tare weight advantages and regulatory compliance tiers. Cost compression in steel coal-service segments is intensifying because Powder River Basin volume collapse outpaces agricultural backfill. Agricultural cooperatives exhibit highest price sensitivity due to consolidated master lease negotiations, while integrated grain merchants prioritize unloading speed over capital outlay.
Supply Chain Analysis
Aluminum billet supply rests on domestic casting capacity concentrated in Texas and Oregon manufacturing clusters, with secondary sourcing from Canadian smelters. Ductile iron casting for outlet gate mechanisms draws from two US foundry regions, creating single-source vulnerability for critical discharge components. Abrasion-resistant steel plate feeds from domestic mills and select Korean producers, exposing builders to tariff exposure on alloy grades. Distribution runs through direct Class I railroad procurement, third-party lessor fleets, and elevator cooperative master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
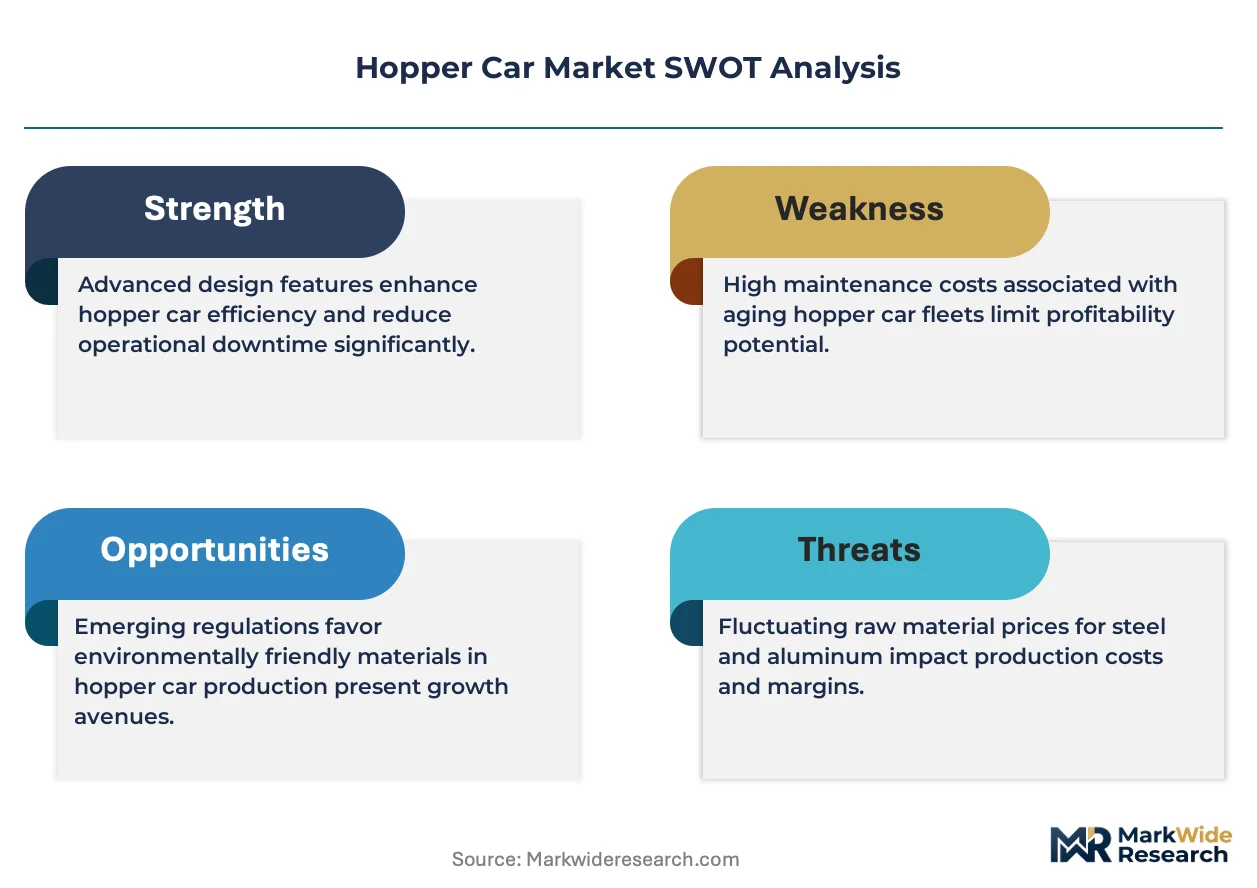
This market compounds regulatory demand through FRA Type E coupler mandates accelerating replacement cycles across legacy mechanical-door fleets.
For Market Incumbents: To counter foundry concentration risk for ductile iron gate castings, secure dual-source agreements with secondary US clusters and Canadian suppliers. Backward integration into aluminum billet casting preserves margin control against London Metal Exchange volatility. Anchor production slots through dedicated fleet commitments with Illinois River super-elevator operators. For New Entrants and Emerging Players: Launch via sensor-as-a-service subscription models targeting mid-size agricultural cooperatives excluded from master lease negotiations. Saskatchewan and Manitoba pulse crop export corridors present the most penetrable geography given covered hopper shortages. Differentiate through rapid-cycle unloading system integration rather than pure capacity metrics. For Investors and Strategic Acquirers: Consolidation pressure builds where welding certification bottlenecks for aluminum MIG and friction-stir qualifications extend production ramp timelines at converted steel facilities. Long-term viability favors builders with in-house extrusion capabilities and AAR interchange certification infrastructure. Watch AAR Plate C dimensional clearance committee decisions as inflection trigger for next-generation 286k GRL design finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | TrinityRail's captive billet casting shields margin from LME price swings across grain service contracts. |
| Sensor-as-a-Service Platform Launch | Grain-quality monitoring hardware subscriptions open fleet access for cooperatives bypassing capital purchase barriers. |
| Dual-Mode Brake System Certification | Greenbrier's ECP-pneumatic compatibility preempts AAR interchange rejection on Columbia River shuttle corridors. |
| Super-Elevator Master Lease Negotiation | Direct holding-company agreements strip specification control from facility managers, locking dedicated 110-car fleets. |
| Canadian Prairie Production Expansion | National Steel Car's Ontario lines capture Saskatchewan pulse crop demand outpacing existing covered hopper availability. |
Methodological Framework
Multiple input streams — primary interviews with railcar procurement officers, plant engineers at elevator cooperatives, and aftermarket service directors; secondary validation through AAR fleet statistics, FRA safety filings, and Class I railroad capex disclosures; customs data on steel plate and aluminum billet trade flows — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Data-stream reconciliation across product type, material grade, capacity tier, and end-user ownership model anchored volume and value projections throughout the forecast period. CAGRs derived from historical replacement cycle analysis, regulatory mandate acceleration curves, and commodity-specific demand elasticity. Forecast inputs incorporated FRA compliance deadlines, EPA locomotive Tier 4 weight penalties, and elevator consolidation patterns along the Illinois River corridor.
Several conditions sit outside the modeled scope, including hypothetical coal demand recovery scenarios, unilateral tariff impositions on Canadian aluminum, and breakthrough composite material commercialization. Forecasts reflect documented assumptions regarding AAR interchange rule timelines and cross-border brake certification harmonization. A small set of named triggers warrants ongoing watch: Plate C dimensional clearance committee decisions, ductile iron foundry capacity expansion announcements, and Class I railroad electrification pilot outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market