
 Automotive Vacuumless Braking Market | 2026-2036
Automotive Vacuumless Braking Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Vacuumless Braking Market Outlook
China is rewriting competitive dynamics in automotive vacuumless braking through aggressive localization of electromechanical brake motor and controller production. Robert Bosch GmbH leverages its integrated sensor-to-actuator portfolio to anchor premium OEM supply agreements across European and Asian markets. Continental AG competes through deep backward integration into brake control software and hardware, while ZF Friedrichshafen AG extends its chassis systems dominance into vacuumless architectures for commercial vehicle electrification.
Automotive vacuumless braking encompasses electromechanically actuated deceleration systems that generate clamping force through motor-driven ball-screw or belt-drive mechanisms rather than engine vacuum or hydraulic boost, typically achieving response latencies below 120 milliseconds and supporting regenerative energy recovery. The technology serves the primary industrial purpose of enabling decoupled brake pedals, software-defined braking feel, and full integration with autonomous emergency braking protocols. Electromechanical Systems leads product type value generation due to higher per-unit content and patent density, while Electric Vehicles application demand expands fastest as native EV platforms abandon vacuum-dependent legacy architectures. OEM end users concentrate procurement leverage, though Fleet Operators represent an emerging segment as logistics electrification mandates accelerate replacement cycles.
NHTSA in the United States and UNECE in Europe shape product standards through advanced emergency braking and pedestrian protection mandates that effectively require vacuumless actuation precision. China's MIIT enforces GB standards for new energy vehicle braking performance that favor domestic electromechanical system adoption. Japan's METI coordinates industry consortia on brake-by-wire interoperability standards. Stakeholders must monitor regulatory divergence between performance-based mandates and technology-neutral safety frameworks to calibrate platform development bets and supplier qualification timelines.
Market Dynamics
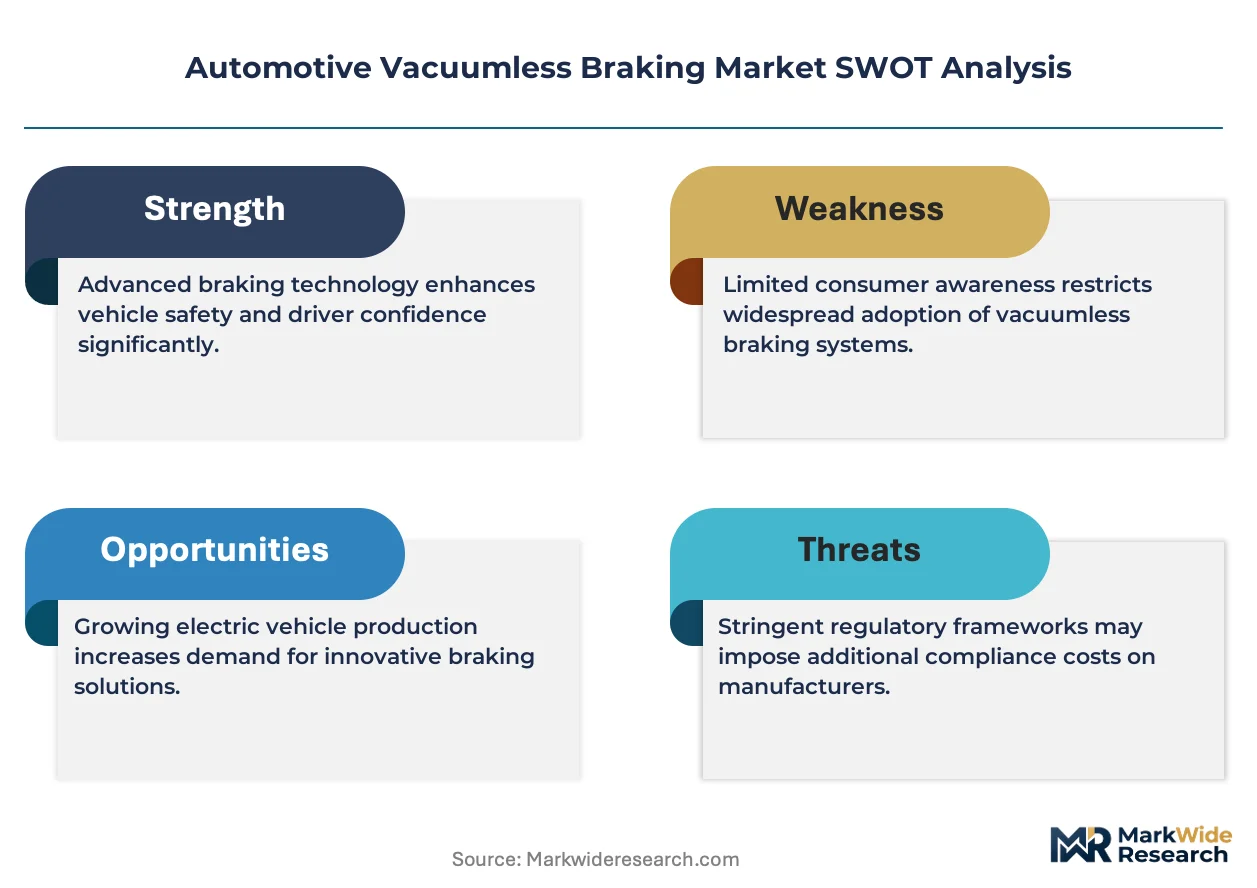
Brake-by-wire architectures are forcing a fundamental restructuring of supplier-OEM relationships as electromechanical actuation replaces vacuum-boosted hydraulic systems across electric vehicle platforms.
Growth Catalysts
- UNECE advanced emergency braking mandates:European regulatory deadlines for pedestrian protection and autonomous braking are compelling OEMs to adopt vacuumless systems with sub-120 millisecond response latencies.
- Regenerative energy recovery integration:Native EV platforms from Tesla, BYD, and Volkswagen Group require decoupled brake pedals to maximize energy recuperation efficiency.
- China's MIIT GB standards:Domestic new energy vehicle braking performance regulations favor electromechanical system adoption and are accelerating localized motor and controller production.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese supply chains compress margins for electromechanical brake motor manufacturers.
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for brake-by-wire systems extends development cycles by 18-24 months versus conventional hydraulic brakes.
- Hydraulic brake legacy infrastructure:Established service networks and technician training for vacuum-boosted systems create switching friction in aftermarket channels.
Strategic Opportunities
- Commercial vehicle electrification:Fleet operators in logistics and urban transit represent an emerging procurement segment as electrification mandates accelerate replacement cycles.
- Software-defined braking feel:Convergence of electromechanical actuation with AI-driven pedal mapping enables premium tier differentiation through customizable deceleration profiles.
- India's PLI scheme for automotive components:Production-linked incentives for advanced automotive systems are attracting electromechanical brake assembly investments to serve domestic and export markets.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of mechanical brake design, motor control, and embedded software requires talent pools concentrated in Germany, Japan, and China's Tier 1 supplier clusters.
- Legacy system integration complexity:Retrofitting brake-by-wire architectures into platforms originally designed for vacuum dependency demands extensive chassis control recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Vacuumless Braking Market |
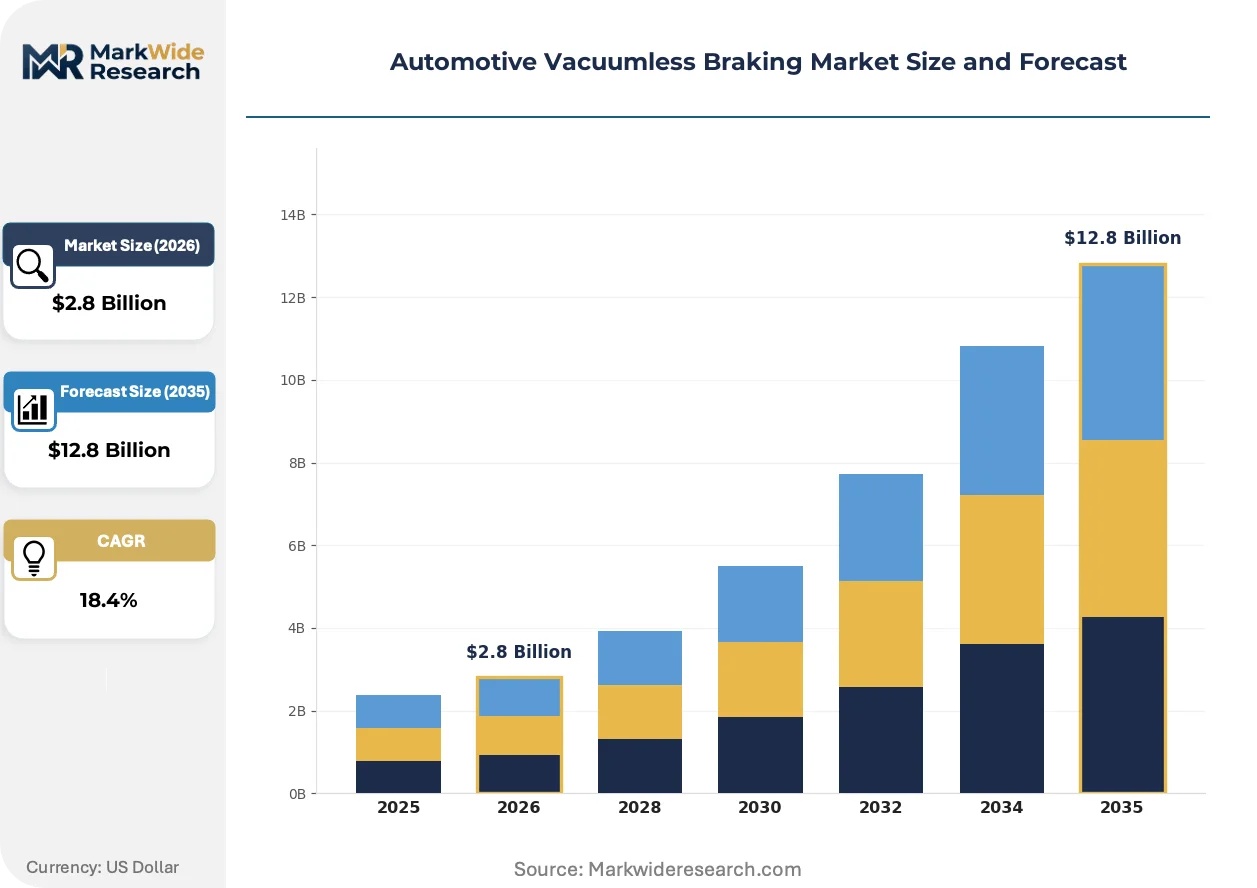
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Systems, Hydraulic Systems, Pneumatic Systems, Electropneumatic Systems End User: OEMs, Aftermarket, Fleet Operators, Vehicle Assemblers Technology: ABS, EBD, ESC, TCS Application: Passenger Vehicles, Commercial Vehicles, Heavy Duty Vehicles, Electric Vehicles |
| Companies Covered | Continental AG, Robert Bosch GmbH, Brembo S.p.A., Aptiv PLC, ZF Friedrichshafen AG, Hitachi Automotive Systems, LSP Innovative Automotive Systems GmbH, Advics Co. Ltd., Knorr-Bremse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Vacuumless Braking Market Strategic Shifts
Three intersecting developments are compressing development timelines and redrawing competitive boundaries in foundation brake systems.
Ball-screw electromechanical actuators are replacing belt-drive mechanisms in premium brake-by-wire modules due to superior force density and backlash control. European and Asian OEMs are specifying these actuators for 2026 platform launches. The technology is rendering obsolete pneumatic backup systems that previously provided fail-safe redundancy in vacuumless architectures.
NHTSA's pedestrian automatic emergency braking mandate is tightening response latency requirements for light vehicles in the United States. The rulemaking effectively disqualifies vacuum-dependent boosters from compliance pathways. Premium EV segments are responding by accelerating supplier qualification of integrated sensor-to-actuator brake modules.
Fleet procurement departments are consolidating brake system sourcing decisions at the holding-company level rather than delegating to individual OEM brand teams. This concentration is compressing supplier negotiation cycles and favoring integrated chassis system providers with multi-vehicle platform coverage. The pattern is most visible in Germany's commercial vehicle sector where logistics electrification mandates are synchronizing replacement timelines.
Automotive Vacuumless Braking Market Segmentation
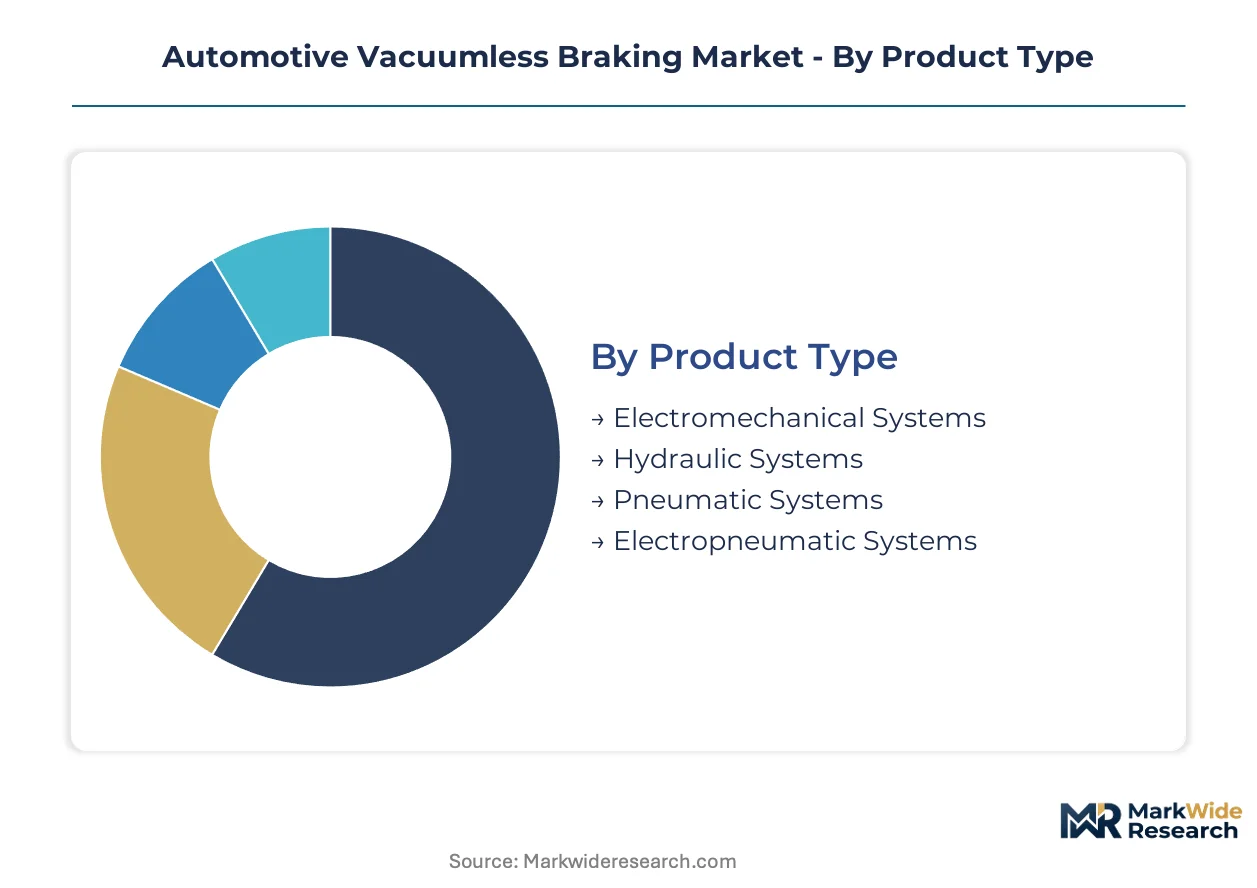
Segmentation in automotive vacuumless braking reveals how technology choices cascade through procurement hierarchies and regulatory compliance pathways. Each dimension exposes different margin structures and supplier qualification barriers.
Product Type:
Cost tier positioning determines motor specification, controller complexity, and patent licensing burden across foundation brake architectures.
- Electromechanical Systems:Motor-driven ball-screw or belt-drive mechanisms generate clamping force without vacuum dependency, achieving sub-120 millisecond response latencies. Demand concentrates in Germany and China's premium EV platforms where regenerative energy recovery integration is mandatory.
- Hydraulic Systems:Electro-hydraulic actuation retains fluid-based force transmission while eliminating vacuum boosters through electric pump assistance. Japanese OEMs favor this architecture for hybrid platforms requiring brake feel continuity with legacy vehicle lines.
- Pneumatic Systems:Compressed air actuation persists in heavy commercial vehicle retrofits where service infrastructure investment constrains electrification speed.
- Electropneumatic Systems:Hybrid architectures bridge pneumatic reliability with electronic control precision for municipal bus and refuse truck applications.
Electromechanical Systems commands the established base. The steepest expansion runs through Electropneumatic Systems.
End User:
Customer type dictates contract structure, volume predictability, and software update responsibility in brake-by-wire deployments.
- OEMs:Integrated vehicle manufacturers specify foundation brake modules at platform conception, locking in multi-year supply agreements with ASIL-D certification requirements. Procurement leverage concentrates in Volkswagen Group, Tesla, and BYD platform teams.
- Fleet Operators:Logistics holding companies are consolidating brake system sourcing decisions across multiple OEM brands, compressing supplier negotiation cycles and favoring integrated chassis providers.
- Aftermarket:Independent service channels face technician training gaps and diagnostic equipment costs for electromechanical brake maintenance.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-integrated brake modules to accelerate time-to-market.
OEMs anchor current procurement volume. Fleet Operators are gaining share fastest as electrification mandates synchronize replacement timelines.
Technology:
Maturity level of electronic control functions determines software validation burden and sensor fusion complexity in vacuumless architectures.
- ABS:Anti-lock braking functions provide the foundational control layer for wheel slip modulation, now standard across all vehicle categories.
- EBD:Electronic brakeforce distribution optimizes deceleration across axles without mechanical proportioning valves, enabling faster calibration cycles.
- ESC:Electronic stability control integrates yaw rate management with brake actuation, requiring the highest functional safety grades.
- TCS:Traction control systems leverage brake intervention for slip mitigation, particularly critical for rear-wheel-drive EV torque characteristics.
ESC absorbs the greatest engineering resource. EBD is climbing the fastest as a cost-effective upgrade path for emerging market platforms.
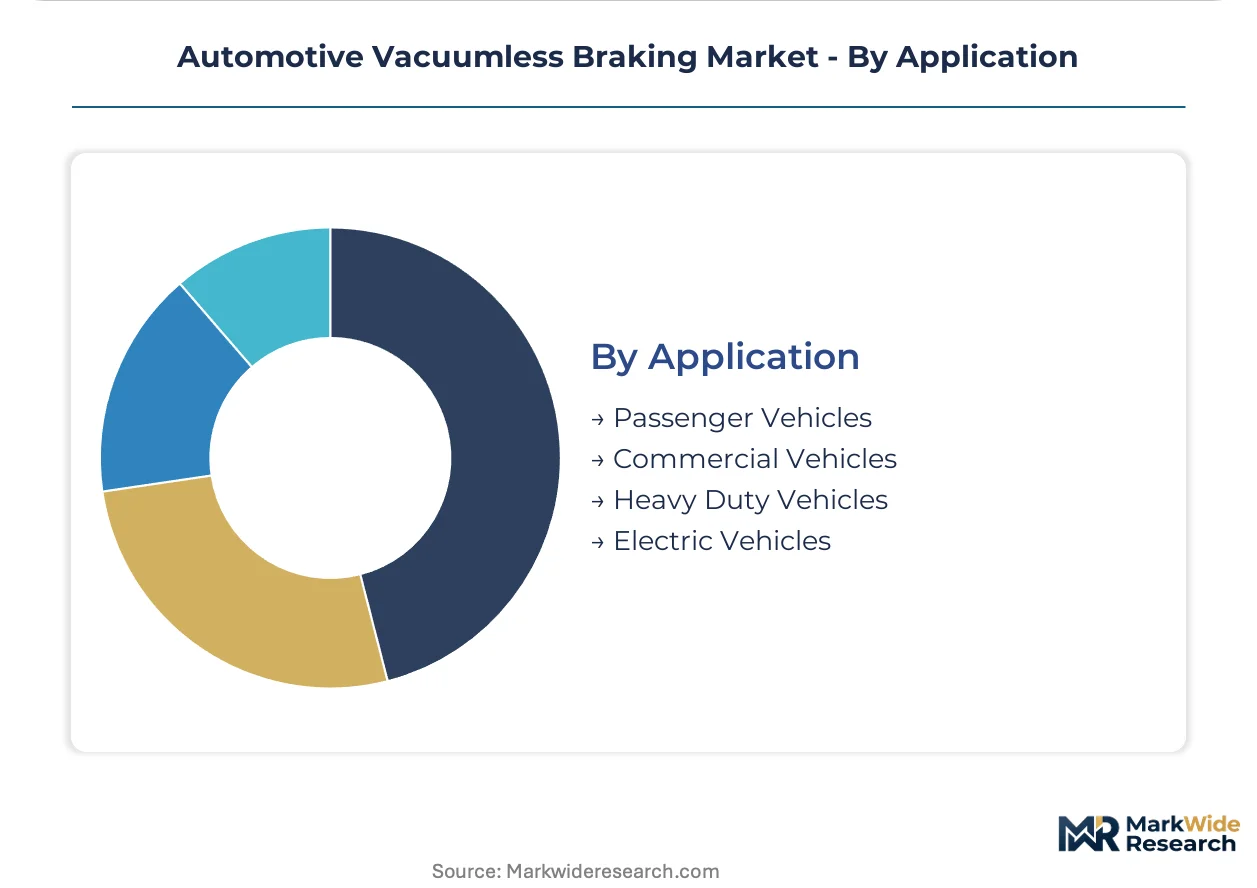
Application:
Vehicle mass and duty cycle dictate actuator sizing, thermal management requirements, and regenerative blending sophistication.
- Electric Vehicles:Native EV platforms from Tesla, BYD, and Volkswagen Group require fully decoupled brake pedals to maximize energy recuperation efficiency and enable one-pedal driving modes.
- Commercial Vehicles:Urban delivery vans and transit buses face payload-dependent braking energy challenges that electromechanical actuation addresses through predictive thermal modeling.
- Passenger Vehicles:Light duty applications prioritize pedal feel customization and packaging compactness for cabin space optimization.
- Heavy Duty Vehicles:Long-haul trucks and construction equipment demand redundant actuation channels and extended service intervals under severe duty cycles.
Passenger Vehicles holds the volume base. Electric Vehicles is expanding most quickly as platform electrification eliminates vacuum-dependent legacy architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromechanical brake motor and controller production clusters in Germany, Japan, and China, with each geography driving distinct regulatory and procurement pathways for vacuumless architectures.
Germany
Volkswagen Group and BMW platform teams specify integrated brake-by-wire modules for 2026 native EV launches. KBA enforces UNECE advanced emergency braking compliance timelines that favor sub-120 millisecond response systems. Stuttgart and Wolfsburg host Tier 1 supplier development centers where ball-screw actuator qualification is accelerating.
China
BYD and Tesla Shanghai factories consume electromechanical brake systems at scale for one-pedal driving configurations. MIIT GB standards for new energy vehicle braking performance mandate decoupled pedal architectures that eliminate vacuum dependency. Suzhou and Shenzhen production corridors are localizing motor winding and controller PCB assembly for domestic supply security.
United States
Tesla's Austin and Fremont operations anchor North American demand for regenerative-integrated brake systems. NHTSA pedestrian automatic emergency braking mandates for light vehicles are disqualifying vacuum-boosted boosters from compliance pathways. Michigan's automotive engineering clusters are retooling for brake control software validation under ISO 26262 ASIL-D grades.
Japan
Toyota and Honda hybrid platforms favor electro-hydraulic architectures for brake feel continuity with legacy vehicle lines. METI coordinates industry consortia on brake-by-wire interoperability standards that shape supplier qualification protocols. Nagoya and Tokyo-Yokohama corridors concentrate mechatronics engineering talent for motor control and embedded software integration.
India
Maharashtra and Tamil Nadu vehicle assembly plants are sourcing pre-integrated brake modules for emerging domestic EV brands. PLI scheme production-linked incentives for advanced automotive components are attracting electromechanical brake investments. Pune and Chennai supplier parks are building controller calibration capabilities for export market qualification.
Automotive Vacuumless Braking Market Competitive Environment
Integrated chassis system providers and specialized electromechanical component suppliers split the market along software-hardware integration depth. Tier 1 automotive suppliers with captive brake control software development anchor premium OEM supply agreements. Three archetypes dominate: full-system integrators with sensor-to-actuator portfolios, electromechanical actuator specialists with motor-control expertise, and brake friction incumbents pivoting toward mechatronic modules. Competitive moves center on backward integration into rare earth magnet supply chains and strategic partnerships for AI-driven pedal mapping algorithms.
Among German-based full-system integrators, Continental AG and Robert Bosch GmbH occupy positions defined by integrated software-hardware development. ZF Friedrichshafen AG exemplifies the chassis systems archetype extending into commercial vehicle electrification. Brembo S.p.A. represents brake friction specialists transitioning toward electromechanical architectures through Italian engineering centers.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Brembo S.p.A. |
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Hitachi Automotive Systems |
| LSP Innovative Automotive Systems GmbH |
| Advics Co. Ltd. |
| Knorr-Bremse AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese electromechanical brake motor winding facilities is compressing supplier margins while accelerating price competition for controller PCB assemblies. This utilization imbalance feeds directly into procurement leverage for Volkswagen Group and BYD platform teams, which are consolidating supplier panels across German and Chinese production corridors.
Pricing Analysis
NHTSA pedestrian automatic emergency braking mandates dictate the pricing tier structure across the North American supplier base. Three-tier pricing stratification separates ASIL-D certified integrated modules from standard electromechanical actuators and economy electro-hydraulic systems. Price differentiation centers on functional safety certification grade and regenerative blending software sophistication. Cost compression in economy-tier electro-hydraulic systems is intensifying because Japanese OEMs are extending hybrid platform life cycles. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership procurement models, while premium EV platform teams prioritize response latency performance over unit cost.
Supply Chain Analysis
Export control restrictions on rare earth magnet processing technology limit neodymium and dysprosium flow transparency between Chinese separation facilities and German motor manufacturers. Supply concentrates in China for rare earth magnet production, Germany for ball-screw actuator machining, and Japan for high-precision motor winding equipment. Raw material dependencies center on neodymium-iron-boron magnets, silicon steel laminations, and automotive-grade controller semiconductors. Single-source vulnerability in Chinese rare earth magnet supply creates structural risk for European electromechanical brake assembly lines. Distribution runs through Tier 1 supplier direct-OEM contracts with limited aftermarket channel penetration due to diagnostic equipment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across German logistics holding companies is shifting procurement leverage toward multi-OEM brake system sourcing decisions, fragmenting incumbent supplier relationships.
For Market Incumbents: Harden ASIL-D certification moats through captive brake control software development centers in Stuttgart and Wolfsburg. Deepen backward integration into rare earth magnet supply chains to offset Chinese price volatility. Defend against emerging Indian electromechanical brake assemblers by accelerating platform standardization across Volkswagen Group and BMW 2026 native EV launches. For New Entrants and Emerging Players: Build out controller calibration capabilities in Pune and Chennai supplier parks to capture PLI scheme incentives for advanced automotive components. Target India's emerging domestic EV brands with pre-integrated brake modules that compress vehicle assembly timelines. Establish go-to-market partnerships with fleet operators seeking multi-OEM brake system standardization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical actuator specialists with multi-year OEM platform supply agreements and software update service contracts. Long-term viability rests on brake-by-wire interoperability standard adoption across European and Asian regulatory clusters. Prioritize acquisition targets with integrated sensor-to-actuator portfolios and established ASIL-D validation track records. Monitor METI brake-by-wire interoperability consortium outputs as an inflection indicator for supplier qualification protocol consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group and BMW are consolidating brake-by-wire module specifications across 2026 native EV architectures. |
| Backward Integration into Rare Earth Magnets | Robert Bosch GmbH and Continental AG are securing captive neodymium supply to stabilize electromechanical brake motor costs. |
| Software-Defined Vehicle Investment | Tesla and BYD are deploying AI-driven pedal mapping algorithms for customizable deceleration profiles in one-pedal driving modes. |
| Geographic Manufacturing Footprint | Suzhou and Shenzhen corridors are localizing controller PCB assembly to satisfy MIIT GB standards compliance requirements. |
| Charging Infrastructure Partnership | Urban transit fleet operators are synchronizing brake system replacement cycles with logistics electrification mandate timelines. |
Study Parameters
The analysis maps electromechanical brake systems, electro-hydraulic architectures, and electropneumatic hybrid modules, each validated through Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operator procurement heads. Primary interviews with brake control software developers and motor control specialists were cross-referenced against vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, and MIIT GB standard filings. Bottom-up segment sizing triangulated with top-down OEM platform content analysis.
Assumptions held fixed include UNECE advanced emergency braking mandate compliance timelines and Chinese rare earth magnet export license procedures, while EV platform electrification speed and fleet operator consolidation pace were varied across sensitivity scenarios. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from unit volume trajectories and average selling price evolution across the projection horizon. Industry-specific forecast inputs included brake-by-wire platform launch schedules and regenerative energy recovery efficiency curves.
Stress conditions across rare earth magnet price volatility, ASIL-D certification timeline extensions, and fleet operator bankruptcy rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate enforcement consistency and OEM platform electrification commitment levels. Material shifts in NHTSA pedestrian automatic emergency braking rulemaking stringency or Chinese dual carbon goals implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market