
 Locomotive Wiring Harness Market | 2026-2036
Locomotive Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Wiring Harness Market Foresight
India's dedicated freight corridor expansion is reshaping procurement patterns for heavy-gauge harness assemblies. Prysmian Group leverages its submarine cable expertise to transfer high-voltage insulation technology into rolling stock applications. TE Connectivity anchors North American rail electrification through its broad connector portfolio certified for MIL-spec vibration resistance. Nexans competes on European high-speed platforms with aluminum conductor harnesses that reduce weight without sacrificing ampacity.
A locomotive wiring harness is an integrated cable assembly engineered to transmit electrical power and control signals across traction systems, auxiliary equipment, and passenger amenities, typically rated for voltages spanning 24V DC control circuits to 25kV AC catenary feeds and manufactured through automated crimping, ultrasonic welding, and overmolding processes. Its primary purpose is to ensure electromagnetic compatibility, fire resistance, and mechanical durability under continuous vibration, temperature cycling, and moisture ingress in rail environments. High voltage harness segments dominate value pools as electrified traction architectures displace diesel-electric propulsion, while aluminum material adoption accelerates where weight reduction governs energy efficiency targets. Passenger locomotive applications sustain premium pricing through redundant safety architectures, whereas freight locomotive demand concentrates on repair-cycle cost minimization.
The Federal Railroad Administration mandates fire-smoke toxicity standards under 49 CFR part 238 that govern harness jacketing compounds for US passenger equipment. Europe's ECHA REACH restrictions on halogenated flame retardants and the EU F-Gas Regulation phase-down are forcing reformulation of wire insulation chemistries across Continental supply chains. China's GB/T standards for railway electrical equipment impose additional type-testing protocols on cross-border component suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment sourcing strategies and certification timelines.
Market Dynamics
Rail electrification mandates and REACH-driven material transitions are compressing supplier lead times while fragmenting certification requirements across procurement jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Halogen-free insulation compound mandates accelerate R&D investment in low-smoke zero-halogen formulations across Continental rolling stock supply chains.
- Freight corridor electrification:Dedicated freight corridors in India and Germany expand fleet renewal cycles, concentrating demand for high-voltage harness assemblies rated to 25kV AC.
- Aluminum conductor adoption:Weight-driven energy efficiency targets in high-speed passenger platforms displace copper in selected power distribution segments.
Market Restraints
- Specialized polymer supply concentration:Halogen-free jacketing compound production clusters in Germany's Ruhr industrial basin, creating single-source vulnerability for tier-2 harness assemblers.
- Copper-aluminum price volatility:Conductor material cost swings compress margin predictability for long-delivery harness contracts indexed to LME benchmarks.
- Cross-border certification friction:Divergent type-testing protocols between China's GB/T standards and US 49 CFR part 238 requirements extend product qualification timelines by 8-14 months.
Strategic Opportunities
- Sub-Saharan rail rehabilitation:Underpenetrated markets in Nigeria and Kenya present first-mover positioning for modular harness kits compatible with legacy BR and Chinese locomotive architectures.
- Digital twin integration:Convergence of harness design software with predictive maintenance platforms enables outcome-based service contracting for fleet operators.
- US IRA clean transit incentives:Federal tax credits for rail electrification infrastructure lower total cost of ownership barriers for municipal transit authorities modernizing diesel fleets.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for halogen-free, high-temperature insulation compounds concentrates among retiring specialists in European compound houses.
- Legacy system integration:Retrofit harness compatibility with 30-year-old locomotive control architectures demands custom engineering that erodes standardization economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Wiring Harness Market |
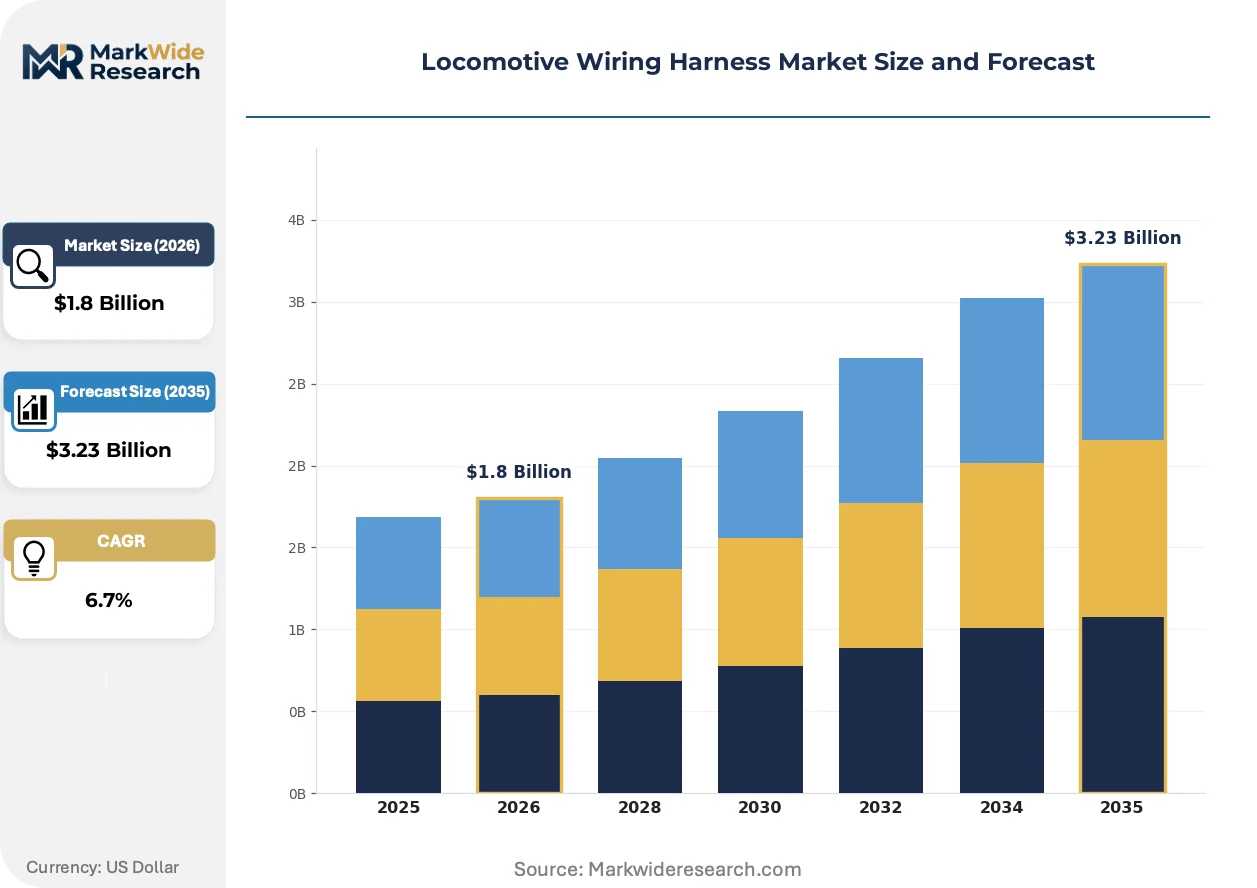
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage Harness, Low Voltage Harness, Engine Harness, Control Panel Harness Material: Copper, Aluminum, Thermoplastic, Polyvinyl Chloride Application: Passenger Locomotives, Freight Locomotives, High-Speed Trains, Diesel Electric Locomotives End User: Original Equipment Manufacturers, Maintenance Providers, Aftermarket Suppliers, Rail Operators |
| Companies Covered | Prysmian Group, Hitachi, TE Connectivity, LS Cable & System, Nexans, Leoni AG, Samvardhana Motherson, HUBER+SUHNER, Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Wiring Harness Market Shifts & Advancements
Material science breakthroughs and predictive maintenance architectures are redefining harness lifecycle economics while regulatory chemistry mandates force supply chain restructuring.
Silicone rubber insulation rated to 180°C continuous operation is rendering obsolete traditional EPDM and XLPE compounds in traction motor feeder applications. European high-speed operators specify these materials for reduced thermal derating and extended maintenance intervals. The shift compresses compound supplier margins on legacy product lines while elevating certification barriers for new market entrants.
Europe's ECHA REACH restrictions on halogenated flame retardants and the concurrent EU F-Gas Regulation phase-down are forcing reformulation of wire insulation chemistries across Continental supply chains. Compound houses must validate alternative phosphorus-nitrogen systems without sacrificing smoke density performance. High-speed passenger platforms face the steepest compliance cost escalation due to redundant safety architecture requirements.
Condition-based maintenance contracts now specify harness impedance monitoring as a standard deliverable. Fleet operators in Germany and Japan unbundle cable health diagnostics from traditional preventive maintenance schedules. This behavioral pivot concentrates purchasing influence among systems integrators capable of embedding fiber-optic sensing within power distribution harnesses.
Locomotive Wiring Harness Market Segmentation
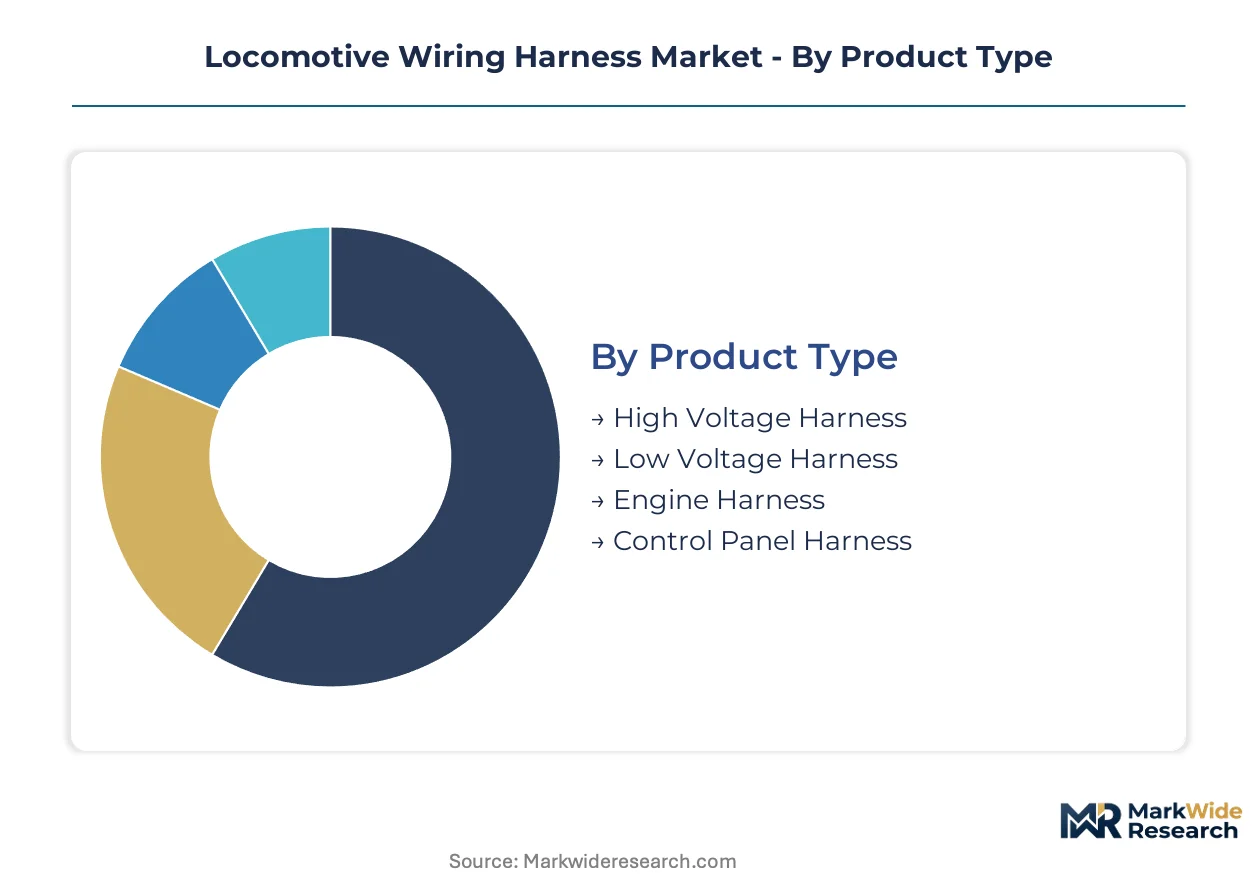
Segmentation in locomotive wiring harness procurement reflects divergent technical specifications across traction voltages, material science trade-offs, and lifecycle cost priorities that separate OEM fleet builds from aftermarket repair cycles.
Product Type:
Use-case spectrum spans traction power distribution through passenger amenity circuits, with voltage rating and fire-resistance specifications governing procurement decisions.
- High Voltage Harness:Engineered for 25kV AC catenary feeds and 3kV DC traction systems using silicone rubber insulation rated to 180°C continuous operation. Demand concentrates in Germany's Ruhr corridor where Siemens and Alstom electrification programs require redundant feeder architectures. ECHA REACH halogen-free mandates accelerate compound reformulation costs for European suppliers.
- Low Voltage Harness:24V-110V control and signal transmission assemblies using cross-linked polyethylene insulation. India's dedicated freight corridor expansion drives procurement volume for auxiliary circuit standardization across WAG-12 and WAP-7 locomotive platforms. BIS certification timelines extend supplier qualification cycles.
- Engine Harness:Diesel-electric power unit interconnects surviving in retrofit markets.
- Control Panel Harness:Cab instrumentation and human-machine interface cabling with MIL-spec vibration resistance.
The dominant share belongs to High Voltage Harness, while Low Voltage Harness is closing the gap fastest.
Material:
Cost tier separation reflects conductor metal pricing volatility against polymer chemistry compliance burdens.
- Copper:Traditional conductivity standard for high-ampacity traction feeders with established crimping and ultrasonic welding processes. Nexans and Prysmian maintain European supply dominance despite LME price swings. REACH-driven halogen-free jacketing requirements now exceed base metal costs in total material spend.
- Aluminum:40% weight reduction enables energy efficiency gains in high-speed passenger platforms. TE Connectivity anchors North American rail electrification with aluminum conductor harnesses certified for 200km/h+ operations. GB/T type-testing protocols impose additional qualification barriers for Chinese market entry.
- Thermoplastic:Halogen-free insulation compounds displacing legacy PVC in fire-critical applications.
- Polyvinyl Chloride:Cost-minimized jacketing surviving in freight locomotive repair cycles outside EU jurisdiction.
Copper retains volume leadership, though Aluminum is expanding most quickly in premium passenger segments.
Application:
Customer type divergence separates safety-redundant passenger architectures from repair-cycle cost minimization in freight operations.
- Passenger Locomotives:Dual-channel harness redundancy with fiber-optic health monitoring embedded for condition-based maintenance. Japan's JR East and Germany's DB specify impedance diagnostics as standard deliverables. FRA 49 CFR part 238 fire-smoke toxicity standards govern US procurement.
- Freight Locomotives:Single-channel power distribution prioritizing mean-time-between-failure metrics over redundant safety. Indian Railways' WAG-12 fleet renewal concentrates demand for repairable harness architectures with field-replaceable connector modules. CEA electrification mandates accelerate diesel-to-electric conversion timelines.
- High-Speed Trains:300km/h+ platforms demanding aerodynamic cable routing and electromagnetic compatibility shielding.
- Diesel Electric Locomotives:Declining OEM demand with aftermarket repair concentration in Sub-Saharan Africa and Southeast Asia.
Freight Locomotives command the largest installed base, while Passenger Locomotives generate the steepest expansion trajectory.
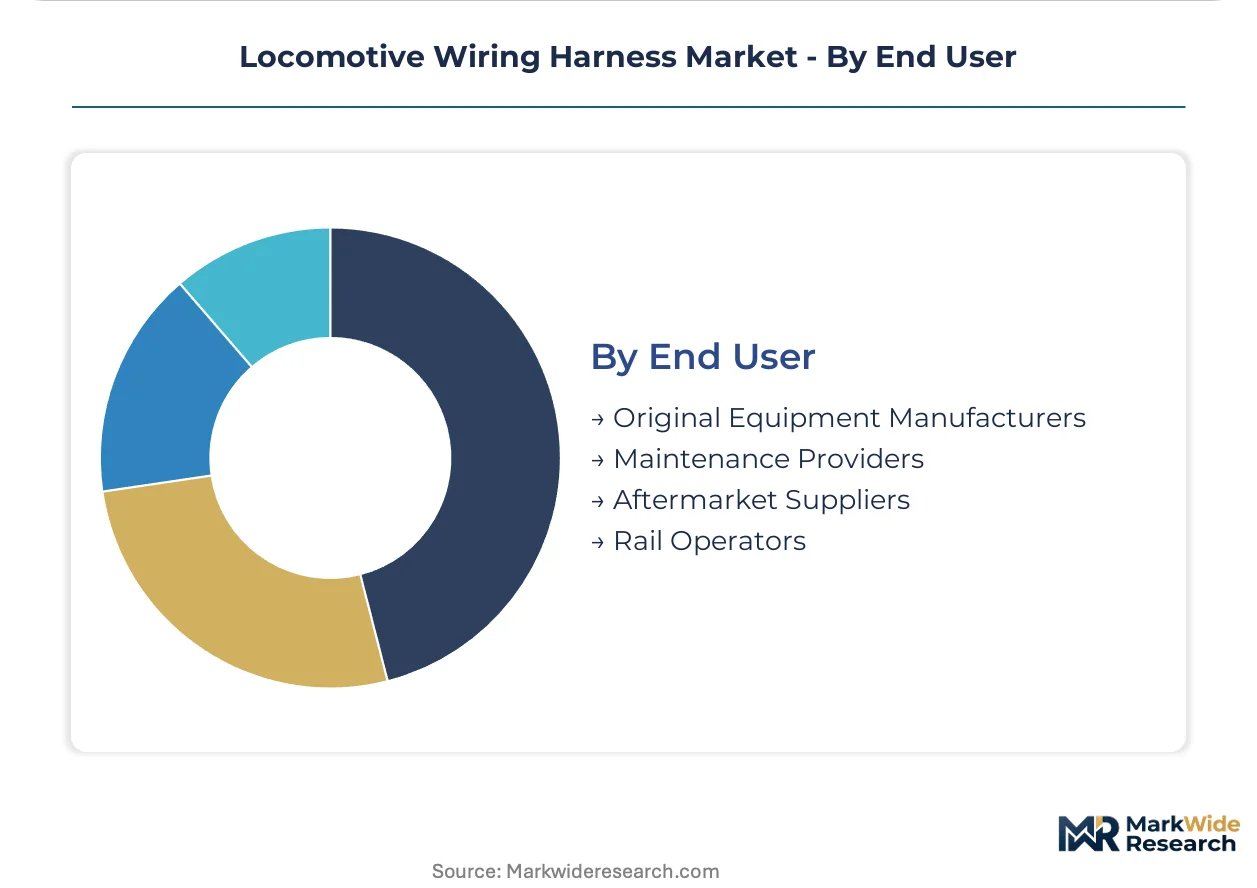
End User:
Supply concentration varies across integrated OEM partnerships versus fragmented aftermarket channels.
- Original Equipment Manufacturers:Long-term supply agreements with compound houses for certified halogen-free formulations. Siemens and Alstom source harness assemblies through captive suppliers in Germany's Ruhr industrial cluster. F-Gas Regulation compliance costs concentrate purchasing influence among vertically integrated systems integrators.
- Maintenance Providers:Condition-based service contracts unbundling cable health diagnostics from traditional preventive schedules. Fleet operators in Germany and Japan now specify harness impedance monitoring as standard deliverables. Digital twin integration enables outcome-based pricing for cable lifecycle management.
- Aftermarket Suppliers:Modular repair kits for legacy BR and Chinese locomotive architectures in underpenetrated markets.
- Rail Operators:Direct procurement for fleet modernization programs leveraging US IRA clean transit incentives.
OEMs dominate contract value, though Maintenance Providers are gaining share fastest through predictive service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer production for halogen-free insulation concentrates in Germany's Ruhr industrial basin, creating supply chain leverage that shapes procurement economics across electrified rail corridors worldwide. This geographic clustering forces tier-2 harness assemblers to navigate single-source vulnerabilities while regulatory divergence between jurisdictions fragments certification timelines.
United States
Municipal transit authorities leverage IRA clean transit incentives to modernize diesel fleets, accelerating demand for 25kV AC catenary-rated assemblies. The Federal Railroad Administration enforces 49 CFR part 238 fire-smoke toxicity standards that govern harness jacketing compounds for passenger equipment. TE Connectivity anchors North American supply through its MIL-spec certified connector portfolio manufactured across Midwest industrial corridors.
Germany
Siemens and Alstom electrification programs in the Ruhr corridor require redundant high-voltage feeder architectures rated for continuous 180°C operation. ECHA REACH restrictions on halogenated flame retardants and the EU F-Gas Regulation phase-down force compound reformulation across Continental supply chains. Nexans competes on high-speed platforms with aluminum conductor harnesses that reduce weight without sacrificing ampacity.
India
Dedicated freight corridor expansion drives procurement volume for WAG-12 and WAP-7 locomotive auxiliary circuit standardization. The Central Electricity Authority electrification mandates accelerate diesel-to-electric conversion timelines across Indian Railways' fleet renewal cycles. Samvardhana Motherson maintains integrated supply partnerships for repairable harness architectures with field-replaceable connector modules.
China
GB/T standards for railway electrical equipment impose additional type-testing protocols on cross-border component suppliers seeking market entry. High-speed rail operators specify aerodynamic cable routing and electromagnetic compatibility shielding for 300km/h+ platforms. Prysmian Group transfers submarine cable high-voltage insulation expertise into rolling stock applications through technology licensing arrangements.
Japan
JR East specifies impedance diagnostics and fiber-optic health monitoring as standard deliverables for condition-based maintenance contracts. METI industrial standards govern silicone rubber insulation adoption in traction motor feeder applications rated for extended maintenance intervals. Furukawa Electric occupies a position within the premium-tier supplier segment serving redundant safety architecture requirements.
Locomotive Wiring Harness Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified insulation compounds and precision connectors. The vendor base stratifies across three tiers: vertically integrated OEM captives in Germany's Ruhr cluster, independent harness assemblers serving aftermarket repair cycles, and compound houses with formulation expertise for halogen-free high-temperature materials. Consolidation pressure concentrates among mid-scale fabricators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into polymer formulation capacity and strategic partnerships for digital twin-enabled predictive maintenance platforms.
Among European cable and connectivity specialists, Prysmian Group, Nexans, and Leoni AG exemplify archetypes spanning submarine-to-rail technology transfer, aluminum conductor lightweighting, and integrated OEM supply partnerships respectively. TE Connectivity represents the North American systems integrator position with broad certification coverage for vibration-resistant interconnects. LS Cable & System and Furukawa Electric anchor the Asia-Pacific supplier tier, with the former occupying a scale-driven position in Korean industrial markets and the latter sitting within Japanese precision manufacturing networks. Hitachi and HUBER+SUHNER occupy specialized positions spanning rolling stock electrification and RF connectivity for signaling applications.
| Leading Market Players |
|---|
| Prysmian Group |
| Hitachi |
| TE Connectivity |
| LS Cable & System |
| Nexans |
| Leoni AG |
| Samvardhana Motherson |
| HUBER+SUHNER |
| Furukawa Electric |
| Others |
Supply & Pricing Matrix
Undercapacity in Germany's Ruhr polymer compounding basin is forcing tier-2 harness assemblers to accept extended qualification timelines and premium pricing for halogen-free insulation formulations. This utilization squeeze transmits directly into contract structures, with long-delivery harness agreements now indexing raw material exposure to LME copper and aluminum benchmarks while OEM captives lock in volume commitments through multi-year offtake arrangements.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across Continental rolling stock supply chains, separating REACH-certified halogen-free formulations from legacy PVC-jacketed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales service bundling. Cost compression in standard-tier harness assemblies is intensifying because aluminum conductor adoption displaces copper in weight-sensitive applications. Freight locomotive operators exhibit highest price sensitivity due to repair-cycle cost minimization priorities, whereas passenger rail authorities accept premium positioning for redundant safety architectures with embedded diagnostics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now characterize procurement relationships between Ruhr-based compound houses and tier-2 harness assemblers facing working capital constraints. Geographic supply concentration centers on Germany, China, and India for insulation compounds, precision connectors, and conductor materials respectively. Raw material dependencies draw from silicone rubber feedstocks, high-purity copper cathode, and phosphorus-nitrogen flame retardant systems. Single-source vulnerability in halogen-free polymer formulation creates structural risk for non-integrated suppliers. Distribution runs through captive OEM supply partnerships in Germany, authorized distributor networks in North America, and direct procurement channels for Indian Railways fleet modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail electrification investment cycles are recovering from pandemic-depressed fleet renewal schedules, with India's dedicated freight corridor expansion and US IRA clean transit incentives providing cyclical momentum through the analysis window.
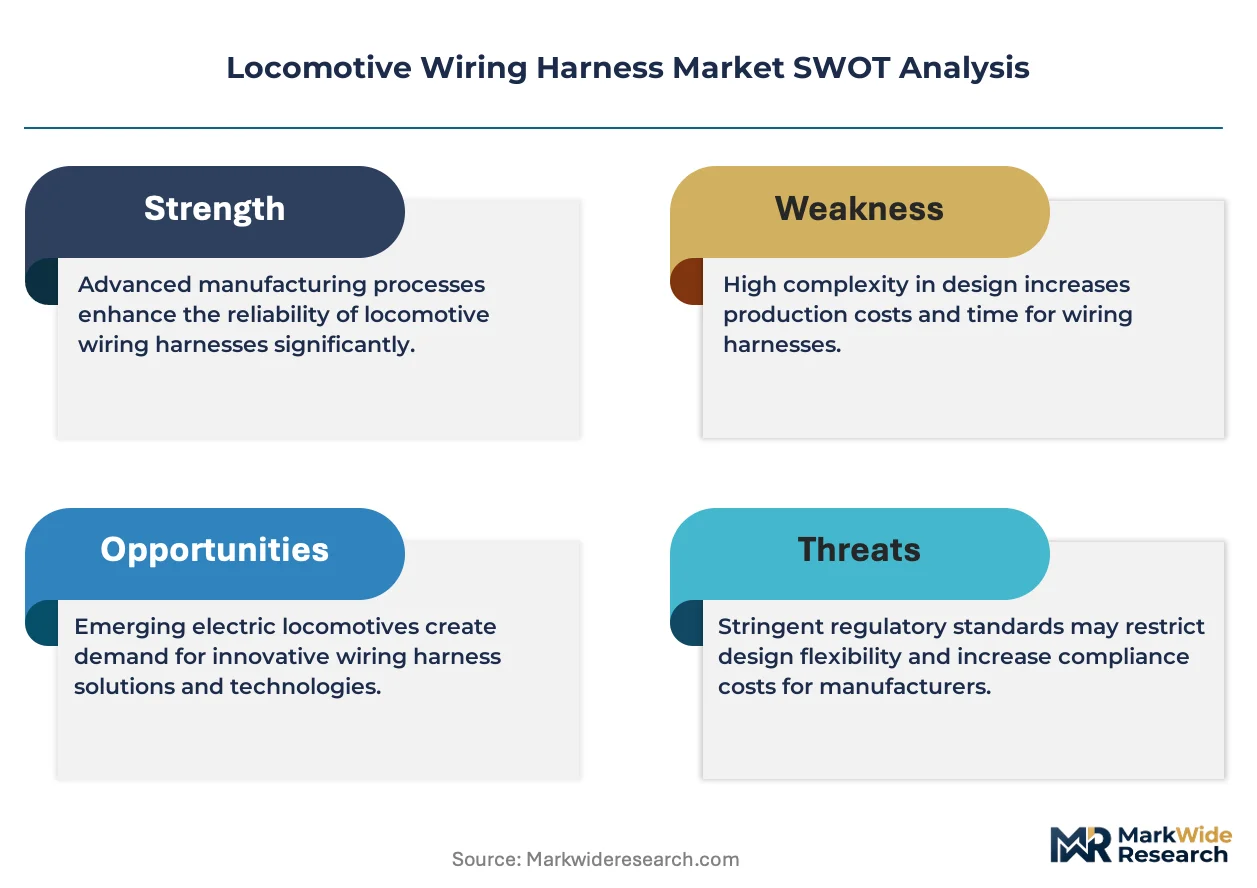
For Market Incumbents: Insulate formulation capabilities through backward integration into polymer compounding capacity or exclusive supply agreements with Ruhr-based compound houses facing chemist retirement waves. Secure certification dual-track investments for both ECHA REACH compliance and China's GB/T type-testing protocols to preempt cross-border qualification friction. Channel control over maintenance provider networks represents the critical defensive lever against systems integrators unbundling cable health diagnostics. For New Entrants and Emerging Players: Sub-Saharan rail rehabilitation markets in Nigeria and Kenya represent the most penetrable entry point for modular harness kits compatible with legacy BR and Chinese locomotive architectures. Aluminum conductor harnesses for 200km/h+ passenger platforms in Southeast Asia offer secondary white-space positioning where weight-driven energy efficiency targets outpace incumbent response capacity. Licensing arrangements with submarine cable specialists for high-voltage insulation technology transfer provide the most viable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across halogen-free compound formulation capacity as REACH compliance costs escalate and equipment retrofit requirements deepen. Acquisition targets should prioritize mid-scale European harness assemblers with captive polymer relationships and pending GB/T certification progress for Chinese market optionality. The signal to monitor is aluminum conductor adoption rates in high-speed platforms, which would indicate sustained margin expansion for lightweighting specialists versus copper-dependent incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH compliance cost escalation favors in-house formulation control over outsourced supply. |
| Dual Certification Investment (REACH/GB/T) | Parallel qualification for European and Chinese protocols compresses market entry timelines. |
| Fiber-Optic Health Monitoring Embedding | JR East and DB maintenance specifications concentrate purchasing influence among systems integrators. |
| Aluminum Conductor Platform Expansion | TE Connectivity's North American certification provides template for 200km/h+ passenger applications. |
| Modular Repair Kit Localization | Legacy BR and Chinese locomotive compatibility opens underpenetrated Sub-Saharan aftermarket channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM procurement disclosures. Primary interviews engaged rolling stock procurement directors, polymer compound house technical leads, and maintenance provider operations managers across Germany, India, and North America. Secondary validation drew from ECHA REACH substance registrations, US FRA safety bulletins, Indian Railways tender documentation, and SEC filings from listed cable manufacturers. Bottom-up segment sizing triangulates against top-down electrification investment forecasts from national rail authorities.
Forecast inputs incorporate traction voltage migration patterns, aluminum substitution elasticity in high-speed platforms, and regulatory chemistry mandate implementation schedules. Segmentation modeling spans product type, conductor material, locomotive application, and end-user channel across the projection horizon. CAGRs derive from installed base renewal cycles, fleet electrification timelines, and compound reformulation cost pass-through assumptions. Industry-specific inputs include silicone rubber insulation adoption curves and condition-based maintenance contract penetration rates.
Practitioners should monitor LME copper-aluminum price spreads, ECHA SVHC candidate list expansions, and Indian CEA electrification mandate acceleration for early signals of forecast deviation. Assumptions reflect current regulatory trajectories and announced fleet investment programs. Macroeconomic contraction in freight rail volumes, unilateral regulatory delay, or breakthrough solid-state conductor technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Human Interface System Market