
 Railway Automated Inspection Equipment Market | 2026-2036
Railway Automated Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Automated Inspection Equipment Market Analysis
Germany's industrial corridor is narrowing the gap between legacy rail maintenance practices and fully automated inspection regimes. Siemens leverages its embedded signaling expertise to dominate European track inspection vehicle deployments. Alstom competes through specialized bridge inspection drone platforms tailored to alpine infrastructure networks. NDT Global anchors transatlantic ultrasonic testing demand with proprietary rail flaw detection algorithms refined across North American Class I railroads.
Railway Automated Inspection Equipment comprises sensor-integrated platforms that detect rail defects, track geometry deviations, and structural fatigue through non-destructive testing protocols operating at speeds up to 120 km/h with millimeter-scale resolution. These systems serve the primary commercial purpose of preventing derailments and service interruptions while extending asset life cycles through predictive intervention schedules. Track Inspection Vehicles command the largest installed base among product categories, though Bridge Inspection Drones represent the fastest-expanding margin pool as viaduct and tunnel inventories age across OECD networks. Machine Vision technology leads technology adoption by deployment volume, while Acoustic Emission systems capture premium pricing in high-speed rail applications where micro-crack detection thresholds are most stringent.
The Federal Railroad Administration enforces mandatory inspection intervals that directly determine equipment replacement cycles and technology upgrade timelines across US freight and passenger networks. Ecodesign requirements under the EU Green Deal and F-Gas Regulation constrain refrigerant-based infrared sensor configurations, redirecting R&D investment toward solid-state thermal imaging alternatives. China's GB standards and NMPA-equivalent rail safety certifications shape export eligibility for European and North American equipment vendors. Stakeholders must monitor how divergent national certification timelines affect platform standardization strategies and service interoperability across cross-border corridors.
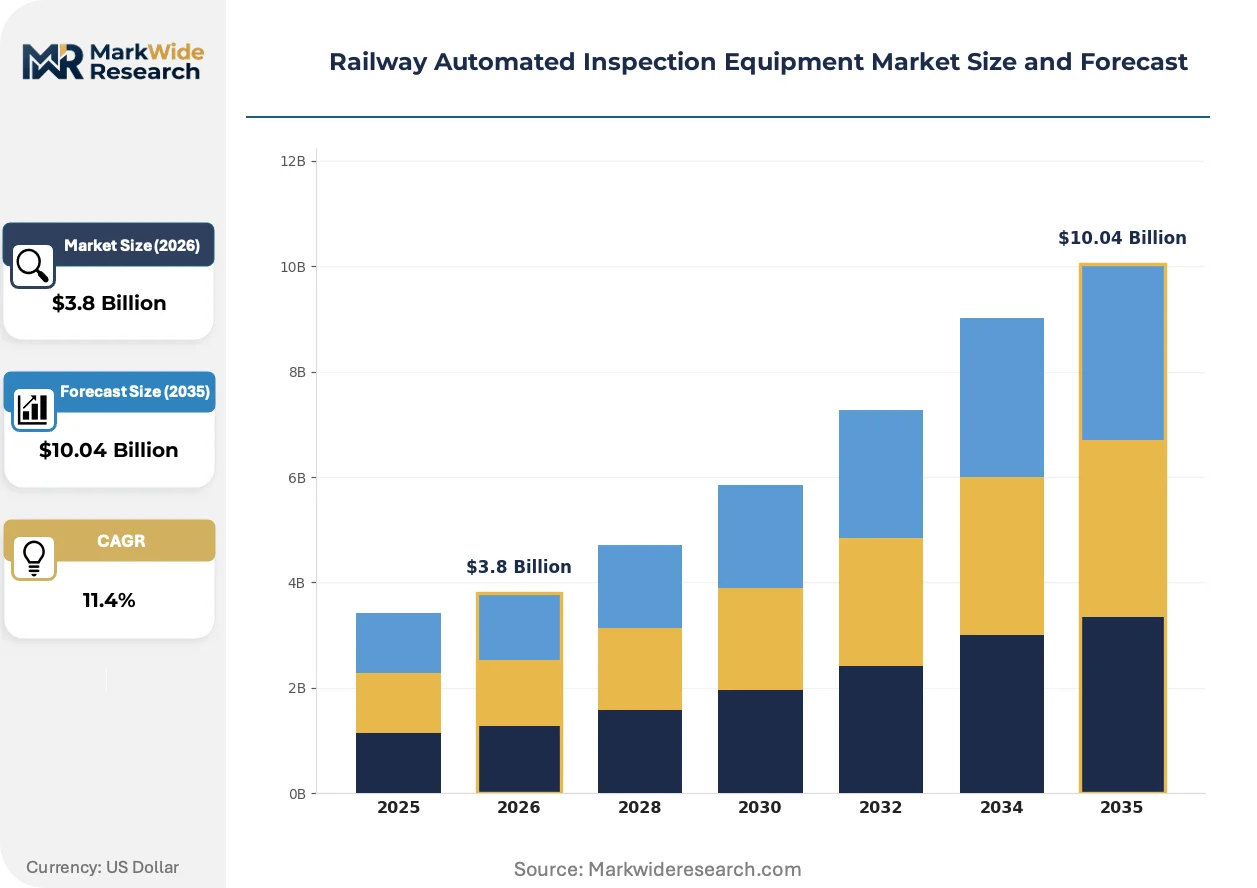
Market Dynamics
Freight rail operators face compressed inspection cycles as FRA-mandated safety intervals tighten, forcing capital redeployment from manual crews toward autonomous sensor platforms that operate at track speed without service interruption.
Growth Catalysts
- FRA Safety Mandates:The Federal Railroad Administration enforces mandatory inspection intervals that directly accelerate replacement of legacy manual testing protocols across US Class I networks.
- Machine Vision:Computer vision algorithms with millimeter-scale defect resolution are displacing human visual inspection across European high-speed corridors.
- Freight Rail Concentration:North American bulk commodity haulers concentrate procurement of automated track monitoring systems to minimize unplanned downtime on transcontinental routes.
Market Restraints
- Solid-State Sensor Costs:Ecodesign requirements under the EU F-Gas Regulation constrain refrigerant-based infrared configurations, elevating R&D expenditure for thermal imaging alternatives.
- Certification Fragmentation:Divergent national approval timelines across China's GB standards, US FRA protocols, and EU CE marking create platform standardization friction for cross-border equipment vendors.
- Ultrasonic Fleet Obsolescence:Legacy rail flaw detection vehicles face accelerated depreciation as inspection speed requirements outpace analog system capabilities.
Strategic Opportunities
- Alpine Infrastructure Networks:Bridge inspection drones address aging viaduct inventories across Swiss and Austrian rail corridors where manual access remains hazardous.
- Acoustic Emission Convergence:Micro-crack detection systems combining acoustic sensors with machine learning algorithms capture premium positioning in high-speed rail applications.
- India's Dedicated Freight Corridors:The country's PLI scheme for rail infrastructure creates localized assembly incentives for automated inspection equipment manufacturers.
Industry Challenges
- Embedded Signaling Integration:Track inspection vehicles must reconcile proprietary communication protocols with legacy signaling infrastructure across heterogeneous national networks.
- NDT Specialist Scarcity:Rail flaw interpretation expertise concentrates among aging ultrasonic technicians, creating knowledge transfer bottlenecks as automated systems require human-in-the-loop validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Automated Inspection Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Track Inspection Vehicles, Bridge Inspection Drones, Ultrasonic Testing Equipment, Laser Scanners Technology: Machine Vision, Infrared Sensors, RFID, Acoustic Emission Application: Preventive Maintenance, Safety Monitoring, Quality Assurance, Asset Management End User: Railway Operators, Infrastructure Authorities, Maintenance Contractors, Inspection Services |
| Companies Covered | Trimble Industries, ANYbotics, ROSEN Group, Bombardier, GE Transportation, Siemens, Alstom, SIASUN, NDT Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Automated Inspection Equipment Market Emerging Trajectories
Inspection technology is compressing the trade-off between detection resolution and operational speed, enabling continuous monitoring regimes that were technically infeasible under manual protocols.
Machine vision systems with sub-millimeter rail surface defect detection are migrating from periodic wayside installations to continuous onboard track inspection vehicles. Deutsche Bahn's digital rail program accelerates this transition across German core corridors. The technology is enabling predictive maintenance schedules that extend rail asset lifecycles while eliminating scheduled possession windows.
The EU F-Gas Regulation bans refrigerant-based infrared sensors from new rail inspection equipment certifications after 2027. Equipment manufacturers redirect thermal imaging R&D toward solid-state alternatives. Bridge inspection drones and tunnel monitoring platforms face the most acute sensor reconfiguration timelines.
North American Class I railroads consolidate inspection equipment procurement under multi-year fleet modernization contracts. Equipment-as-a-service models displace discrete capital purchases for mid-tier regional operators. This concentration is most visible across Union Pacific and BNSF corridor networks where standardized platform specifications reduce supplier qualification overhead.
Railway Automated Inspection Equipment Market Segmentation
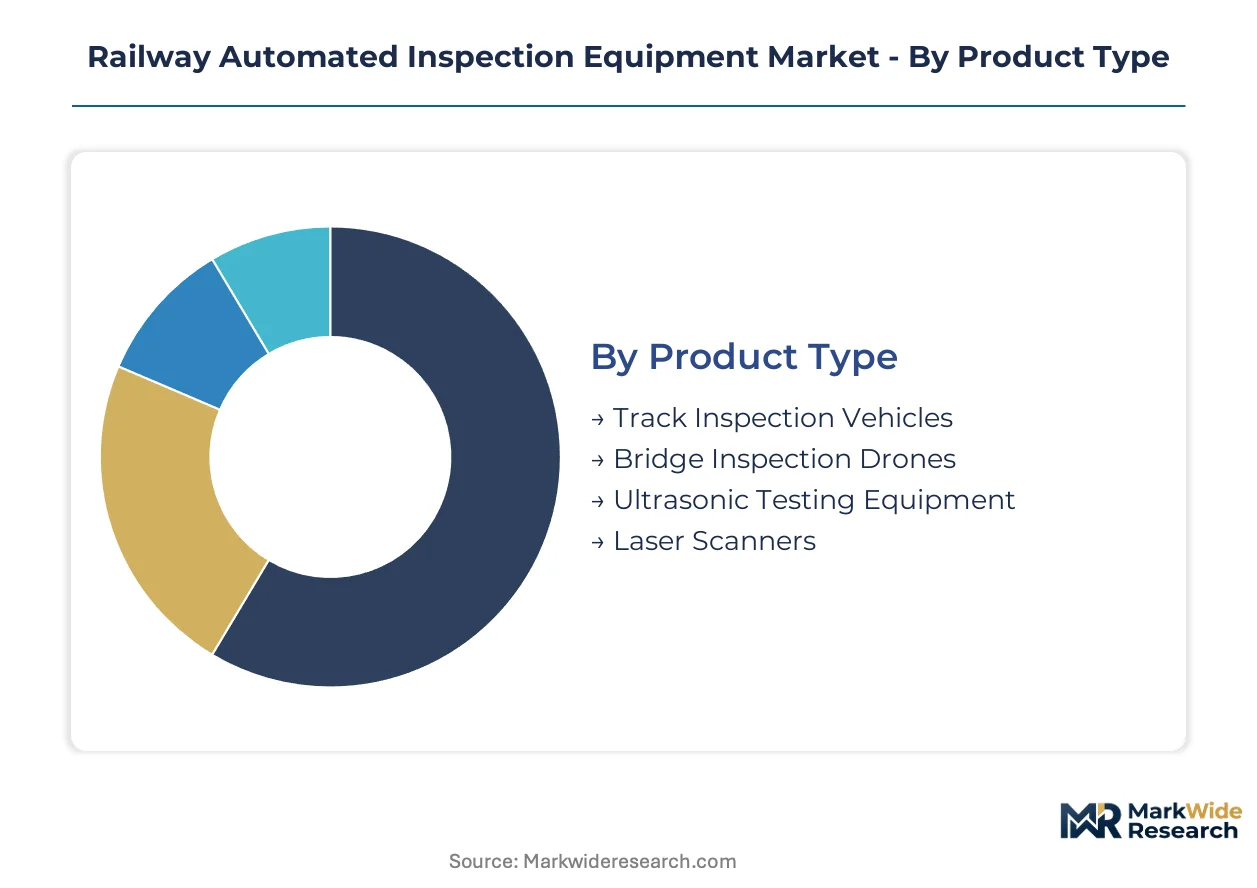
Equipment segmentation in railway automated inspection reflects divergent operational requirements across track geometry, structural integrity, and surface defect detection workflows. Procurement patterns cluster around inspection speed capabilities, sensor fusion complexity, and integration with legacy signaling infrastructure.
Product Type:
Use-case spectrum spans continuous track monitoring at operational speeds, confined-space structural assessment, subsurface flaw detection, and precision geometry mapping across heterogeneous rail networks.
- Track Inspection Vehicles:Rail-mounted sensor platforms integrate machine vision, laser profilometry, and inertial measurement units to capture track geometry deviations at speeds up to 120 km/h. Deutsche Bahn's digital rail program drives replacement demand across German core corridors where possession windows for manual inspection have compressed to economically unsustainable intervals.
- Bridge Inspection Drones:Aerial platforms equipped with high-resolution cameras and LiDAR payloads access viaduct soffits, piers, and bearings without track possession or scaffolding. Alpine infrastructure networks across Switzerland and Austria deploy these systems where manual access poses fall hazards and tunnel inventories exceed safe working platform reach.
- Ultrasonic Testing Equipment:Rail flaw detection systems using piezoelectric transducers identify internal defects including transverse fissures and bolt hole cracks.
- Laser Scanners:Terrestrial and mobile LiDAR systems generate millimeter-accurate point clouds for clearance envelope verification and wear pattern analysis.
The dominant share belongs to Track Inspection Vehicles, while Bridge Inspection Drones are closing the gap fastest.
Technology:
Cost tier stratification separates commodity sensor configurations from premium multi-modal fusion platforms commanding integration service margins.
- Machine Vision:Computer vision algorithms process high-speed camera feeds to classify rail surface defects including head checks, squats, and rolling contact fatigue cracks. European high-speed corridors prioritize these systems for continuous monitoring without speed restrictions, displacing periodic manual visual inspection.
- Acoustic Emission:Piezoelectric sensors detect stress wave emissions from active crack propagation in rail steel and concrete structural elements. High-speed rail applications in France and Japan specify these systems for micro-crack detection below ultrasonic resolution thresholds.
- Infrared Sensors:Thermal imaging identifies subsurface delamination and bearing overheating through temperature differential mapping.
- RFID:Radio-frequency identification tags automate asset location tracking and inspection history reconciliation across distributed rail networks.
Machine Vision commands the broadest deployment base, though Acoustic Emission platforms achieve the steepest pricing premiums.
Application:
Volume concentration aligns with maintenance regime maturity, from reactive intervention schedules toward predictive asset lifecycle management.
- Preventive Maintenance:Scheduled inspection protocols using automated equipment identify degradation trends before functional failure. North American Class I railroads concentrate procurement here to extend rail asset lifecycles and eliminate unplanned possession windows.
- Safety Monitoring:Real-time defect detection systems trigger immediate speed restrictions or service suspensions. FRA-mandated inspection intervals directly accelerate deployment across US freight networks where derailment liability costs exceed equipment amortization.
- Quality Assurance:Post-installation verification of new rail welds, turnouts, and track renewals against specification tolerances.
- Asset Management:Long-term condition data aggregation informs capital replacement prioritization and residual life estimation.
Preventive Maintenance absorbs the largest equipment allocation, while Safety Monitoring is gaining share fastest.
End User:
Customer type determines procurement modality, from capital ownership toward equipment-as-a-service arrangements with performance guarantees.
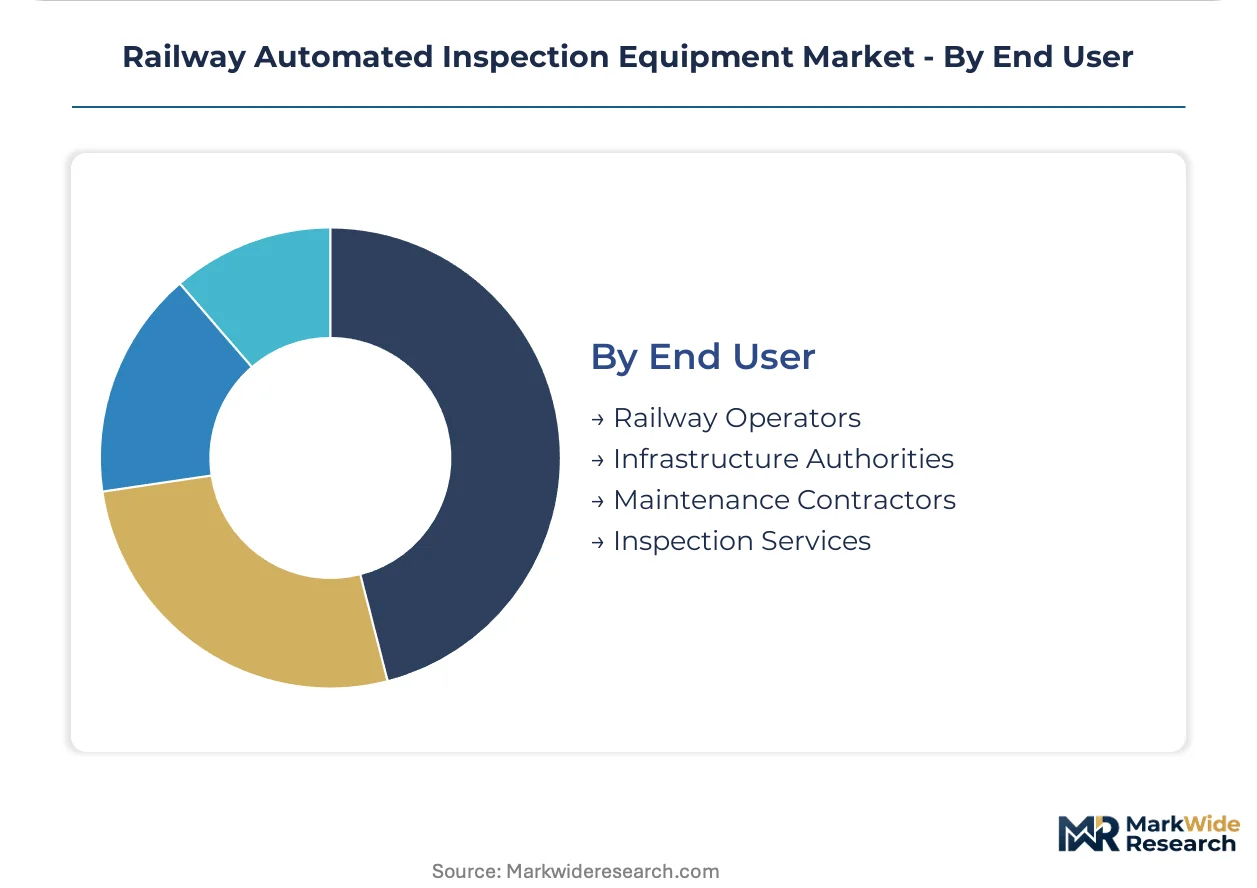
- Railway Operators:Integrated freight and passenger carriers deploy owned inspection fleets across core network segments. Union Pacific and BNSF consolidate multi-year fleet modernization contracts with standardized platform specifications reducing supplier qualification overhead.
- Infrastructure Authorities:Government track access providers specify inspection equipment for regulatory compliance verification. Germany's KBA and France's EPSF mandate independent assessment protocols creating dedicated procurement streams.
- Maintenance Contractors:Third-party service providers lease equipment to fulfill short-term inspection obligations.
- Inspection Services:Specialized NDT firms offer flaw interpretation and certification as bundled offerings.
Railway Operators retain the dominant procurement volume, though Infrastructure Authorities are expanding their share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers cluster around rail infrastructure investment corridors where regulatory mandates compress inspection cycles and digital replacement programs accelerate procurement. Germany, the United States, Japan, China, and India concentrate deployment volumes through divergent policy mechanisms and network modernization timelines.
Germany
Deutsche Bahn's digital rail program drives replacement of legacy ultrasonic testing fleets across core corridors. The EU F-Gas Regulation bans refrigerant-based infrared sensors from new certifications after 2027, redirecting thermal imaging R&D toward solid-state alternatives. Bavaria and North Rhine-Westphalia host the densest concentration of track inspection vehicle deployments as possession windows for manual inspection compress to economically unsustainable intervals.
United States
Class I freight railroads consolidate multi-year fleet modernization contracts to meet FRA-mandated safety intervals on transcontinental bulk commodity routes. The Federal Railroad Administration enforces mandatory inspection cycles that directly determine equipment replacement timelines across Union Pacific and BNSF corridor networks. Chicago and Omaha serve as procurement coordination hubs where standardized platform specifications reduce supplier qualification overhead.
Japan
High-speed rail operators specify acoustic emission systems for micro-crack detection below ultrasonic resolution thresholds on Shinkansen corridors. METI guidelines shape domestic certification protocols that constrain import eligibility for European and North American equipment vendors. The Kanto region around Tokyo concentrates the largest installed base of machine vision platforms operating at track speed without service interruption.
China
GB standards and NMPA-equivalent rail safety certifications determine export eligibility for foreign equipment vendors seeking access to dedicated freight corridor programs. State-owned rail operators deploy sensor-integrated platforms across the Beijing-Tianjin-Hebei cluster and Yangtze River Delta to address track geometry deviations at operational speeds. MIIT directives accelerate localization requirements for critical inspection subsystems.
India
The PLI scheme for rail infrastructure creates localized assembly incentives for automated inspection equipment manufacturers targeting dedicated freight corridors. Indian Railways mandates predictive maintenance schedules across the Delhi-Mumbai and Delhi-Kolkata trunk routes where manual inspection regimes face capacity constraints. Maharashtra and Gujarat host emerging equipment integration facilities serving western corridor modernization programs.
Railway Automated Inspection Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and flaw detection algorithms. The vendor base stratifies between full-stack track inspection vehicle providers and modular subsystem suppliers. Three archetypes dominate: signaling-embedded industrial conglomerates, specialized NDT technology firms, and robotics-focused automation entrants. Consolidation pressure manifests through multi-year fleet modernization contracts and equipment-as-a-service model proliferation.
Within the industrial conglomerate tier, Siemens and Alstom occupy positions leveraging embedded signaling expertise across European track inspection deployments. NDT Global anchors the specialized technology segment with proprietary rail flaw detection algorithms refined across North American Class I railroads. SIASUN represents the automation-focused archetype among Asian robotics manufacturers targeting bridge inspection drone applications. These three exemplify divergent strategic postures: vertical integration through signaling infrastructure, algorithmic specialization in ultrasonic testing, and aerial platform robotics for confined-space structural assessment.
| Leading Market Players |
|---|
| Trimble Industries |
| ANYbotics |
| ROSEN Group |
| Bombardier |
| GE Transportation |
| Siemens |
| Alstom |
| SIASUN |
| NDT Global |
| Others |
Supply Flow & Price Mechanics
The Trans-Siberian corridor's cost dynamics illustrate how supply concentration among German and Japanese sensor manufacturers shapes pricing power across inspection equipment tiers, while downstream price differentiation reflects the divergence between Class I railroad procurement and regional operator leasing models.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European inspection equipment markets, separating solid-state thermal imaging platforms from legacy refrigerant-based configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FRA, CE marking, and GB standard protocols. Pricing pressure stems from equipment-as-a-service model proliferation among mid-tier North American operators. Class I railroads exhibit lowest price sensitivity through multi-year fleet modernization contracts, while maintenance contractors face acute margin compression in spot procurement markets.
Supply Chain Analysis
Extended payment terms from North American Class I railroads anchor supplier financing structures, compressing working capital cycles for component specialists. Manufacturing concentration rests on Germany, Japan, and China for piezoelectric transducers, solid-state infrared sensors, and machine vision processors respectively. Supply chain risk centers on single-source vulnerability for high-speed rail-grade acoustic emission modules. Distribution runs through OEM direct sales for integrated track inspection vehicles and specialized NTD firms for flaw interpretation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through North American Class I railroad procurement consolidation, fragmenting pricing leverage among mid-tier equipment vendors and redirecting margin capture toward fleet modernization contractors.
For Market Incumbents: Harden embedded signaling integration capabilities to defend against robotics-focused automation entrants targeting bridge inspection drone applications. Deepen backward integration into solid-state sensor production to offset EU F-Gas Regulation compliance cost elevation. Prioritize certification investment under China's GB standards to maintain export eligibility for dedicated freight corridor programs. For New Entrants and Emerging Players: India's dedicated freight corridors represent the most penetrable geographic entry point, where PLI scheme localization incentives reduce incumbent cost advantages. Target acoustic emission system white space in high-speed rail applications where micro-crack detection thresholds command premium positioning. Pursue joint venture structures with established maintenance contractors to bypass direct procurement qualification barriers. For Investors and Strategic Acquirers: Algorithm-specialist NDT firms with proprietary rail flaw detection libraries offer asymmetric return profiles as automated inspection displaces manual protocols. Long-term viability hinges on 5-10 year predictive maintenance regime maturation across OECD networks. Monitor FRA safety interval tightening velocity as inflection indicator for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Signaling Integration | Siemens and Alstom leverage captive rail infrastructure protocols to lock out modular subsystem competitors. |
| Solid-State Sensor Transition | EU F-Gas Regulation redirects R&D expenditure toward refrigerant-free thermal imaging alternatives. |
| Equipment-as-a-Service Rollout | Union Pacific and BNSF consolidation contracts displace discrete capital purchases among regional operators. |
| Alpine Drone Certification | Swiss and Austrian infrastructure authorities mandate specialized viaduct access platforms for aging tunnel inventories. |
| GB Standard Localization | MIIT directives force foreign vendors into domestic joint ventures for China dedicated freight corridor access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FRA safety compliance databases, EU equipment certification registries, and Class I railroad capital expenditure disclosures. Interviews with track maintenance directors, NDT service procurement leads, signaling integration engineers, and infrastructure authority compliance officers informed demand-side validation. Bottom-up equipment deployment counts triangulate against top-down rail network modernization budget aggregates.
Forecast inputs span inspection speed capability tiers, sensor fusion complexity levels, and integration requirements with legacy signaling infrastructure across the projection horizon. Product type segmentation incorporates track inspection vehicles, bridge inspection drones, ultrasonic testing equipment, and laser scanner platforms. Technology segmentation captures machine vision, acoustic emission, infrared sensor, and RFID modalities. CAGRs derive from equipment replacement cycle analysis under tightening regulatory intervals and predictive maintenance regime adoption curves.
Practitioners should monitor FRA safety mandate revision schedules, EU F-Gas Regulation enforcement intensity, and China localization requirement acceleration for early signals of forecast deviation. Macroeconomic contraction in freight rail volumes, regulatory harmonization failure across cross-border corridors, or breakthrough detection technology displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Market
Railway
Solar Powered Train Market
Railway
Global Train Brake Market
Railway
Automatic Train Supervision Market
Railway
Railway Management System Market
Railway
Railway Track Market
Railway
Connected Rail Market
Railway
Rail Brake Frame Market
Railway
Railway Overhead Catenary System Market
Railway
Train Exterior Lighting Market
Railway
Global High-Speed Train Seat Market
Railway
Railway Axle Market
Railway
Railroads Market
Railway
Asia Pacific Rail Freight Transport Market
Railway
Railway System Market
Railway
France Connected Rail Market