
 Solar Train Market | 2026-2036
Solar Train Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Train Market Analysis
India is tilting toward solar rail infrastructure with dedicated photovoltaic corridors along existing track networks. Alstom SA leverages its hydrogen and hybrid rail expertise to compete in integrated clean transit platforms. Siemens AG anchors European solar rail development through power management and electrification systems. CRRC Corporation Limited dominates manufacturing scale with capacity for photovoltaic-integrated rolling stock.
A solar train is a rail vehicle or railway system that draws primary or supplementary power from photovoltaic panels mounted on rooftops, trackside arrays, or dedicated solar farms, typically paired with battery energy storage systems rated between 500 kWh and 2 MWh to maintain traction during tunnel transit or low-irradiance conditions. Its commercial purpose is to reduce diesel dependency and grid electricity consumption in rail operations while cutting lifecycle carbon emissions per passenger-kilometer. Light rail systems occupy the largest installed base due to lower power requirements and favorable roof-to-weight ratios for onboard panel deployment. Energy storage systems represent the fastest-expanding technology segment as battery cost curves improve and operators demand uninterrupted service across variable weather patterns. Photovoltaic cells remain the margin-critical component where monocrystalline silicon efficiency gains directly reduce required panel surface area and infrastructure footprint.
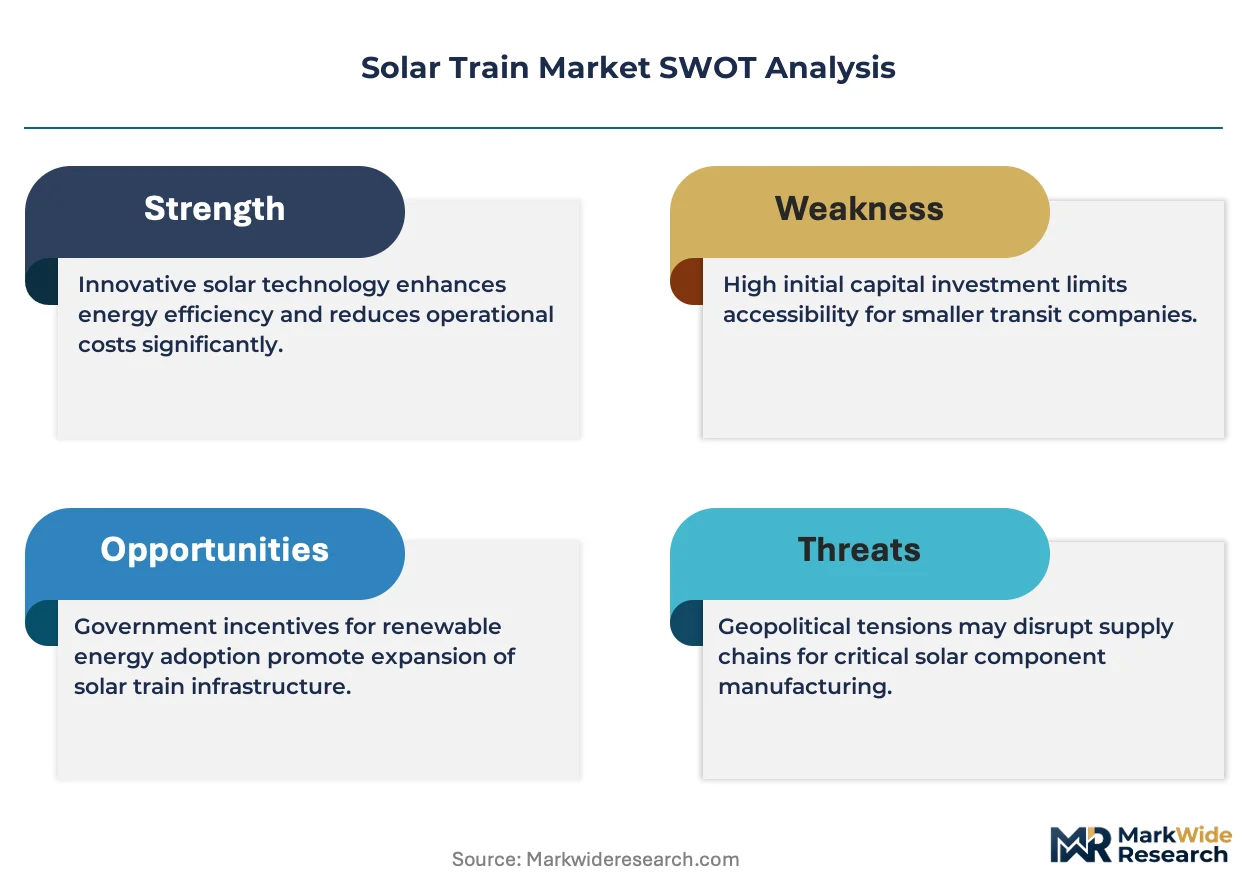
The International Union of Railways sets cross-border technical standards for photovoltaic integration in rolling stock, while India's Ministry of Railways mandates solar procurement quotas for station and traction power. The EU Green Deal and F-Gas Regulation pressure operators to abandon diesel multiple units and adopt zero-emission alternatives including solar-battery hybrids. Stakeholders must monitor whether national rail regulators will mandate minimum renewable energy shares for fleet procurement or restrict market access to non-compliant vendors.
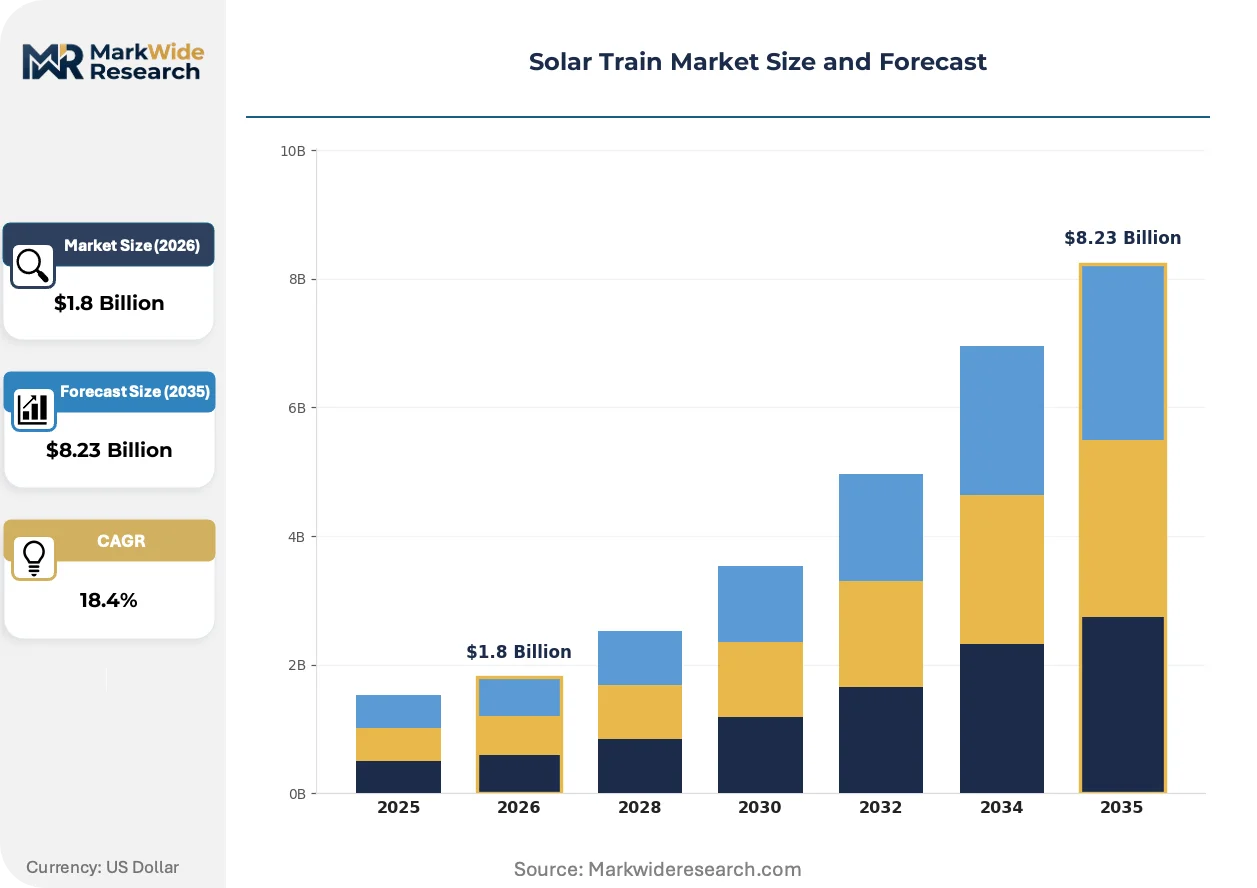
Market Dynamics
Photovoltaic cell efficiency gains above 26% are compressing panel surface requirements for onboard deployment, while lithium-ion battery cost curves below $100 per kWh are enabling viable energy storage integration at fleet scale.
Growth Catalysts
- India's Ministry of Railways renewable mandates:Station and traction power procurement quotas create guaranteed offtake for photovoltaic-integrated rolling stock across dedicated solar corridors.
- Perovskite tandem cell commercialization:Laboratory-validated efficiency pathways above 30% promise to halve rooftop panel area for equivalent energy capture in light rail configurations.
- Australia's regional network electrification gap:Sparse grid infrastructure in Queensland and New South Wales makes solar-battery hybrids economically competitive against diesel multiple units on unelectrified branch lines.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based ingot and wafer production dominates upstream photovoltaic manufacturing, exposing fleet operators to forced labor compliance risks and trade restriction exposure.
- Intermittency engineering costs:Battery energy storage systems rated at 1-2 MWh per trainset add 40-60% capital cost premiums versus conventional electrified rolling stock.
- F-Gas Regulation phase-down schedules:EU-mandated hydrofluorocarbon restrictions complicate thermal management system design for battery compartments in solar-hybrid trains.
Strategic Opportunities
- Indonesia's unelectrified island networks:Java and Sumatra regional rail operators seek diesel displacement solutions where overhead catenary installation proves cost-prohibitive across volcanic terrain.
- Vehicle-to-grid integration:Bidirectional charging infrastructure allows stationary trainsets to arbitrage peak electricity prices and stabilize renewable-heavy grids.
- EU Green Deal fleet renewal funding:Innovation tenders and Just Transition Mechanism allocations specifically target zero-emission rail technologies including solar-battery hybrids.
Industry Challenges
- Battery thermal runaway containment engineering:Rail-specific fire suppression and venting system certification lags automotive standards, extending type approval timelines by 18-24 months.
- Photovoltaic-rolling stock structural integration:Aerodynamic loading, vibration fatigue, and electromagnetic compatibility testing for roof-mounted panels requires bespoke validation protocols absent from highway vehicle standards.
- Traction power engineer retraining:Maintenance workforces accustomed to diesel-electric or pure electric systems lack competency in hybrid energy management and DC-DC conversion diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Train Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Rail, Heavy Rail, Commuter Train, Freight Train Technology: Photovoltaic Cells, Energy Storage Systems, Integrated Circuits, Power Management Systems End User: Public Transit Authorities, Private Operators, Logistics Companies, Government Agencies Installation: On-Track Systems, Centralized Power Stations, Decentralized Power Units, Hybrid Systems |
| Companies Covered | Alstom SA, Hanwha S&C, Byron Bay Railroad Company, Siemens AG, Canadian Solar, Riding Sunbeams, CRRC Corporation Limited, Greenrail, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Train Market Emerging Trajectories
Digital twin simulation of photovoltaic yield patterns is compressing route planning cycles and enabling dynamic energy dispatch algorithms that match generation profiles to traction load curves.
Silicon-perovskite tandem photovoltaic architectures are digitizing fleet energy modeling by enabling granular irradiance-to-traction-power conversion predictions across variable weather corridors. European light rail operators in France and Germany are piloting these cells on tram roof retrofits. The technology is compressing payback period calculations from annual averages to route-segment specificity.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are forcing thermal management redesigns in battery compartment HVAC systems. Manufacturers must substitute CO2 or hydrocarbon-based cooling circuits before 2030 deadlines. Light rail segments with high tunnel density face the steepest engineering adaptation costs due to confined-space fire safety requirements.
Transit authorities are unbundling rolling stock procurement from 30-year energy service contracts, creating separate vendor accountability for photovoltaic generation performance versus traction system reliability. Australian regional operators pioneered this split-contract structure. The model is concentrating vendor selection criteria on guaranteed cost-per-kilometer outcomes rather than capital expenditure minimization.
Solar Train Market Segmentation
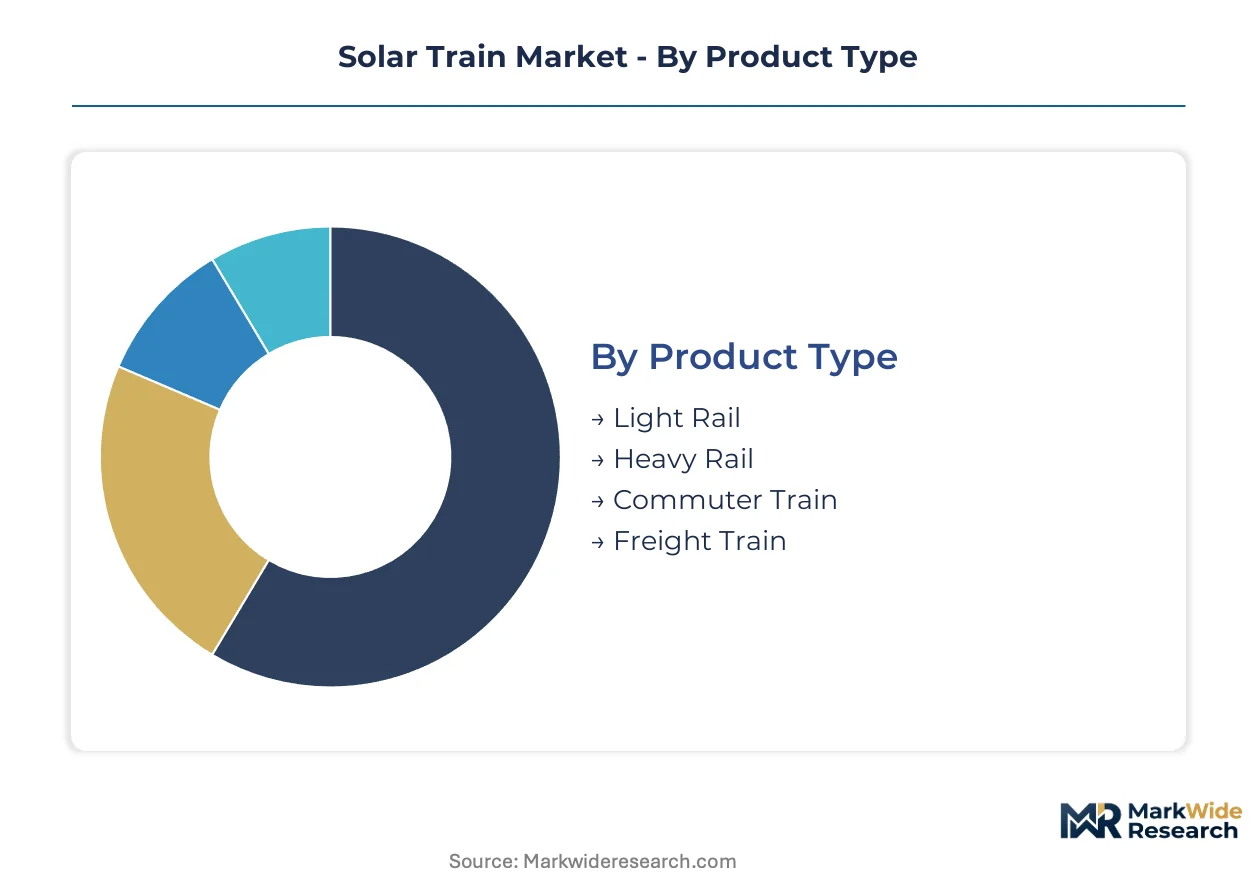
Solar train procurement cycles vary dramatically by rail category and technology maturity. Fleet operators structure capital deployment around rolling stock lifecycles spanning 25-40 years versus energy storage replacements every 8-12 years.
Product Type:
Light rail systems turn over fastest at 20-25 year intervals, while freight locomotives stretch replacement cycles beyond 35 years.
- Light Rail:Tram and streetcar configurations dominate rooftop photovoltaic deployment due to favorable surface-area-to-weight ratios and lower continuous power draw. Australian operators in Byron Bay and regional Queensland networks are expanding light rail solar pilots to displace diesel buses on tourist and commuter corridors.
- Heavy Rail:Mainline passenger services require 1-2 MWh battery configurations to maintain traction through tunnels and low-irradiance zones. India's Ministry of Railways is targeting heavy rail solar integration along dedicated photovoltaic corridors where catenary electrification remains incomplete.
- Commuter Train:Suburban rolling stock with predictable stop-start patterns suits regenerative braking paired with solar supplementation.
- Freight Train:High continuous power demands and extended route distances limit onboard solar viability to hybrid auxiliary systems.
Light rail dominates installed base. Heavy rail is where expansion concentrates.
Technology:
Cost tier differentiation separates margin-critical photovoltaic components from commoditized power electronics.
- Photovoltaic Cells:Monocrystalline silicon architectures above 26% efficiency are compressing panel surface requirements for rooftop mounting. European operators in France and Germany are piloting silicon-perovskite tandem cells that promise 30%+ conversion rates.
- Energy Storage Systems:Lithium-ion configurations rated 500 kWh to 2 MWh enable tunnel transit and weather-independent scheduling. Battery thermal management engineering represents the steepest certification hurdle under EU F-Gas Regulation phase-down mandates.
- Integrated Circuits:Power conversion and MPPT control electronics face automotive-grade reliability standards.
- Power Management Systems:DC-DC conversion and grid synchronization hardware enables vehicle-to-grid revenue arbitrage.
Photovoltaic cells command premium pricing. Energy storage systems are climbing the fastest as battery cost curves improve.
End User:
Procurement authority concentration shapes contract structures and vendor accountability models.
- Public Transit Authorities:State-owned operators in India and Australia are unbundling rolling stock procurement from 30-year energy service contracts, creating separate vendor accountability for generation performance versus traction reliability.
- Private Operators:European light rail concessions in France and Germany prioritize guaranteed cost-per-kilometer outcomes over capital expenditure minimization.
- Logistics Companies:Freight rail operators evaluate solar auxiliary systems for yard switching and last-mile diesel displacement.
- Government Agencies:Defense and industrial rail networks seek energy security through decentralized photovoltaic generation.
Public transit authorities dominate procurement volume. Private operators are gaining share fastest through concession restructuring.
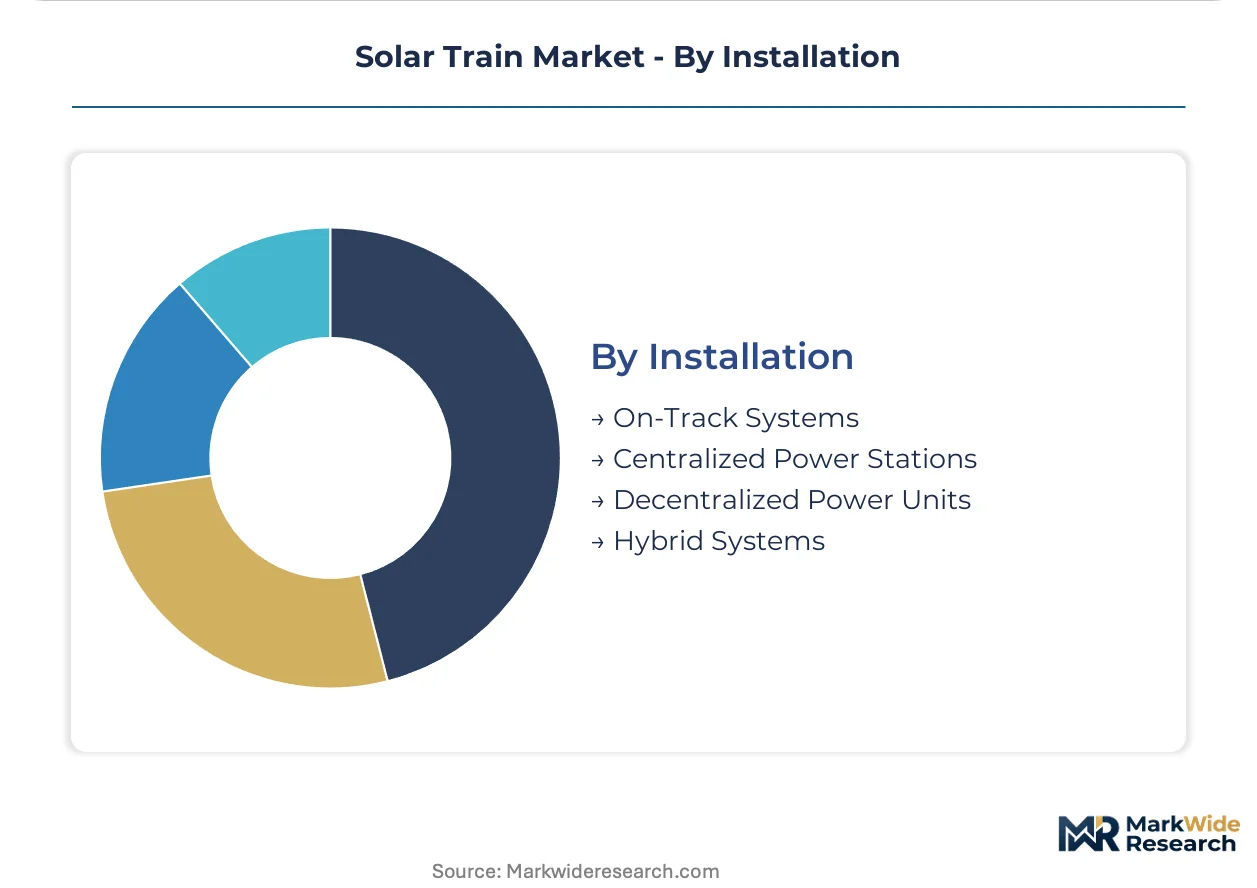
Installation:
Supply concentration in upstream photovoltaic manufacturing shapes installation architecture decisions.
- On-Track Systems:Photovoltaic panels mounted directly on rolling stock rooftops maximize land-use efficiency but require aerodynamic and vibration-resistant engineering. Australia's Riding Sunbeams pilots demonstrate commercial viability for regional branch lines.
- Centralized Power Stations:Dedicated solar farms feeding grid-connected traction substations avoid onboard weight penalties. Indian Railways is expanding centralized installations along unelectrified corridors in Rajasthan and Gujarat.
- Decentralized Power Units:Trackside photovoltaic arrays with localized battery buffering serve sparse networks.
- Hybrid Systems:Combinations of onboard generation, trackside arrays, and grid connection optimize for route-specific irradiance patterns.
On-track systems anchor technology development. Centralized power stations are expanding most quickly in markets with land availability and grid integration capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Railways anchors deployment momentum through renewable energy procurement mandates that create guaranteed offtake for photovoltaic-integrated rolling stock. Four countries concentrate near-term installation activity.
India
Rajasthan and Gujarat host dedicated solar corridors where catenary electrification remains incomplete, driving heavy rail integration pilots. The Ministry of Railways mandates solar procurement quotas for station and traction power under national renewable energy targets. Indian Railways operates concentrated deployment along the Delhi-Mumbai freight corridor where land availability supports trackside photovoltaic arrays.
Australia
Queensland and New South Wales regional networks face sparse grid infrastructure that makes solar-battery hybrids competitive against diesel multiple units. Byron Bay Railroad Company operates the world's first fully solar train on a 3-kilometer tourist corridor. Riding Sunbeams pilots demonstrate commercial viability for branch line electrification without overhead catenary.
Germany
Siemens AG anchors European power management and electrification system development for solar-hybrid platforms. The EU Green Deal and F-Gas Regulation pressure operators to abandon diesel multiple units through mandated hydrofluorocarbon phase-down schedules. Light rail operators in Baden-Württemberg pilot silicon-perovskite tandem cells on tram roof retrofits.
China
CRRC Corporation Limited dominates manufacturing scale with capacity for photovoltaic-integrated rolling stock production. Xinjiang-based polysilicon ingot and wafer production concentrates upstream photovoltaic supply, exposing fleet operators to forced labor compliance risks. The Yangtze River Delta clusters battery energy storage system integration facilities serving domestic and export markets.
United States
California transit authorities evaluate solar auxiliary systems for yard switching and last-mile diesel displacement in freight operations. The EPA and state-level renewable portfolio standards create procurement pressure for zero-emission rail technologies. The Pacific Northwest hosts pilot programs pairing hydroelectric grid integration with solar-battery hybrid switching locomotives.
Solar Train Market Vendor Landscape
Rolling stock manufacturers and photovoltaic system integrators split the market between traction platform expertise and energy generation specialization. The competitive structure concentrates around three strategic archetypes: European electrification conglomerates with hybrid rail portfolios, Chinese state-owned manufacturing enterprises with integrated supply chains, and regional solar rail specialists with demonstration project track records. Dominant competitive moves include strategic partnerships between rail operators and photovoltaic developers for 30-year energy service contracts, plus geographic expansion through unelectrified corridor targeting in Southeast Asia and Latin America.
Within the European electrification tier, Alstom SA and Siemens AG represent integrated clean transit platform development, each leveraging hydrogen and hybrid rail expertise to compete for photovoltaic corridor contracts. CRRC Corporation Limited occupies the scale-driven manufacturing position with captive capacity for photovoltaic-integrated rolling stock production. Among regional specialists, Byron Bay Railroad Company and Riding Sunbeams exemplify demonstration-to-commercialization pathways for solar-battery hybrid operations on unelectrified branch lines.
| Leading Market Players |
|---|
| Alstom SA |
| Hanwha S&C |
| Byron Bay Railroad Company |
| Siemens AG |
| Canadian Solar |
| Riding Sunbeams |
| CRRC Corporation Limited |
| Greenrail |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
Xinjiang polysilicon concentration exposes fleet procurement to forced labor compliance audits and US UFLPA detention risk, compressing pricing spreads between verified-origin and unverified photovoltaic modules while reshaping supplier qualification protocols across rolling stock tenders. Indian Railways and Australian regional operators now mandate supply chain documentation that adds certification premiums to tier-one sourcing while disqualifying tier-two bids.
Pricing Analysis
European light rail operators pay 15-25% premiums over Indian procurement for identical photovoltaic-integrated trainsets due to EU F-Gas Regulation thermal management requirements and CE marking complexity. Pricing stratifies across premium, standard, and economy tiers based on battery energy storage capacity ratings and monocrystalline silicon efficiency grades. Cost compression in standard-tier configurations is intensifying because lithium-ion cell prices are dropping faster than balance-of-system integration costs. Public transit authorities in India exhibit highest price sensitivity, while German private operators prioritize guaranteed cost-per-kilometer outcomes over capital expenditure minimization.
Supply Chain Analysis
Polysilicon ingot and wafer production draws from Xinjiang, Inner Mongolia, and Yunnan provinces in China, with South Korean and Malaysian facilities providing alternative sourcing for compliance-sensitive buyers. Lithium carbonate feedstock hinges on Chilean and Australian hard-rock spodumene deposits, while battery cell assembly concentrates in China's Yangtze River Delta and South Korea's Gyeonggi Province. Single-source vulnerability runs through Xinjiang-based ingot supply where UFLPA enforcement creates sudden procurement freezes. Distribution runs through rail OEM direct contracting for rolling stock integration, with photovoltaic module suppliers establishing dedicated transportation and logistics certification tracks for vibration-resistant packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diesel multiple unit phase-out mandates across EU and Indian rail networks position solar-battery hybrids as the incumbent electrification alternative, yet hydrogen fuel cell trains and battery-electric catenary connections threaten to capture corridor segments where solar yield variability proves operationally prohibitive.
For Market Incumbents: Pre-empt hydrogen fuel cell encroachment by securing 30-year energy service contracts with guaranteed irradiance-adjusted performance clauses that lock out competing zero-emission technologies. Backward integration into polysilicon ingot sourcing through joint ventures with Malaysian or Vietnamese wafer producers eliminates Xinjiang exposure while defending margin position against compliance-premium erosion.
For New Entrants and Emerging Players: Pursue Indonesia's unelectrified island networks where volcanic terrain prevents overhead catenary installation and diesel displacement mandates create immediate procurement windows. Java and Sumatra regional rail operators represent the most penetrable geography for solar-battery hybrid demonstration projects. A go-to-market angle anchored to vehicle-to-grid revenue arbitrage contracts differentiates against incumbent rolling stock vendors focused solely on traction performance.
For Investors and Strategic Acquirers: The market sits at a demonstration-to-commercialization phase that favors regional specialists with pilot project track records over capital-heavy manufacturing scale plays. Long-term viability favors acquisition targets possessing silicon-perovskite tandem cell integration partnerships and F-Gas Regulation-compliant thermal management certifications. The signal to watch is Indian Railways unbundling procurement structures that separate energy service vendors from rolling stock manufacturers, which would validate independent power producer models.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Perovskite Tandem Cell Integration | European operators in Baden-Württemberg validate 30%+ efficiency pathways that halve rooftop panel area requirements. |
| 30-Year Energy Service Contract Unbundling | Australian regional operators pioneer split-accountability models that concentrate vendor selection on cost-per-kilometer outcomes. |
| Xinjiang-Exempt Polysilicon Sourcing | Malaysian and Vietnamese wafer production eliminates UFLPA detention risk for EU and US fleet procurement. |
| Vehicle-to-Grid Infrastructure Deployment | Bidirectional charging systems allow stationary trainsets to arbitrage peak electricity prices in renewable-heavy grids. |
| F-Gas Regulation Thermal Management Redesign | CO2-based cooling circuit substitution before 2030 deadlines secures EU market access for battery compartment HVAC systems. |
Methodological Framework
Desk research of railway electrification standards, photovoltaic cell efficiency publications, and national renewable energy procurement databases preceded structured interviews with rolling stock procurement directors, battery energy storage system integration engineers, and regulatory affairs specialists at transit authorities. Primary fieldwork with Indian Railways planning officers and Australian regional network operators validated secondary assumptions on deployment timelines. Analysis combined bottom-up project pipeline tracking with top-down policy mandate quantification across the EU Green Deal, India's Ministry of Railways renewable targets, and Australia's Clean Energy Finance Corporation funding mechanisms.
Assumptions held photovoltaic cell efficiency gains and lithium-ion cost curves within observed trajectories while varying rail electrification subsidy intensity and diesel price volatility as scenario inputs. Segmentation modeling incorporated product type, technology tier, end-user procurement authority, and installation architecture dimensions. CAGRs derived from installed base replacement cycles and new corridor electrification announcements across the projection horizon. Forecast inputs included India's dedicated solar corridor land availability assessments and Australia's Riding Sunbeams pilot expansion commitments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned manufacturers into downstream project development would shift outcomes through vertically integrated pricing. Cross-checking against International Union of Railways standards adoption timelines and national rail regulator procurement quota enforcement is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Train Control and Management Systems Market
Railway
40-Foot Platform Wagons Market
Railway
Railway Engine Market
Railway
Freight Cars Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Locomotive Maintenance Market
Railway
Railway Buffer Stops Market
Railway
Rail Transit Traction Converter Market
Railway
Maglev Train Market
Railway
Rolling Stock Management Market
Railway
Global Train Lighting Market
Railway
Automatic Train Control Market
Railway
Rail Composites Market
Railway
Locomotive Parking Brake Market
Railway
Road-Rail Vehicles Market
Railway
Railway Draft Gears Market