
 Transit Ticketing Market | 2026-2036
Transit Ticketing Market Size, Share, and Industry Trends Forecast 2026-2036
Transit Ticketing Market Analytics
India's urban transit infrastructure build-out is tilting procurement priorities toward interoperable digital fare collection. Cubic Transportation Systems leverages its installed base in North American rail networks to extend platform capabilities into emerging smart city contracts. Thales Group anchors European market presence through embedded security modules and contactless validator hardware. NXP Semiconductors dominates NFC chipset supply for transit form factors, competing on EMVCo certification breadth and transit-specific power optimization.
Transit ticketing encompasses hardware, software, and service layers that authenticate passenger entitlement, calculate fares, and reconcile revenue across multimodal journeys. Core systems integrate ISO 14443-compliant contactless readers, back-office clearing engines, and real-time APIs linking operators to payment networks. Contactless technology leads transaction volume in mature markets while mobile and QR code segments capture fastest growth in smartphone-dense emerging economies. Smart card infrastructure sustains margin pools in legacy system maintenance, whereas parking and ride-sharing service types attract new platform entrants seeking recurring SaaS revenue.
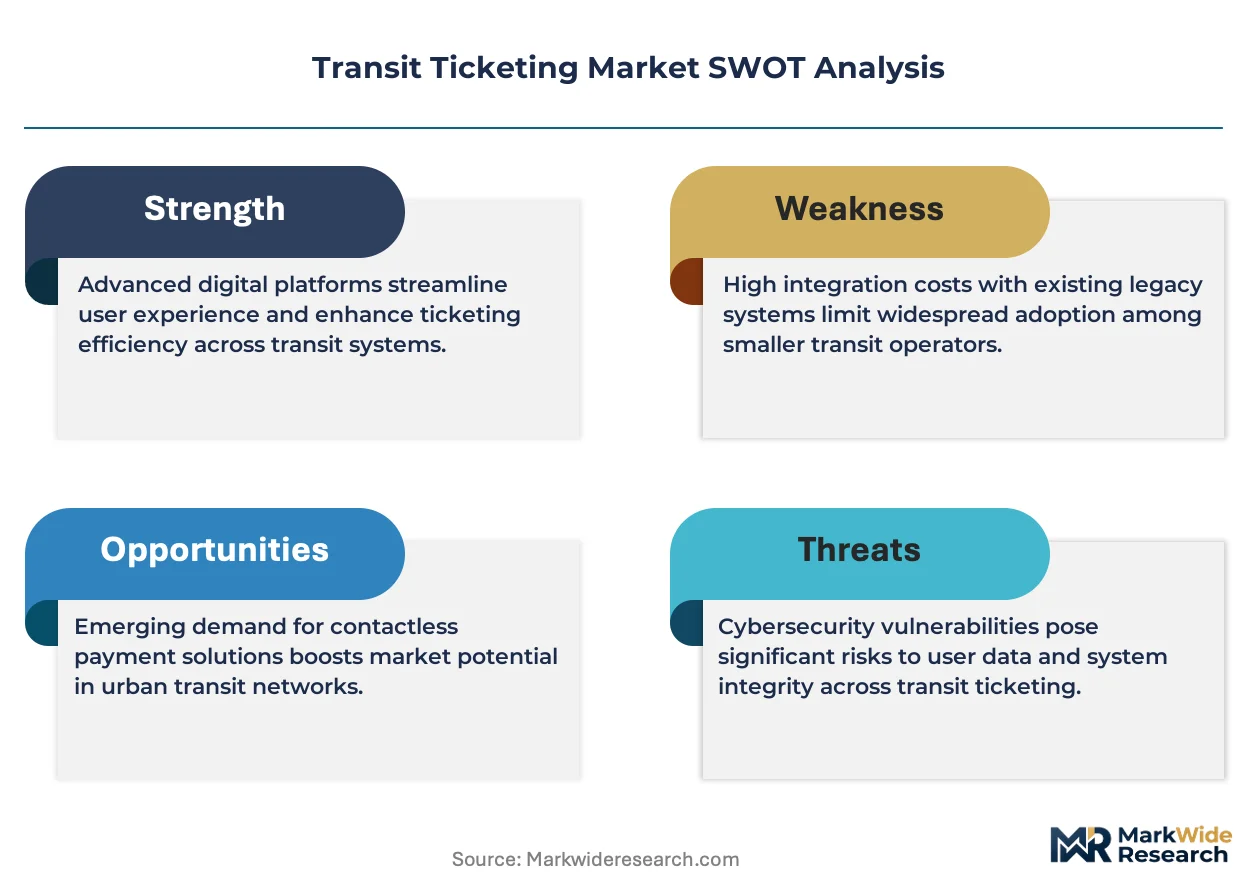
FCC Part 15 governs radio frequency emissions for U.S. validator hardware, while the European Commission's Interoperable Fare Management framework mandates cross-border ticket recognition. India's BIS certifies terminal durability standards under its smart cities program, and PCI-DSS compliance shapes payment method architecture across all geographies. Stakeholders must monitor regulatory divergence between open-loop financial standards and closed-loop transit operator requirements when architecting next-generation platform investments.
Market Dynamics
Account-based ticketing architectures are compressing legacy closed-loop infrastructure replacement cycles, forcing hardware vendors to pivot toward API-first platform revenue models and recurring software subscriptions.
Growth Catalysts
- PCI-DSS compliance mandates:Payment card industry security standards are compelling transit operators to upgrade validator hardware and encryption modules, accelerating procurement of certified contactless readers.
- India's National Common Mobility Card:The interoperable fare media rollout across 25+ Indian cities is generating concentrated demand for multimodal clearing engines and back-office integration services.
- Smartphone penetration corridors:Mobile wallet density in Southeast Asian urban clusters is pulling QR-code and NFC-tap adoption ahead of smart card deployment timelines.
Market Restraints
- NFC chipset supply concentration:Foundry capacity constraints for EMVCo-certified secure elements are extending lead times for validator OEMs dependent on single-source semiconductor vendors.
- Copper and rare earth input volatility:Antenna substrate materials and magnetic component feedstock costs are compressing hardware margins on contactless reader production.
- European Interoperable Fare Management fragmentation:Cross-border ticket recognition standards remain inconsistently implemented across national rail operators, delaying unified procurement specifications.
Strategic Opportunities
- MaaS platform convergence:Integration of transit ticketing with ride-hailing and bike-share APIs is opening white-space revenue pools for middleware providers orchestrating multimodal journey planners.
- China's integrated multimodal platforms:Super-app ecosystems combining subway, bus, and intercity rail payments are demonstrating scalable templates for operator consortiums in other high-density corridors.
- Open-loop payment tailwinds:European Commission mandates eliminating proprietary closed-loop systems are creating replacement demand for bank-card-ready validator infrastructure.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for ISO 14443-compliant readers requires specialized RF antenna tuning expertise that competes with broader IoT device talent pools.
- Legacy AFC integration complexity:Backward compatibility requirements with decades-old magnetic stripe and proprietary smart card systems are inflating deployment timelines and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transit Ticketing Market |
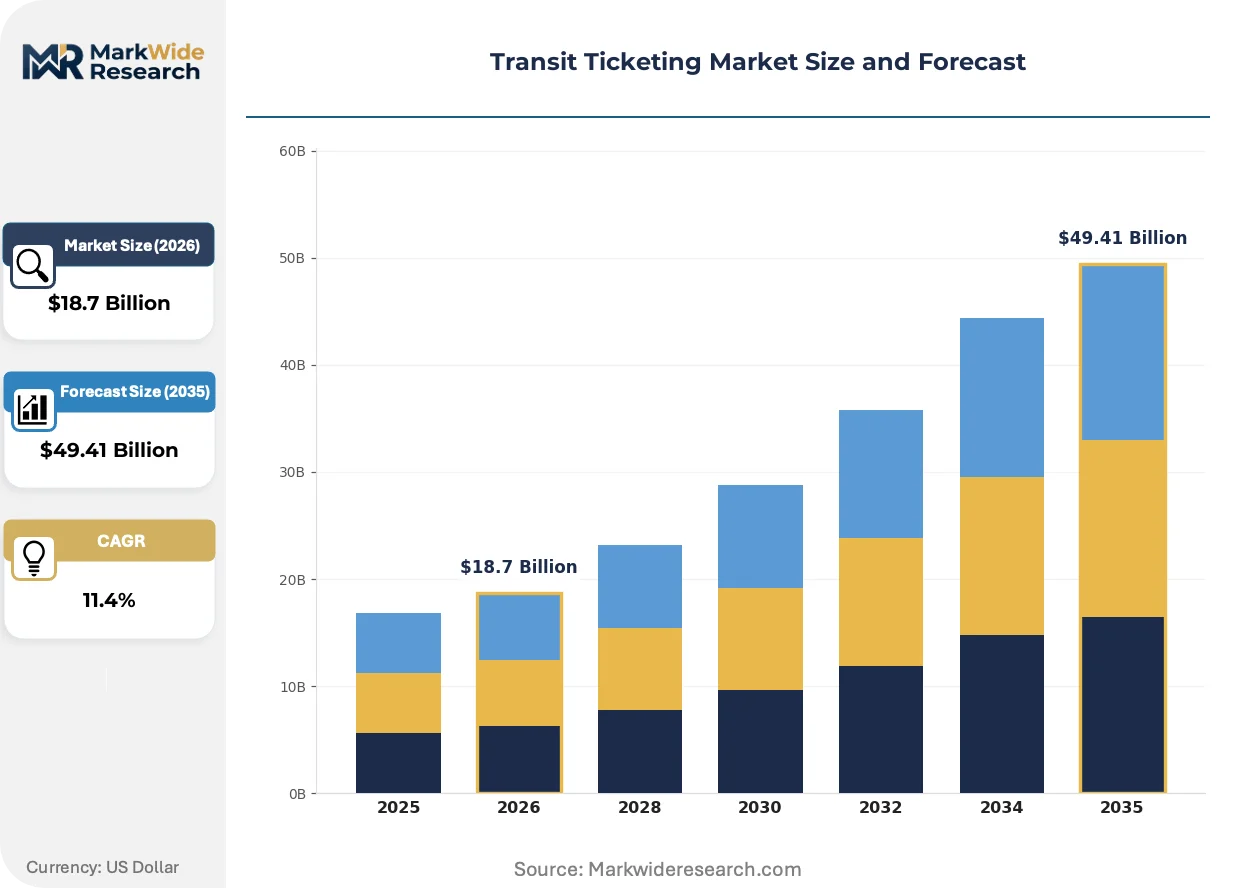
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Contactless, Mobile, QR Code, Smart Card Service Type: Public Transport, Parking, Ride Sharing, Taxi Services End User: Commuters, Tourists, Businesses, Agencies Payment Method: Credit Card, Mobile Wallet, Cash, Digital Currency |
| Companies Covered | Conduent, Cubic Transportation Systems, Thales Group, Giesecke + Devrient, HID Global, NXP Semiconductors, Scheidt & Bachmann, Infineon Technologies, Masabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transit Ticketing Market Evolving Landscape
Cloud-native fare collection platforms are collapsing the traditional hardware-software boundary, enabling operators to push fare logic updates over-the-air while validators become thin edge devices.
Biometric facial recognition ticketing is digitizing passenger authentication at fare gates, eliminating physical media entirely. Shenzhen Metro and Moscow Transport are deploying 3D camera arrays for fare-deduct-on-entry workflows. The technology is digitizing revenue assurance by binding payment credentials to immutable biological identifiers rather than transferable cards or devices.
Europe's Cyber Resilience Act is mandating security-by-design requirements for connected transit infrastructure, forcing validator OEMs to embed hardware root-of-trust modules and automated patch management. Hardware vendors serving EU rail operators must now certify against IEC 62443 industrial cybersecurity standards before contract award. The regulation is compressing procurement timelines as operators accelerate pre-mandate replacement cycles.
Rider expectations shaped by retail payment experiences are forcing transit agencies to unbundle fare products from physical media ownership. Subscription capping and post-pay journey aggregation are displacing prepaid season ticket models. London's capping mechanism and Singapore's SimplyGo platform demonstrate this behavioral shift most visibly in high-frequency commuter corridors.
Transit Ticketing Market Segmentation
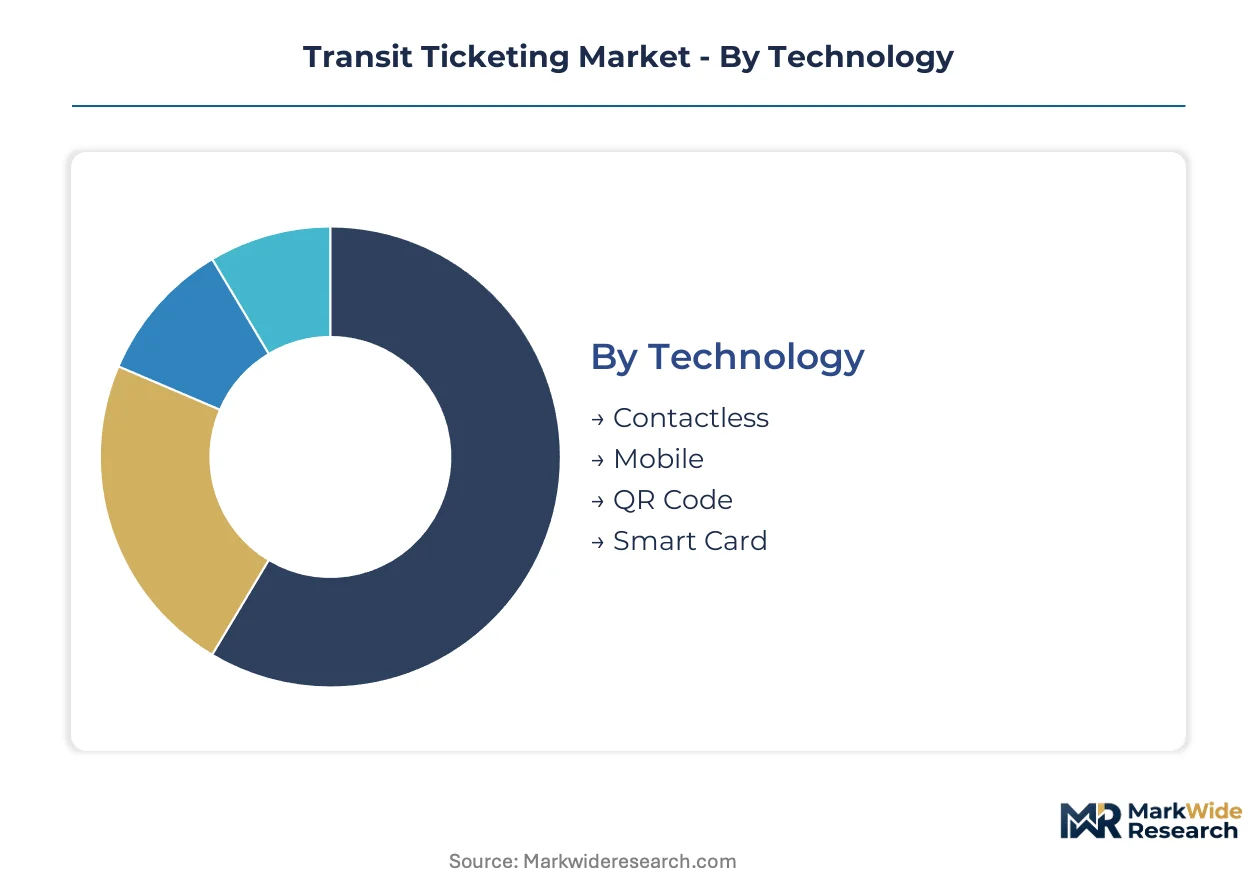
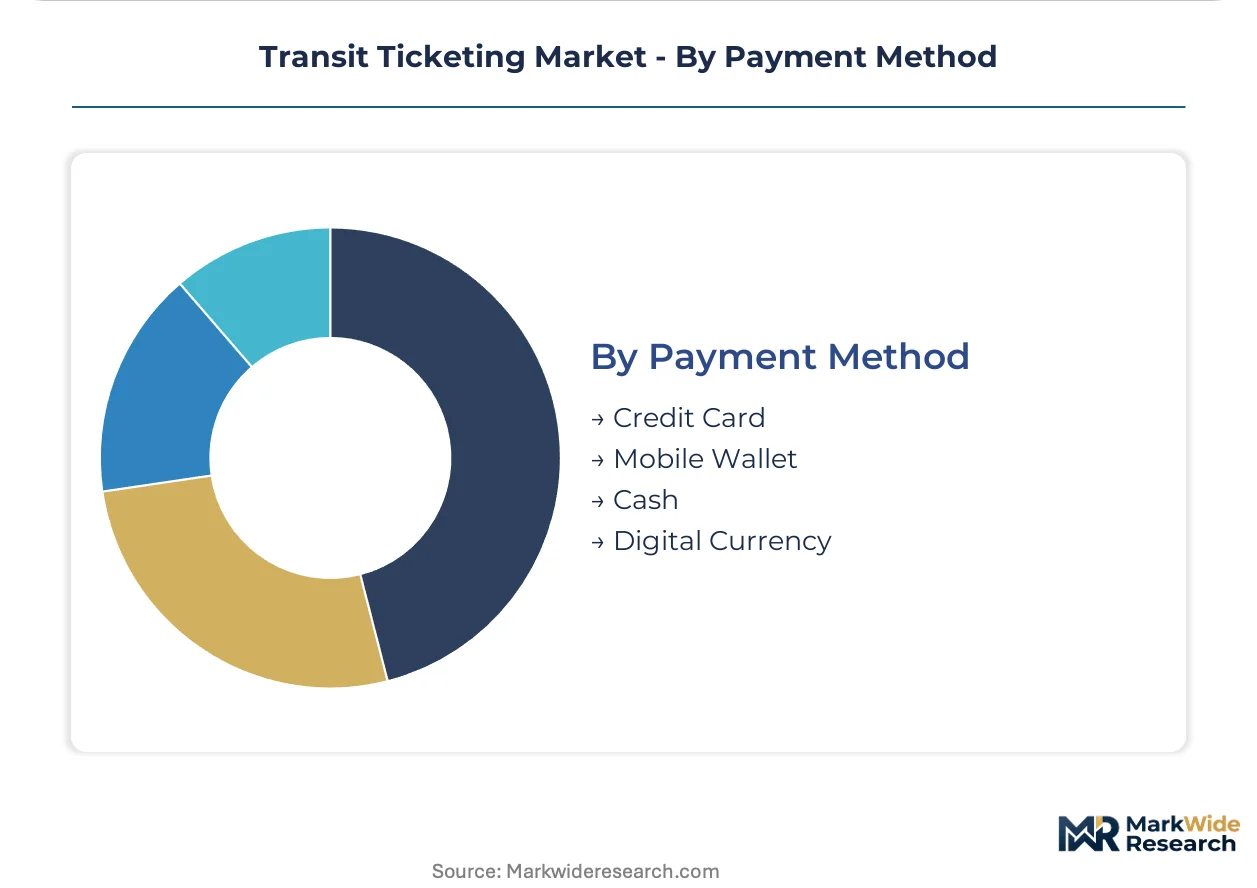
Technology choices in transit ticketing determine hardware procurement cycles, software architecture investments, and regulatory compliance pathways. Payment method fragmentation across geographies forces operators to support multiple authentication layers within unified platform stacks. End-user behavioral differences between daily commuters and occasional tourists shape fare product design and revenue recognition models.
Technology:
Cost tier differentiation separates legacy infrastructure maintenance from next-generation platform deployment across validator hardware and back-office systems.
- Contactless:ISO 14443-compliant readers with EMVCo-certified secure elements process tap-to-pay transactions at fare gates and onboard validators. London's Oyster network and Singapore's SimplyGo platform anchor concentrated demand for bank-card-ready infrastructure. PCI-DSS compliance mandates are compressing replacement timelines for older encryption modules.
- Mobile:NFC-tap and app-based barcode solutions leverage smartphone penetration density to bypass physical card distribution costs. India's National Common Mobility Card corridors and Southeast Asian urban clusters are pulling mobile adoption ahead of smart card deployment schedules. Smartphone OS fragmentation complicates validator firmware standardization.
- QR Code:Camera-based authentication enables low-cost entry for operators without NFC reader retrofit budgets.
- Smart Card:Proprietary closed-loop media sustains margin pools in legacy system maintenance contracts.
Contactless holds installed capacity. Mobile is rotating up the share rankings.
Service Type:
Application scope defines integration complexity — multimodal journey planners require API orchestration across historically siloed operator databases.
- Public Transport:Subway, bus, and rail networks constitute the core revenue base with highest transaction volume density and strictest latency requirements for fare gate throughput. China's integrated super-app platforms demonstrate scalable templates for operator consortiums. Account-based ticketing architectures are collapsing traditional closed-loop infrastructure replacement cycles.
- Parking:Off-street and curb-side payment integration attracts SaaS platform entrants seeking recurring subscription revenue outside municipal procurement cycles. Sensor-based occupancy detection and license plate recognition are converging with mobile payment workflows. Municipal budget constraints favor cloud-native deployments over on-premise hardware.
- Ride Sharing:API middleware linking transit schedules with on-demand vehicle dispatch creates white-space revenue for journey planning aggregators.
- Taxi Services:Meter-integrated payment terminals compete with driver-owned smartphone acceptance solutions.
Public Transport dominates transaction volume. Parking is climbing the fastest as platform entrants capture SaaS margins.
End User:
Customer type determines fare product bundling — subscription models for commuters versus single-journey convenience for occasional riders.
- Commuters:High-frequency daily travelers generate predictable revenue streams that justify account-based platform investments and capping mechanisms. London's fare capping and post-pay aggregation models demonstrate behavioral shifts away from prepaid season tickets. Subscription retention metrics drive operator loyalty program design.
- Tourists:Occasional visitors with unfamiliar payment credentials require simplified onboarding and multi-language interface support. Contactless bank card acceptance eliminates foreign visitor card acquisition friction. Visitor pass economics compete with retail payment convenience expectations.
- Businesses:Corporate account management and centralized billing integration support employee transit benefit programs.
- Agencies:Municipal and educational institutions negotiate volume-based pricing and consolidated reporting requirements.
Commuters anchor recurring revenue. Tourists are gaining share fastest as open-loop payment eliminates visitor onboarding friction.
Payment Method:
Volume concentration in financial infrastructure shapes validator hardware certification requirements and transaction routing economics.
- Credit Card:EMV contactless and chip-and-PIN acceptance mandates from the European Commission are forcing proprietary closed-loop system replacements. PCI-DSS compliance requirements dictate encryption module specifications and key management protocols across all geographies. Bank interchange fee structures compete with transit operator margin preservation.
- Mobile Wallet:Apple Pay, Google Pay, and regional super-app integrations are displacing physical card tap volumes in smartphone-dense urban corridors. Tokenized credential storage reduces PCI scope for transit operators. Platform dependency creates concentration risk for validator OEMs.
- Cash:Coin and note acceptance persists in unbanked population segments and legacy infrastructure maintenance contracts.
- Digital Currency:Central bank digital currency pilots and cryptocurrency acceptance remain experimental in municipal procurement frameworks.
Credit Card dominates transaction value. Mobile Wallet is expanding most quickly as tokenization reduces compliance overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Commission's Interoperable Fare Management framework anchors procurement momentum in Western Europe, while India's BIS certification program and China's MIIT standards are accelerating validator deployments across Asia-Pacific urban corridors.
United States
FCC Part 15 emissions standards govern validator hardware certification for New York MTA and Chicago Transit Authority procurements. The Federal Transit Administration's capital investment grants are co-funding contactless reader retrofits in legacy rail networks. Cubic Transportation Systems maintains installed base leverage across these major metropolitan systems.
United Kingdom
Transport for London's fare capping mechanism and Oyster network integration are demonstrating account-based ticketing at scale. The Department for Transport's open-loop payment mandates are compressing proprietary smart card replacement timelines. London's validator procurement specifications are influencing Edinburgh and Manchester system upgrades.
Germany
Deutsche Bahn's Deutschland-Ticket subscription model is forcing regional transit consortia toward unified clearing engines. The KBA's vehicle-type approval framework extends to onboard validator durability standards. Berlin-Brandenburg's Verkehrsverbund procurement is consolidating multimodal fare collection across 14 operator territories.
India
The National Common Mobility Card rollout across 25+ cities is generating concentrated demand for interoperable back-office platforms. BIS certification requirements under the Smart Cities Mission are standardizing terminal durability specifications. Mumbai Metro and Delhi Transport Corporation are anchoring validator deployment volumes in the Maharashtra and Delhi-NCR corridors.
China
MIIT's national standards for QR-code transit interoperability are binding subway and bus operators into unified payment ecosystems. Shenzhen Metro's biometric facial recognition deployment is establishing reference architecture for fare-deduct-on-entry workflows. The Yangtze River Delta integration is demonstrating super-app consolidation across Shanghai, Hangzhou, and Nanjing transit networks.
Transit Ticketing Market Competitive Landscape
Transportation integrators and semiconductor specialists split the market into capability-differentiated tiers. The vendor base concentrates around validator hardware OEMs, secure element suppliers, and cloud-native platform providers. Two dominant archetypes emerge: legacy AFC system maintainers with installed base leverage, and API-first SaaS entrants capturing MaaS integration contracts. Competitive moves center on strategic partnerships with municipal operators and vertical integration into secure element supply chains.
Within the legacy systems tier, Cubic Transportation Systems and Thales Group exemplify geographic anchoring strategies—Cubic leveraging North American rail network presence, Thales embedding European security module requirements. NXP Semiconductors occupies a position as the NFC chipset supply anchor, with EMVCo certification breadth shaping validator OEM procurement decisions. Masabi represents the cloud-native platform archetype, illustrating how API-first entrants are capturing middleware revenue pools in multimodal journey planning.
| Leading Market Players |
|---|
| Conduent |
| Cubic Transportation Systems |
| Thales Group |
| Giesecke + Devrient |
| HID Global |
| NXP Semiconductors |
| Scheidt & Bachmann |
| Infineon Technologies |
| Masabi |
| Others |
Value Network & Pricing Analysis
Single-source dependency on EMVCo-certified secure element foundries compresses validator hardware margins while simultaneously widening price spreads between premium-certified and uncertified reader tiers. This concentration dynamic forces procurement officers to accept longer lead times or pay tier-one premiums, reshaping how transit authorities structure their equipment replacement cycles and supplier qualification processes.
Pricing Analysis
Validator hardware pricing spreads widest between European Union and Indian procurement corridors, reflecting divergent certification burdens and local content requirements. Three-tier pricing structure across premium, standard, and economy levels separates PCI-DSS Level 1 certified readers from regional encryption modules and basic contactless units without bank-card acceptance. Pricing pressure stems from copper and rare earth feedstock volatility in antenna substrate production. Municipal transit authorities in emerging corridors exhibit highest price sensitivity, while established operators in London and Singapore prioritize certification breadth over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor procurement risk for NFC chipset sourcing in validator manufacturing. Taiwan, South Korea, and the Netherlands anchor secure element fabrication capacity, while China concentrates QR-code scanner module assembly. Antenna copper, ferrite substrates, and EMVCo-certified firmware licenses constitute critical input dependencies. Single-source vulnerability persists for EMVCo certification testing capacity. Distribution runs through direct OEM contracts with transit authorities and tier-one systems integrators rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment—PCI-DSS compliance mandates and national certification programs create switching costs that lock operators into validated supplier relationships across decade-long procurement cycles.
For Market Incumbents: Insulate installed base revenue by embedding API-first subscription layers that capture MaaS integration contracts before cloud-native entrants displace hardware-centric relationships. Accelerate captive production of secure element supply through backward integration into semiconductor packaging partnerships, reducing exposure to foundry concentration risk. Prioritize firmware talent retention as embedded systems engineering scarcity intensifies competition with broader IoT device markets. For New Entrants and Emerging Players: Parking payment SaaS platforms in Southeast Asian urban clusters represent the most penetrable entry point, as municipal budget constraints favor cloud-native deployments over on-premise validator hardware. India's National Common Mobility Card corridor back-office integration services offer a second white-space target, with demand concentrating in cities beyond Mumbai and Delhi-NCR. A go-to-market angle emphasizing subscription capping and post-pay journey aggregation aligns with rider behavioral shifts away from prepaid season tickets. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors cloud-native middleware providers with proven multimodal API orchestration capabilities. Long-term viability across the next decade hinges on capturing recurring SaaS revenue pools as account-based ticketing architectures displace legacy closed-loop infrastructure. Acquisition target archetype: API-first fare collection platforms with established municipal operator relationships in high-growth corridors. The signal to watch is European Commission enforcement action on open-loop payment mandates, which will accelerate replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Backward Integration | Captive NFC chipset supply reduces foundry dependency and compresses procurement lead times for validator OEMs. |
| API-First Platform Migration | Cloud-native fare logic deployment enables recurring subscription revenue capture from municipal operators. |
| MaaS Middleware Development | Multimodal journey planner integration opens white-space revenue pools beyond core transit ticketing. |
| Biometric Authentication Piloting | Facial recognition fare gates in Shenzhen and Moscow establish reference architecture for hardware refresh cycles. |
| Regional Certification Pre-Positioning | Early BIS and MIIT compliance investment secures contract eligibility in India's Smart Cities Mission corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, municipal procurement databases, EMVCo certification registries, and customs trade data for semiconductor components. Primary interviews engaged transit authority procurement directors, validator OEM product managers, secure element supplier account executives, and MaaS platform engineering leads. Bottom-up equipment deployment tracking across 25+ urban corridors triangulates against top-down market sizing from payment network transaction disclosures.
Forecast inputs incorporate technology substitution curves for contactless-to-mobile payment migration, regulatory mandate implementation timelines, and foundry capacity expansion announcements across the analysis window. Segmentation modeling spans payment method, service type, technology tier, and end-user behavioral archetype. CAGRs derive from equipment replacement cycle compression rates and SaaS revenue capture trajectories. Industry-specific inputs include NFC penetration density curves and open-loop payment mandate enforcement probability.
Practitioners should monitor European Commission Interoperable Fare Management implementation consistency, India National Common Mobility Card city rollout pace, and secure element foundry utilization rates for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Transportation Systems
Tram Systems Market
Public Transportation Systems
Demand-Responsive Transit (DRT) Market
Public Transportation Systems
Mass Transit Signage Market
Public Transportation Systems
Electric Public Transport System Market
Public Transportation Systems
Passenger Service System Market
Public Transportation Systems
Automated Fare Collection System Market
Public Transportation Systems
Municipal Vehicles Market
Public Transportation Systems
Public Transportation Dispatch Software Market
Public Transportation Systems
Taxi and Limousine Software Market
Public Transportation Systems
Transit Oriented Development Market
Public Transportation Systems
Public Transport Smart Card Market
Public Transportation Systems
Qatar Taxi Market
Public Transportation Systems
Public Transportation Software Market