
 Railway Bearing Market | 2026-2036
Railway Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
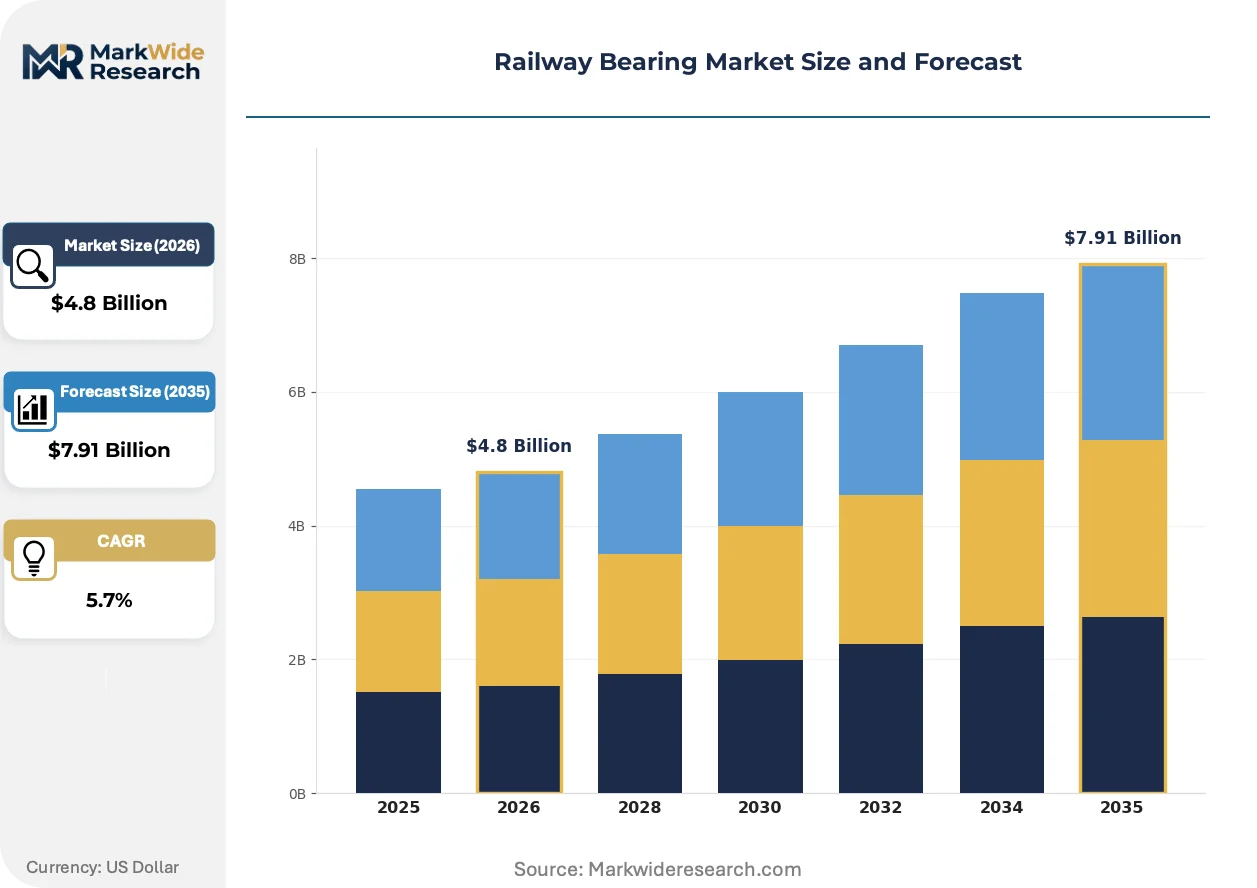
Railway Bearing Market Outlook
A shortage of certified metallurgical engineers and precision-grinding technicians is redrawing competitive boundaries across the supply base. SKF leverages its captive R&D centers in Sweden and India to sustain technology leadership in sensor-integrated bearing units. Timken Company anchors North American freight demand through backward integration into specialty steel production. Schaeffler Group competes on manufacturing scale across European passenger rail programs.
Railway bearings are precision-engineered rolling-element components designed to manage radial and axial loads in wheelsets, traction motors, and suspension systems, typically manufactured from vacuum-degassed bearing steel with hardness ratings exceeding 58 HRC and dimensional tolerances within ISO 492 Class 4 specifications. Their primary purpose is ensuring rotational accuracy, vibration damping, and extended maintenance intervals under cyclic thermal and mechanical stress. Roller bearings occupy the dominant share of product-type revenue due to load-carrying superiority in freight applications, while ceramic bearings represent the fastest-expanding material category as operators pursue weight reduction and electrical insulation. High-speed train applications command premium positioning within the application dimension, whereas freight wagon bearing demand remains volume-driven with thinner margin pools.
China's SAMR enforces GB standards for railway bearing fatigue life and dimensional interchangeability, while the EU's CE marking and MDR frameworks impose conformity requirements on safety-critical subsystems deployed in cross-border rolling stock. Japan's METI coordinates JIS standards with railway operators to mandate predictive maintenance compatibility in new bearing procurements. Stakeholders must monitor how regulatory divergence between Asian and European certification regimes affects platform standardization strategies and supplier qualification timelines.
Market Dynamics
The railway bearing market is experiencing a fundamental restructuring around predictive maintenance mandates and ceramic-composite material transitions, as operators seek to eliminate unplanned downtime while reducing axle weight for high-speed electrified networks.
Growth Catalysts
- GB Standard Fatigue Mandates:China's SAMR enforcement of upgraded bearing life certification is forcing domestic and foreign suppliers to retool metallurgical processes, accelerating technology refresh cycles across CRRC's procurement pipeline.
- Ceramic Insulation Demand:Silicon nitride hybrid bearings are penetrating traction motor applications to prevent electrical pitting damage, with Japanese Shinkansen operators specifying ceramic-rolling-element designs for new N700S series procurement.
- REACH Compliance Migration:European ECHA restrictions on hexavalent chromium surface treatments are compelling manufacturers to adopt sealed, pre-lubricated bearing units that eliminate field maintenance and extend replacement intervals.
Market Restraints
- Vacuum-Degassed Steel Concentration:Specialty bearing steel production clusters in Sweden, Japan, and select Chinese provinces, creating input vulnerability when blast furnace capacity tightens or trade flows disrupt.
- Dimensional Interchangeability Friction:Divergent GB, JIS, and EN standards for bore tolerances and outer-ring geometry prevent universal component substitution, fragmenting inventory pools and raising qualification costs for multinational suppliers.
- Magnetic Levitation Substitution:Urban maglev transit systems in Shanghai, Changsha, and Tokyo eliminate mechanical bearings entirely from propulsion subsystems, capping addressable market growth in premium passenger corridors.
Strategic Opportunities
- Sensor-Integrated Unit Penetration:Vibration and temperature monitoring modules embedded in bearing housings enable condition-based maintenance contracts, with French SNCF and German DB piloting fleet-wide telemetry retrofits.
- Indian Freight Modernization:Indian Railways' dedicated freight corridors and 25-ton axle-load wagon procurement create demand for heavy-duty spherical roller bearings that exceed legacy domestic manufacturing capability.
- EU Green Deal Alignment:Life-cycle carbon accounting requirements under CSRD and EU Green Deal technical screening criteria favor bearings with documented recycled steel content and extended service intervals, rewarding sealed-unit suppliers with verifiable durability data.
Industry Challenges
- Precision-Grinding Technician Scarcity:ISO 492 Class 4 tolerance achievement requires specialized grinding operators whose training pipelines have collapsed in Western Europe and North America, constraining quality-rated output expansion.
- Multi-Standard Certification Burden:Simultaneous GB, JIS, EN, and AAR qualification for global rolling stock platforms extends product launch timelines by 18-24 months and duplicates testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Bearing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Spherical Bearings End User: Freight Transport, Passenger Transport, Rail Maintenance Companies, OEMs Material: Steel, Ceramic, Composite, Bronze Application: Locomotives, Coaches, Freight Wagons, High-Speed Trains |
| Companies Covered | Timken Company, JTEKT Corporation, SKF, C&U, Wafangdian Bearing Group, Schaeffler Group, NTN Corporation, NKE Austria GmbH, NSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Bearing Market Strategic Shifts
Ceramic-composite materials and embedded sensor architectures are fragmenting traditional bearing procurement into performance-tiered categories, while regulatory pressure on maintenance access and chemical content accelerates sealed-unit standardization.
Silicon nitride ceramic rolling elements deliver electrical insulation and 40% density reduction versus steel equivalents, with high-speed rail operators in France and Japan specifying hybrids for inverter-fed traction motor shafts. The technology is bifurcating procurement into premium ceramic-hybrid and commodity steel-bearing tiers, compressing mid-range product positioning.
REACH Annex XVII restrictions on chromium(VI) compounds in corrosion protection coatings are eliminating open-bearing designs that require periodic regreasing and external sealing maintenance. European rolling stock OEMs are responding by mandating factory-sealed, lifetime-lubricated units with integrated labyrinth seals, transferring maintenance liability upstream to component suppliers.
Condition-monitoring service unbundling is separating hardware procurement from predictive analytics subscriptions, with infrastructure managers in Germany and Switzerland negotiating bearing-plus-telemetry packages that include algorithmic failure prediction. Channel intermediaries lacking diagnostic software capabilities are losing position to integrated suppliers with captive IoT platforms.
Railway Bearing Market Segmentation
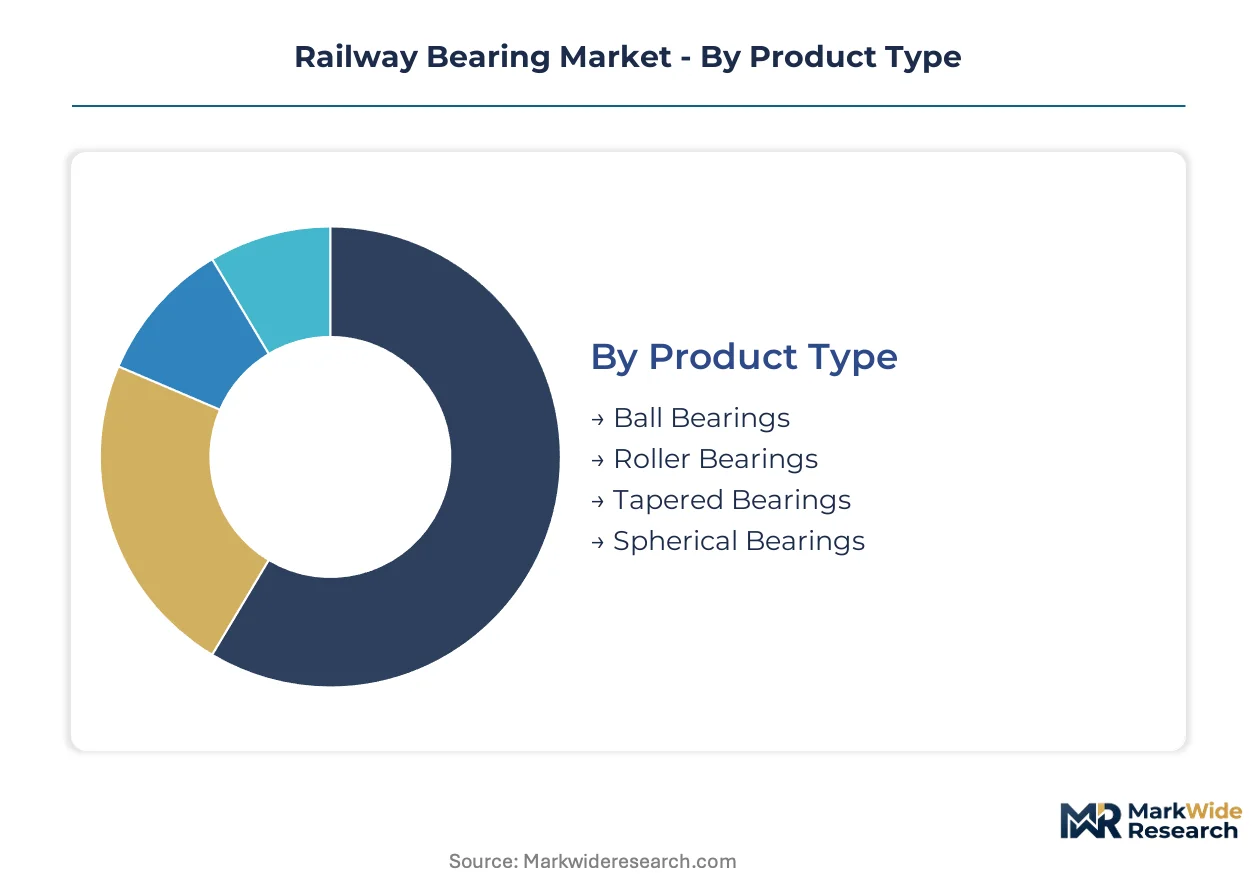
Railway bearing procurement patterns diverge sharply between domestic maintenance cycles and export-driven new build programs. Segmentation reveals how material specifications and application requirements reshape supplier qualification priorities across regional supply chains.
Product Type:
Domestic aftermarket demand concentrates on standardized roller and ball configurations, while export contracts for high-speed rolling stock specify precision-tapered and spherical variants with enhanced load distribution.
- Roller Bearings:Cylindrical and spherical roller designs manage heavy radial loads in freight axleboxes and traction motor suspensions. Chinese freight corridors and Indian 25-ton axle-load wagon programs specify these for their superior fatigue resistance under cyclic shock loading.
- Ball Bearings:Deep-groove and angular-contact configurations serve lighter-duty auxiliary systems including HVAC blowers and door mechanisms. Japanese Shinkansen maintenance depots and European commuter fleets procure these for standardized interchangeability across multiple rolling stock platforms.
- Tapered Bearings:Conical raceway geometry handles combined radial and thrust loads in wheelset applications where flange contact generates axial forces.
- Spherical Bearings:Self-aligning capability accommodates misalignment in suspension linkages and bolster connections on legacy freight wagon designs.
Roller bearings command the established base. The steepest expansion runs through tapered configurations specified for high-speed bogie retrofits.
End User:
Cost tier stratification separates capital-intensive OEM procurement from maintenance-driven aftermarket purchasing, with distinct margin structures and contract durations.
- Freight Transport:Volume-driven operators prioritize unit cost and field serviceability over premium specifications. North American Class I railroads and Russian Railways specify heavy-duty sealed units with extended regreasing intervals to minimize wayside maintenance.
- Passenger Transport:Reliability-critical applications demand predictive maintenance compatibility and documented fatigue life certification. French SNCF and German DB negotiate performance-based contracts with embedded sensor telemetry for fleet-wide condition monitoring.
- Rail Maintenance Companies:Third-party service providers source replacement bearings through competitive tender with emphasis on dimensional interchangeability and rapid availability.
- OEMs:Rolling stock manufacturers qualify suppliers through extended validation cycles, locking in multi-year supply agreements for new build programs.
Freight transport absorbs the highest unit volumes. Passenger transport generates the premium pricing tier through specification intensity.
Material:
Supply concentration for vacuum-degassed bearing steel creates input vulnerability, while ceramic sourcing fragments across specialized Japanese and European suppliers.
- Steel:Vacuum-degassed chromium-molybdenum alloys remain the baseline for 90% of installed capacity, with hardness ratings exceeding 58 HRC and through-hardened raceway durability. Swedish and Japanese steel mills supply the premium grades specified for high-speed applications.
- Ceramic:Silicon nitride rolling elements deliver electrical insulation and 40% density reduction versus steel equivalents. Japanese Shinkansen N700S series and French TGV M procurement specify ceramic hybrids for inverter-fed traction motor shafts to prevent electrical pitting damage.
- Composite:Polymer-matrix cages and reinforced retainers reduce weight in suspension linkages where inertial loads affect ride quality.
- Bronze:Leaded tin-bronze bushings persist in legacy journal bearing conversions and specialty low-speed applications.
Steel retains the volume dominance. Ceramic materials are climbing the fastest through electrified high-speed fleet procurement.
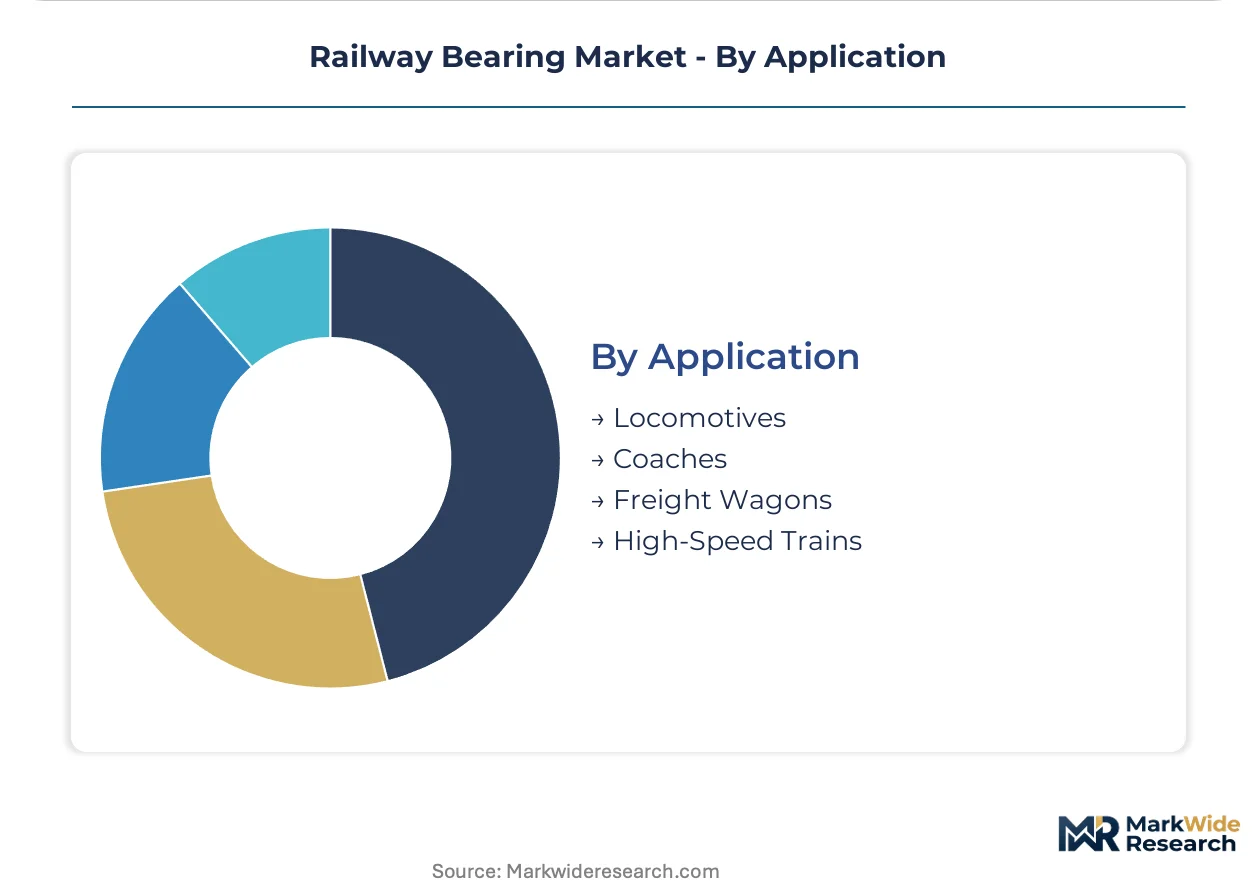
Application:
Application-driven specification divergence creates distinct supplier ecosystems, with high-speed programs demanding precision grades unavailable to freight-focused manufacturers.
- High-Speed Trains:ISO 492 Class 4 tolerances and ceramic hybrid configurations address rotational accuracy requirements above 300 km/h. Chinese CR400 series, Japanese N700S, and French TGV M programs specify these for minimized unsprung mass and thermal stability.
- Locomotives:Traction motor and gearbox bearings manage high torque transmission with contamination-resistant sealing. Indian Railways' WAG-12 electric freight locomotives and North American AC-traction rebuilds drive demand for heavy-duty spherical roller units.
- Freight Wagons:Axlebox bearings prioritize cost efficiency and field serviceability over precision, with standardized cylindrical roller designs dominating procurement.
- Coaches:Passenger car bogie bearings balance ride comfort specifications with maintenance interval extension, typically employing sealed tapered or cylindrical roller configurations.
Freight wagons represent the volume foundation. High-speed trains define the technology frontier and pricing ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes railway bearings through high-speed fleet procurement and CRRC supply chain concentration, while European operators prioritize sealed-unit specifications for cross-border interoperability, and North American demand anchors on heavy-haul freight wagon retrofits with extended maintenance intervals.
China
CRRC's procurement pipeline drives ceramic-hybrid bearing adoption for 350 km/h CR400 series trains. SAMR enforces upgraded GB standard fatigue life certification, forcing metallurgical retooling across domestic suppliers. Wafangdian and Luoyang bearing clusters concentrate precision grinding capacity for high-speed bogie specifications.
Germany
Deutsche Bahn's fleet-wide telemetry pilots create demand for sensor-integrated bearing housings with predictive maintenance compatibility. ECHA REACH Annex XVII restrictions on hexavalent chromium push manufacturers toward factory-sealed, lifetime-lubricated designs. Bavaria's industrial corridor hosts specialized suppliers qualifying for TSI certification.
Japan
Shinkansen N700S series procurement specifies silicon nitride hybrid bearings for inverter-fed traction motor shafts. METI coordinates JIS standards with JR operators to mandate predictive maintenance compatibility in new bearing contracts. Kansai and Nagoya manufacturing clusters supply ceramic rolling elements for domestic high-speed programs.
United States
Class I railroads specify heavy-duty sealed spherical roller units for 286,000-pound gross rail load operations. Federal Railroad Administration safety regulations emphasize bearing condition monitoring for wayside defect detection systems. Midwest steel production clusters supply vacuum-degassed bearing alloys for traction motor and axlebox applications.
India
Dedicated freight corridors and 25-ton axle-load wagon procurement exceed legacy domestic bearing manufacturing capability. Indian Railways' electrification push drives demand for electrically insulated ceramic-hybrid designs. Gujarat and Maharashtra industrial zones attract foreign joint ventures for heavy-duty spherical roller bearing production.
Railway Bearing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated R&D and steel-making capabilities separating premium suppliers from component assemblers. The upper tier commands qualification for high-speed and sensor-integrated specifications, while mid-scale players compete on freight wagon volume contracts. Strategic differentiation runs through backward integration into specialty steel production, captive ceramic material sourcing, and predictive maintenance service bundling. Capacity expansion and M&A activity concentrate around Indian freight modernization and European sealed-unit transitions.
Among European-integrated suppliers, Schaeffler Group and NKE Austria GmbH exemplify the scale-driven archetype with manufacturing depth across passenger rail programs. SKF anchors the technology-intensive tier through sensor-integrated bearing units. Timken Company represents North American freight specialization with upstream steel production integration. These three occupy positions that span premium specification access and regional procurement channel control.
| Leading Market Players |
|---|
| Timken Company |
| JTEKT Corporation |
| SKF |
| C&U |
| Wafangdian Bearing Group |
| Schaeffler Group |
| NTN Corporation |
| NKE Austria GmbH |
| NSK |
| Others |
Value Chain & Pricing Dynamics
Specialized grinding capacity utilization at Wafangdian and Luoyang bearing clusters creates scale economies that simultaneously elevate price floors for precision-grade units and concentrate supply leverage among qualified suppliers serving CRRC's high-speed procurement pipeline.
Pricing Analysis
Long-term offtake agreements dominate procurement between CRRC, Deutsche Bahn, and Japanese Shinkansen operators and their certified bearing suppliers, locking in volume commitments that insulate premium-tier manufacturers from spot-market volatility. Price differentiation rests on ISO 492 Class 4 certification status and ceramic-hybrid material specification, with sensor-integrated bearing housings commanding substantial premiums over commodity sealed units. Cost compression in freight wagon bearings is intensifying because Indian Railways and Russian Railways are consolidating procurement through competitive tender processes. Freight transport operators exhibit the highest price sensitivity, while high-speed rail programs prioritize fatigue life certification and predictive maintenance compatibility over unit cost.
Supply Chain Analysis
Strategic stockpiling of vacuum-degassed bearing steel prevails among European and North American manufacturers buffering against blast furnace capacity constraints in Sweden and Japan, whereas Chinese suppliers maintain leaner just-in-time inventories feeding CRRC's domestic production lines. Raw material sourcing draws from Swedish specialty steel mills, Japanese metallurgical producers, and select Chinese provinces for chromium-molybdenum alloys, while silicon nitride ceramic rolling elements feed from Kansai and Nagoya manufacturing clusters. Single-source vulnerability concentrates in premium-grade vacuum-degassed steel production. Distribution runs through rolling stock OEM direct procurement channels and third-party rail maintenance company tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through multi-standard certification burdens creates switching costs that protect incumbent positions against unqualified challengers.
For Market Incumbents: Compound technology leadership by embedding vibration and temperature monitoring modules into bearing housings to capture condition-based maintenance contracts from French SNCF and German DB fleet-wide telemetry programs. Extend backward integration into specialty steel production to secure input cost control against vacuum-degassed alloy supply volatility. Defend against magnetic levitation substitution in premium passenger corridors by emphasizing hybrid ceramic-steel configurations for electrified networks.
For New Entrants and Emerging Players: Differentiate on predictive maintenance software bundling rather than hardware commodity competition, targeting Indian freight corridor modernization where 25-ton axle-load specifications exceed legacy domestic manufacturing capability. Penetrate the aftermarket service provider segment through rapid availability guarantees and dimensional interchangeability certification. Pursue joint venture structures with Gujarat and Maharashtra industrial zones to access heavy-duty spherical roller bearing production capacity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with captive ceramic material sourcing and sensor-integrated unit portfolios over pure-play steel-bearing assemblers. Long-term viability hinges on qualification for REACH-compliant sealed designs and GB standard fatigue certification. Target acquisition archetypes include precision-grinding specialists with ISO 492 Class 4 capability and telemetry platform developers. Watch for inflection when Indian Railways electrification procurement specifies ceramic-hybrid traction motor bearings at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Hybrid Bearing Scale-Up | Silicon nitride rolling element production expansion serves Shinkansen N700S and TGV M electrified traction motor procurement. |
| Sensor-Integrated Unit Development | Embedded telemetry modules enable condition-based maintenance contracts with SNCF and DB fleet operators. |
| Backward Integration into Specialty Steel | Captive vacuum-degassed alloy production insulates Timken and integrated suppliers from Swedish and Japanese mill supply volatility. |
| REACH-Compliant Sealed Design Transition | Lifetime-lubricated bearing units eliminate hexavalent chromium surface treatments under ECHA Annex XVII restrictions. |
| Indian Joint Venture Manufacturing | Gujarat and Maharashtra production facilities address dedicated freight corridor demand exceeding domestic bearing capability. |
Study Parameters
Initial hypotheses were tested against primary input from rolling stock OEM procurement directors, railway operator maintenance executives, precision grinding facility managers, and aftermarket service provider commercial leads and refined through secondary validation against customs trade data, SEC filings from listed bearing manufacturers, railway operator annual procurement disclosures, and ISO certification registry records. Bottom-up demand modeling across high-speed train, locomotive, freight wagon, and coach applications was triangulated with top-down market sizing from supplier revenue aggregation.
Variance decomposition across the projection horizon isolated volume drivers by product type, material specification, end-user cost tier, and application performance requirement. CAGRs were derived from segmented growth trajectory analysis incorporating CRRC procurement pipeline visibility, Indian Railways electrification schedules, and European sealed-unit transition timelines. Industry-specific forecast inputs included blast furnace capacity utilization at Swedish and Japanese specialty steel mills and precision-grinding technician training pipeline recovery rates in Western Europe.
Material uncertainties — trade flow disruptions affecting vacuum-degassed steel inputs, regulatory divergence between GB and EN certification timelines, and magnetic levitation corridor expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding CRRC supply chain concentration persistence and REACH compliance migration pace. Revision becomes warranted when ceramic rolling element supply constraints or precision-grinding labor scarcity cross thresholds that delay high-speed bogie qualification cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Automated Inspection Equipment Market
Railway
Railway Rolling Stock Market
Railway
Freight Wagon Market
Railway
Europe Intermodal Terminals Market
Railway
Locomotive Market
Railway
Rail Seat Market
Railway
Tugger Trains Market
Railway
Railroads Market
Railway
Heritage Railways Trains Market
Railway
Global Hyperloop Train Market
Railway
Rolling Stock Management Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
South Korea Connected Rail Market
Railway
40-Foot Platform Wagons Market
Railway
Rail Transit Traction Converter Market
Railway
Gangway for Railway Vehicles Market