
 Bullet Train Market | 2026-2036
Bullet Train Market Size, Share, and Industry Trends Forecast 2026-2036
Bullet Train Market Analysis
Japan's F-Gas Regulation is shifting the cost-of-entry calculus for climate system suppliers in high-speed rolling stock. Siemens AG leverages its European manufacturing footprint to sustain competitive positioning across electrified corridors. CRRC Corporation Limited anchors its dominance through captive supply chains spanning bogie fabrication to signaling systems.
Bullet trains are steel-wheel-on-rail passenger systems engineered for sustained commercial speeds exceeding 250 km/h, utilizing continuous welded track, active suspension, and regenerative braking to minimize energy consumption per passenger-kilometer. High-speed rail occupies the dominant value share where electrified technology leads deployment, while maglev systems capture premium-margin projects despite narrower installed bases. Passenger transport generates the highest volume throughput, though freight-capable configurations are gaining traction in select Asian corridors.
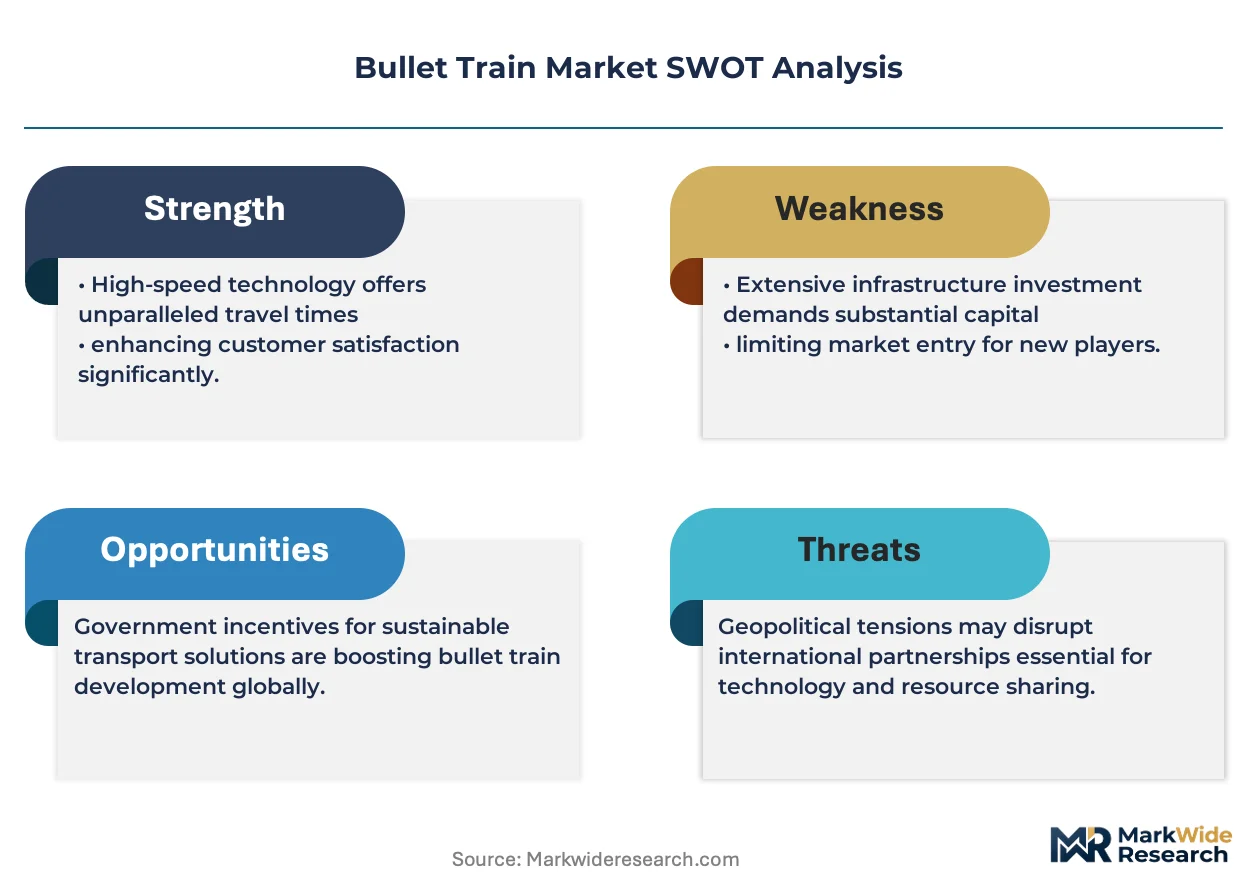
China's MIIT enforces GB standards for electromagnetic compatibility and crashworthiness that dictate supplier qualification timelines. The EU Green Deal and F-Gas Regulation jointly constrain refrigerant choices and lifecycle carbon accounting for rolling stock serving European routes. Japan's METI coordinates JIS standards with export financing mechanisms that shape competitive access across Southeast Asian tenders. Stakeholders must weigh electrification infrastructure commitments against hybrid technology flexibility as corridor-specific energy grids mature at uneven speeds.
Market Dynamics
Electrification infrastructure commitments across Asia-Pacific corridors are compressing supplier qualification timelines while fragmenting procurement authority between transport ministries and grid operators.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic rolling stock manufacturing accelerate localization of traction motor and bogie assembly capacity along the Mumbai-Ahmedabad corridor.
- Regenerative braking systems:Energy recovery technology reduces per-passenger-kilometer consumption, improving operational economics on high-frequency routes.
- Urban corridor densification:Metropolitan congestion in Chinese cities absorbs expanding fleet deployments as intercity passenger volumes shift from aviation to rail.
Market Restraints
- Specialized steel supply concentration:High-grade rail steel production clusters in select East Asian and European mills, creating input cost volatility for track infrastructure.
- Japan's F-Gas Regulation:Refrigerant phase-down mandates force climate system redesigns, extending certification cycles for cabin HVAC suppliers.
- Maglev substitution economics:Premium-margin magnetic levitation projects capture limited corridor budgets, constraining conventional high-speed rail expansion in wealthy urban zones.
Strategic Opportunities
- Southeast Asian tender pipeline:Indonesia's Java corridor and Vietnam's north-south axis present underpenetrated demand for electrified passenger systems.
- Freight-capable configurations:Select Asian operators pilot high-speed cargo services, opening application white space beyond passenger transport.
- EU Green Deal alignment:Lifecycle carbon accounting requirements create competitive differentiation for rolling stock with documented supply chain emissions.
Industry Challenges
- Electromagnetic compatibility certification:China's MIIT enforces GB standards that delay foreign supplier market entry by 18-24 months.
- Signaling system integration:Legacy trackside infrastructure requires costly retrofitting to accommodate ETCS Level 2 and equivalent protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bullet Train Market |
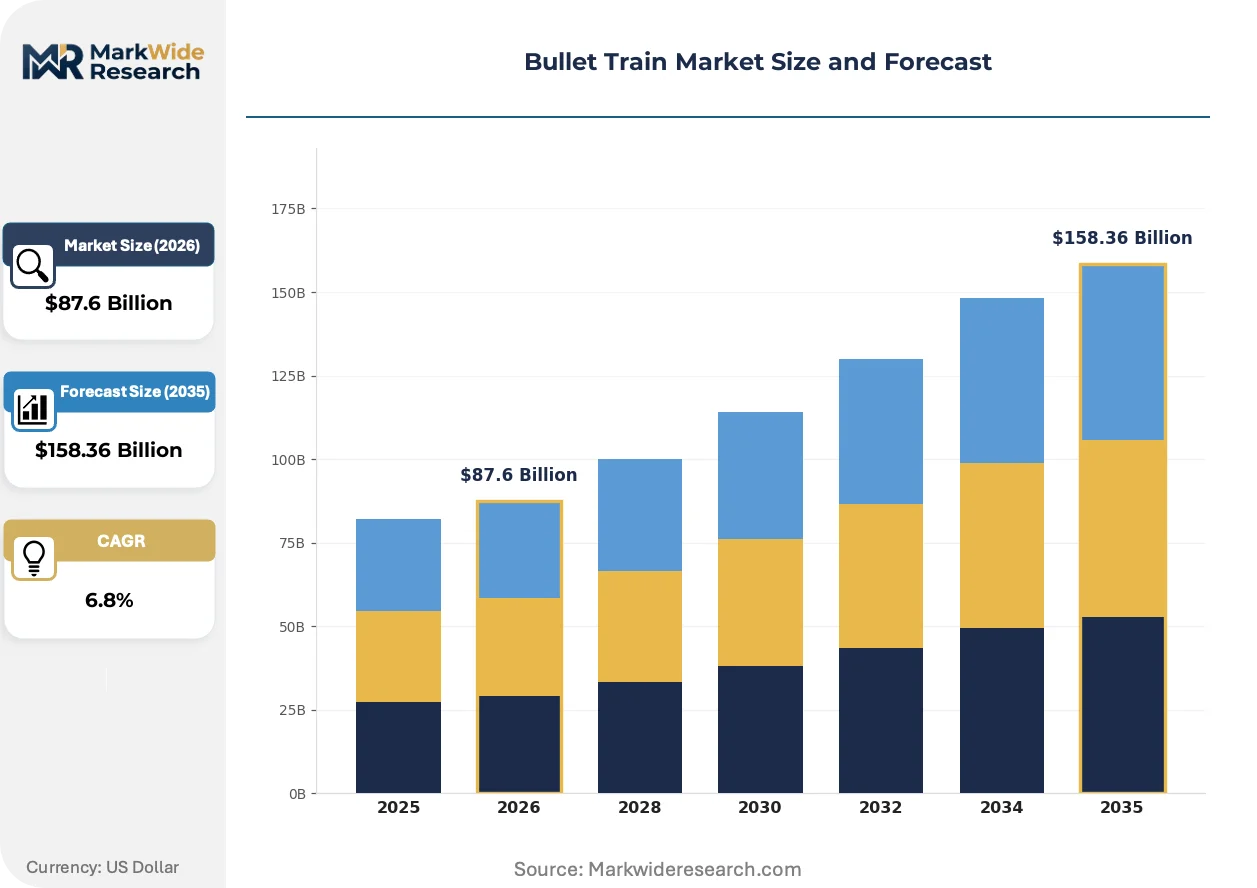
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Rail, Conventional Train, Maglev, Commuter Train Technology: Electromagnetic, Diesel, Electric, Hybrid End User: Government, Private Operators, Tourists, Logistics Companies Application: Passenger Transport, Freight Transport, Urban Transit, Intercity Travel |
| Companies Covered | Hitachi Ltd, Mitsubishi Heavy Industries Ltd, CRRC Corporation Limited, Stadler Rail, Hyundai Rotem, Alstom SA, Kawasaki Heavy Industries Ltd, CAF Construcciones y Auxiliar de Ferrocarriles, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bullet Train Market Emerging Trajectories
Active suspension and regenerative braking architectures are converging with digital signaling platforms, compressing the technology refresh cycle for rolling stock operators.
Silicon carbide traction inverters are modularizing power conversion subsystems in next-generation trainsets. Japanese and European manufacturers deploy these wide-bandgap semiconductors to reduce converter weight and thermal management overhead. The technology is modularizing supplier tiers, allowing specialized electronics firms to displace integrated drivetrain incumbents in auxiliary power markets.
Japan's METI coordinates JIS standards with export financing mechanisms that shape competitive access across Southeast Asian tenders. This regulatory-industrial linkage accelerates Japanese supplier penetration in markets where financing terms outweigh technical specifications. Rolling stock serving Indonesian and Thai corridors faces procurement criteria that privilege bundled financing packages over standalone equipment bids.
Maintenance contracting is unbundling from initial fleet procurement, with operators separating lifecycle service agreements from capital expenditure decisions. European state railways and Chinese regional operators now tender predictive maintenance platforms independently from rolling stock acquisition. This pattern concentrates most visibly in Germany's Deutsche Bahn and China's provincial rail bureaus, where asset management optimization overrides bundled vendor relationships.
Bullet Train Market Segmentation
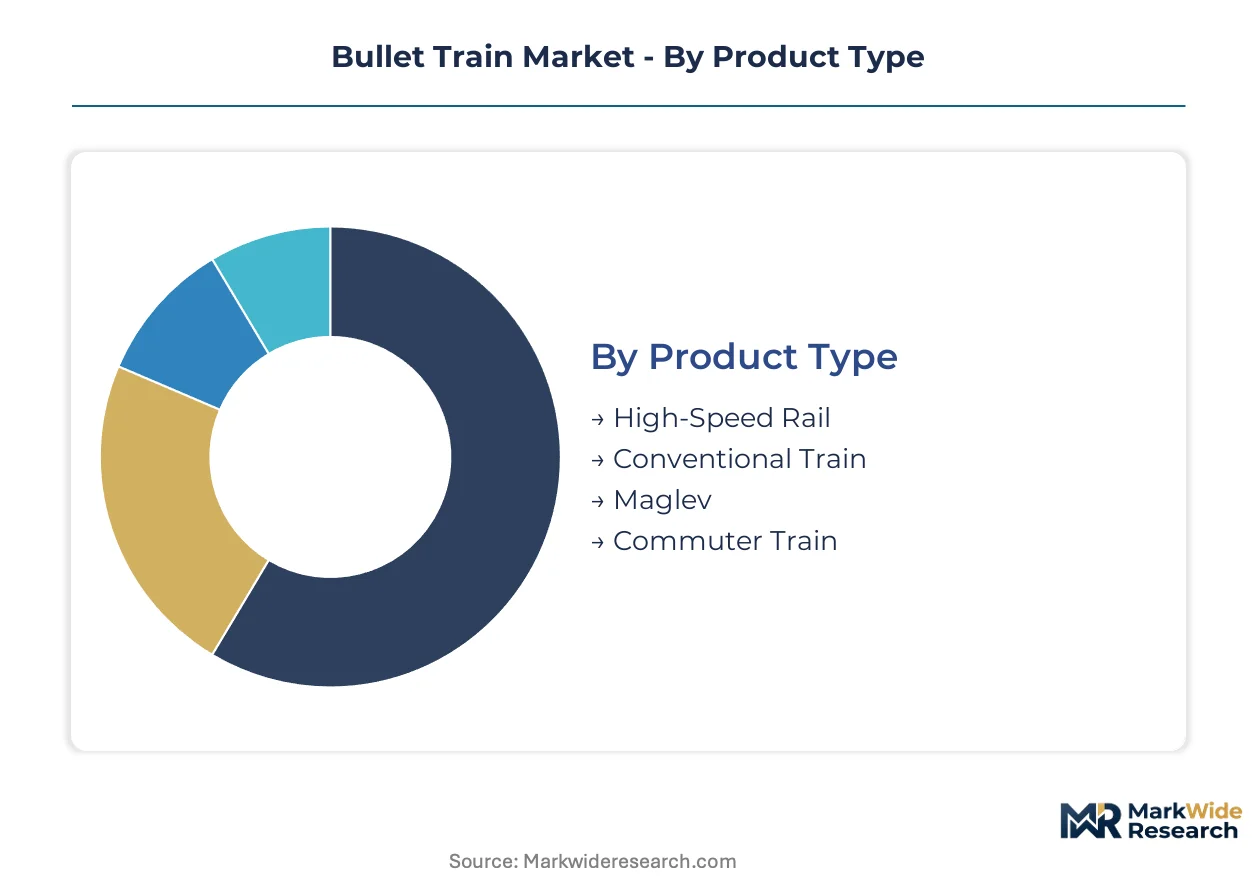
Segmentation in the bullet train market exposes how procurement authority fragments between transport ministries and grid operators across electrified corridors. Supplier qualification timelines compress where technology choices lock in decades of infrastructure commitment.
Product Type:
Supply concentration in rolling stock manufacturing clusters around integrated drivetrain and signaling system capabilities.
- High-Speed Rail:Steel-wheel-on-rail systems engineered for sustained commercial speeds exceeding 250 km/h utilize continuous welded track and active suspension architectures. China's MIIT enforces GB standards for electromagnetic compatibility that dictate supplier qualification timelines across domestic corridors.
- Maglev:Magnetic levitation technology eliminates wheel-rail contact through electromagnetic suspension, enabling premium-margin projects in wealthy urban zones despite narrower installed bases. Japan's METI coordinates JIS standards with export financing mechanisms that shape competitive access across Southeast Asian tenders.
- Conventional Train:Legacy diesel-electric and electric multiple units serve lower-speed corridors where infrastructure upgrade cycles lag.
- Commuter Train:High-frequency regional services absorb metropolitan passenger volumes shifting from aviation to rail in Chinese cities.
High-Speed Rail absorbs the bulk of installed capacity; Maglev is expanding most quickly in corridor budgets.
Technology:
Cost tier differentiation separates mature electrification from hybrid flexibility as energy grids mature at uneven speeds.
- Electric:Overhead catenary and third-rail systems dominate where grid infrastructure supports continuous power delivery. India's PLI scheme accelerates localization of traction motor capacity along the Mumbai-Ahmedabad corridor.
- Hybrid:Dual-mode configurations combine electrified operation with onboard diesel or battery reserves for non-electrified segments. European state railways pilot these systems where ETCS Level 2 retrofitting costs constrain full electrification.
- Electromagnetic:Linear motor propulsion enables maglev deployment through guideway-integrated stator windings.
- Diesel:Compression-ignition powertrains persist in corridors where electrification infrastructure commitments remain unfunded.
Electric technology captures the dominant value share; Hybrid configurations are climbing the fastest where grid maturity lags corridor development.
End User:
Customer type fragmentation concentrates procurement authority differently across state-backed and commercial operators.
- Government:National transport ministries and regional rail bureaus dominate fleet acquisition through sovereign-backed financing. China's provincial rail bureaus now tender predictive maintenance platforms independently from rolling stock acquisition.
- Private Operators:Commercial concessionaires and special purpose vehicles operate under build-operate-transfer frameworks. Indonesia's Java corridor and Vietnam's north-south axis present underpenetrated demand for these entities.
- Tourists:Premium service tiers target leisure travel on scenic corridors with differentiated amenity packages.
- Logistics Companies:Freight-capable configurations attract pilot interest for high-speed cargo services beyond passenger transport.
Government end users absorb the bulk of installed capacity; Private Operators are gaining share fastest in Southeast Asian tender pipelines.
Application:
Volume concentration tracks urban corridor densification and the modal shift from aviation to rail.
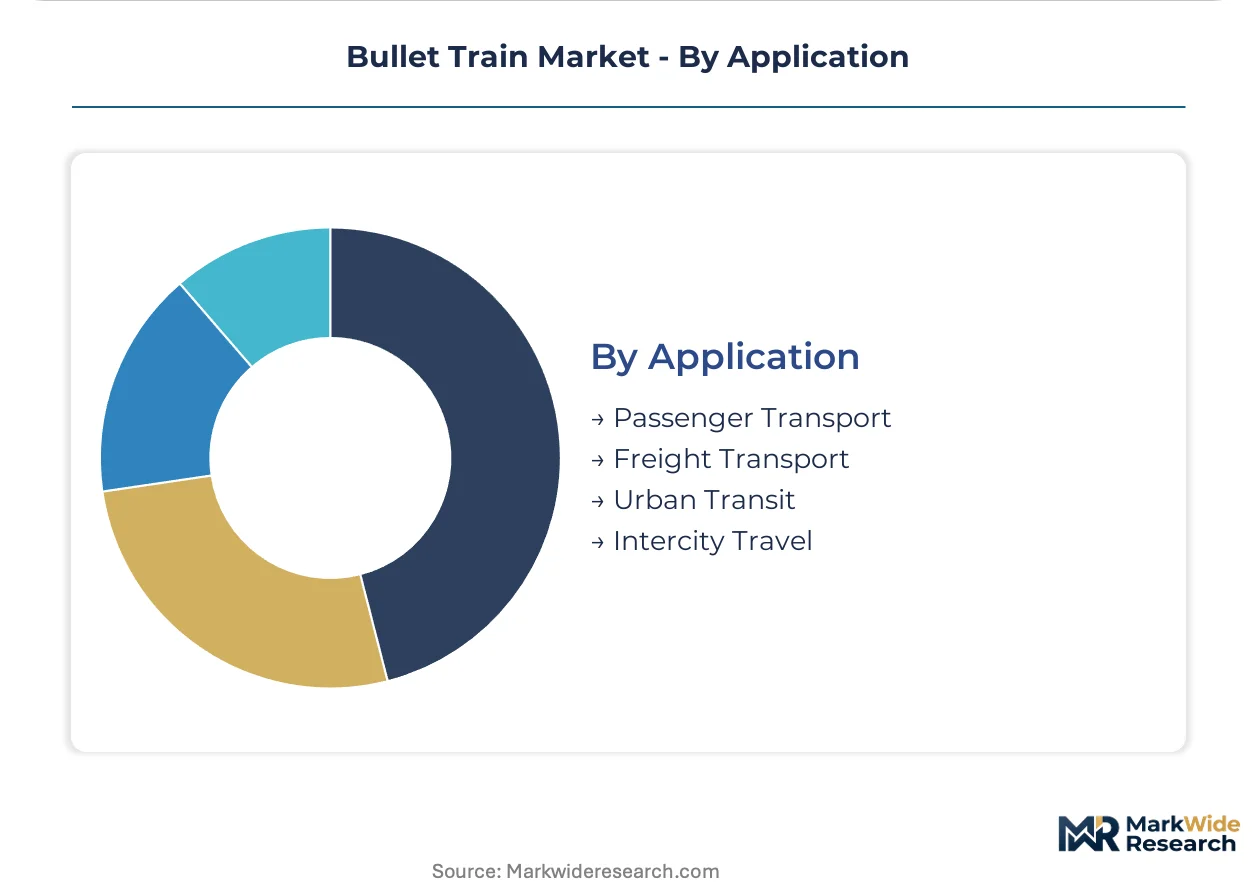
- Passenger Transport:Intercity and commuter services generate the highest volume throughput across electrified networks. Metropolitan congestion in Chinese cities absorbs expanding fleet deployments.
- Urban Transit:High-frequency metro and regional express services connect metropolitan cores with peripheral clusters. Regenerative braking systems reduce per-passenger-kilometer consumption on these routes.
- Freight Transport:High-speed cargo configurations pilot in select Asian corridors where time-sensitive logistics demand rail alternatives.
- Intercity Travel:Long-haul services compete directly with aviation on corridors under four hours duration.
Passenger Transport absorbs the bulk of installed capacity; Freight Transport is expanding most quickly in application white space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones concentrate rolling stock manufacturing capacity alongside electrified corridor development. Japan's technology licensing zones anchor export-oriented production clusters. India's dedicated freight corridors and production-linked incentive zones reshape supplier localization patterns across South Asia.
China
Urban corridor densification in Beijing, Shanghai, and Guangzhou absorbs expanding fleet deployments as intercity passenger volumes shift from aviation to rail. MIIT enforces GB standards for electromagnetic compatibility and crashworthiness that dictate supplier qualification timelines. The Yangtze River Delta manufacturing cluster anchors CRRC Corporation Limited's captive supply chains spanning bogie fabrication to signaling systems.
Japan
Metropolitan congestion around Tokyo and Osaka sustains demand for high-frequency commuter services on the Shinkansen network. METI coordinates JIS standards with export financing mechanisms that shape competitive access across Southeast Asian tenders. The Kansai industrial corridor hosts integrated manufacturing facilities where Hitachi Ltd and Kawasaki Heavy Industries Ltd concentrate traction motor and active suspension production.
India
The Mumbai-Ahmedabad corridor drives government-backed electrification and fleet deployment under sovereign financing structures. India's PLI scheme accelerates localization of traction motor and bogie assembly capacity through production-linked incentives. Gujarat's manufacturing zones attract component suppliers positioning for dedicated freight corridor contracts.
Germany
Deutsche Bahn's predictive maintenance platform tenders separate lifecycle service agreements from capital expenditure decisions, reshaping supplier relationships. The EU Green Deal and F-Gas Regulation jointly constrain refrigerant choices and lifecycle carbon accounting for rolling stock serving European routes. Siemens AG leverages its manufacturing footprint across Bavaria and North Rhine-Westphalia to sustain competitive positioning in electrified corridor projects.
South Korea
The Seoul-Busan corridor expansion sustains domestic fleet renewal programs while export tenders target Southeast Asian markets. National rail modernization programs prioritize ETCS Level 2 signaling integration for cross-border compatibility. Hyundai Rotem anchors production in the Changwon industrial complex, supplying domestic operators and bidding on Indonesian and Vietnamese corridor projects.
Bullet Train Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers and geographic markets. The vendor base clusters around three strategic archetypes: integrated rolling stock manufacturers with captive signaling capabilities, component specialists in traction and braking systems, and state-backed national champions with preferential domestic access. Competitive moves concentrate on strategic partnerships for corridor-specific financing packages and technology licensing agreements that accelerate market entry timelines.
Among Japanese industrial conglomerates, Hitachi Ltd and Mitsubishi Heavy Industries Ltd exemplify the integrated systems archetype, combining rolling stock manufacturing with digital signaling platforms. CRRC Corporation Limited represents the state-backed national champion model, leveraging scale advantages across domestic corridor deployments. Alstom SA and Siemens AG occupy positions within the European diversified technology tier, competing on lifecycle carbon accounting and EU regulatory alignment.
| Leading Market Players |
|---|
| Hitachi Ltd |
| Mitsubishi Heavy Industries Ltd |
| CRRC Corporation Limited |
| Stadler Rail |
| Hyundai Rotem |
| Alstom SA |
| Kawasaki Heavy Industries Ltd |
| CAF Construcciones y Auxiliar de Ferrocarriles |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
High-grade rail steel price indices cascade through bullet train procurement tiers, compressing margins for track infrastructure suppliers while elevating premiums for rolling stock manufacturers with captive metallurgical capacity. China's Yangtze River Delta manufacturing clusters absorb these input cost fluctuations through backward integration into specialty steel production, insulating domestic suppliers from spot market volatility that strains European and Japanese competitors.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations where government-backed corridor deployments face compressed qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates integrated system suppliers with signaling capabilities from component specialists and state-backed national champions. Pricing pressure stems from India's PLI scheme localization mandates, which force foreign suppliers to absorb technology transfer costs or cede share to domestic assembly operations. State transport ministries exhibit lowest price sensitivity due to sovereign financing structures, while private concessionaires in Southeast Asian tenders demand aggressive lifecycle cost guarantees.
Supply Chain Analysis
Refurbishment flows for traction motors and bogie assemblies concentrate in China's Changzhou and Germany's Nuremberg industrial zones, creating secondary supply streams that compete with original equipment channels. High-grade rail steel production draws from Japan, Germany, and China; silicon carbide wafers for traction inverters rest on Taiwanese and South Korean semiconductor fabrication; advanced composites for lightweight carbody construction hinge on Japanese and European specialty chemical suppliers. Single-source vulnerability permeates electromagnetic compatibility certification testing, where China's MIIT-accredited laboratories control access to domestic corridor markets. Distribution runs through state rail bureaus and special purpose vehicle concessionaires, with maintenance contracting unbundling from initial fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bullet train market is becoming a vertical-integration race where control over traction inverter and signaling system supply determines margin capture. Players are pursuing backward integration into silicon carbide semiconductor fabrication and predictive maintenance software platforms to lock in recurring revenue streams.
For Market Incumbents: Lock in supplier qualification timelines by pre-certifying rolling stock configurations across multiple regulatory regimes simultaneously. Siemens AG and Alstom SA should deepen captive supply of silicon carbide traction components before Japanese electronics specialists displace integrated drivetrain incumbents in auxiliary power markets. METI-coordinated financing bundles in Southeast Asia threaten European competitive positioning where standalone equipment bids face structural disadvantage.
For New Entrants and Emerging Players: Private concessionaires in Indonesia's Java corridor and Vietnam's north-south axis represent the most penetrable buyer archetype, as these entities prioritize bundled financing packages over technical specifications. Component specialists should target predictive maintenance platform tenders that Chinese provincial rail bureaus and Germany's Deutsche Bahn now separate from capital expenditure decisions. A go-to-market angle anchored in lifecycle carbon accounting documentation aligns with EU Green Deal procurement criteria.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electronics specialists with silicon carbide traction inverter capabilities in South Korea and Taiwan, where modularization of power conversion subsystems is displacing integrated drivetrain incumbents. Long-term viability across the projection horizon rests on positioning for freight-capable configuration pilots in Asian corridors. Practitioners should monitor ETCS Level 2 signaling retrofitting commitments across European state railways as an inflection indicator for maintenance contracting unbundling velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Fabrication | Taiwanese semiconductor specialists displace integrated drivetrain incumbents in traction auxiliary markets. |
| Predictive Maintenance Platform Development | Deutsche Bahn's unbundled tendering patterns concentrate asset management optimization with independent software vendors. |
| Multi-Regime Pre-Certification Investment | Simultaneous GB standards and JIS alignment compresses 18-24 month MIIT qualification delays for foreign suppliers. |
| Freight-Capable Configuration Piloting | High-speed cargo services in Asian corridors open application white space beyond passenger transport saturation. |
| Lifecycle Carbon Accounting Documentation | EU Green Deal alignment creates competitive differentiation for rolling stock with verified supply chain emissions. |
Methodological Framework
Document review covered regulatory filings from China's MIIT, Japan's METI, and India's Ministry of Railways, complemented by interviews with rolling stock procurement directors at state rail bureaus, signaling system integration engineers, and predictive maintenance platform specialists. Secondary validation drew from customs trade data on high-grade rail steel flows, ETCS implementation databases, and production-linked incentive scheme disclosures. Bottom-up triangulation across corridor-specific deployment schedules intersected with top-down market sizing anchored in electrification infrastructure commitment announcements.
Cross-referencing historical fleet deployment patterns against expert panel inputs on technology refresh cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, signaling protocol tier, end-user financing structure, and corridor-specific grid maturity. CAGRs emerged from elasticity analysis of passenger-kilometer demand against aviation modal shift velocities and urban corridor densification trajectories. Forecast inputs incorporated regenerative braking adoption curves and silicon carbide traction inverter penetration assumptions.
Revisions become necessary when electromagnetic compatibility certification timelines extend beyond modeled parameters or when maglev substitution economics shift corridor budget allocations unexpectedly. Practitioners should monitor F-Gas Regulation refrigerant phase-down implementation and Southeast Asian tender financing package structures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Road-Rail Vehicles Market
Railway
Railway Engine Market
Railway
Global Hyperloop Train Market
Railway
Rail Damper Market
Railway
Railway Draft Gears Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Rolling Stock Management Market
Railway
Gangway for Railway Vehicles Market
Railway
Railroads Market
Railway
India Rail Freight Transport Market
Railway
Railroad Brake Shoe Market
Railway
Gearbox for Rail Vehicles Market
Railway
Locomotive Parking Brake Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Railway Buffer Stops Market
Railway
Rail Brace Market