
 South America Electric Vehicles Market | 2026-2036
South America Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicles Market Analytics
Brazil is narrowing its manufacturing deficit through localized battery assembly partnerships and component sourcing agreements. BYD leverages its integrated cell-to-pack production to secure cost advantages across Latin American markets. Volkswagen sustains engineering investments adapted to regional temperature extremes and altitude variations. Chery Group anchors its regional strategy through dedicated assembly lines in São Paulo state.
South America electric vehicles encompass battery electric, plug-in hybrid, fuel cell, and hybrid configurations powered by lithium-ion, nickel-metal hydride, solid-state, or lead-acid storage systems, with electric drivetrains converting stored energy to mechanical propulsion through permanent magnet or induction motors. Battery electric vehicles dominate unit volumes where government procurement rules favor zero tailpipe emissions, while plug-in hybrid systems retain structural importance in Andean markets where charging infrastructure remains sparse across mountain corridors. Corporate fleet segments concentrate margin pools due to predictable utilization patterns and bulk service contracts, whereas individual consumer demand tracks home charging availability and electricity tariff structures.
Brazil's ANFAVEA emissions protocols, Chile's Ministry of Energy decarbonization mandates, and Argentina's national automotive regulator standards collectively shape product homologation requirements and import duty classifications across the region. These frameworks determine which powertrain configurations qualify for tax exemptions and which battery chemistries meet local content thresholds. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and unilateral national incentive programs to anticipate compliance cost trajectories.
Market Dynamics
Corporate fleet electrification in Brazil and Chile is compressing payback periods for battery electric buses and light commercial vehicles, pulling forward capital deployment timelines that previously favored diesel alternatives.
Growth Catalysts
- ANFAVEA Emissions Protocols:Brazil's automotive industry association mandates tighten annually, disqualifying conventional powertrains from preferential financing and procurement pools.
- Andean Altitude Engineering:Powertrain adaptations for 3,000-meter-plus elevations unlock previously inaccessible municipal bus routes across Peru and Bolivia.
- Lithium Triangle Proximity:Argentina, Chile, and Bolivia's combined brine reserves position regional cell assembly for localized content advantages under Mercosur trade rules.
Market Restraints
- Cobalt and Lithium Price Volatility:Cathode material cost swings transmit directly to fleet procurement budgets, freezing multi-year contract negotiations.
- Charging Infrastructure Gaps:Mountain corridor coverage remains sparse between Santiago and Mendoza, trapping vehicles in urban catchments.
- Import Duty Regime Uncertainty:Unilateral national incentive programs diverge from Mercosur harmonization talks, fragmenting compliance pathways.
Strategic Opportunities
- Colombia's Atlantic Coast Corridors:Cartagena-Barranquilla freight routes lack electrified alternatives, creating first-mover positioning for regional logistics operators.
- Vehicle-to-Grid Integration:Bidirectional charging hardware converges with Brazil's distributed generation framework, enabling fleet operators to monetize stationary storage.
- Argentina's Zero-Emission Powertrain Thresholds:New national automotive regulator standards accelerate homologation pathways for fuel cell configurations in heavy-duty segments.
Industry Challenges
- High-Voltage Technician Scarcity:Service networks across São Paulo state lack certified personnel for battery pack diagnostics and thermal management repair.
- Homologation Timeline Compression:Simultaneous compliance with Chile's Ministry of Energy decarbonization mandates and Brazil's ANFAVEA protocols strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicles Market |
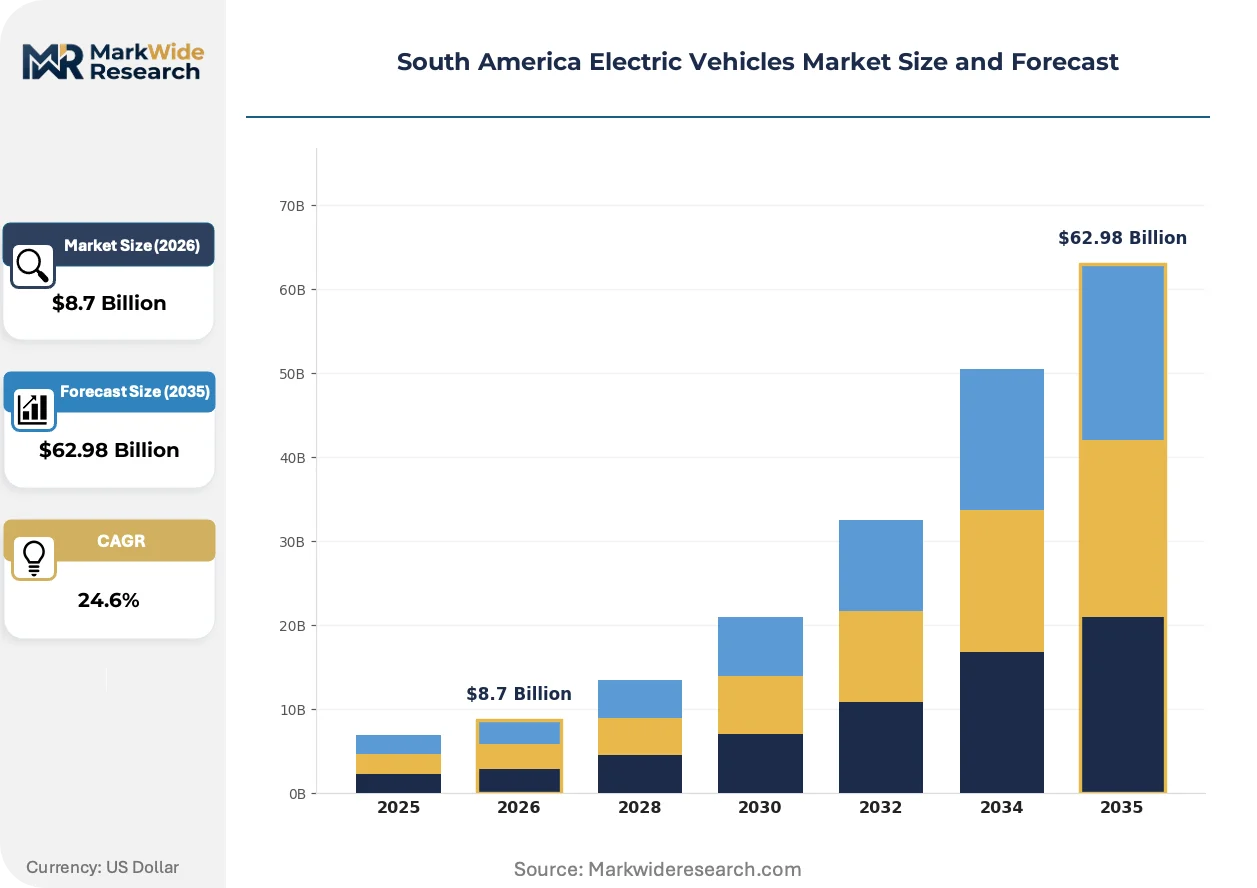
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
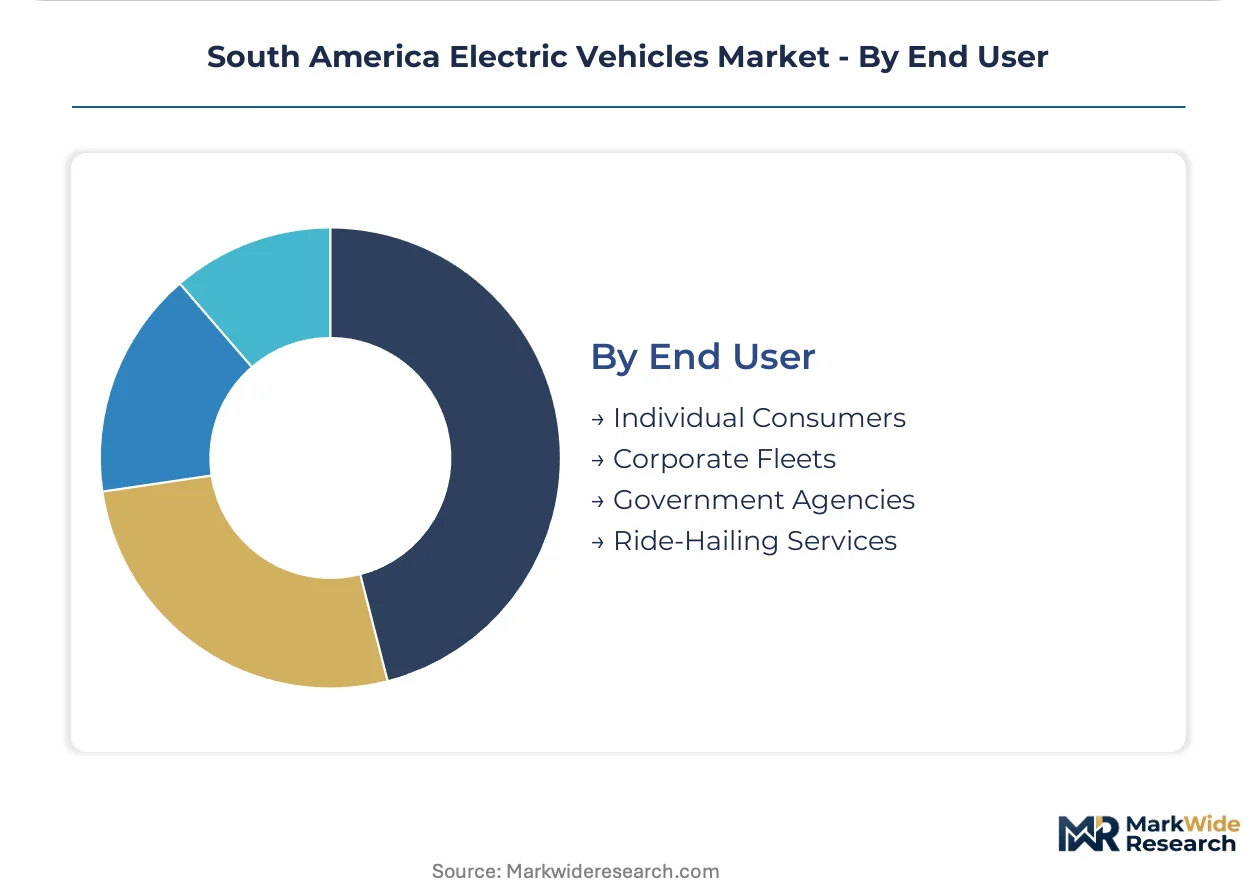
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Hybrid Electric Vehicle Battery Technology: Lithium-ion, Nickel-Metal Hydride, Solid-State, Lead-Acid Charging Infrastructure: Public Charging Stations, Home Charging Solutions, Fast Chargers, Superchargers End User: Individual Consumers, Corporate Fleets, Government Agencies, Ride-Hailing Services |
| Companies Covered | Chery Group, Volkswagen, BYD, Eletra, Chevrolet, Great Wall Motor (GWM), MG Motor, Renault, Geely, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicles Market Evolving Landscape
Telematics integration and predictive maintenance platforms are rewiring how fleet operators calculate total cost of ownership, shifting valuation frameworks from upfront capital to lifecycle operational metrics.
Cell-to-pack battery architectures are digitizing thermal management and state-of-health monitoring across Brazilian and Chilean electric bus fleets. Municipal transit authorities in São Paulo and Santiago are specifying these configurations in tender documents. The technology is digitizing warranty risk allocation, transferring predictive maintenance obligations from operators to cell suppliers.
Argentina's national automotive regulator has introduced emissions thresholds that favor zero-emission powertrains in commercial vehicle categories. The framework compresses homologation timelines for battery electric configurations while extending compliance windows for hybrid alternatives. Heavy-duty manufacturers are responding by accelerating fuel cell pilot programs in Mendoza and Córdoba provinces.
Fleet procurement departments are consolidating vendor relationships around integrated service contracts that bundle vehicles, charging infrastructure, and energy management. This aggregation displaces fragmented sourcing across separate equipment and utility providers. The pattern concentrates contract values in Brazil's São Paulo metropolitan corridor and surrounding industrial states.
South America Electric Vehicles Market Segmentation

Segmentation in South America electric vehicles reveals how powertrain configurations, battery chemistries, and charging modalities align with distinct procurement budgets and utilization patterns across the Andean corridor and Atlantic coastlines.
Vehicle Type:
Mature configurations dominate municipal procurement pools while emerging alternatives carve niches in altitude-challenged corridors and long-haul freight routes.
- Battery Electric Vehicle:Pure-electric drivetrains with lithium-ion cell-to-pack architectures deliver zero tailpipe emissions. São Paulo metropolitan transit authorities specify these in bulk tender documents for urban bus routes where depot charging infrastructure already exists.
- Plug-in Hybrid Electric Vehicle:Dual-powertrain systems combine internal combustion range extension with electric-only urban operation. Chilean corporate fleets in Santiago-Valparaíso corridors deploy these where mountain charging gaps strand pure-electric alternatives.
- Fuel Cell Electric Vehicle:Hydrogen-fed proton exchange membrane stacks suit heavy-duty segments with extreme range requirements. Argentina's national automotive regulator has accelerated homologation pathways for these configurations in Mendoza province freight corridors.
- Hybrid Electric Vehicle:Non-plug-in electric assist systems capture regenerative braking energy without grid dependency. Brazilian individual consumers in industrial states select these as bridging technology during home charging infrastructure buildout.
Battery Electric Vehicle handles the majority of throughput; Fuel Cell Electric Vehicle is the fastest mover on share.
Battery Technology:
Cost tiers separate established mass-production chemistries from next-generation architectures still scaling manufacturing yields.
- Lithium-ion:NMC and LFP cathode formulations power the installed base across Brazilian and Chilean electric bus fleets. BYD leverages integrated cell-to-pack production to secure cost advantages in Latin American markets through localized assembly partnerships.
- Solid-State:Ceramic or polymer electrolyte architectures promise energy density improvements and thermal stability gains. Early pilot deployments are concentrating in high-altitude municipal routes across Peru where reduced cooling loads offset premium pricing.
- Nickel-Metal Hydride:Mature chemistry retains cost advantages in mild-hybrid auxiliary power applications. Toyota and Honda legacy hybrid platforms continue sourcing these for Brazilian assembly lines under Mercosur content rules.
- Lead-Acid:Flooded and AGM variants persist in low-speed electric utility vehicles and aftermarket replacement cycles. Argentine industrial state logistics operators specify these for warehouse yard tractors where capital constraints outweigh energy density requirements.
Lithium-ion commands the dominant cost tier; Solid-State is climbing the fastest as manufacturing scales.
Charging Infrastructure:
Application context determines whether utilization patterns favor centralized public investment or distributed private installation.
- Public Charging Stations:AC Level 2 and DC fast charger networks deployed along federal highway corridors and municipal streetscapes. Brazil's ANFAVEA emissions protocols tie preferential fleet financing to documented public charging accessibility in São Paulo state.
- Home Charging Solutions:Residential wall-mounted AC units leveraging overnight dwell periods for slow replenishment. Individual consumer demand tracks electricity tariff structures and distributed generation frameworks enabling solar-battery-vehicle integration.
- Fast Chargers:DC rapid replenishment hardware compressing stop durations for commercial route operators. Chile's Ministry of Energy decarbonization mandates specify minimum fast charger density along Santiago-Mendoza freight corridors.
- Superchargers:Ultra-high-power DC infrastructure enabling sub-30-minute replenishment for premium passenger segments. Sparse deployment concentrates in São Paulo and Santiago metropolitan cores where real estate and grid upgrade costs justify throughput economics.
Public Charging Stations anchor the installed base; Fast Chargers are expanding most quickly on route electrification mandates.
End User:
Customer type stratifies around procurement scale, predictability of utilization, and access to captive charging infrastructure.
- Corporate Fleets:Predictable route patterns and bulk service contracts enable total cost of ownership optimization through telematics integration. Brazilian logistics operators in the São Paulo metropolitan corridor consolidate vendor relationships around integrated vehicle-charging-energy bundles.
- Government Agencies:Municipal transit authorities and federal procurement pools specify zero-emission powertrains through tender documents with local content thresholds. Argentina's national automotive regulator emissions protocols accelerate homologation for qualifying configurations.
- Individual Consumers:Dispersed demand tracks home charging availability, electricity tariff structures, and financing access. Andean altitude engineering adaptations unlock previously inaccessible markets across Peru and Bolivia for passenger categories.
- Ride-Hailing Services:High-utilization urban mobility platforms prioritize total cost per kilometer and rapid replenishment capability. Colombian Atlantic coast corridor operators in Cartagena-Barranquilla routes evaluate electrified alternatives against diesel baselines.
Corporate Fleets concentrate margin pools through scale procurement; Government Agencies are gaining share fastest on regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery assembly partnerships concentrate manufacturing momentum in São Paulo state, while lithium brine reserves across Argentina, Chile, and Bolivia anchor upstream material sourcing for regional cell production.
Brazil
Corporate fleet procurement in the São Paulo metropolitan corridor drives battery electric bus deployment, with ANFAVEA emissions protocols disqualifying conventional powertrains from preferential financing pools. Localized cell-to-pack assembly partnerships narrow manufacturing deficits through component sourcing agreements with Chinese technology providers.
Chile
Ministry of Energy decarbonization mandates compress payback periods for light commercial vehicle electrification, pulling forward capital deployment timelines. Santiago-Valparaíso corridor operators deploy plug-in hybrid systems where mountain charging gaps strand pure-electric alternatives.
Argentina
The national automotive regulator's zero-emission powertrain thresholds accelerate homologation pathways for fuel cell configurations in Mendoza province freight corridors. Heavy-duty manufacturers pilot hydrogen-fed systems to exploit extended compliance windows for commercial vehicle categories.
Colombia
Atlantic coast logistics operators evaluate electrified alternatives for Cartagena-Barranquilla freight routes lacking existing charging infrastructure. Ride-hailing platforms in coastal urban centers prioritize total cost per kilometer calculations against diesel baselines.
Peru
High-altitude municipal bus routes above 3,000 meters unlock demand for powertrain adaptations with reduced cooling loads. Solid-state battery pilot deployments concentrate in Andean corridors where thermal stability gains offset premium pricing structures.
South America Electric Vehicles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and thermal management subsystems. The market structures around three archetypes: integrated automotive conglomerates with regional assembly footprints, dedicated electric vehicle pure-plays leveraging battery verticalization, and commercial vehicle specialists adapting powertrains for altitude and duty-cycle extremes. Competitive moves concentrate on strategic partnerships for localized content compliance and capacity expansion in lithium triangle proximity.
Within the integrated automotive tier, Volkswagen and Chery Group exemplify divergent regional strategies. BYD anchors the pure-play archetype through cell-to-pack production integration. Eletra represents the commercial vehicle specialist position with altitude-engineered configurations for Andean municipal procurement.
| Leading Market Players |
|---|
| Chery Group |
| Volkswagen |
| BYD |
| Eletra |
| Chevrolet |
| Great Wall Motor (GWM) |
| MG Motor |
| Renault |
| Geely |
| Others |
Value Network & Pricing Analysis
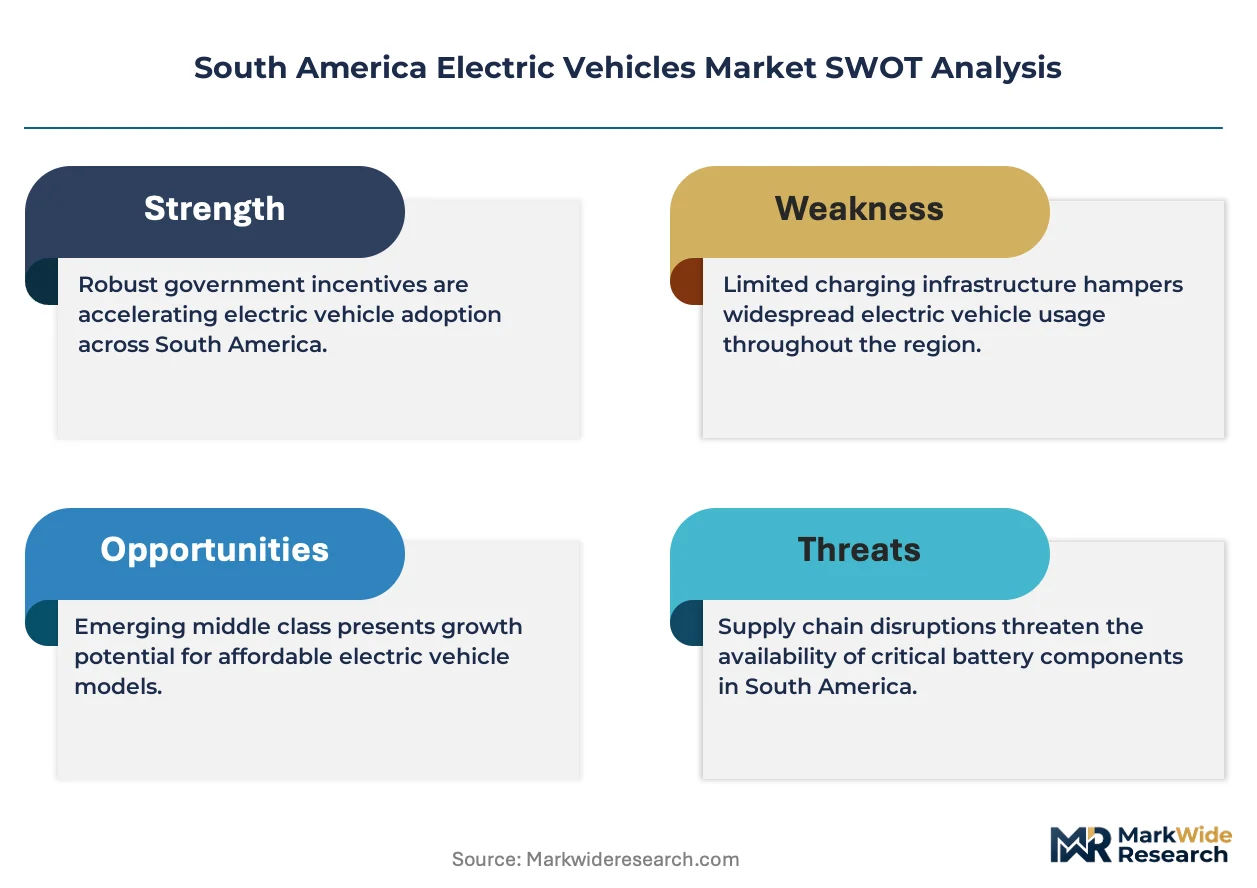
Cobalt and lithium price volatility transmits directly to fleet procurement budgets across South America, compressing pricing tier spreads between premium cell-to-pack architectures and economy-grade lead-acid alternatives while forcing supply chain restructuring toward lithium triangle brine sourcing.
Pricing Analysis
ANFAVEA emissions protocols dictate the pricing tier structure across Brazil's electric vehicle procurement landscape. Three-tier pricing separates premium battery electric configurations with integrated telematics from standard plug-in hybrid systems and economy-grade hybrid alternatives. Price differentiation hinges on certification grade for local content thresholds and volume scale of corporate fleet contracts. Cost compression in the economy tier intensifies because Argentine logistics operators prioritize capital constraints over energy density. Government agencies exhibit the lowest price sensitivity due to mandate-driven procurement timelines, while individual consumers in Peru's Andean corridors demonstrate acute responsiveness to financing access and electricity tariff structures.
Supply Chain Analysis
Tariff exposure between Argentina and Brazil under divergent Mercosur harmonization timelines dominates supply chain risk assessment for regional assemblers. Cell production concentrates in China, South Korea, and emerging Argentine brine processing facilities. Cathode material supply draws from Chilean and Bolivian lithium reserves alongside Indonesian nickel processing. Single-source vulnerability persists for high-voltage thermal management subsystems sourced from German and Japanese Tier 1 suppliers. Distribution runs through São Paulo state assembly partnerships for localized content compliance, with aftermarket service networks radiating from Santiago and Buenos Aires metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America electric vehicles market represents a platform-economics inflection where vehicle-to-grid interoperability standards are consolidating procurement decisions around integrated energy management ecosystems rather than discrete asset acquisitions.
For Market Incumbents: Pre-empt margin erosion from Chinese pure-play battery verticalization by deepening captive supply of lithium-ion cells through Argentine brine joint ventures and accelerating certification investments for ANFAVEA protocol compliance. Lock in channel control across São Paulo state fleet procurement pools before homologation timelines compress further. For New Entrants and Emerging Players: Mid-altitude municipal bus routes in Peru and Bolivia represent the most penetrable entry point, with powertrain adaptations for 3,000-meter-plus elevations creating defensible positioning against sea-level-optimized incumbents. Colombia's Atlantic coast freight corridors offer secondary white-space for electrified logistics alternatives where charging infrastructure buildout lags demand. A service-contract bundling go-to-market angle displaces fragmented vehicle-plus-infrastructure sourcing. For Investors and Strategic Acquirers: The market sits at a regulatory-mandate acceleration phase that favors cell chemistry specialists with lithium triangle feedstock access and thermal management subsystem providers. Long-term viability over the coming decade hinges on backward integration into regional brine processing and cathode material production. The signal to watch is Mercosur harmonization progress on import duty classifications, which would trigger consolidation among compliance-constrained assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | BYD's cell-to-pack integration secures cost advantages across Latin American fleet procurement pools. |
| Geographic Manufacturing Footprint | Chery Group's dedicated São Paulo assembly lines anchor regional content compliance under ANFAVEA protocols. |
| Charging Infrastructure Partnership | Brazil's distributed generation framework converges with bidirectional hardware to monetize fleet stationary storage. |
| Platform Standardization | Volkswagen's altitude and temperature engineering investments adapt powertrains for Andean corridor extremes. |
| Software-Defined Vehicle Investment | Telematics integration shifts fleet valuation frameworks from upfront capital to lifecycle operational metrics. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, municipal transit authority fleet managers, and charging infrastructure developers, then refined through secondary validation against ANFAVEA production databases, Chilean Ministry of Energy decarbonization filings, Argentine national automotive regulator homologation records, and IHS Markit vehicle registration data. Bottom-up unit deployment estimates across vehicle class and propulsion architecture were triangulated with top-down market sizing from corporate fleet procurement disclosures and government tender documentation.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning vehicle type, battery chemistry, charging modality, and end-user procurement scale. CAGRs were derived from slope analysis of historical fleet electrification timelines and elasticity estimates for regulatory mandate acceleration. Industry-specific forecast inputs incorporated lithium carbonate price trajectory assumptions and Mercosur trade rule evolution scenarios without binding to specific timeline commitments.
Practitioners should monitor cobalt price volatility, Mercosur harmonization deadlock, and high-voltage technician certification pipeline capacity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market