
 Modular Test Equipment Market | 2026-2036
Modular Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Test Equipment Market Foresight
CE marking under the EU Radio Equipment Directive is realigning the cost-of-entry calculus for RF modular test equipment sold into European defense and aerospace channels. Keysight Technologies leverages its PXI and AXIe portfolio breadth to sustain leadership in high-frequency signal analysis. Rohde & Schwarz GmbH & Co. KG anchors its position through deep calibration infrastructure and sovereign European manufacturing.
Modular test equipment comprises interchangeable instrument cards housed in standardized chassis, typically achieving measurement bandwidths from DC to 110 GHz depending on the plug-in module, and serves primarily to reduce capital expenditure through reusable hardware platforms across sequential validation workflows. Oscilloscope modules capture the largest share of product-type revenue due to their ubiquity in embedded systems debug, while RF modules are expanding fastest as millimeter-wave device proliferation extends test frequency requirements. Network analyzers concentrate margin pools in aerospace and defense applications where traceable metrology carries certification premiums.
FCC equipment authorization rules shape RF modular test demand in the United States by mandating pre-compliance validation, while ETSI standards in Europe and MIC regulations in Japan enforce divergent spurious emission test protocols that fragment firmware and filter configurations. The EU AI Act and emerging automated test orchestration requirements are beginning to influence how self-calibrating instrument modules document decision audit trails. Stakeholders must decide whether to architect platform ecosystems around proprietary chassis standards or bet on the OpenTAP open-source automation framework gaining traction across multinational OEM supply chains.
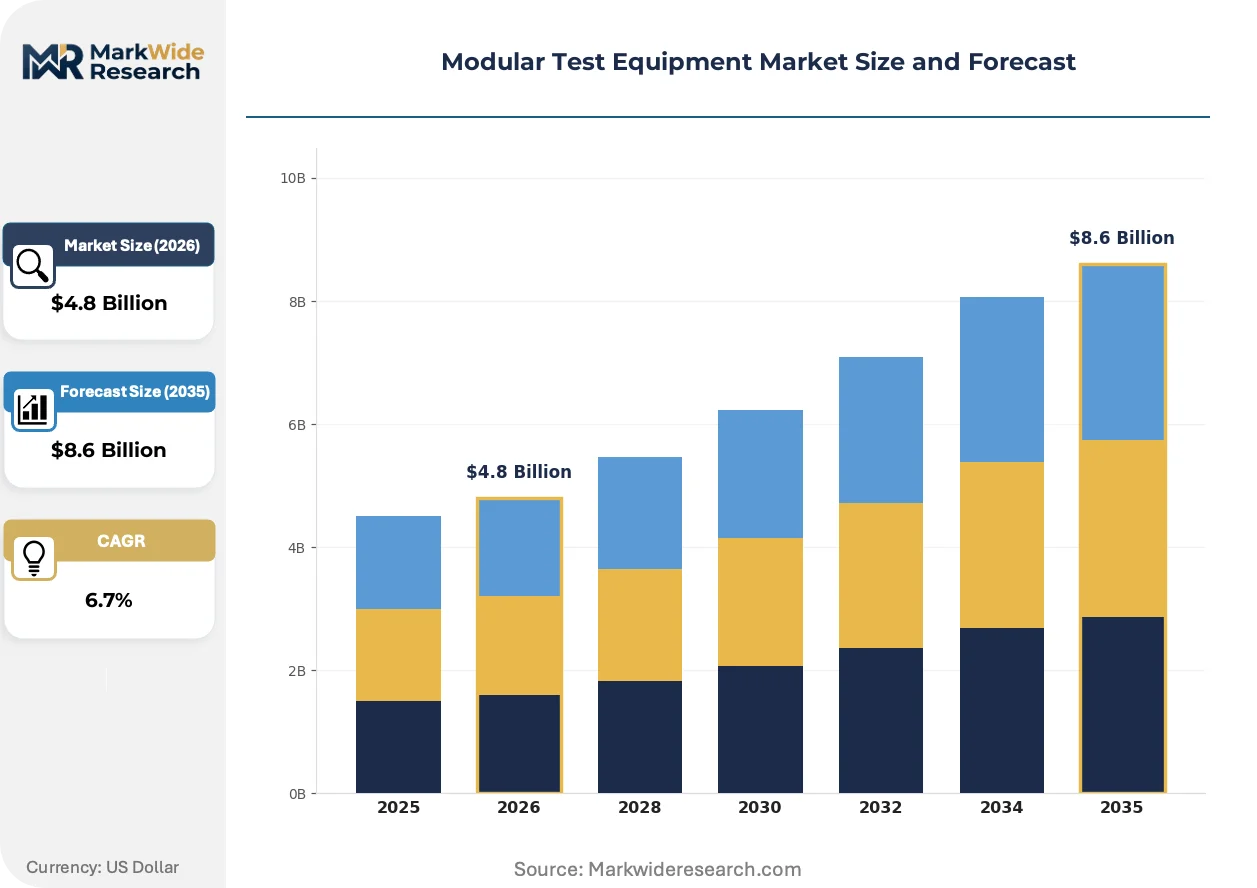
Market Dynamics
The transition from 5G to 5G-Advanced and Open RAN architectures is compressing test equipment refresh cycles while fragmenting interoperability requirements across multi-vendor telecommunications deployments.
Growth Catalysts
- Defense Procurement Acceleration:United States military programs are expanding RF and mixed-signal test platform acquisitions for electronic warfare and radar system validation.
- Automotive Electrification Mandates:Germany's autonomous vehicle validation labs and battery test facilities are scaling instrument capacity to meet homologation timelines.
- EU Radio Equipment Directive:CE marking requirements are recalibrating cost-of-entry for European defense and aerospace channels, favoring modular platforms with rapid reconfigurability.
Market Restraints
- Calibration Infrastructure Concentration:Sovereign European manufacturing and deep calibration networks create geographic supply bottlenecks for traceable metrology.
- Regulatory Fragmentation:Divergent spurious emission test protocols between FCC equipment authorization rules, ETSI standards, and MIC regulations force redundant firmware and filter configurations.
- Millimeter-Wave Component Costs:RF modules above 67 GHz depend on gallium arsenide and indium phosphide substrates with volatile raw material pricing.
Strategic Opportunities
- OpenTAP Automation Framework:Open-source test orchestration is gaining traction across multinational OEM supply chains, creating ecosystem differentiation for early platform adopters.
- EU AI Act Compliance:Automated test modules with self-calibration capabilities must document decision audit trails, opening service revenue for compliance documentation.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and telecom equipment production are seeding modular test demand in Bengaluru and Hyderabad validation clusters.
Industry Challenges
- Legacy Chassis Integration:Proprietary PXI and AXIe standards create friction when migrating existing module libraries to next-generation chassis architectures.
- Metrology Talent Scarcity:RF calibration engineers with traceable standards expertise are concentrating in aerospace hubs, creating recruitment bottlenecks for commercial test houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Test Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Generators, Power Meters, Network Analyzers, Oscilloscopes End User: Aerospace, Telecommunications, Automotive, Defense Technology: Digital, Analog, Mixed-Signal, RF Application: Research & Development, Manufacturing, Quality Assurance, Testing Services |
| Companies Covered | Astronics Corporation, Cohu Inc, National Instruments, Rohde & Schwarz GmbH & Co. KG, Keysight Technologies, Advantest Corporation, Chroma ATE Inc, Marvin Test Solutions, Teradyne Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Test Equipment Market Shifts & Advancements
Software-defined instrumentation is dissolving hardware boundaries between traditional instrument categories, enabling single chassis configurations to reconfigure across oscilloscope, spectrum analyzer, and network analyzer functions through firmware updates.
PXIe-based digitizers with direct RF sampling architectures are absorbing intermediate frequency stages previously handled by discrete downconverter modules. Aerospace prime contractors in the United States are deploying these platforms for phased array radar characterization, collapsing test rack footprints by eliminating external mixing hardware. This consolidation is absorbing margin pools from standalone spectrum analyzer vendors while shifting value toward FPGA-based signal processing IP.
The EU AI Act's automated decision documentation requirements are reshaping calibration workflows for self-optimizing instrument modules. European test houses must now maintain immutable logs of algorithmic threshold adjustments during self-calibration sequences, particularly for aerospace certification bodies. German automotive labs are responding by integrating blockchain-anchored calibration certificates into their PXI-based validation pipelines.
Telecommunications OEMs are unbundling capital acquisition from operational test capacity through instrument-as-a-service arrangements. South Korean 5G base station manufacturers are piloting usage-based pricing for millimeter-wave test modules, replacing outright purchase with throughput-metered access. This model is compressing vendor sales cycles while shifting balance sheet exposure toward lessors with captive calibration infrastructure.
Modular Test Equipment Market Segmentation
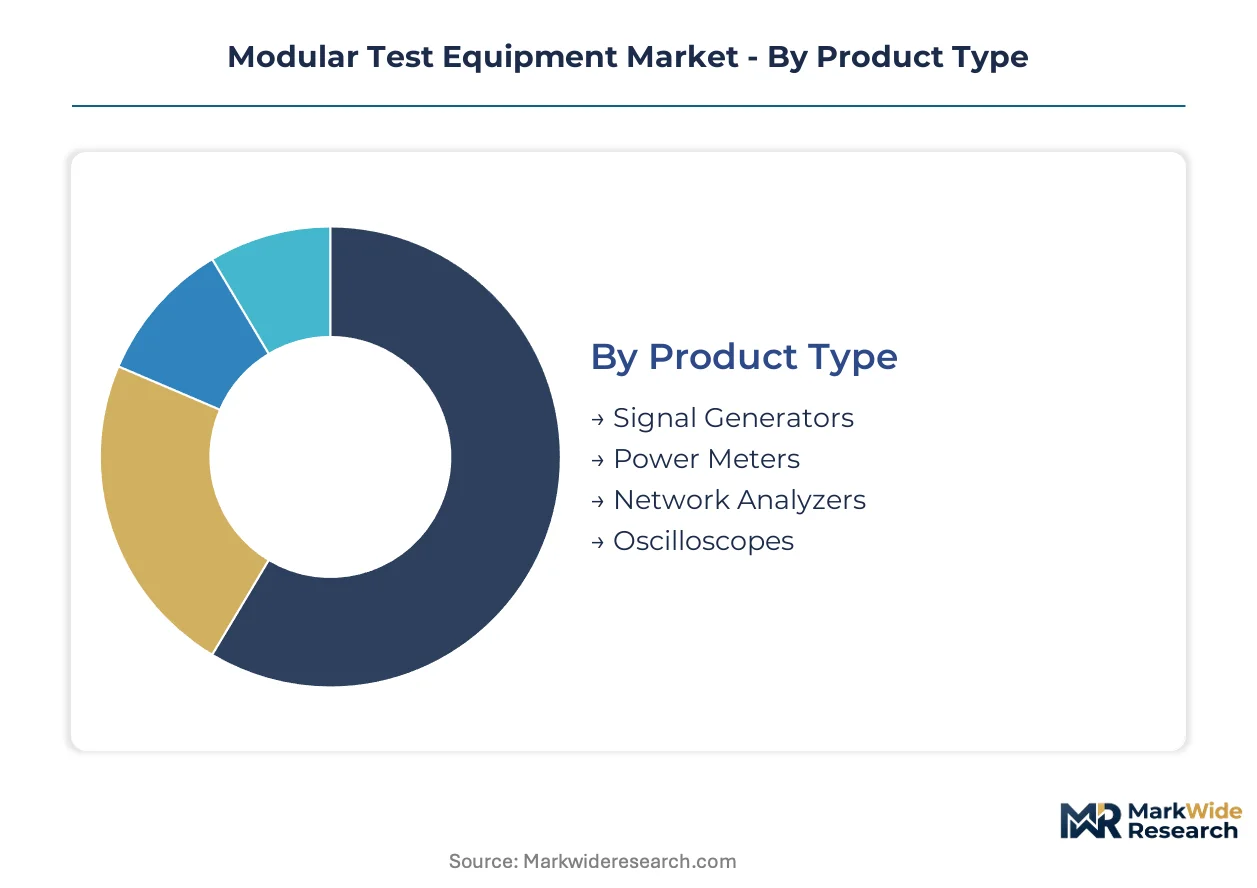
Modular test equipment architectures derive competitive advantage from interchangeable instrument modules that amortize capital investment across sequential validation workflows. Segmentation reveals how technical specifications, end-use requirements, and regulatory compliance pressures concentrate purchasing decisions around specific module categories and deployment contexts.
Product Type:
Volume procurement concentrates in oscilloscope modules due to their ubiquity across embedded systems debug, while premium margins pool in RF and network analyzer modules serving aerospace certification requirements.
- Oscilloscopes:These modules capture voltage waveforms with bandwidths typically spanning 50 MHz to 33 GHz depending on the plug-in configuration. Demand concentrates in German automotive electrification labs and United States semiconductor validation facilities where high-channel-count debug of power electronics dominates procurement.
- RF Modules:Signal analysis capabilities extend from baseband through 110 GHz using gallium arsenide and indium phosphide substrate technologies. United States defense procurement programs and South Korean 5G-Advanced base station manufacturers are expanding capacity for millimeter-wave device characterization.
- Network Analyzers:S-parameter measurement modules serve phased array radar and antenna test applications with traceable metrology requirements.
- Signal Generators:Arbitrary waveform and vector signal modules provide stimulus sources for receiver test and system emulation workflows.
- Power Meters:RF power sensing modules deliver absolute and relative power measurements for transmitter compliance verification.
Mature deployment sits with oscilloscope modules in general-purpose test houses. Newer deployment is concentrated in RF modules above 67 GHz for 5G-Advanced and electronic warfare applications.
End User:
Defense and aerospace channels command premium pricing for traceable calibration documentation, while automotive electrification is expanding total addressable volume through validation lab buildouts.
- Defense:Electronic warfare and radar system validation programs in the United States require RF and mixed-signal test platforms with sovereign manufacturing provenance and deep calibration infrastructure. FCC equipment authorization rules and ITAR compliance constraints shape procurement specifications.
- Aerospace:Phased array characterization and satellite payload test applications demand network analyzer modules with certification-grade metrology. European CE marking under the EU Radio Equipment Directive recalibrates cost-of-entry for modular platforms.
- Automotive:German autonomous vehicle validation labs and battery test facilities are scaling PXI-based instrument capacity to meet homologation timelines.
- Telecommunications:Open RAN interoperability testing and 5G-Advanced base station manufacturing are fragmenting requirements across multi-vendor deployments.
Defense procurement anchors premium margin pools through traceable standards requirements. Automotive electrification represents the steepest expansion trajectory as validation timelines compress.
Technology:
Digital architectures dominate unit volume through software-defined reconfigurability, while mixed-signal and RF technologies concentrate value in high-frequency measurement applications.
- Digital:FPGA-based signal processing enables single chassis reconfiguration across oscilloscope, spectrum analyzer, and network analyzer functions through firmware updates. PXIe-based digitizers with direct RF sampling are collapsing test rack footprints by eliminating external mixing hardware.
- RF:Millimeter-wave measurement capabilities above 67 GHz depend on compound semiconductor substrates with volatile raw material pricing. South Korean telecommunications OEMs are piloting instrument-as-a-service arrangements for throughput-metered access.
- Mixed-Signal:Combined analog and digital stimulus/measurement modules serve power electronics and sensor interface validation in automotive applications.
- Analog:Traditional voltage and current measurement modules persist in general-purpose test infrastructure with lower replacement frequency.
Digital platforms concentrate new deployment through software-defined flexibility. RF technology commands sustained investment despite substrate cost volatility.
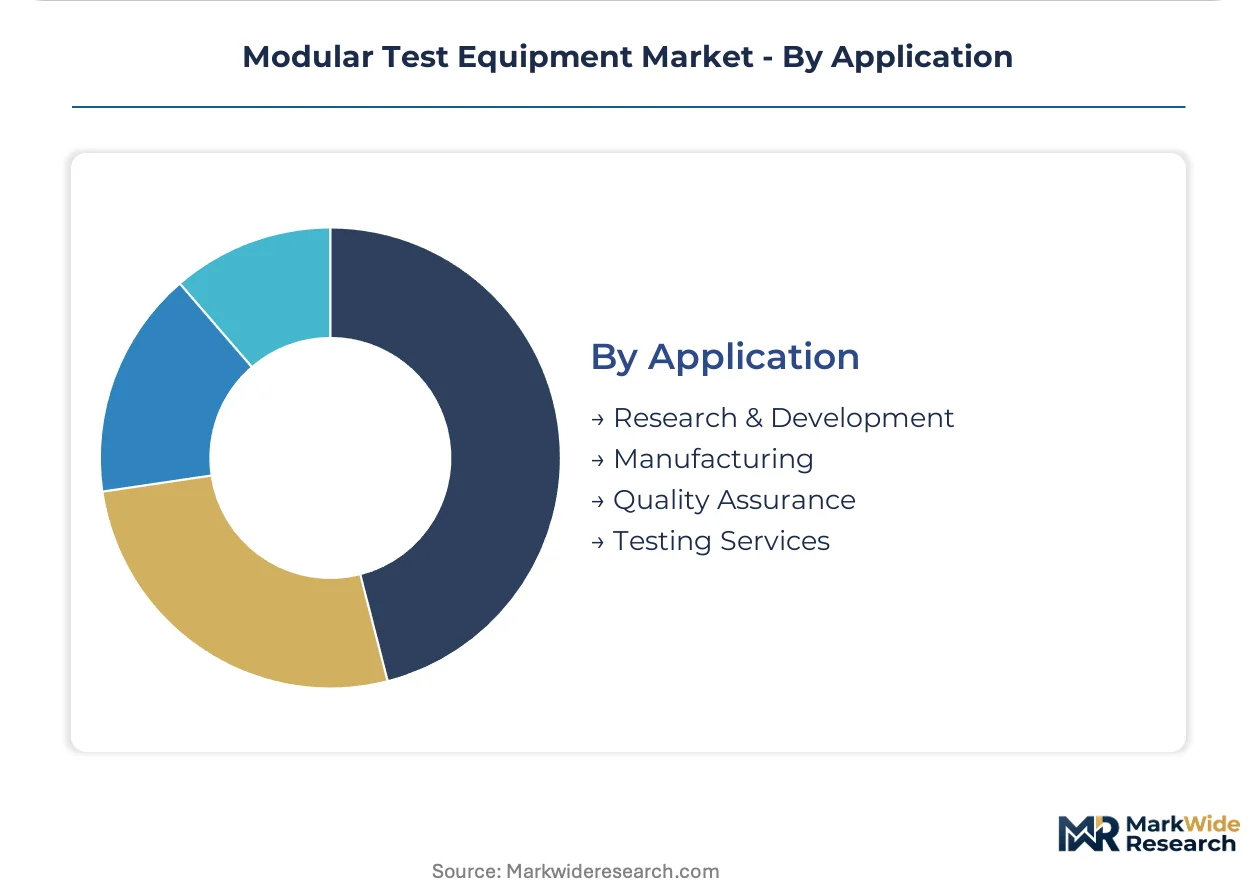
Application:
Manufacturing test consumes highest module volume through repetitive validation workflows, while research and development commands premium specifications for exploratory characterization.
- Manufacturing:Production line test stations leverage modular architectures to amortize chassis investment across multiple product generations. India's PLI scheme incentives for semiconductor and telecom equipment production are seeding demand in Bengaluru and Hyderabad validation clusters.
- Research & Development:Exploratory characterization workflows require highest measurement bandwidth and reconfigurability. United States aerospace prime contractors deploy these platforms for phased array radar development.
- Quality Assurance:Pre-compliance validation for FCC equipment authorization and ETSI spurious emission protocols forces redundant firmware configurations across regulatory domains.
- Testing Services:Commercial test houses face metrology talent scarcity as RF calibration engineers with traceable standards expertise concentrate in aerospace hubs.
Manufacturing applications anchor volume procurement through standardized test sequences. Research and development concentrates newer deployment in software-defined instrumentation with maximum reconfigurability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bengaluru concentrate modular test equipment demand through electronics manufacturing clusters. Tax incentives under India's PLI scheme and China's bonded zone policies accelerate validation infrastructure buildouts. These zones anchor procurement decisions for multinational OEMs.
United States
Defense procurement programs for electronic warfare and radar validation drive RF test platform acquisitions. FCC equipment authorization rules mandate pre-compliance validation workflows. Aerospace prime contractors in California and Texas deploy PXI-based systems for phased array characterization.
Germany
Automotive electrification mandates and autonomous vehicle homologation timelines expand instrument capacity in validation labs. CE marking under the EU Radio Equipment Directive recalibrates cost-of-entry for defense and aerospace channels. Munich and Stuttgart clusters concentrate battery test facility buildouts.
China
MIIT standards for 5G-Advanced base station manufacturing fragment test requirements across domestic OEM supply chains. Bonded zone incentives in Shenzhen and Shanghai seed modular test demand for semiconductor validation. Yangtze River Delta electronics clusters absorb highest chassis deployment volumes.
India
PLI scheme incentives for telecom equipment and semiconductor production concentrate demand in Bengaluru and Hyderabad validation clusters. BIS certification requirements for RF equipment shape procurement specifications. Electronics manufacturing zones in Karnataka and Telangana scale instrument-as-a-service pilots.
South Korea
5G-Advanced base station manufacturers pilot throughput-metered access models for millimeter-wave test modules. MFDS-equivalent telecom regulations enforce spurious emission protocols. Seoul Capital Area OEMs unbundle capital acquisition from operational test capacity.
Modular Test Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across modular test equipment architectures. The vendor base stratifies into three tiers: chassis platform providers, module specialists, and calibration service integrators. Consolidation pressure concentrates in RF and millimeter-wave segments where compound semiconductor substrates create supply bottlenecks. Competitive moves center on strategic partnerships for OpenTAP framework adoption and geographic expansion into India PLI scheme zones.
Among diversified measurement technology providers, Keysight Technologies and Rohde & Schwarz GmbH & Co. KG exemplify platform breadth strategies spanning PXI and AXIe chassis ecosystems. National Instruments represents the pure-play modular architecture specialist archetype with concentrated investment in software-defined instrumentation. These three companies anchor competitive positioning through divergent approaches to calibration infrastructure and automation framework alignment.
| Leading Market Players |
|---|
| Astronics Corporation |
| Cohu Inc |
| National Instruments |
| Rohde & Schwarz GmbH & Co. KG |
| Keysight Technologies |
| Advantest Corporation |
| Chroma ATE Inc |
| Marvin Test Solutions |
| Teradyne Inc |
| Others |
Supply & Pricing Matrix
Certification-grade metrology tiers bifurcate procurement economics between aerospace defense channels demanding traceable calibration documentation and commercial test houses prioritizing capital efficiency. This divergence manifests in chassis platform pricing that scales with calibration infrastructure depth while supply chains concentrate compound semiconductor substrate sourcing for millimeter-wave modules.
Pricing Analysis
Short lead-time premiums of thirty to sixty days command fifteen to twenty-five percent markups over standard delivery windows in RF module procurement. Three-tier pricing structure across premium, standard, and economy levels reflects calibration grade and sovereign manufacturing provenance as primary differentiation drivers. Cost compression in economy-tier oscilloscope modules is intensifying because Chinese chassis manufacturers are expanding PXIe-compatible platform supply. Commercial test houses exhibit highest price sensitivity, while United States defense programs demonstrate inelastic demand for ITAR-compliant instrument sourcing.
Supply Chain Analysis
Freight costs for gallium arsenide and indium phosphide substrates from Japan and Germany represent twelve to eighteen percent of landed module cost for millimeter-wave RF instruments. Manufacturing concentration in the United States, Germany, and South Korea anchors chassis assembly and final calibration stages. Raw material dependencies center on compound semiconductor wafers, high-frequency connectors, and FPGA signal processing chips. Single-source vulnerability sits with indium phosphide substrate supply from Japanese specialty chemical producers. Distribution runs through authorized channel partners with captive calibration infrastructure serving aerospace and defense primes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
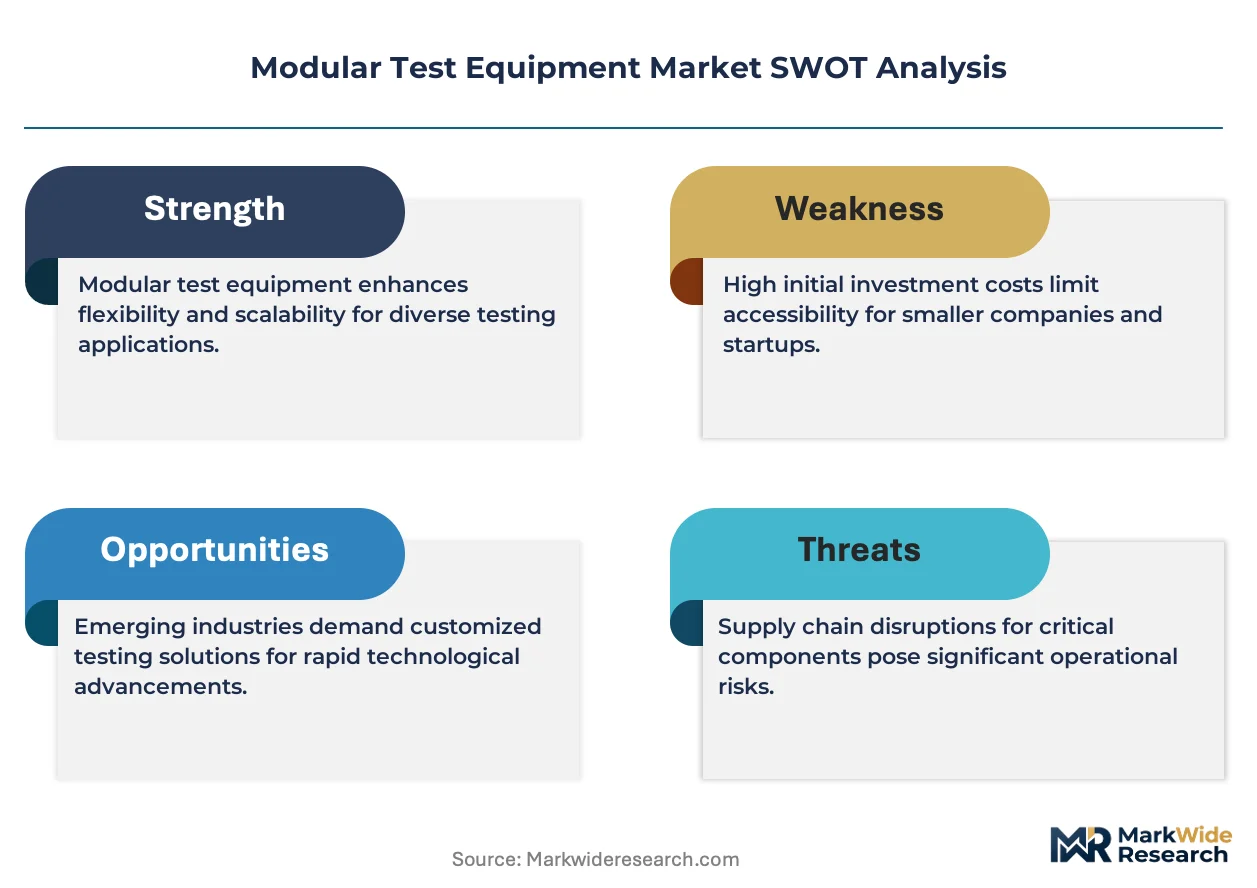
Software-defined instrumentation is displacing discrete hardware categories, collapsing oscilloscope-spectrum analyzer-network analyzer boundaries into reconfigurable FPGA-based platforms.
For Market Incumbents: Extend calibration service revenue through blockchain-anchored certificate offerings that address EU AI Act automated decision documentation requirements. Fortify position against OpenTAP framework adoption by integrating proprietary automation APIs with early ecosystem partners. Capacity addition in Bengaluru and Hyderabad validation clusters captures India PLI scheme procurement flows.
For New Entrants and Emerging Players: Launch via instrument-as-a-service arrangements targeting South Korean 5G-Advanced base station manufacturers seeking throughput-metered millimeter-wave access. White-space concentration sits with mid-tier commercial test houses facing metrology talent scarcity in non-aerospace geographies. Penetrate through OpenTAP-native platform architectures that reduce customer switching costs from legacy PXI module libraries.
For Investors and Strategic Acquirers: Re-rating potential sits with calibration infrastructure specialists given EU AI Act compliance documentation mandates expanding service attach rates. Long-term viability favors platforms with sovereign European manufacturing and deep traceable standards networks. Acquisition target archetype: regional test houses with captive aerospace certification relationships. Signal to watch: OpenTAP framework adoption velocity across multinational OEM supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| OpenTAP Framework Adoption | Reduces customer switching costs for modular platform migrations across multinational OEM supply chains. |
| Blockchain-Anchored Calibration Certificates | Addresses EU AI Act immutable documentation requirements for self-optimizing instrument modules. |
| India PLI Zone Expansion | Captures semiconductor and telecom equipment validation demand in Bengaluru and Hyderabad clusters. |
| Instrument-as-a-Service Launch | Compresses sales cycles for South Korean 5G-Advanced base station manufacturers. |
| Millimeter-Wave RF Module Development | Secures position in 5G-Advanced and electronic warfare test applications above 67 GHz. |
Research Methodology
SEC filings, ETSI standards documentation, and FCC equipment authorization databases formed the secondary backbone for vendor positioning and regulatory requirement mapping. Primary interviews with RF calibration engineers, aerospace procurement officers, automotive validation lab directors, and telecommunications test managers informed demand segmentation and purchasing decision hierarchies. Bottom-up module shipment analysis and top-down chassis deployment estimates were triangulated against customs trade data and bonded zone infrastructure disclosures.
Bottom-up modeling aggregated product-type, end-user, and technology segment volumes across the projection horizon. Segmentation dimensions included instrument module category, chassis architecture standard, calibration grade tier, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical procurement cycles and technology refresh patterns. Forecast inputs incorporated defense procurement acceleration timelines, automotive homologation mandates, and Open RAN interoperability testing requirements.
Defense budget reallocation, compound semiconductor supply disruption, and OpenTAP framework adoption velocity are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding regulatory enforcement consistency and technology transition pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Signal Generator Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
Diamond Tester Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market