
 Digital RF Memory Market | 2026-2036
Digital RF Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Digital RF Memory Market Insights
Asset-light leasing models for high-speed converter subsystems is fragmenting traditional procurement pathways for defense primes. Lockheed Martin Corporation leverages captive semiconductor partnerships to sustain vertical control over critical signal processing chains. Thales Group anchors European sovereignty initiatives through localized FPGA implementation foundries. Mercury Systems competes on rapid customization cycles for classified electronic warfare programs.
Digital RF Memory captures, digitizes, and regenerates radio frequency signals with nanosecond latency using gigasample-per-second converters and field-programmable gate arrays for coherent deception of hostile radar. The technology enables real-time manipulation of electromagnetic signatures to protect aircraft, naval vessels, and ground platforms from guided threats. Signal processors and memory arrays dominate current program spend given their central role in threat replication fidelity. FPGA implementation shows the fastest expansion trajectory as reprogrammable logic reduces non-recurring engineering costs for evolving threat libraries.
US Department of Defense electromagnetic spectrum superiority directives intersect with FAA frequency coordination mandates and NATO STANAG interoperability standards to shape product roadmaps. EAR and ITAR export controls restrict technology transfer, compressing accessible supplier pools for non-US end users. Stakeholders must weigh sovereign content requirements against the performance advantages of foreign-sourced ASIC fabrication when designing next-generation deception architectures.
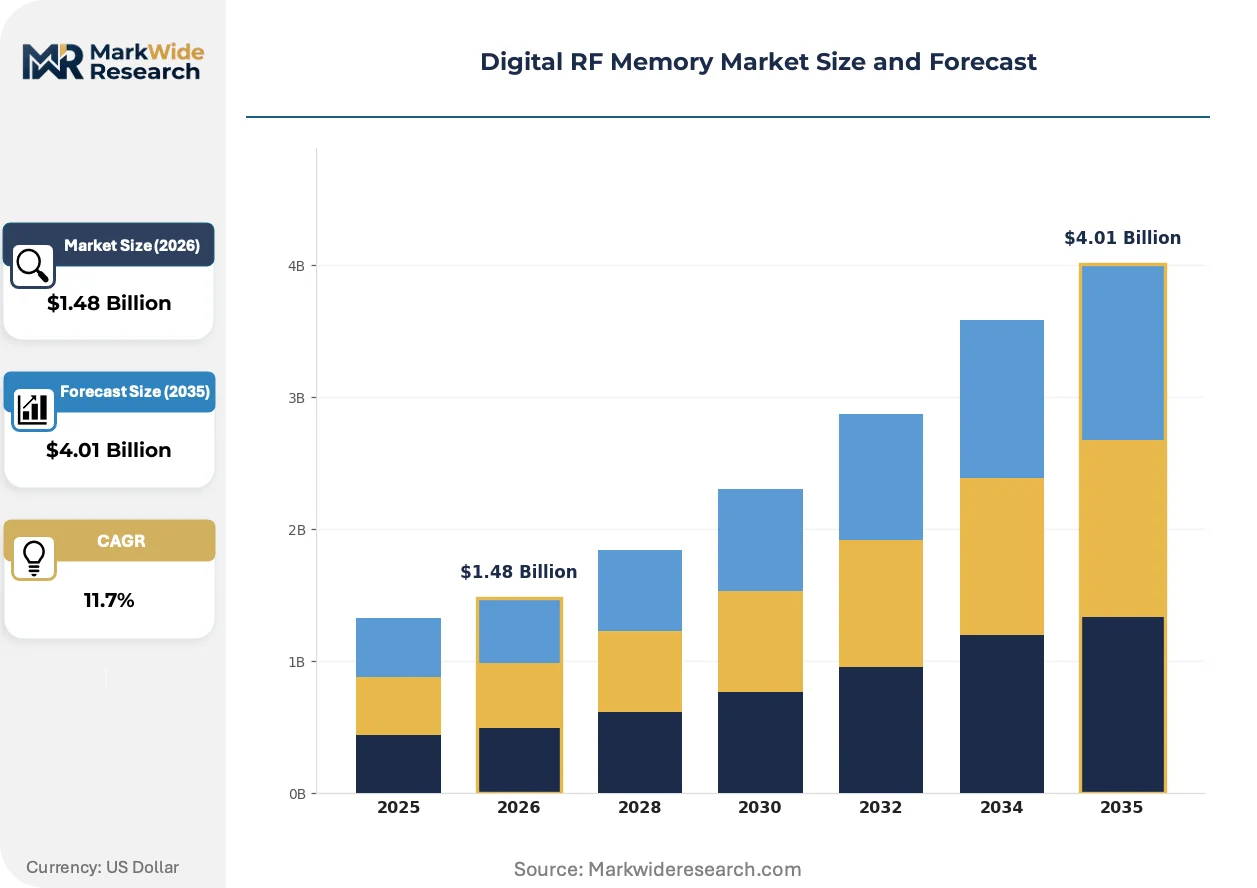
Market Dynamics
Defense procurement cycles are compressing as NATO militaries accelerate electromagnetic spectrum modernization, forcing DRFM subsystem suppliers to absorb development risk before contract award while maintaining ITAR-compliant supply chains.
Growth Catalysts
- US Department of Defense electromagnetic spectrum superiority directives:These mandates prioritize coherent deception capabilities for fifth-generation fighter platforms, channeling classified R&D funding toward reprogrammable threat libraries.
- FPGA-based signal regeneration:Field-programmable gate arrays reduce non-recurring engineering costs when threat profiles evolve, enabling rapid firmware updates without hardware redesign.
- NATO STANAG interoperability standards:Common electronic warfare architectures across allied forces create pooled procurement volumes for deception subsystems deployed on multinational aerial platforms.
Market Restraints
- ITAR export controls:US State Department restrictions on high-speed converter technology transfer compress accessible supplier pools for non-US end users, fragmenting procurement pathways.
- GaN-on-SiC substrate concentration:Gallium nitride power amplifier substrates depend on a concentrated US-Japan-Taiwan supply base, exposing programs to single-source vulnerability.
- Classified program opacity:Compartmentalized threat intelligence limits competitive visibility into actual operational requirements, inflating bid preparation costs for prime contractors.
Strategic Opportunities
- Australian AUKUS integration:Trilateral security pact commitments to shared electronic warfare architectures open procurement pathways for DRFM subsystems on P-8 Poseidon and future nuclear-powered submarine platforms.
- Swarming drone countermeasures:Low-cost unmanned aerial vehicle threats require coherent deception at reduced unit economics, expanding addressable market beyond manned aircraft protection.
- EU Chips Act sovereignty incentives:European semiconductor fabrication subsidies enable localized FPGA foundry capacity, reducing dependency on foreign-sourced programmable logic for classified programs.
Industry Challenges
- Clearance-constrained engineering workforce:TS/SCI-cleared digital signal processing specialists remain scarce, extending program staffing timelines for classified electronic warfare development.
- Legacy radar integration complexity:Backward compatibility with analog deception systems on fourth-generation aircraft platforms consumes engineering bandwidth without advancing competitive differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital RF Memory Market |
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $4.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Converters, Signal Processors, Data Storage Devices, Timing Modules, Memory Arrays Technology: Sampling, Digitizing, Data Compression, Signal Modulation, FPGA Implementation, ASIC Design Application: Radar Systems, Communication Equipment, Electronic Warfare, Test & Measurement, Signal Intelligence End User: Defense Contractors, Telecom Operators, Aerospace Firms, Research Laboratories, Security Agencies |
| Companies Covered | Lockheed Martin Corporation, Thales Group, Northrop Grumman Corporation, Mercury Systems, Israel Aerospace Industries, BAE Systems, Leonardo S.P.A, Airbus Group, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital RF Memory Market Trends and Innovations
Signal processing architectures are converging around software-defined electromagnetic manipulation, collapsing the boundary between hardware-defined threat replication and algorithmic deception.
Direct RF sampling is digitizing intermediate frequency stages previously handled by analog downconversion chains. Fifth-generation electronic warfare suites on F-35 and NGAD platforms are adopting multi-gigasample converters to capture full bandwidth threat signatures without analog preprocessing. This is digitizing the front-end signal path, compressing subsystem footprint while enabling real-time spectral analysis that analog architectures cannot achieve.
FAA frequency coordination mandates are intersecting with DoD electromagnetic spectrum allocation priorities, creating dual-use pressure on converter bandwidth specifications. Civil-military spectrum sharing frameworks require DRFM systems to demonstrate non-interference with commercial aviation radars before deployment. European NATO members are responding through EASA-aligned certification pathways that parallel national military approval processes.
Asset-light leasing models for high-speed converter subsystems are displacing traditional capital acquisition in classified program prototyping. Prime contractors now access calibrated measurement hardware through subscription arrangements rather than balance-sheet ownership, compressing technology refresh cycles. This pattern concentrates in US-based electronic warfare development centers where rapid iteration outweighs long-term asset control.
Digital RF Memory Market Segmentation
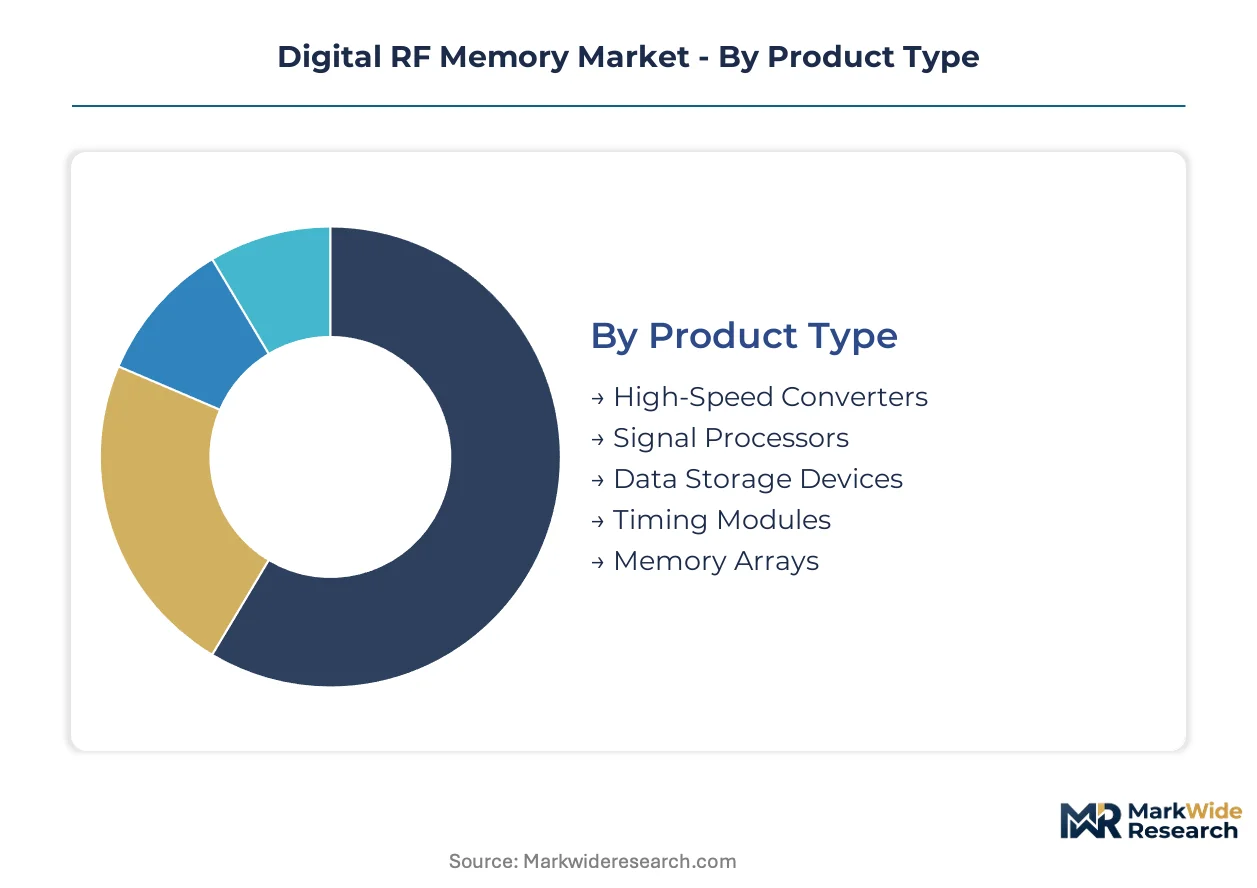
DRFM procurement patterns diverge sharply across product architectures, with defense primes prioritizing reprogrammable signal chains while commercial test houses favor fixed-function cost efficiency. Segmentation reveals where sovereign content mandates intersect with performance thresholds.
Product Type:
Use cases span from laboratory calibration rigs requiring picosecond timing precision to airborne pods demanding vibration-hardened memory arrays.
- High-Speed Converters:Gigasample-per-second analog-to-digital interfaces digitize RF signatures at intermediate frequency stages. US-based electronic warfare development centers concentrate procurement for fifth-generation fighter platform integration, driven by DoD electromagnetic spectrum superiority directives.
- Signal Processors:Field-programmable gate arrays and dedicated ASICs execute real-time convolution for coherent deception algorithms. NATO STANAG interoperability requirements channel pooled procurement volumes toward reprogrammable architectures that accommodate evolving threat libraries without hardware redesign.
- Data Storage Devices:Solid-state buffers capture threat signatures for post-mission analysis.
- Timing Modules:Nanosecond-synchronization circuits align regenerated signals with hostile radar pulse repetition intervals.
- Memory Arrays:High-density SRAM buffers store digitized waveform templates for rapid recall.
Established volume favors signal processors; emerging adoption favors high-speed converters.
Technology:
Engineering trade-offs center on non-recurring engineering amortization against unit production economics.
- FPGA Implementation:Reprogrammable logic fabrics enable firmware updates when threat profiles shift, eliminating mask-set costs for each iteration. European defense primes leverage EU Chips Act subsidies to localize foundry capacity, reducing ITAR exposure for classified programs.
- ASIC Design:Custom silicon delivers power efficiency and latency advantages for fielded systems with stable requirements. US-Japan-Taiwan substrate concentration creates single-source vulnerability for gallium nitride power amplifier integration.
- Sampling:Direct RF digitization architectures bypass analog downconversion stages.
- Digitizing:Quantization methods determine dynamic range and spurious-free dynamic performance.
- Data Compression:Lossless algorithms reduce storage footprint for extended mission profiles.
- Signal Modulation:Phase and amplitude manipulation generates coherent false targets.
ASIC design captures current program spend; FPGA implementation climbs the fastest on refresh cycle compression.
Application:
Operational environments dictate environmental hardening, bandwidth, and deception sophistication requirements.
- Electronic Warfare:Coherent deception systems protect manned and unmanned platforms from radar-guided threats through real-time signature manipulation. Australian AUKUS integration opens procurement pathways for P-8 Poseidon and nuclear-powered submarine platforms under trilateral architecture commitments.
- Radar Systems:Test and evaluation facilities replicate hostile emitter signatures for operator training and system validation. FAA frequency coordination mandates impose dual-use certification burdens on converter bandwidth specifications.
- Communication Equipment:Signal regeneration supports spectrum monitoring and interference mitigation.
- Test & Measurement:Calibration laboratories require traceable reference sources for converter characterization.
- Signal Intelligence:Intercept platforms demand wideband capture for emitter identification and geolocation.
Electronic warfare commands premium pricing; radar systems expand most quickly on training infrastructure investment.
End User:
Contracting mechanisms range from classified indefinite-delivery vehicles to commercial purchase orders.
- Defense Contractors:Prime systems integrators absorb development risk before contract award while maintaining ITAR-compliant supply chains for DRFM subsystem integration. Clearance-constrained engineering workforce scarcity extends program staffing timelines.
- Research Laboratories:National laboratories and university-affiliated research centers prototype next-generation deception algorithms. Asset-light leasing models for high-speed converter subsystems displace capital acquisition in prototyping phases.
- Telecom Operators:Spectrum monitoring applications drive commercial demand for signal regeneration capabilities.
- Aerospace Firms:Platform OEMs specify DRFM performance for electronic warfare suite integration.
- Security Agencies:Intelligence community procurement concentrates on signals intelligence and counter-surveillance applications.
Defense contractors anchor procurement volume; research laboratories gain share fastest on technology refresh acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import asymmetries in high-speed converter technology concentrate DRFM procurement advantages within ITAR-compliant jurisdictions. The United States maintains net exporter status in classified signal processing subsystems, while allied nations navigate sovereign content mandates against performance trade-offs.
United States
DoD electromagnetic spectrum superiority directives channel classified R&D funding toward coherent deception capabilities for fifth-generation fighter platforms. ITAR export controls administered by the US State Department restrict high-speed converter technology transfer, compressing accessible supplier pools for foreign end users. Defense prime contractors cluster in the Baltimore-Washington corridor and Greater Boston, absorbing development risk before contract award while maintaining security-cleared engineering workforces.
United Kingdom
BAE Systems and Leonardo anchor sovereign electronic warfare capabilities through NATO STANAG interoperability commitments. The UK Ministry of Defence's Integrated Review prioritizes electromagnetic spectrum operations as a warfighting domain, accelerating DRFM refresh cycles on Typhoon and Tempest platforms. Bristol and Edinburgh host specialized signal processing research centers developing next-generation deception algorithms for multinational aerial platforms.
France
Thales Group leverages localized FPGA implementation foundries to reduce ITAR exposure for classified European programs. The French Defence Procurement Agency's SCORPION program mandates sovereign content thresholds for electronic warfare subsystems on armored vehicles and aircraft. The Paris-Saclay cluster concentrates GaN-on-SiC substrate research for power amplifier integration into airborne DRFM pods.
Israel
Israel Aerospace Industries specializes in compact DRFM architectures for unmanned aerial vehicle protection and swarming drone countermeasures. The Israeli Ministry of Defense's Directorate of Defense Research and Development funds rapid threat library updates for regional emitter profiles. Haifa and Beersheba host vertically integrated electronic warfare development centers with captive semiconductor partnerships.
Australia
AUKUS trilateral security commitments open procurement pathways for DRFM subsystems on P-8 Poseidon maritime patrol aircraft and future nuclear-powered submarines. The Australian Defence Force's Joint Capabilities Group prioritizes electromagnetic spectrum superiority under the 2023 Defence Strategic Review. Edinburgh Defence Precinct in South Australia anchors sovereign electronic warfare integration facilities for allied architecture compatibility.
Digital RF Memory Market Competitive Landscape
On the supply side, the industry is consolidated around defense primes with captive semiconductor partnerships and clearance-constrained engineering workforces. Tier-one systems integrators absorb development risk before contract award while maintaining ITAR-compliant supply chains. Three strategic archetypes dominate: vertically integrated primes controlling critical signal processing chains, specialized subsystem suppliers competing on rapid customization cycles, and sovereign champions leveraging localized foundry capacity. Competitive dynamics center on strategic partnerships for FPGA implementation and technology licensing for threat library access.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the vertically integrated archetype through captive control over converter and processing subsystems. Thales Group occupies a distinct position as the anchor European sovereign champion, leveraging localized supply chains to satisfy classified program requirements. Mercury Systems represents the rapid-customization specialist tier, competing on compressed development cycles for compartmentalized electronic warfare programs.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Thales Group |
| Northrop Grumman Corporation |
| Mercury Systems |
| Israel Aerospace Industries |
| BAE Systems |
| Leonardo S.P.A |
| Airbus Group |
| Raytheon Technologies Corporation |
| Others |
Pricing and Supply Chain Analysis
ITAR export controls on high-speed converter technology determine both pricing tier spreads and supply chain shape in the Digital RF Memory market. The US State Department's restrictions compress accessible supplier pools for foreign end users, creating premium pricing for ITAR-compliant subsystems while fragmenting procurement pathways for non-US buyers.
Pricing Analysis
Defense prime contractors anchor pricing structure around classified program specifications rather than commercial benchmarks. Three-tier pricing structure across ITAR-restricted, NATO-cleared, and commercial-off-the-shelf levels reflects security clearance thresholds and sovereign content mandates. Cost compression in commercial-off-the-shelf tiers is intensifying because asset-light leasing models displace capital ownership for prototyping phases. Research laboratories exhibit highest price sensitivity due to constrained federal grant funding, while classified program offices demonstrate lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
TSMC, GlobalFoundries, and Intel Foundry Services hold dominant capacity for gigasample-per-second converter fabrication. Geographic supply concentration centers on Taiwan, the United States, and Japan for advanced node processing, with back-end packaging concentrated in Malaysia and Vietnam. Raw material dependencies include GaN-on-SiC substrates, high-purity silicon wafers, and rare-earth magnet components for precision timing modules. Single-source vulnerability in gallium nitride power amplifier substrates exposes programs to supply disruption. Distribution runs through defense prime contractor integration facilities rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital RF Memory sits at a high-growth disruption inflection driven by DoD electromagnetic spectrum superiority directives accelerating fifth-generation fighter platform procurement. FPGA-based reprogrammability is collapsing hardware refresh cycles while expanding addressable applications beyond manned aircraft protection.
For Market Incumbents: Entrench competitive position through captive semiconductor partnerships securing converter foundry allocation and TS/SCI-cleared engineering workforce development. Lockheed Martin Corporation's vertical control over signal processing chains exemplifies defensive architecture against rapid-customization specialists. Prioritize backward integration into GaN-on-SiC substrate supply to mitigate single-source vulnerability.
For New Entrants and Emerging Players: Australian AUKUS integration represents the most penetrable geographic underpenetration, with trilateral security commitments opening procurement pathways for P-8 Poseidon and nuclear-powered submarine platforms. Swarming drone countermeasures offer second white-space target given low-cost unmanned aerial vehicle threat proliferation. Position through rapid firmware update capabilities and subscription-based converter subsystem leasing to bypass capital-intensive prime contractor infrastructure.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors rapid-customization specialists with clearance-constrained engineering depth and reprogrammable logic expertise. Long-term viability centers on firms demonstrating sustained access to classified program pipelines and localized foundry partnerships reducing ITAR exposure. Watch Australian Defence Force Joint Capabilities Group procurement announcements as inflection indicator for AUKUS architecture adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Foundry Localization | EU Chips Act subsidies enable Thales Group to reduce ITAR exposure for classified European programs. |
| Captive Semiconductor Partnership | Lockheed Martin secures vertical control over converter allocation for fifth-generation fighter integration. |
| Asset-Light Leasing Model | Mercury Systems compresses prototyping cycles through subscription-based high-speed converter access. |
| AUKUS Architecture Integration | Australian Defence Force opens procurement pathways for P-8 Poseidon electronic warfare suites. |
| Swarming Drone Countermeasure Development | Israel Aerospace Industries targets low-cost unmanned aerial vehicle threat expansion with compact architectures. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with electronic warfare program managers, FPGA design engineers, defense procurement officers, and semiconductor foundry executives; and secondary validation through DoD electromagnetic spectrum superiority directives, NATO STANAG documentation, FAA frequency coordination mandates, SEC 10-K filings from defense primes, and customs trade data for high-speed converter subsystems. Bottom-up triangulation across product architecture segments and top-down validation against classified program spending estimates anchored market sizing.
Forecast inputs included FPGA implementation refresh cycles, GaN-on-SiC substrate supply constraints, and AUKUS trilateral procurement commitments across the projection horizon. Segmentation dimensions modeled encompass product type, technology implementation, application environment, and end-user contracting mechanism. CAGRs derived from defense procurement cycle compression rates and reprogrammable logic adoption curves. Industry-specific inputs incorporated ITAR compliance cost premiums and sovereign content threshold evolution.
Practitioners should monitor GaN-on-SiC substrate supply disruptions, ITAR regulation amendments, and AUKUS platform procurement announcements for early signals of forecast revision. Quarterly review of defense prime contractor backlog disclosures and foundry capacity allocation reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Memory IC Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Nano RAM Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
In-Memory Grid Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Smartphone RAM Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
Contactless Memory Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Japan DRAM Market
Memory Chips
New RAM Market
Memory Chips
Automotive Memory Market