
 Semiconductor Capital Equipment Market | 2026-2036
Semiconductor Capital Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Capital Equipment Market Analysis
Photonics and vacuum engineering talent scarcity is redrawing competitive boundaries for equipment vendors. Applied Materials leverages its broad process technology portfolio to sustain service revenue density across customer fabs. ASML dominates extreme ultraviolet lithography supply, a position it anchors through exclusive source partnerships for critical subcomponents.
Semiconductor capital equipment encompasses the precision machinery used to manufacture integrated circuits, including systems that achieve sub-nanometer pattern resolution, atomic-scale film uniformity, and plasma-based material removal at wafer throughputs exceeding 100 wafers per hour. Photolithography equipment commands the largest capital allocation share due to the technical complexity and sole-source dependency of leading-edge tools. Etching equipment and deposition equipment represent the fastest-growing product categories as three-dimensional device architectures multiply process steps per wafer. Foundries and integrated device manufacturers drive divergent procurement patterns, with foundries prioritizing flexibility across multiple nodes and IDMs concentrating volume at mature technology generations.
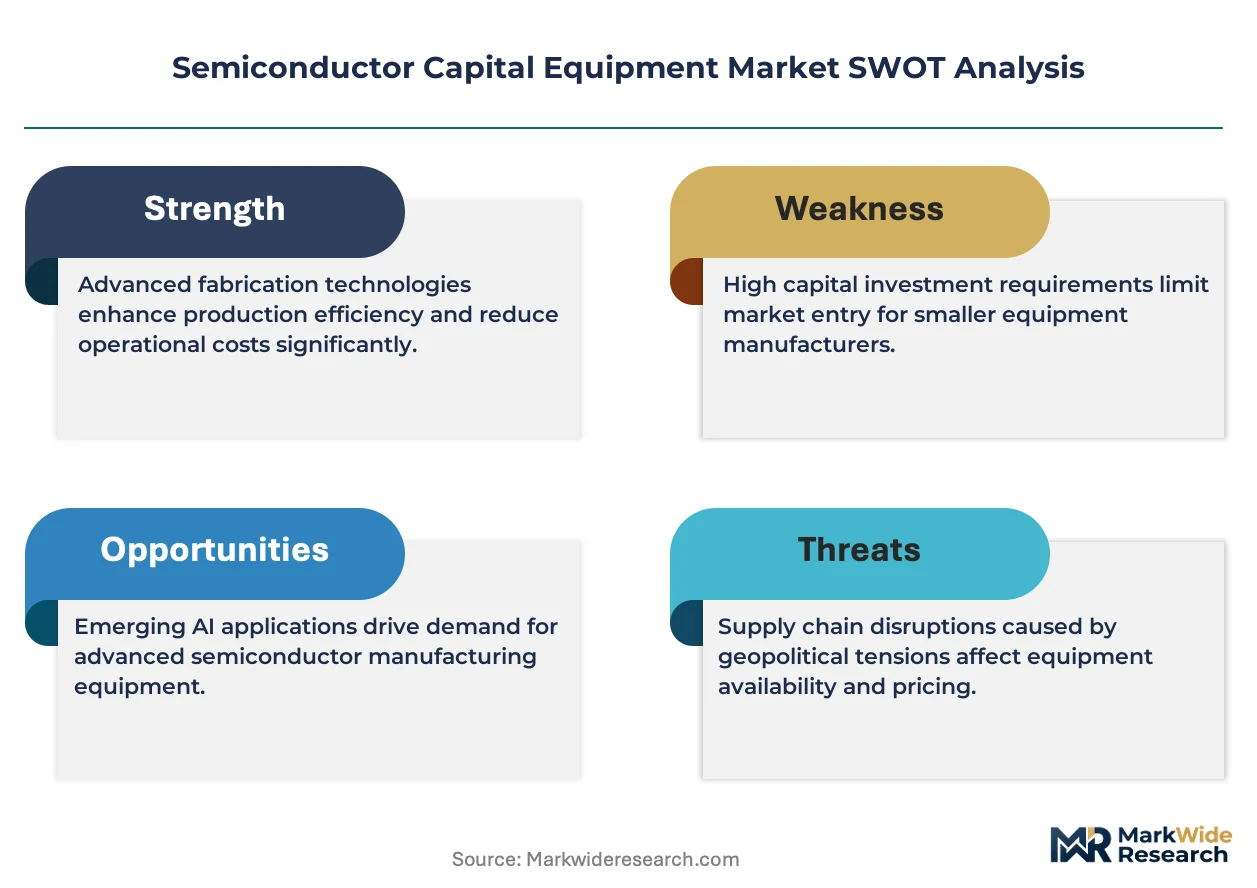
Export control frameworks administered by the US Bureau of Industry and Security, Japan's Ministry of Economy Trade and Industry, and Netherlands national authorities restrict lithography and deposition tool shipments to designated entities, directly constraining market access and redirecting demand toward alternative supplier ecosystems. REACH and RoHS compliance requirements from European regulators impose material composition standards that influence chamber design and consumables chemistry. Stakeholders must monitor evolving multilateral coordination on technology transfer restrictions while calibrating regional capacity investments against the risk of further tool-specific trade barriers.
Market Dynamics
Three-dimensional gate-all-around transistor architectures are multiplying deposition and etch process steps per wafer, forcing equipment vendors to prioritize throughput and chamber-matching precision over legacy planar-tool refresh cycles.
Growth Catalysts
- Sub-3nm Node Ramp:Foundries in Taiwan and South Korea are qualifying high-numerical-aperture EUV systems for 2025-2027 production windows, locking in multi-year tool procurement pipelines.
- CHIPS Act Disbursements:US Department of Commerce facility funding is accelerating cleanroom construction in Arizona, Texas, and New York, pulling forward demand for metrology and inspection equipment.
- Power Device Reshoring:Silicon carbide substrate capacity expansion for automotive traction inverters is driving specialized ion implant and anneal system orders.
Market Restraints
- Neon Gas Supply Concentration:Ukrainian neon purification infrastructure disruption has exposed lithography laser supply chain fragility, forcing fabs to absorb 300-400% noble gas cost volatility.
- Single-Source EUV Optics:Zeiss SMT's exclusive supply of aspheric mirror substrates for ASML systems creates irreplaceable dependency at the 0.33 NA and 0.55 NA generations.
- Export Control Fragmentation:Divergent US BIS, Japan METI, and Netherlands national licensing thresholds for deposition and lithography tools are complicating multi-fab equipment deployment planning.
Strategic Opportunities
- India Fab Incentives:Modified PLI scheme disbursements for display and semiconductor manufacturing are attracting first-mover equipment vendors to Gujarat and Assam greenfield sites.
- Advanced Packaging Integration:Hybrid bonding and through-silicon via equipment for chiplet architectures represents a process technology convergence between front-end and back-end tool categories.
- Digital Twin Deployment:Virtual commissioning of etch and deposition chambers using physics-based simulation is compressing customer acceptance timelines and reducing field engineering intensity.
Industry Challenges
- Plasma Physics Talent Scarcity:Doctoral-level expertise in computational electromagnetics and surface reaction kinetics is concentrating at a handful of university programs, constraining R&D headcount expansion.
- Legacy Node Tool Support:Maintaining service parts availability for 200mm deposition systems across fragmented automotive and industrial MCU fabs is diverting field engineering resources from advanced node priorities.
- CoO Model Standardization:Absence of unified cost-of-ownership calculation methodologies between IDM and foundry procurement teams is prolonging equipment selection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Capital Equipment Market |
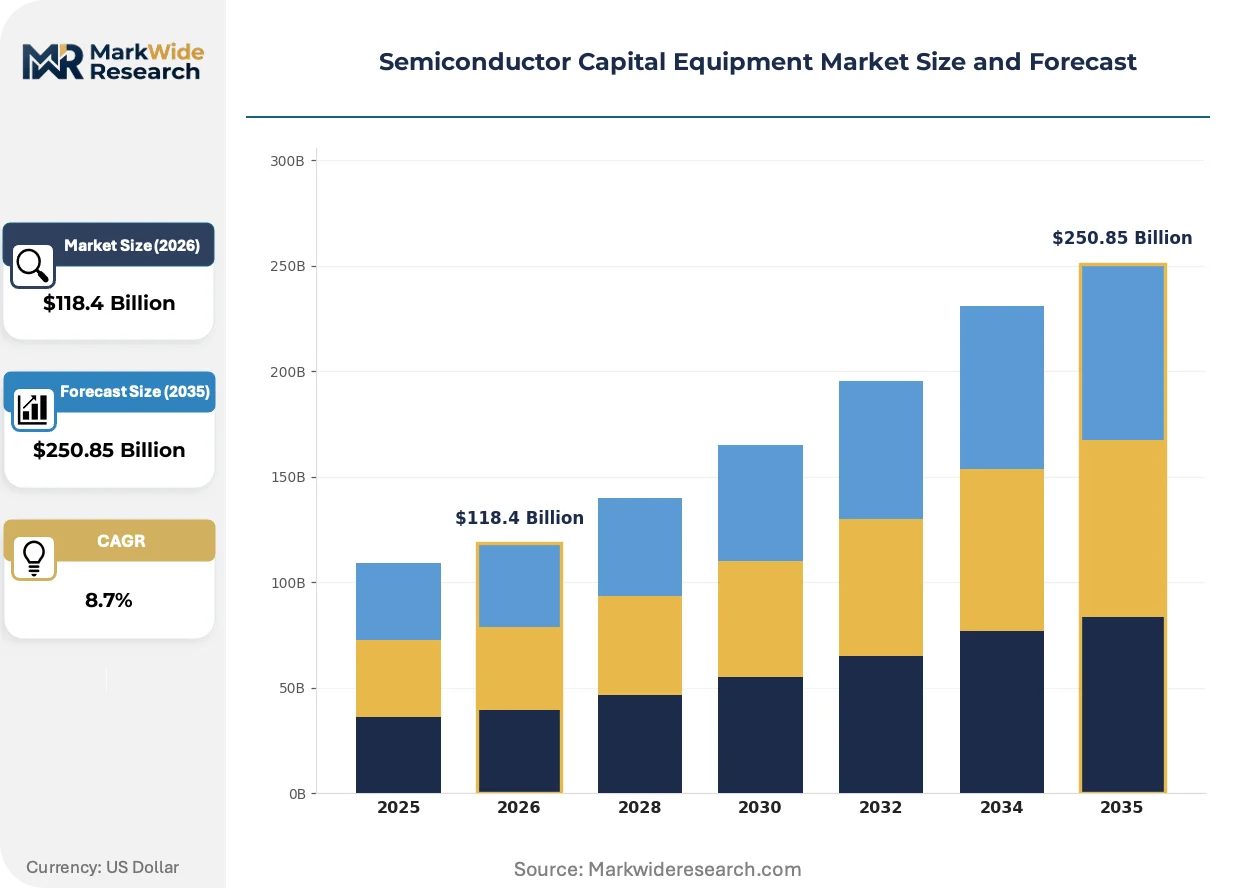
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $250.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photolithography Equipment, Etching Equipment, Deposition Equipment, Mask/Etch Tools End User: Foundries, Integrated Device Manufacturers, Outsourced Semiconductor Assembly, Test Facilities Technology: Extreme Ultraviolet Lithography, Atomic Layer Deposition, Plasma Etching, Chemical Mechanical Polishing Application: Memory Devices, Logic Devices, Analog Devices, Power Devices |
| Companies Covered | Applied Materials, ASML, Lam Research, Tokyo Electron, KLA Corporation, Advantest, ASM International, Hitachi High-Tech, SCREEN Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Capital Equipment Market Emerging Trajectories
Atomic-scale process control requirements are compressing equipment development cycles while fragmenting vendor R&D priorities across divergent transistor architectures.
Gate-all-around nanosheet transistors are miniaturizing channel dimensions below 5nm while maintaining electrostatic control, requiring atomic layer deposition systems to achieve sub-angstrom thickness uniformity across 300mm wafers. Memory manufacturers in South Korea are qualifying these tools for 3D NAND string stacking beyond 300 layers. This dimensional scaling is miniaturizing defect tolerance budgets to single-digit atom counts, forcing metrology vendors to deploy high-throughput electron beam inspection at production ramp speeds.
Japan's METI semiconductor equipment export licensing framework is expanding coverage to deposition and etch tools with sub-14nm capability, creating compliance overhead for Tokyo Electron and Hitachi Kokusai sales teams. The regulation is fragmenting customer qualification timelines as vendors segment product roadmaps into licensable and non-licensable configurations. Chinese memory and logic fabs are responding by accelerating domestic equipment vendor qualification for mature node tools.
Fab operators are unbundling equipment service contracts from original tool purchases, creating independent lifecycle revenue pools for third-party maintenance specialists. Foundries in Taiwan are leading this transition, separating warranty-period support from extended service agreements to optimize operational expenditure recognition. This procurement restructuring is most visible in the lithography segment, where ASML's service revenue density now exceeds 25% of installed base value annually.
Semiconductor Capital Equipment Market Segmentation
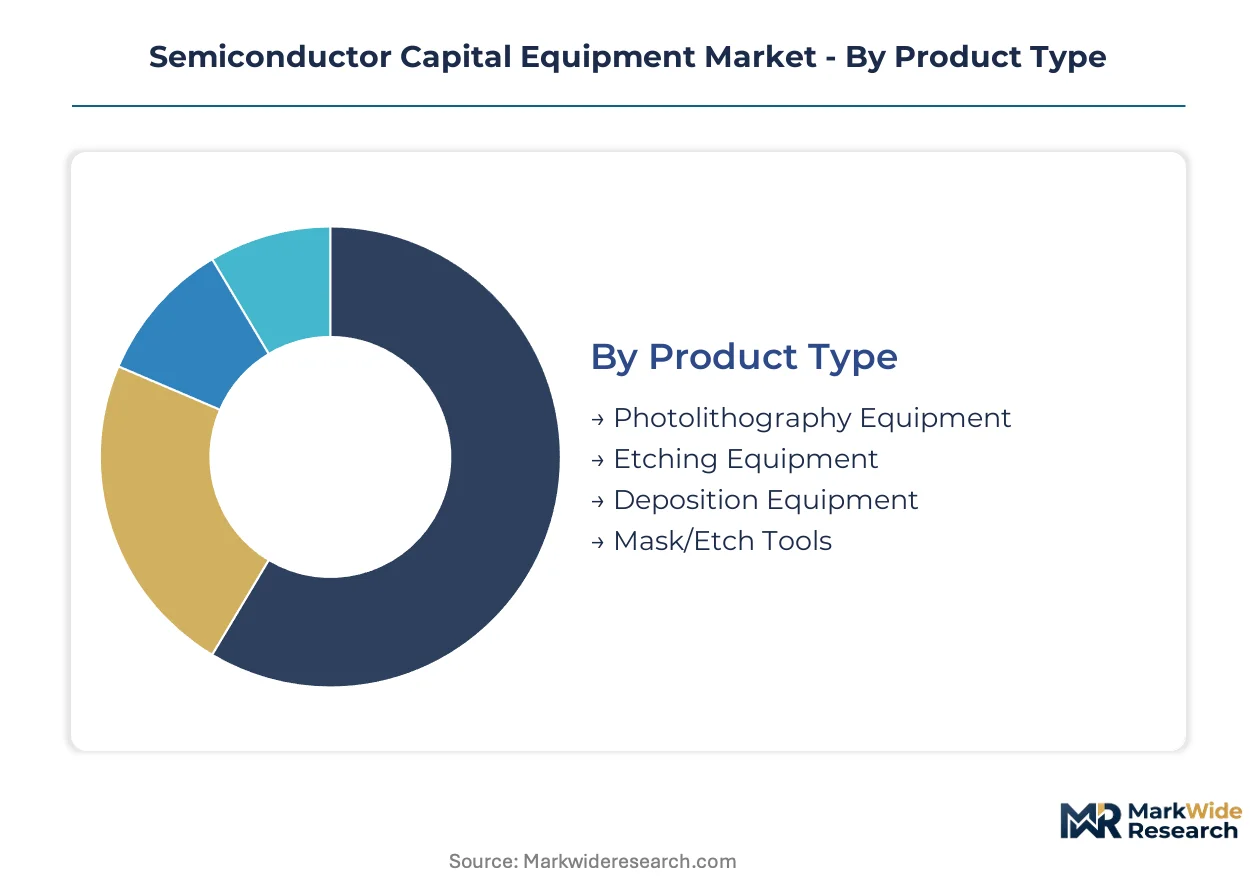
Equipment procurement patterns diverge sharply across customer types and technology nodes. Understanding these segment boundaries clarifies where vendors must align product roadmaps with distinct operational requirements and capital allocation timelines.
Product Type:
Direct sales dominate photolithography and deposition categories given installation complexity and sole-source dependencies, while etching tools flow more readily through distributor networks serving fragmented legacy node fabs.
- Photolithography Equipment:Systems achieving sub-nanometer pattern resolution through extreme ultraviolet light sources command the highest capital allocation per tool. Taiwan and South Korea foundries lock in multi-year procurement pipelines for high-numerical-aperture systems as they qualify sub-3nm production windows.
- Deposition Equipment:Atomic layer deposition and chemical vapor deposition systems create atomically uniform films across 300mm wafers. Memory manufacturers in South Korea are qualifying these tools for 3D NAND string stacking beyond 300 layers, multiplying chamber counts per fab.
- Etching Equipment:Plasma-based material removal systems achieve wafer throughputs exceeding 100 wafers per hour.
- Mask/Etch Tools:Photomask patterning and repair equipment serve leading-edge lithography qualification.
By volume, etching equipment leads. By growth pace, deposition equipment is climbing the fastest.
End User:
Cost tier segmentation separates capital-intensive leading-edge investments from operational expenditure-focused maintenance procurement.
- Foundries:Merchant manufacturers prioritize tool flexibility across multiple technology nodes to serve diverse customer portfolios. Taiwan-based foundries are unbundling service contracts from original tool purchases, creating independent lifecycle revenue pools.
- Integrated Device Manufacturers:Captive producers concentrate volume at mature technology generations for automotive and industrial applications. IDMs in the United States and Japan maintain captive 200mm capacity for analog and power device production.
- Outsourced Semiconductor Assembly:Third-party packaging and test providers procure back-end metrology and inspection systems.
- Test Facilities:Dedicated validation centers acquire probe stations and parametric test equipment.
By capital deployment scale, foundries lead. By procurement cycle stability, integrated device manufacturers hold firmer ground.
Technology:
Application requirements dictate technology selection, with logic manufacturers driving leading-edge adoption while memory producers optimize for vertical scaling.
- Extreme Ultraviolet Lithography:13.5nm wavelength systems enable single-exposure patterning at sub-7nm nodes. Netherlands national authorities administer export licensing frameworks that restrict shipments to designated entities, fragmenting customer qualification timelines.
- Atomic Layer Deposition:Self-limiting surface reactions achieve sub-angstrom thickness uniformity for gate-all-around transistor architectures. This dimensional scaling miniaturizes defect tolerance budgets to single-digit atom counts.
- Plasma Etching:Reactive ion and inductively coupled plasma systems remove material with anisotropic profiles.
- Chemical Mechanical Polishing:Slurry-based planarization creates atomically flat surfaces between deposition layers.
By installed base value, extreme ultraviolet lithography leads. By process step multiplication, atomic layer deposition is expanding most quickly.
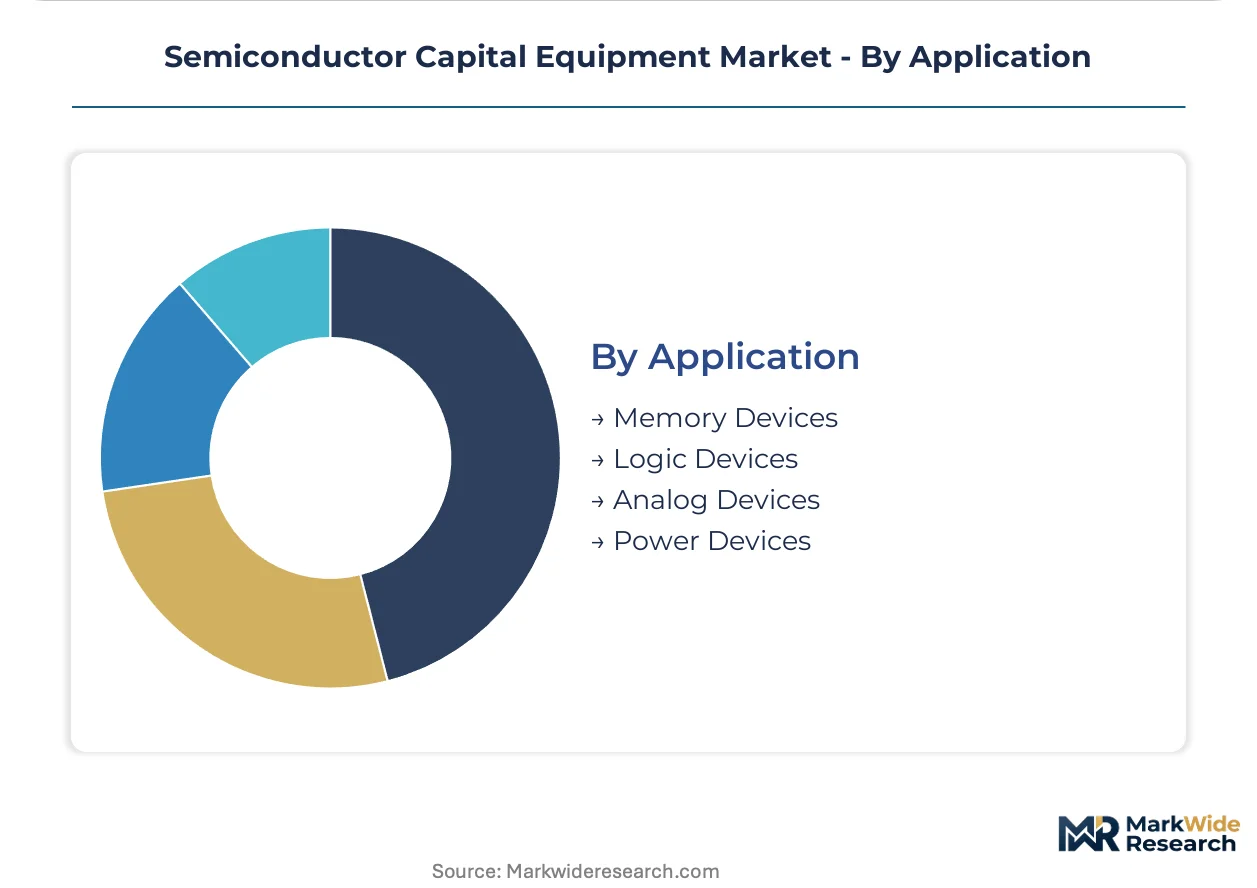
Application:
Maturity stage separates applications with stable equipment reuse from those demanding continuous technology refresh.
- Memory Devices:3D NAND and DRAM production drives deposition and etch intensity as layer counts multiply. South Korean manufacturers are qualifying atomic layer deposition tools for string stacking beyond 300 layers.
- Logic Devices:Advanced node microprocessors and mobile SoCs command priority allocation of EUV lithography systems. Taiwan foundries are qualifying high-numerical-aperture EUV for production ramp.
- Analog Devices:Mature node signal processing chips utilize 200mm and 300mm legacy equipment.
- Power Devices:Silicon carbide substrate expansion for automotive traction inverters drives specialized ion implant and anneal system orders.
By equipment intensity per wafer, memory devices lead. By node migration urgency, logic devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan, South Korea, and the United States consume semiconductor capital equipment through fundamentally different operational models. Taiwan foundries prioritize tool flexibility across multiple nodes, South Korean memory producers optimize for vertical scaling intensity, and US integrated device manufacturers concentrate procurement at mature technology generations.
United States
CHIPS Act disbursements from the Department of Commerce are accelerating cleanroom construction in Arizona, Texas, and New York. Bureau of Industry and Security export licensing frameworks restrict lithography and deposition tool shipments to designated entities. Greater Phoenix anchors the most active fab cluster, with Taiwan Semiconductor Manufacturing and Intel qualifying high-numerical-aperture EUV systems for production ramp.
South Korea
Memory manufacturers are driving atomic layer deposition tool orders for 3D NAND string stacking beyond 300 layers. Ministry of Trade, Industry and Energy subsidy frameworks support domestic equipment vendor development and greenfield fab construction. Samsung Electronics and SK Hynix in the Seoul Capital Area command priority allocation of etching and metrology systems from Tokyo Electron and KLA Corporation.
Japan
Materials engineering heritage sustains dominant positions in photoresist, substrates, and process chemicals. Ministry of Economy, Trade and Industry export licensing thresholds for sub-14nm deposition and etch tools are fragmenting customer qualification timelines. Tokyo Electron and Hitachi High-Tech in the Tokyo-Yokohama corridor face compliance overhead as they segment product roadmaps into licensable configurations.
Netherlands
ASML's extreme ultraviolet lithography monopoly concentrates critical optics and laser source expertise in Eindhoven. National authorities administer export licensing frameworks that restrict EUV system shipments to designated entities, directly constraining market access. The Brainport Eindhoven region anchors Zeiss SMT's exclusive supply of aspheric mirror substrates, creating irreplaceable dependency at 0.33 NA and 0.55 NA generations.
Taiwan
Foundries are unbundling service contracts from original tool purchases, creating independent lifecycle revenue pools. Taiwan Semiconductor Manufacturing leads procurement of high-numerical-aperture EUV systems for sub-3nm node qualification. The Hsinchu Science Park anchors the densest lithography and deposition tool installed base globally, with priority allocation from ASML and Applied Materials.
Semiconductor Capital Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in semiconductor capital equipment. Three vendors control extreme ultraviolet lithography, atomic layer deposition, and plasma etching at leading-edge nodes, while regional specialists dominate mature-node and consumables segments. Strategic archetypes include sole-source technology monopolists, broad-process portfolio integrators, and single-product deep-specialists. Competitive moves concentrate on exclusive source partnerships for critical subcomponents and physics-based digital twin deployment to compress customer acceptance timelines.
Within the integrated-leader tier, Applied Materials exemplifies broad-process portfolio coverage, ASML occupies the sole-source lithography position, and Tokyo Electron represents the Japanese materials-engineering archetype. Lam Research and KLA Corporation sit within the specialist tier with concentrated expertise in plasma processing and inspection metrology respectively. ASM International and Advantest anchor European and Japanese positions in atomic layer deposition and test equipment. These seven entities structure competitive dynamics through exclusive partnerships, service revenue unbundling, and qualification-timeline fragmentation under divergent export control regimes.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Lam Research |
| Tokyo Electron |
| KLA Corporation |
| Advantest |
| ASM International |
| Hitachi High-Tech |
| SCREEN Holdings |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for EUV lithography systems lock in multi-year price visibility for Taiwan foundries while tethering supplier capacity to named customer allocation schedules under Netherlands export licensing constraints.
Pricing Analysis
Contract-based long-term offtake dominates lithography procurement, with premium-mid-economy pricing differentiation anchored to numerical aperture capability and throughput specifications. Price differentiation stems from volume scale commitments and after-sales service bundling. Cost compression in mature-node deposition tools is intensifying because Chinese domestic vendors are qualifying alternatives for 28nm-plus processes. Integrated device manufacturers exhibit highest price sensitivity due to fixed automotive contract pass-through limitations, while foundries absorb premium pricing for node-flexibility guarantees.
Supply Chain Analysis
Strategic stockpiling of noble gases and mirror substrates has replaced just-in-time inventory norms after Ukrainian neon infrastructure disruption. Critical component supply concentrates in Germany, Japan, and the Netherlands, with Zeiss SMT aspheric optics and Cymer laser sources feeding ASML system assembly. Raw material dependencies span neon and helium isotopes, silicon carbide substrates, and fluorinated process chemicals. Single-source vulnerability at the EUV optics tier creates irreplaceable dependency. Distribution runs through direct vendor-fab relationships with field engineering teams embedded at customer sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service revenue unbundling from original equipment sales is expanding faster than hardware growth, with lithography vendors capturing lifecycle value through independent maintenance contracts and consumables replenishment.
For Market Incumbents: Compound service revenue density through predictive maintenance platforms and consumables subscription models. Defend against Chinese domestic equipment vendors by accelerating qualification timelines for mature-node alternatives. Prioritize vertical integration into laser source and optical component supply to reduce Zeiss SMT dependency exposure. For New Entrants and Emerging Players: Aftermarket service contract fragmentation creates entry paths for independent maintenance specialists targeting 200mm legacy tool installed bases. Focus initial penetration on India greenfield fabs where Modified PLI scheme disbursements are accelerating first-mover equipment procurement. Deploy digital twin commissioning capabilities to compress customer acceptance timelines against established vendor field engineering intensity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among lithography and deposition equipment vendors with installed base service attach rates exceeding hardware replacement cycles. Five-to-ten year viability favors vendors with exclusive source partnerships for critical subcomponents. Monitor export control licensing threshold harmonization across US BIS, Japan METI, and Netherlands national authorities as inflection indicator for geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Source Partnership | Zeiss SMT mirror substrate supply locks ASML into irreplaceable EUV optics dependency. |
| Service Revenue Unbundling | Taiwan foundries separate warranty support from extended agreements, creating independent lifecycle pools. |
| Digital Twin Deployment | Physics-based chamber simulation compresses customer acceptance timelines for etch and deposition tools. |
| Geographic Capacity Expansion | CHIPS Act disbursements accelerate Arizona and Texas cleanroom construction, pulling forward metrology demand. |
| Domestic Vendor Qualification | Chinese memory fabs accelerate mature-node tool qualification in response to METI licensing expansion. |
Methodological Framework
Operator-level perspectives from fab engineering directors, equipment procurement managers, field service technicians, and process integration specialists anchored the qualitative base. Primary interviews combined with secondary validation from SEC equipment vendor filings, SEMI industry association data, and national trade ministry subsidy disclosures. Bottom-up unit deployment estimates triangulated against top-down foundry and IDM capital expenditure guidance.
Sensitivity analysis tested forecast outputs against variable node migration timelines, export control licensing stringency scenarios, and noble gas supply disruption recurrence. Segmentation dimensions modeled include equipment type, end-user archetype, technology node, and regional regulatory cluster across the projection horizon. CAGR derivation incorporated equipment intensity per wafer trends, process step multiplication factors for 3D architectures, and service revenue attach rate trajectories.
Underlying assumptions cover sustained sub-3nm node ramp schedules, stable multilateral export control coordination, and continued EUV source power scaling, with deviation risk concentrated in licensing threshold fragmentation and domestic equipment vendor acceleration in China. Revision becomes warranted when export control harmonization crosses divergence thresholds or when high-numerical-aperture EUV qualification timelines extend beyond modeled windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Semiconductor CVD Equipment Market