
 Printed Circuit Board Market | 2026-2036
Printed Circuit Board Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Circuit Board Market Intelligence
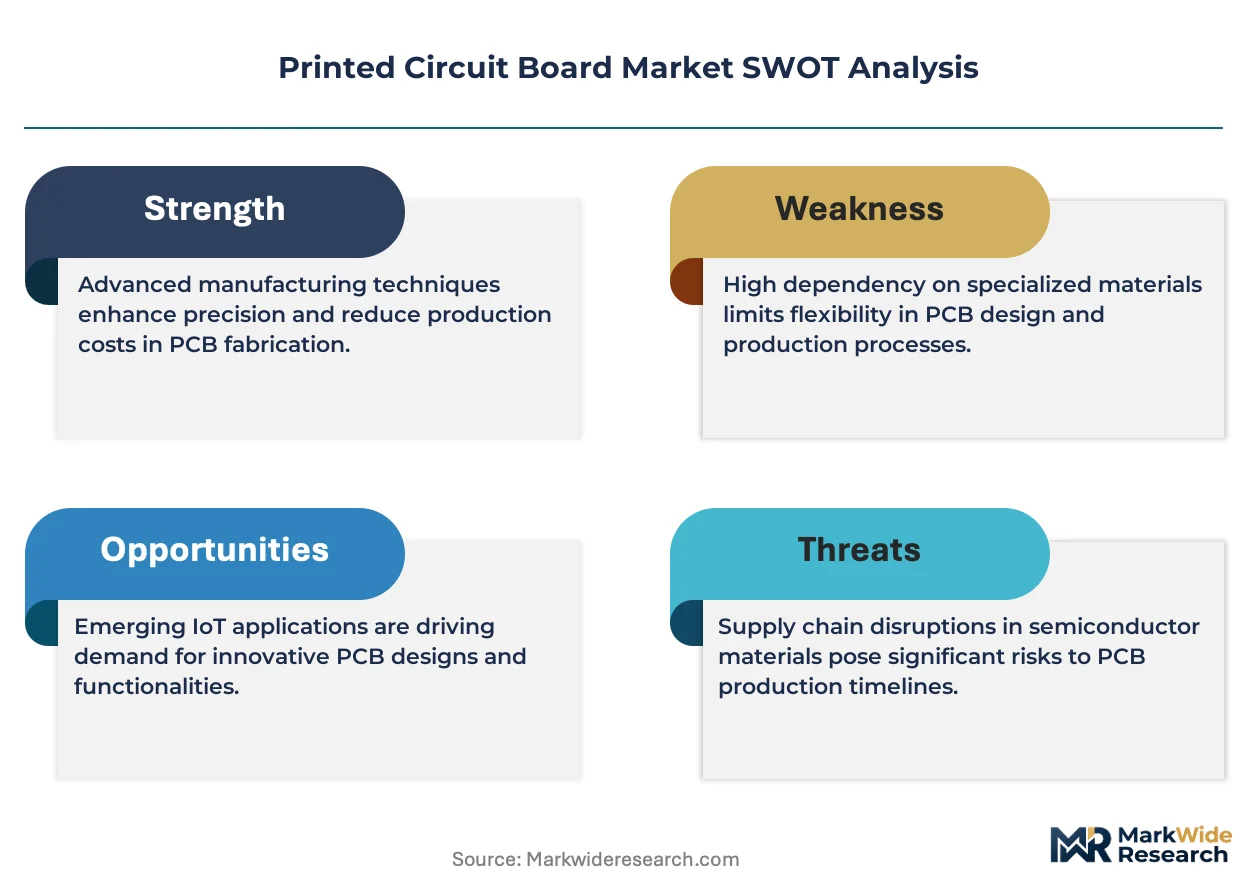
IPC-6012 qualification for rigid printed circuit boards is collapsing the supplier base as Tier-1 OEMs enforce Class 3 reliability mandates for automotive and aerospace programs. TTM Technologies dominates North American military and aerospace board supply through captive facilities in California and Wisconsin. Sanmina Corporation anchors high-mix, low-volume production for medical and industrial instrumentation. Jabil leverages global manufacturing footprints across Mexico and China to serve consumer electronics brands with compressed lead times.
A printed circuit board is a non-conductive substrate laminated with copper foil traces that electrically interconnect discrete components through plated vias and surface-mount pads, typically manufactured via photolithographic etching or laser direct imaging with line/space resolutions below 50 micrometers. Its primary purpose is to provide mechanical support and signal routing for electronic assemblies in everything from smartphones to satellite systems. Multi-layer boards now capture the dominant share of value as data rates exceed 10 Gbps and power integrity demands grow. Rigid-flex configurations are expanding fastest in medical wearables and foldable consumer devices where dynamic bending cycles exceed hundreds of thousands. FR-4 remains the volume substrate but faces margin pressure from halogen-free alternatives and polyimide films in high-temperature automotive applications.
FCC electromagnetic compatibility rules in the United States constrain board layer stack-ups and shielding designs for telecommunications infrastructure. EPA hazardous waste regulations govern copper etchant recovery and spent solvent disposal at fabrication plants. ECHA REACH substance restrictions in Europe limit brominated flame retardants and specific phthalate plasticizers in laminate resins. Stakeholders must monitor how substrate material certifications, regional chemical bans, and OEM sustainability scorecards collectively reshape qualified supplier lists and procurement geography.
Market Dynamics
Substrate material certification requirements under IPC-6012 Class 3 are collapsing the qualified supplier base as Tier-1 automotive and aerospace OEMs enforce reliability mandates that disqualify legacy fabricators.
Growth Catalysts
- Electrified powertrain proliferation:Battery management systems and inverter modules in electric vehicles require heavy-copper boards with thermal management capabilities that standard consumer-grade suppliers cannot manufacture.
- ECHA REACH substance restrictions:European mandates on brominated flame retardants and phthalate plasticizers are accelerating halogen-free laminate adoption, creating first-mover advantages for qualified resin formulators.
- Advanced driver-assistance systems:Radar and LiDAR sensor modules demand high-frequency substrates with controlled dielectric constants below 3.5, pulling specialized material science capabilities into automotive supply chains.
Market Restraints
- Copper foil supply concentration:Electrodeposited copper foil for fine-line etching concentrates among Japanese and Chinese metallurgical suppliers, exposing fabricators to raw material allocation risk during capacity crunches.
- FR-4 thermal limitation:Glass-reinforced epoxy laminates degrade above 130°C continuous operation, forcing costly substrate substitutions in underhood automotive modules and power electronics.
- EPA hazardous waste governance:Spent ammoniacal etchant and solvent recovery requirements add fixed compliance costs that disproportionately burden mid-volume fabrication facilities in the United States.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor and component manufacturing are attracting substrate and fabrication investments to Gujarat and Tamil Nadu clusters.
- Foldable device rigid-flex integration:Dynamic bending cycles exceeding 200,000 repetitions in consumer electronics are creating specification gaps that specialized polyimide adhesive suppliers can exploit.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for electronics waste are incentivizing design-for-recycling protocols that favor easily separable substrate-metal constructions.
Industry Challenges
- IPC-6012 Class 3 certification timelines:Qualification protocols spanning 12-18 months for automotive and aerospace programs delay revenue recognition and strain working capital for fabrication entrants.
- Laser direct imaging technician scarcity:Operation of LDI systems for sub-25 micrometer line/space resolution requires specialized photolithography expertise that vocational programs have not scaled to match equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Circuit Board Market |
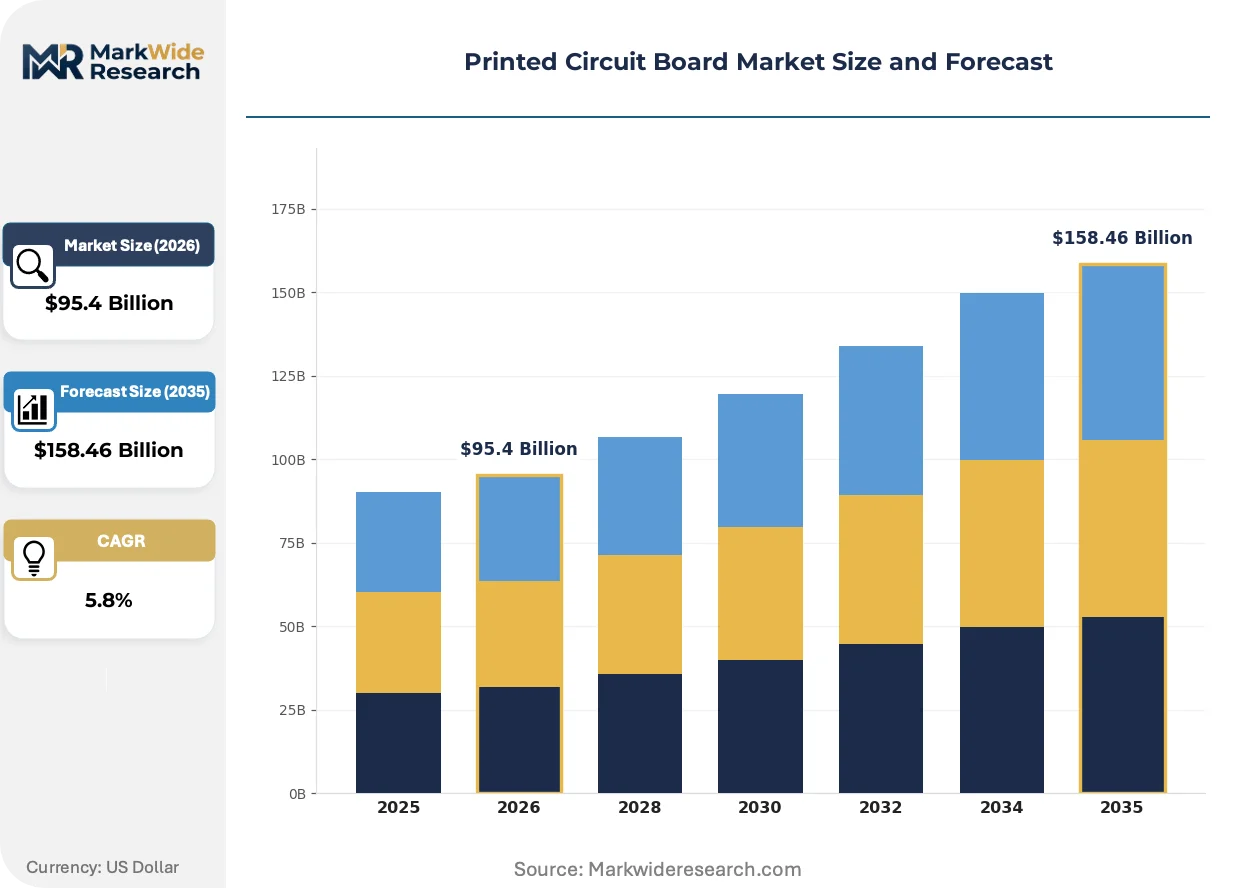
| Market Size in 2026 | $95.4 Billion |
| Market Size in 2035 | $158.46 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Rigid-Flex Material: FR-4, Polyimide, Aluminum, Copper End User: Consumer Electronics, Telecommunications, Automotive, Healthcare Manufacturing Process: Screen Printing, Photo Etching, Laser Cutting, Surface Mount Technology |
| Companies Covered | Flex, Summit Interconnect, TTM Technologies, APCT, Sierra Circuits, Sanmina Corporation, Benchmark Electronics, Advanced Circuits, Jabil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Circuit Board Market Strategic Shifts & Innovations
Photolithographic processing capabilities are diverging between commodity consumer boards and mission-critical applications, with equipment investments and process control methodologies separating into distinct competitive tiers.
Embedded die packaging with copper-pillar interconnects is bifurcating the substrate market between traditional laminate fabricators and semiconductor packaging houses. Automotive module suppliers at Continental and Bosch are migrating power stage integration into embedded die configurations to reduce parasitic inductance. This technology compression is eliminating the historical boundary between PCB fabrication and wafer-level packaging, forcing laminate suppliers to develop low-loss dielectric materials compatible with chip-attach reflow temperatures.
China MIIT GB standards for halogen-free substrates are accelerating material substitution timelines faster than European REACH implementation schedules. Domestic substrate producers in Jiangsu and Guangdong provinces are achieving scale in modified epoxy formulations that satisfy both environmental mandates and cost targets for consumer electronics. High-volume smartphone OEMs are responding by consolidating qualified supplier lists around Chinese resin compounders with captive glass-weaving operations.
Consolidated procurement through electronic component distributors is displacing direct mill relationships for sub-10,000 unit production runs. Medical device and industrial instrumentation OEMs in Germany and Switzerland are channeling laminate and pre-preg purchases through Arrow Electronics and Avnet to compress vendor management overhead. This intermediation is most visible in Alpine and Mittelstand manufacturing regions where procurement headcount constraints favor consolidated supplier portals over direct technical engagement with substrate mills.
Printed Circuit Board Market Segmentation
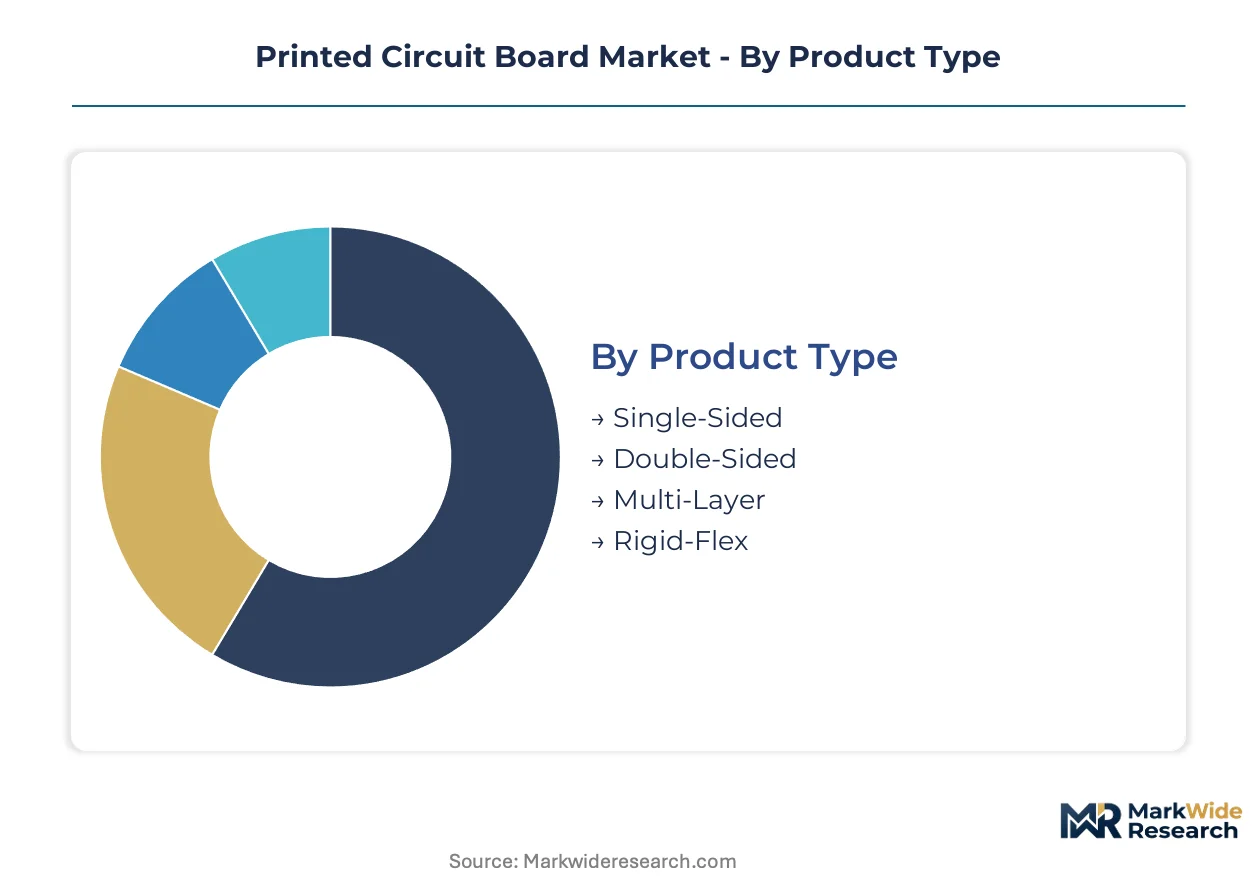
PCB segmentation reveals how regulatory pressure and application complexity split manufacturing capabilities into non-interchangeable tiers. Material certifications and process controls now determine supplier eligibility more than scale or geography.
Product Type:
IPC-6012 Class 3 mandates disqualify single-sided fabricators from automotive and aerospace procurement, while consumer electronics tolerances permit broader supplier participation.
- Single-Sided:Copper traces on one substrate face serve cost-sensitive appliances and basic lighting controls. Demand concentrates in Southeast Asian contract manufacturers supplying white goods OEMs; EPA hazardous waste rules on etchant recovery burden US-based production.
- Double-Sided:Plated through-holes interconnect copper layers on both faces, supporting industrial sensors and power supplies. European REACH substance restrictions on brominated flame retardants are accelerating halogen-free laminate migration in German industrial automation supply chains.
- Multi-Layer:Stacked laminates with buried and blind vias route high-speed signals in data center switches and 5G base stations.
- Rigid-Flex:Hybrid constructions combining stable sections with dynamic bending zones serve medical imaging equipment and aerospace avionics.
Multi-layer boards handle the majority of throughput; rigid-flex is gaining share fastest in medical and aerospace procurement.
Material:
Cost tiers separate commodity substrates from specialty formulations required for thermal and electrical performance.
- FR-4:Glass-reinforced epoxy laminate remains the volume standard for consumer electronics and industrial controls. Chinese MIIT GB standards for halogen-free formulations are forcing faster material substitution than European REACH schedules, consolidating procurement around Jiangsu and Guangdong resin compounders.
- Polyimide:High-temperature films withstand continuous operation above 200°C in underhood automotive modules and downhole oil instrumentation. Battery management system integration in electric vehicles is pulling specialized polyimide supply into automotive Tier-1 qualification programs.
- Aluminum:Metal-core substrates dissipate heat from LED lighting and power conversion modules.
- Copper:Heavy-copper boards above 3 oz/ft² carry current in electric vehicle inverters and welding equipment.
FR-4 dominates volume; polyimide shows the steepest expansion trajectory as automotive electrification accelerates.
End User:
Application-specific reliability requirements fragment procurement channels and qualification timelines.
- Consumer Electronics:Smartphones, laptops, and wearables demand fine-line resolution below 25 micrometers with compressed lead times. Production concentrates in Chinese fabrication clusters serving Apple, Samsung, and domestic OEMs; FCC electromagnetic compatibility rules constrain layer stack-ups for devices sold in the United States.
- Telecommunications:Base stations, routers, and optical transport equipment require controlled impedance for 10 Gbps+ signaling. 5G mmWave deployment in South Korea and Japan is pulling high-frequency substrate demand toward specialized material suppliers with dielectric constant precision below 3.5.
- Automotive:Advanced driver-assistance systems and electrified powertrains impose thermal cycling and vibration standards.
- Healthcare:Diagnostic imaging and patient monitoring equipment demand IPC-6012 Class 3 reliability with biocompatibility certifications.
Consumer electronics commands the largest volume; automotive is expanding most quickly as electrification penetrates vehicle platforms.
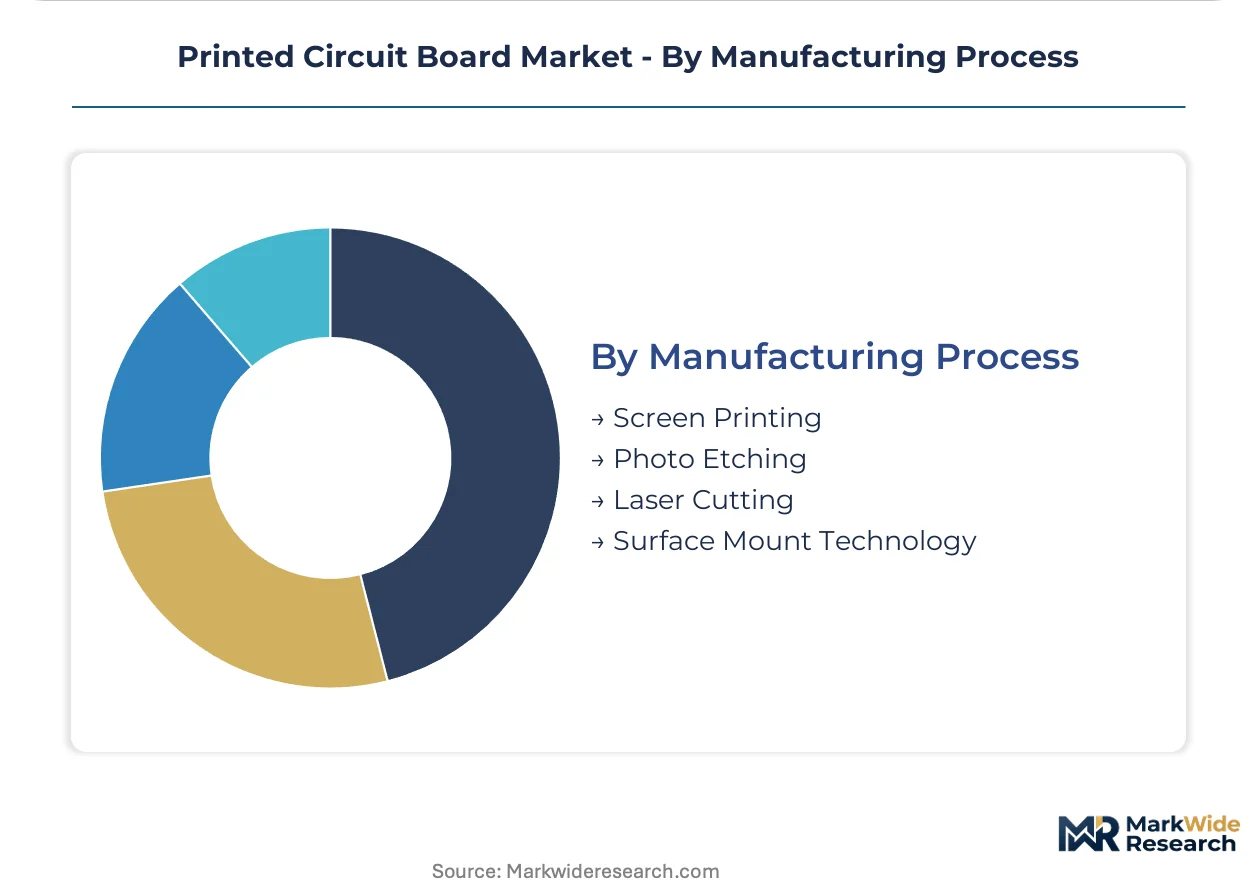
Manufacturing Process:
Volume scale and precision requirements separate process technologies into distinct competitive tiers.
- Screen Printing:Stencil-based solder paste and legend application serves high-volume consumer board production. Mexican and Chinese facilities serving North American OEMs leverage this mature process for cost-sensitive assemblies.
- Photo Etching:Photolithographic copper removal defines traces with 50 micrometer line/space resolution. Japanese electrodeposited copper foil suppliers concentrate feedstock supply, exposing fabricators to allocation risk during capacity crunches.
- Laser Cutting:Direct ablation creates microvias and complex board profiles without mechanical tooling.
- Surface Mount Technology:Automated component placement and reflow soldering completes assembly sequences.
Photo etching handles the majority of precision throughput; laser cutting is climbing the fastest as via density requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex and Pearl River Delta logistics corridor underwrite China's dominance in substrate feedstock and finished board exports. Dense fabrication clusters in Jiangsu and Guangdong provinces leverage this infrastructure to compress lead times for consumer electronics OEMs.
China
Domestic substrate production and downstream PCB fabrication clusters have achieved unmatched scale in Jiangsu and Guangdong provinces. MIIT GB standards for halogen-free substrates are accelerating material substitution timelines faster than European REACH schedules. High-volume smartphone OEMs are consolidating qualified supplier lists around Chinese resin compounders with captive glass-weaving operations in the Pearl River Delta.
United States
Advanced driver-assistance systems and electrified powertrains from Detroit and Austin OEMs are pulling specialized PCB demand toward heavy-copper and high-frequency substrates. EPA hazardous waste regulations govern copper etchant recovery and spent solvent disposal at fabrication plants in California and Wisconsin. TTM Technologies anchors North American military and aerospace board supply through captive facilities serving defense primes.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg demand IPC-6012 Class 3 reliability for sensor modules and power electronics. ECHA REACH substance restrictions limit brominated flame retardants and specific phthalate plasticizers in laminate resins. Mittelstand manufacturers in Alpine regions are channeling laminate purchases through consolidated distributor portals to compress vendor management overhead.
India
Production-linked incentive schemes for semiconductor and component manufacturing are attracting substrate and fabrication investments to Gujarat and Tamil Nadu clusters. BIS certification requirements for electronic components are tightening material traceability standards. Domestic EMS providers in Bengaluru and Chennai are expanding captive PCB assembly capacity to serve telecom infrastructure rollouts.
Japan
Electrodeposited copper foil suppliers concentrate feedstock supply for fine-line etching, exposing fabricators to allocation risk during capacity crunches. METI industrial standards govern high-frequency substrate specifications for 5G base station deployments. Osaka and Nagoya metropolitan areas host specialized material science capabilities for controlled dielectric constant formulations below 3.5.
Printed Circuit Board Market Key Industry Players
Listed leaders compete with private specialists across certification tiers and end-market focus. The supplier base stratifies between scale-driven commodity fabricators and qualification-heavy mission-critical specialists. Three archetypes dominate: captive aerospace-military suppliers, high-mix medical-industrial operators, and consumer electronics volume players. M&A activity concentrates on acquiring IPC-6012 Class 3 certifications and geographic expansion into India and Southeast Asia.
Among North American fabricators, TTM Technologies, Sanmina Corporation, and Jabil occupy distinct competitive positions. TTM Technologies exemplifies the captive aerospace-military archetype through California and Wisconsin facilities. Sanmina Corporation anchors high-mix, low-volume production for medical and industrial instrumentation. Jabil represents scale-driven consumer electronics supply with global manufacturing footprints across Mexico and China.
| Leading Market Players |
|---|
| Flex |
| Summit Interconnect |
| TTM Technologies |
| APCT |
| Sierra Circuits |
| Sanmina Corporation |
| Benchmark Electronics |
| Advanced Circuits |
| Jabil |
| Others |
Cost & Logistics Intelligence
Twenty-one-day laminate lead times from Jiangsu substrate mills signal how Pearl River Delta fabrication clusters translate geographic concentration into procurement leverage over North American OEMs. This inventory compression dynamic separates buyers locked into annual contracts from spot-market participants exposed to copper foil allocation volatility.
Pricing Analysis
Three-tier pricing structure across IPC-6012 Class 3 certified, industrial-grade, and consumer-tier fabrication separates automotive-aerospace procurement from commoditized consumer electronics. Price differentiation hinges on reliability certification tier and heavy-copper processing capability, with halogen-free laminate mandates from ECHA REACH adding formulation premiums to European-bound shipments. Cost compression in consumer-grade multilayer boards is intensifying as Chinese MIIT GB standards accelerate domestic resin compounder scale. Medical device OEMs in Germany and Switzerland show lowest price sensitivity due to IPC-6012 Class 3 qualification barriers, while Southeast Asian white-goods contract manufacturers operate on thinnest margins.
Supply Chain Analysis
Inbound logistics costs through Shenzhen port congestion and trans-Pacific container availability swings expose North American fabricators to working capital strain during allocation crunches. Electrodeposited copper foil supply concentrates in Japan and China, with Japanese metallurgical suppliers anchoring fine-line etching feedstock for sub-25 micrometer resolution boards. Raw material dependencies span glass-weaving operations in Jiangsu, modified epoxy resin formulations from Guangdong compounders, and brominated flame retardant alternatives pressured by REACH substance restrictions. Single-source vulnerability concentrates in electrodeposited copper foil during capacity crunches. Distribution runs through consolidated electronic component distributors for sub-10,000 unit medical and industrial runs, while high-volume consumer electronics channels direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printed circuit board incumbents face substitution pressure from embedded die packaging with copper-pillar interconnects, as semiconductor packaging houses compress the historical boundary with traditional laminate fabricators.
For Market Incumbents: Consolidate IPC-6012 Class 3 certification portfolios through targeted acquisition of qualified aerospace fabricators in California and Wisconsin, defending against embedded die packaging migration by Continental and Bosch. Backward integration into halogen-free resin formulation capabilities secures first-mover positioning under ECHA REACH implementation timelines. Capacity discipline in FR-4 commodity tiers preserves margin structure against Chinese domestic substrate scale. For New Entrants and Emerging Players: IPC-6012 Class 3 fast-track qualification programs open procurement channels to German Mittelstand industrial automation OEMs in Bavaria and Baden-Württemberg, where distributor consolidation has created technical engagement gaps. India's PLI schemes for Gujarat and Tamil Nadu substrate clusters offer greenfield fabrication positioning with BIS certification as entry barrier. Go-to-market leverage rests on rigid-flex polyimide specialization for medical wearable bending-cycle specifications exceeding 200,000 repetitions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with captive PCB divisions lacking standalone scale to justify IPC-6012 Class 3 reinvestment. Long-term viability over a decade horizon favors specialists with automotive electrification exposure and embedded die packaging compatibility. Signal to monitor: MIIT GB standard acceleration pulling halogen-free laminate substitution ahead of European REACH schedules, reshaping qualified supplier list consolidation dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| IPC-6012 Class 3 Certification Acquisition | Unlocks Tier-1 automotive and aerospace procurement channels requiring reliability mandates. |
| Halogen-Free Laminate Formulation Investment | Captures ECHA REACH compliance premiums ahead of material substitution timelines. |
| India Manufacturing Footprint Establishment | Positions for PLI scheme benefits in Gujarat and Tamil Nadu substrate clusters. |
| Embedded Die Packaging Capability Integration | Responds to Continental and Bosch power stage integration eliminating PCB-packaging boundaries. |
| Rigid-Flex Polyimide Specialization | Addresses medical wearable specifications requiring 200,000-plus dynamic bending cycles. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with PCB fabrication plant managers, Tier-1 automotive procurement leads, laminate resin R&D directors, and electronic component distributor category managers. Secondary validation drew from EPA hazardous waste enforcement records, ECHA REACH substance restriction filings, MIIT GB standard publications, and SEC 10-K disclosures from listed fabrication groups. Bottom-up capacity assessments across Jiangsu and Guangdong clusters were triangulated against top-down demand modeling from OEM bill-of-materials analysis.
Across the analysis window, the forecasting framework modeled PCB segmentation by product type, substrate material tier, end-use application, and manufacturing process technology. CAGRs were derived from production capacity expansion schedules, OEM platform electrification roadmaps, and regulatory substitution timelines for halogen-free formulations. Industry-specific inputs incorporated electrodeposited copper foil allocation cycles, IPC-6012 Class 3 qualification queue lengths, and rigid-flex medical device bending-cycle specification trajectories.
Underlying assumptions cover laminate lead-time stability and REACH implementation adherence, with deviation risk concentrated in copper foil supply crunches and embedded die packaging adoption velocity. Recalibration cycles align with material shifts in automotive electrification penetration and Chinese environmental standard acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Wall Charger Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Microspeaker Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Screw Washer Market
Electronic Components
Flexible Heater Market
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
North America USB Retimer Market
Electronic Components
Motherboard Market
Electronic Components
Audio Capacitor Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Digital Isolator Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market