
 ATX Motherboards Market | 2026-2036
ATX Motherboards Market Size, Share, and Industry Trends Forecast 2026-2036
ATX Motherboards Market Insights
Gaming enthusiasts are rotating toward high-refresh-rate display configurations that demand motherboard-level bandwidth headroom. ASUS leverages in-house PCB fabrication to sustain premium positioning across overclocking-capable boards. MSI anchors its competitive stance through specialized thermal engineering for extended ATX workstation builds. Gigabyte Technology differentiates via aggressive feature stacking across RGB lighting and Wi-Fi connectivity tiers.
An ATX motherboard is a standardized printed circuit board measuring 305 by 244 millimeters that hosts the CPU socket, memory slots, expansion buses, and chipset interconnects to coordinate data flow between subsystems. Its primary commercial purpose is to provide a modular platform for system builders and OEM manufacturers to assemble compatible computing systems without custom engineering. Standard ATX retains the largest installed base among form factors, while Extended ATX captures disproportionate margin pools in server-adjacent and multi-GPU workstation deployments. Socket type segmentation shows AM4 sustaining relevance in upgrade-path markets even as LGA 1700 and AM5 architectures displace legacy interfaces in new builds.
FCC electromagnetic emissions certification in the United States and CE marking under EU RoHS and REACH frameworks constrain PCB material selection and solder composition across export-bound production. China's MIIT enforces GB standards for domestic electromagnetic compatibility that foreign manufacturers must satisfy for market access. Stakeholders must monitor how impending EU Ecodesign requirements for standby power and material recyclability will reshape bill-of-materials decisions and regional product variant strategies.
Market Dynamics
PCIe 5.0 interface proliferation and DDR5 memory controller integration are compressing thermal design margins and forcing PCB layer-count escalation across mid-range and premium board tiers.
Growth Catalysts
- Esports hardware refresh cycles:Gaming enthusiasts now replace motherboards every 18-24 months to maintain competitive frame rates, creating sustained replacement demand independent of CPU socket transitions.
- MIIT GB standards compliance:China's domestic electromagnetic compatibility certification requirements for MIIT registration accelerate local production capacity expansion and captive supply chain development.
- Multi-GPU workstation builds:Extended ATX form factors capture disproportionate margin pools in server-adjacent deployments where thermal headroom and expansion slot density command pricing premiums.
Market Restraints
- Copper and resin input cost volatility:PCB substrate materials face pricing pressure from commodity fluctuations that compress gross margins on volume-oriented Micro ATX SKUs.
- FCC Part 15 certification timelines:United States electromagnetic emissions testing creates 8-12 week launch delays that disadvantage smaller board vendors against vertically integrated competitors with in-house compliance labs.
- Socket architecture fragmentation:Concurrent AM4, AM5, and LGA 1700 ecosystems force inventory duplication and working capital intensity for distributors serving upgrade-path markets.
Strategic Opportunities
- India system builder channel expansion:BIS certification harmonization with IEC standards reduces import friction for premium ATX boards targeting domestic gaming café and content creator verticals.
- EU Ecodesign standby power mandates:Impending efficiency requirements for idle-state consumption create first-mover advantage for vendors with integrated power management firmware.
- PCIe 5.0 and CXL convergence:Memory expansion and accelerator attachment protocols are merging, enabling motherboard-level disaggregation of compute and memory subsystems for workstation builds.
Industry Challenges
- High-speed signal integrity engineering talent scarcity:DDR5-6400+ and PCIe 5.0 layout expertise concentrates among senior PCB designers at Taiwanese and Korean fabrication houses, constraining design cycle velocity for second-tier vendors.
- RoHS solder composition transitions:REACH substance restriction updates force qualification of alternative alloy compositions that risk thermal fatigue failures in extended ATX multi-VRM configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATX Motherboards Market |
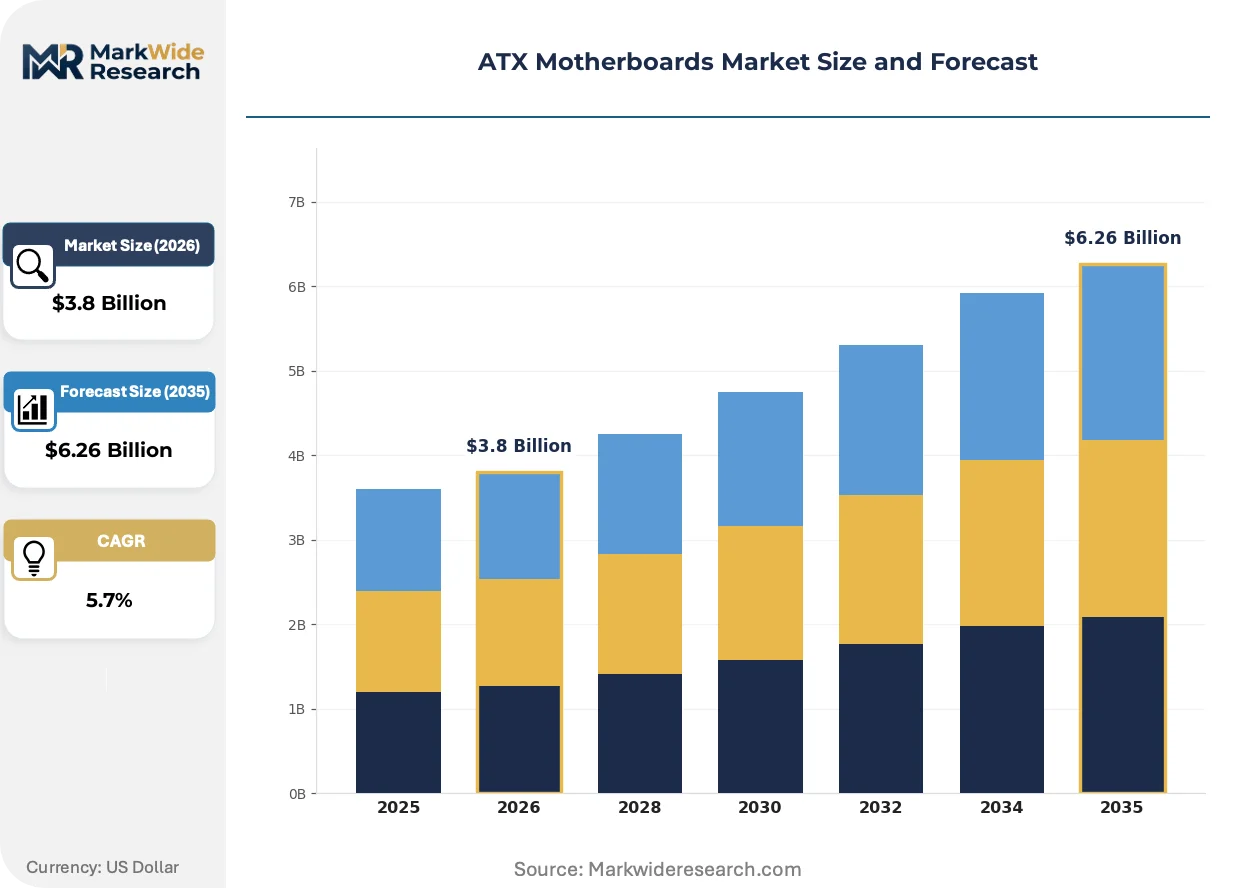
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form Factor: Standard ATX, Micro ATX, Mini ATX, Extended ATX Socket Type: LGA 1151, LGA 1200, AM4, LGA 2066 Features: RGB Lighting, Wi-Fi Connectivity, Overclocking Support, Multiple GPU Slots End User: Gaming Enthusiasts, System Builders, OEM Manufacturers, Commercial Users |
| Companies Covered | ASUS, MSI, Gigabyte Technology, ASRock, Supermicro, Advantech, Intel, Biostar, Colorful, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATX Motherboards Market Trends and Innovations
Active cooling integration and power delivery subsystem densification are redefining motherboard industrial design priorities. Vendors now compete on thermal engineering rather than port count alone.
PCIe 5.0 signaling is decomposing traditional motherboard layout constraints by demanding retimer chips and thicker PCB substrates that increase bill-of-materials costs by 15-20 percent. Gaming enthusiasts and workstation builders absorb these premiums for bandwidth headroom. The technology is compressing mid-range board margins while concentrating profitability at the premium tier where thermal and signal integrity investments differentiate.
EU Ecodesign requirements for standby power consumption and material recyclability are reshaping component selection and firmware development roadmaps. The regulations mandate sub-0.5 watt idle states and standardized disassembly documentation. Extended ATX workstation boards face the steepest compliance costs due to multi-phase VRM complexity and larger PCB surface areas requiring recycled copper verification.
Direct-to-system-builder procurement is displacing traditional distribution layers in China and Southeast Asia. Domestic OEM manufacturers now negotiate annual volume contracts with board vendors, bypassing regional distributors. This channel compression is most advanced in Guangdong and Jiangsu provinces where integrated PC assembly clusters consolidate purchasing power and enforce just-in-time delivery terms.
ATX Motherboards Market Segmentation
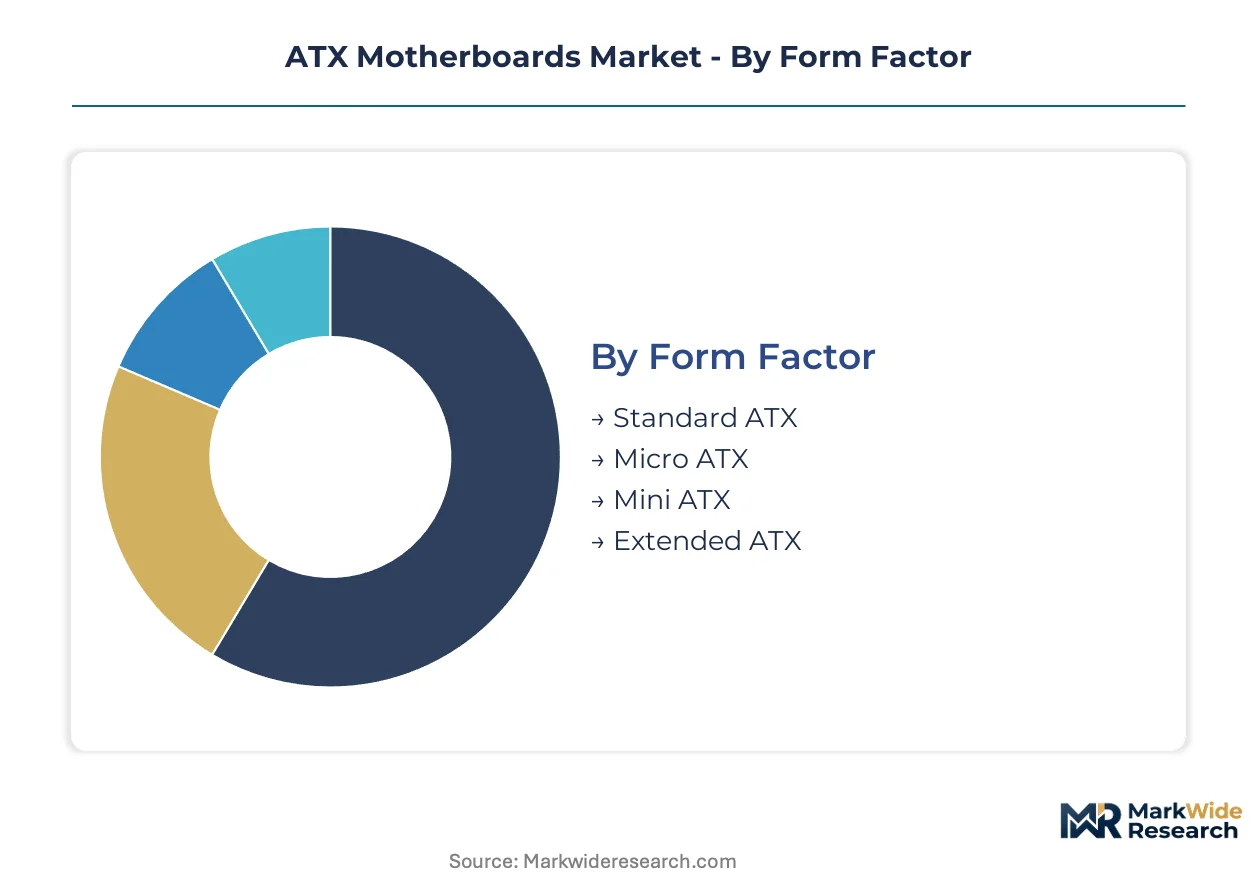
Form factor selection dictates thermal design margins and expansion slot density, directly constraining which CPU architectures and memory standards a build can accommodate. Socket compatibility creates upgrade-path dependencies that lock users into specific chipset ecosystems for 3-5 year cycles. Feature differentiation and end-user segmentation determine margin capture, with enthusiast-grade capabilities commanding pricing premiums over volume-oriented configurations.
Form Factor:
Substitution pressure intensifies as Mini ATX encroaches on Micro ATX territory in compact gaming builds, while Extended ATX defends workstation strongholds against emerging E-ATX variants from domestic Chinese manufacturers.
- Standard ATX:The 305 by 244 millimeter specification remains the reference design for consumer motherboards, accommodating dual-GPU configurations and full-size cooling solutions. Demand concentrates among gaming enthusiasts in China and the United States who prioritize expansion flexibility over chassis compactness, though PCIe 5.0 signal integrity requirements are forcing PCB layer-count escalation that compresses mid-tier margins.
- Micro ATX:Reduced 244 by 244 millimeter footprint sacrifices two expansion slots versus Standard ATX while retaining dual-channel memory and single-GPU capability. System builders in India and Southeast Asia favor this form factor for cost-optimized gaming café deployments where per-unit chassis volume determines freight economics, though copper and resin input volatility squeezes gross margins on high-volume SKUs.
- Mini ATX:Compact 170 by 170 millimeter design integrates directly into small-form-factor enclosures for streaming and living-room gaming applications.
- Extended ATX:Oversized 305 by 330 millimeter variant serves multi-GPU workstation and server-adjacent builds where thermal headroom and VRM phase density justify pricing premiums.
Standard ATX anchors the volume base while Mini ATX gains share at the steepest rate.
Socket Type:
Cost tier stratification separates legacy upgrade-path markets from new-build premiums, with AM4 sustaining relevance in budget-conscious segments as LGA 1700 and AM5 architectures capture enthusiast refresh cycles.
- AM4:AMD's long-lived PGA socket supports Ryzen 5000-series processors and maintains backward compatibility across four chipset generations. Demand concentrates in Eastern European and Latin American upgrade-path markets where CPU retention strategies extend platform lifecycles, though inventory duplication across AM4, AM5, and Intel alternatives strains distributor working capital.
- LGA 1700:Intel's 12th and 13th generation Core processor interface introduces hybrid performance-core and efficiency-core architectures with DDR5 memory support. Gaming enthusiasts in Germany, South Korea, and the United States absorb platform-switching costs for PCIe 5.0 bandwidth headroom, creating sustained replacement demand independent of generational performance gains.
- LGA 1151:Legacy Intel 6th through 9th generation socket sustains minimal volume in institutional refresh cycles and embedded applications.
- LGA 1200:10th and 11th generation Intel interface occupies a narrowing upgrade window between LGA 1151 deprecation and LGA 1700 proliferation.
- LGA 2066:High-end desktop and workstation socket for Intel Core X-series and Xeon W processors serves content creator and professional visualization segments.
AM4 retains the largest installed base while LGA 1700 climbs the fastest among active sockets.
Features:
Application-driven feature bundling separates premium positioning from commodity competition, with thermal engineering and power delivery sophistication displacing port count as the primary differentiation vector.
- Overclocking Support:Enhanced VRM designs with 12+2 phase or greater power delivery, robust heatsink arrays, and BIOS voltage manipulation capabilities define enthusiast-grade tiering. Gaming enthusiasts in China and the United States select these configurations for competitive esports frame-rate stability, with DDR5-6400+ memory support demanding senior PCB design talent concentrated at Taiwanese fabrication houses.
- Wi-Fi Connectivity:Integrated 802.11ax or 802.11be wireless modules eliminate add-in card requirements for compact builds. System builders targeting domestic gaming café verticals in India and Vietnam prioritize this feature for reduced cable management complexity, though FCC Part 15 certification timelines create 8-12 week launch disadvantages for vendors lacking in-house compliance laboratories.
- RGB Lighting:Addressable LED headers and onboard illumination controllers serve aesthetic customization demand in consumer retail channels.
- Multiple GPU Slots:Dual or triple PCIe x16 physical slot configurations support workstation and cryptocurrency mining applications despite declining gaming multi-GPU relevance.
Overclocking Support commands the highest pricing premiums while Wi-Fi Connectivity expands most quickly into mid-range tiers.
End User:
Customer type concentration shapes procurement modality, with direct-to-manufacturer contracting displacing traditional distribution in high-volume segments while enthusiast retail preserves margin-rich specialty channels.
- Gaming Enthusiasts:Individual consumers pursuing high-refresh-rate display configurations and competitive esports performance represent the fastest-expanding buyer segment. Demand concentrates in China, South Korea, and the United States where hardware refresh cycles compress to 18-24 months, with PCIe 5.0 and DDR5 integration forcing 15-20 percent bill-of-materials cost escalation that vendors pass through at premium tiers.
- OEM Manufacturers:Domestic Chinese system assemblers in Guangdong and Jiangsu provinces negotiate annual volume contracts for Micro ATX and Extended ATX variants, bypassing regional distributors through direct procurement relationships that enforce just-in-time delivery terms and compress supplier margins.
- System Builders:Regional integrators serving gaming café, content creator, and small business verticals across India, Indonesia, and Brazil.
- Commercial Users:Enterprise and institutional procurement for office productivity, point-of-sale, and embedded applications prioritizing stability certifications and extended lifecycle guarantees.
OEM Manufacturers drive the highest absolute volume while Gaming Enthusiasts generate the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese motherboard manufacturers ship Extended ATX and Micro ATX variants to system builders across India, Indonesia, and Brazil, with Guangdong province assembly clusters coordinating just-in-time procurement for gaming café and workstation verticals.
United States
Gaming enthusiasts in California, Texas, and Washington State compress hardware refresh cycles to 18-24 months for competitive esports performance. FCC Part 15 electromagnetic emissions certification creates 8-12 week launch delays that favor vendors with in-house compliance laboratories. The Pacific Northwest technology corridor concentrates demand for overclocking-capable boards with DDR5-6400+ memory support.
China
Domestic OEM manufacturers in Guangdong and Jiangsu provinces negotiate annual volume contracts for Micro ATX and Extended ATX variants, bypassing traditional distribution layers. MIIT enforces GB standards for electromagnetic compatibility that accelerate local production capacity expansion. Shenzhen and Dongguan assembly clusters enforce just-in-time delivery terms on Taiwanese and Korean PCB suppliers.
Germany
Gaming enthusiasts absorb platform-switching costs for LGA 1700 architectures with PCIe 5.0 bandwidth headroom. EU Ecodesign requirements for standby power consumption mandate sub-0.5 watt idle states and standardized disassembly documentation. The Bavaria and Baden-Württemberg industrial regions host system integrators serving content creator and professional visualization segments.
India
System builders target gaming café and content creator verticals with cost-optimized Micro ATX configurations where per-unit chassis volume determines freight economics. BIS certification harmonization with IEC standards reduces import friction for premium ATX boards. Maharashtra and Karnataka states concentrate procurement from Chinese OEM channels for domestic assembly operations.
South Korea
Esports hardware refresh cycles drive sustained replacement demand for LGA 1700 and AM5 socket platforms independent of generational performance gains. The country's national telecommunications regulator enforces electromagnetic compatibility standards for wireless-integrated boards. Seoul Capital Area system builders prioritize Wi-Fi connectivity modules for reduced cable management complexity in compact gaming builds.
ATX Motherboards Market Competitive Landscape
Player mix skews toward vertically integrated Taiwanese fabricators with captive PCB production and in-house thermal engineering capabilities. Three to four vendors control premium-tier positioning through overclocking-focused VRM designs and signal integrity investments. Strategic archetypes separate into: (1) full-stack fabricators controlling PCB lamination and BIOS firmware development, (2) thermal engineering specialists targeting Extended ATX workstation builds, and (3) cost-optimized assemblers serving high-volume Micro ATX procurement channels. Competitive moves concentrate on backward integration into copper-clad laminate supply and direct-to-system-builder contracting that displaces regional distribution.
Within the full-stack fabricator tier, ASUS and MSI exemplify archetypes combining in-house PCB fabrication with specialized thermal engineering for extended ATX workstation deployments. Gigabyte Technology occupies a position representing aggressive feature stacking across connectivity and illumination tiers. ASRock anchors the cost-optimized segment serving high-volume Micro ATX procurement for emerging market system builders. These three companies collectively illustrate how vendor positioning stratifies across premium thermal engineering, mid-tier feature differentiation, and volume-oriented assembly efficiency.
| Leading Market Players |
|---|
| ASUS |
| MSI |
| Gigabyte Technology |
| ASRock |
| Supermicro |
| Advantech |
| Intel |
| Biostar |
| Colorful |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Taiwanese PCB fabrication houses concentrates supply-side leverage among vendors with captive lamination facilities, compressing price floors for second-tier assemblers while granting premium-tier players margin insulation through DDR5-6400+ signal integrity investments. Guangdong province system builders exploit this concentration by enforcing annual volume contracts that strip distribution markups from Micro ATX procurement channels.
Pricing Analysis
PCIe 5.0 versus PCIe 4.0 versus next-generation CXL-ready configurations stratify pricing across three distinct technology tiers. Premium-mid-economy pricing differentiation separates enthusiast-grade overclocking boards with 12+2 phase VRM designs from cost-optimized Micro ATX SKUs for Indian gaming cafés. Pricing pressure stems from copper and resin input volatility that squeezes gross margins on high-volume configurations. OEM manufacturers in China exhibit lowest price sensitivity due to annual contract structures, while Southeast Asian system builders absorb freight-adjusted premiums for chassis-optimized form factors.
Supply Chain Analysis
Just-in-time delivery terms dominate procurement relationships between Guangdong assembly clusters and Taiwanese PCB suppliers, compressing inventory buffers to 7-10 days for standard ATX variants. Manufacturing concentration centers on Taiwan, China, and South Korea for high-layer-count substrates and retimer chip integration. Raw material dependencies draw from copper-clad laminate, low-loss resin systems, and DDR5 memory controller silicon. Single-source vulnerability concentrates in senior PCB design talent pools at Korean and Taiwanese fabrication houses. Distribution runs through direct-to-manufacturer contracting that displaces regional distributors across China and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection arrives as socket architecture fragmentation between AM4, AM5, and LGA 1700 ecosystems forces vendor commitment to interoperability investments that lock in 3-5 year upgrade-path dependencies.
For Market Incumbents: Secure captive supply of copper-clad laminate through backward integration into substrate manufacturing, insulating margin structures from commodity volatility that disproportionately impacts Micro ATX volume tiers. Deepen BIOS firmware development capabilities to defend against emerging Chinese vendors leveraging MIIT GB standards compliance for domestic market access. Prioritize in-house FCC Part 15 certification laboratories to eliminate 8-12 week launch delays that disadvantage smaller competitors. For New Entrants and Emerging Players: Extended ATX thermal engineering for multi-GPU workstation builds represents an under-served niche where incumbent focus on gaming enthusiasts leaves margin pools exposed. Target Indian system builder channels with BIS-certified Micro ATX configurations optimized for gaming café freight economics. Deploy direct technical support teams to bypass distributor layers and capture procurement relationships from Guangdong assembly clusters. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated fabricators with in-house PCB lamination and signal integrity engineering capabilities that concentrate DDR5-6400+ layout expertise. Long-term viability across the 5-10 year horizon rests on vendors controlling retimer chip integration and CXL protocol convergence for memory disaggregation applications. The signal to monitor is PCIe 6.0 specification finalization timing, which would trigger working capital intensity spikes for inventory transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper-Clad Laminate | Captive substrate supply insulates margin structures from resin and copper commodity volatility affecting high-volume SKUs. |
| In-House FCC Certification Laboratory Investment | Eliminates 8-12 week launch delays that disadvantage board vendors against ASUS and MSI compliance capabilities. |
| Direct-to-System-Builder Contracting Expansion | Bypasses regional distribution layers in Guangdong and Jiangsu provinces where procurement power concentrates. |
| DDR5-6400+ Signal Integrity Engineering Acquisition | Captures scarce senior PCB design talent concentrated at Taiwanese fabrication houses for premium tier differentiation. |
| EU Ecodesign Firmware Development Partnership | First-mover positioning for sub-0.5 watt standby power mandates reshaping component selection and documentation requirements. |
Research Methodology
Initial hypotheses were tested against primary input from motherboard product managers, PCB fabrication engineers, system builder procurement leads, and esports hardware distributors and refined through secondary validation against SEC 10-K filings, customs trade databases, MIIT registration records, and FCC equipment authorization files. Bottom-up volume estimates triangulated with top-down market sizing across form factor, socket type, and end-user segmentation dimensions.
Variance-decomposition analysis isolated technology transition effects, regional procurement modality shifts, and input cost volatility contributions to growth trajectory uncertainty. Modeled dimensions span form factor selection, socket architecture generation, feature tier bundling, and regional regulatory cluster. CAGRs derived from installed base rotation rates, replacement cycle compression, and platform-switching cost absorption patterns. Forecast inputs incorporated PCIe 5.0 retimer chip availability and DDR5 memory controller yield curves.
Material uncertainties — copper and resin commodity spikes, socket architecture consolidation timing, and EU Ecodesign implementation enforcement — sit outside the modeled envelope. Forecasts reflect assumptions regarding technology adoption curves and procurement relationship stability. Revision becomes warranted when PCIe 6.0 specification release accelerates beyond baseline expectations or when Chinese domestic OEM vertical integration crosses captive supply thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Flip Chip Technology Market