
 EV Capacitor Films Market | 2026-2036
EV Capacitor Films Market Size, Share, and Industry Trends Forecast 2026-2036
EV Capacitor Films Market Insights
Electric vehicle manufacturers is rebalancing procurement weight toward 800V architectures, pulling film capacitor specifications upward. Toray Industries leverages its biaxially oriented polypropylene dominance to anchor Japanese OEM supply chains. Panasonic competes through in-house vertical integration from resin to metallized film. KEMET Corporation specializes in high-temperature DC-link designs that sustain margin pools in performance-tier segments.
EV capacitor films are thin dielectric polymer layers, typically polypropylene or polyester, metallized with aluminum or zinc-aluminum alloys to form self-healing capacitor electrodes; they function as charge storage and ripple current absorption media in power inverter modules. Film capacitors occupy the largest volume share due to their established reliability in DC-link applications, while advanced dielectric materials capture expanding margin pools as OEMs push for higher energy density and thermal tolerance. Metallized film capacitors lead in unit shipments for onboard chargers, though supercapacitors are gaining structural importance in regenerative braking subsystems.
The US NHTSA and EPA shape demand through EV mileage mandates and battery safety standards that cascade into capacitor qualification requirements. China's MIIT enforces GB standards for automotive electronics, while the EU Green Deal and REACH constrain halogenated flame retardants in film substrates. Stakeholders must monitor how 800V platform proliferation and solid-state battery thermal profiles redraw capacitor specification boundaries.
Market Dynamics
800V battery architectures are compressing capacitor specification cycles as automakers demand thinner dielectric films that withstand higher thermal loads and ripple currents. This voltage migration is redrawing procurement priorities across inverter supply chains.
Growth Catalysts
- China's dual carbon goals:Domestic polypropylene film substitution accelerates as NMPA guidelines favor local dielectric material sourcing for automotive electronics.
- DC-link capacitor demand:Power inverter modules in battery electric vehicles consume metallized film capacitors for ripple current absorption, pulling volume through tier-one suppliers.
- Germany's automotive corridor:Bosch, Continental, and ZF localize inverter production, concentrating procurement weight toward regional film converters.
Market Restraints
- Polypropylene resin concentration:Biaxially oriented film feedstock depends on petrochemical complexes clustered in the US Gulf Coast and Middle East, exposing margins to feedstock volatility.
- Metallization equipment scarcity:Vacuum coating lines for aluminum-zinc alloy deposition face 18-24 month lead times, capping expansion speed for mid-tier converters.
- REACH substance restrictions:EU constraints on halogenated flame retardants in film substrates force reformulation of legacy polyester dielectrics, extending qualification timelines.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized capacitor manufacturing incentives attract film metallizers to establish conversion capacity near emerging EV assembly clusters.
- Solid-state battery thermal profiles:Next-generation cell architectures generate distinct ripple signatures, opening specification windows for high-temperature polyimide dielectrics.
- Direct OEM-film converter relationships:Bypassing traditional component distributors, automakers negotiate metallized film specifications directly with Toray and Panasonic for captive supply security.
Industry Challenges
- Vacuum metallization technician scarcity:Specialized coating process engineers command premium wages as converter capacity expansion outpaces vocational training pipelines.
- Automotive electronics certification timelines:AEC-Q200 qualification for DC-link capacitors extends 12-18 months, delaying revenue recognition for new film formulations.
- Legacy 400V inverter integration:Mixed fleet architectures force capacitor suppliers to maintain dual specification streams, fragmenting production runs and compressing lot sizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Capacitor Films Market |
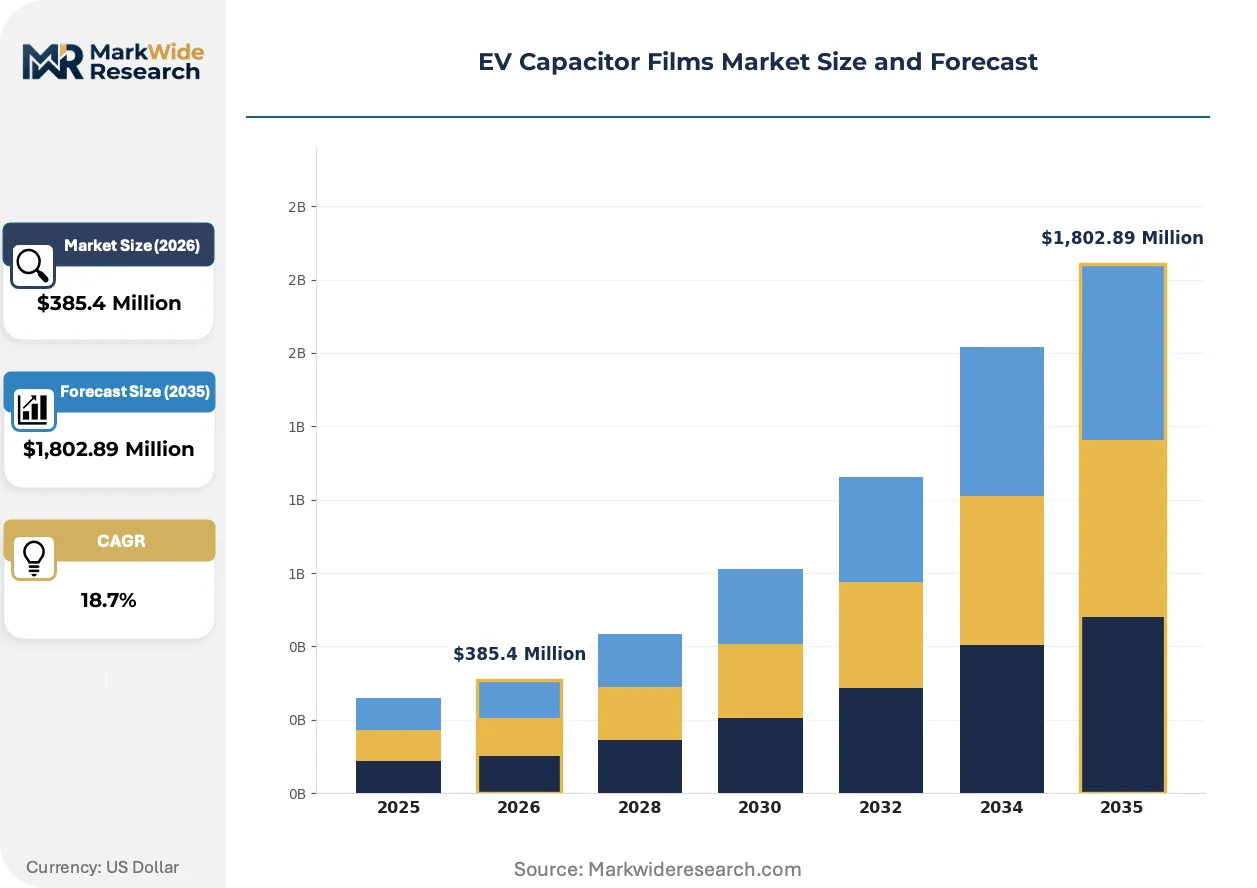
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Capacitors, Metallized Film Capacitors, Ceramic Capacitors, Supercapacitors End User: Electric Vehicle Manufacturers, Battery Producers, Automotive OEMs, Renewable Energy Systems Technology: Hybrid Capacitors, Organic Capacitors, Solid Electrolyte Capacitors, Advanced Dielectric Materials Application: Power Management, Energy Storage, Motor Control, Electric Drives |
| Companies Covered | Toray Industries, JPFL Films, Cosmo Films, Mitsubishi Chemical Corporation, Panasonic, TDK Corporation, Vishay Intertechnology, KEMET Corporation, Xiamen Faratronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Capacitor Films Market Trends and Innovations
Dielectric material science and metallization precision are converging to enable thinner, higher-temperature films that match solid-state power module requirements. These advances are compressing the gap between laboratory performance and automotive qualification.
Segmented electrode designs are integrating self-healing architectures that isolate pinhole defects without catastrophic failure. Tier-one inverter suppliers adopt these films for 800V platforms ahead of full vehicle model refreshes. The technology is integrating margin protection for capacitor manufacturers facing raw material volatility.
EU F-Gas Regulation phase-down mandates are accelerating search for alternative cooling in film capacitor manufacturing processes. Vacuum coating operations face refrigerant transition costs that favor consolidated producers with capital reserves. German automotive electronics suppliers absorb these compliance costs through long-term supply agreements with metallized film converters.
Fleet electrification targets are compressing procurement cycles from annual blanket orders to quarterly demand signals tied to battery pack production schedules. Tier-one component distributors lose volume share as inverter manufacturers negotiate direct metallized film contracts. This pattern concentrates most visibly in China's Yangtze River Delta EV manufacturing cluster.
EV Capacitor Films Market Segmentation
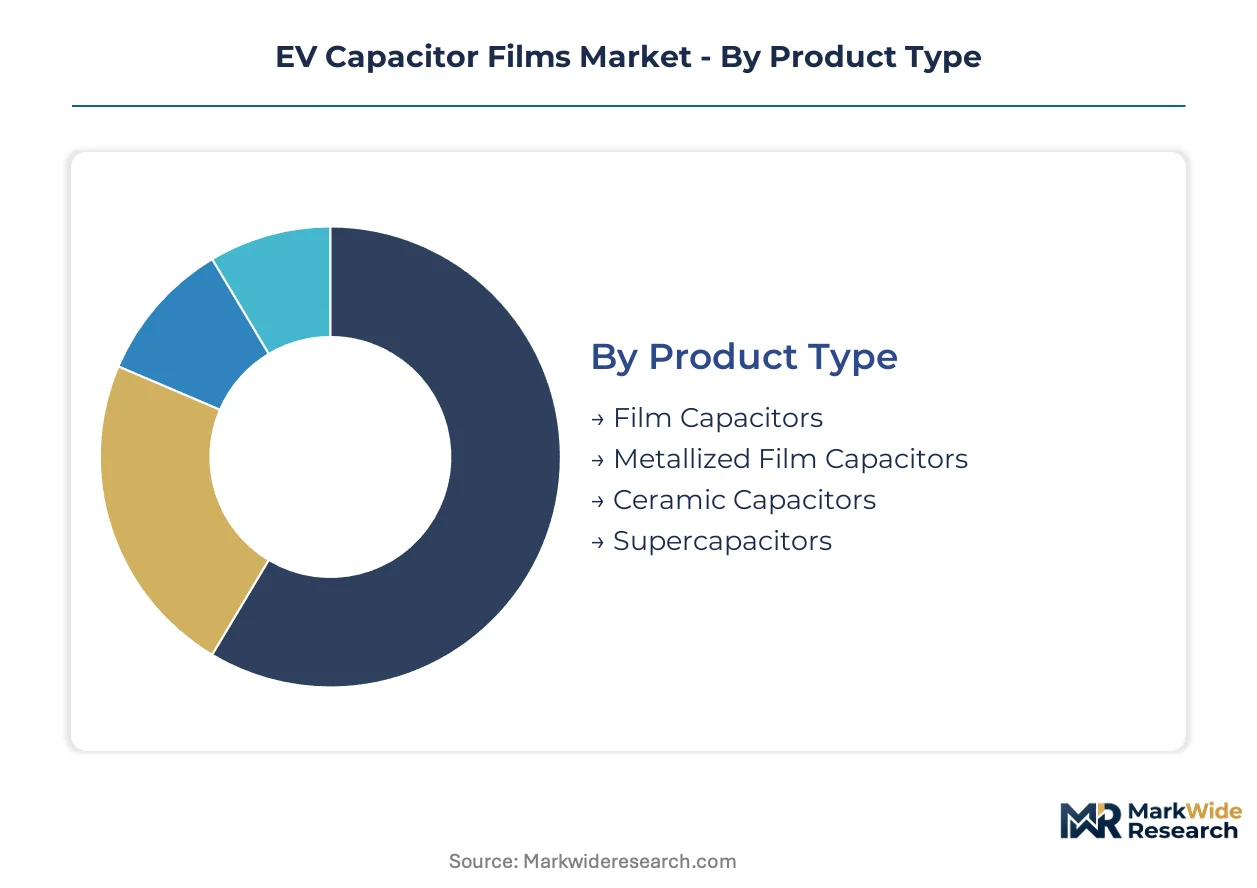
Capacitor film specifications diverge sharply across voltage tiers and thermal envelopes. Procurement patterns track directly to inverter architecture choices and battery platform roadmaps.
Product Type:
Cost tier determines converter selection between commodity films and performance-grade dielectrics.
- Film Capacitors:Polypropylene and polyester dielectric layers dominate DC-link applications for their self-healing properties under ripple current stress. Demand concentrates in Germany's automotive corridor where Bosch and Continental specify biaxially oriented films for 800V inverter modules.
- Metallized Film Capacitors:Aluminum-zinc alloy deposition creates segmented electrodes that isolate pinhole defects without catastrophic failure. China's NMPA guidelines favor these for onboard chargers as domestic converters scale vacuum coating capacity in the Yangtze River Delta.
- Ceramic Capacitors:MLCC formulations address high-frequency decoupling in gate driver circuits.
- Supercapacitors:Activated carbon electrodes absorb regenerative braking energy spikes in hybrid architectures.
Volume sits with Film Capacitors; growth tilts toward Metallized Film Capacitors.
End User:
Customer type fragments procurement between captive vertical integration and merchant supply.
- Electric Vehicle Manufacturers:Direct metallized film contracts bypass traditional distributors as Tesla and BYD negotiate specifications with Toray and Panasonic for supply security.
- Battery Producers:CATL and LG Energy Solution integrate DC-link capacitors into module designs, pulling film selection upstream.
- Automotive OEMs:Volkswagen and Toyota qualify multiple film sources to hedge against metallization equipment scarcity.
- Renewable Energy Systems:Grid-scale inverters consume thicker dielectric films for utility-grade reliability.
Procurement weight concentrates with Electric Vehicle Manufacturers; specification influence is climbing fastest among Battery Producers.
Technology:
Maturity curves separate established polymer films from emerging ceramic-polymer hybrids.
- Hybrid Capacitors:Polymer-ceramic composites merge high capacitance density with low equivalent series resistance. Solid-state battery thermal profiles in Japan's METI-funded programs are opening qualification windows for these formulations.
- Organic Capacitors:Conductive polymer cathodes replace liquid electrolytes for high-temperature endurance. ZF and Continental specify these for integrated motor-inverter units where coolant loops run hotter.
- Solid Electrolyte Capacitors:Tantalum-polymer hybrids address space-constrained onboard chargers.
- Advanced Dielectric Materials:Polyimide and PEN substrates target 150°C continuous operation.
Organic Capacitors hold current volume; Hybrid Capacitors are expanding most quickly as 800V platforms proliferate.
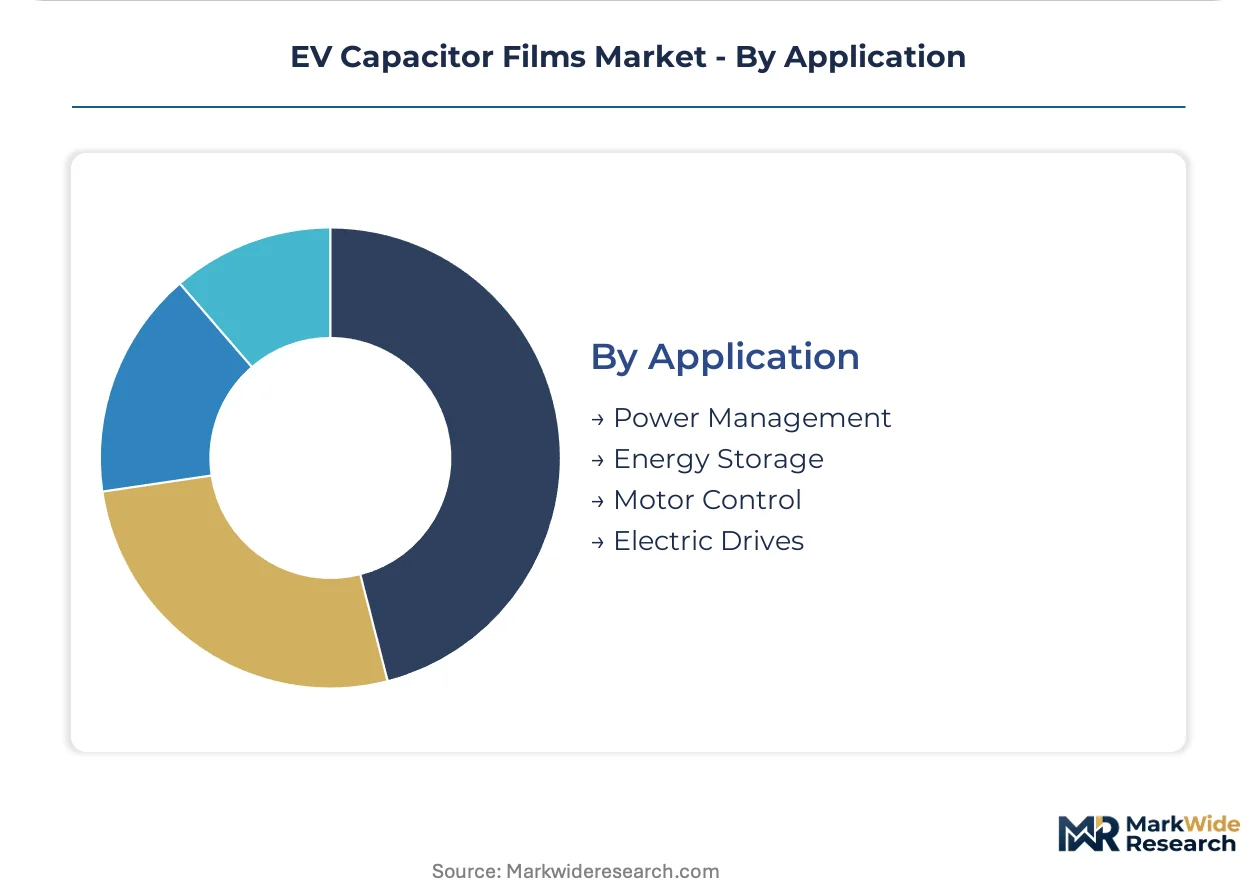
Application:
Functional role dictates ripple current ratings and thermal cycling requirements.
- Power Management:DC-link capacitors buffer battery-inverter interfaces against voltage transients. China's MIIT enforces GB standards that cascade into ripple current specifications for these components.
- Energy Storage:Metallized films in regenerative braking subsystems absorb megawatt-scale power spikes. EU Green Deal fleet targets compress procurement cycles to quarterly demand signals tied to battery pack schedules.
- Motor Control:IGBT and SiC gate drivers require low-inductance film geometries.
- Electric Drives:Traction inverter modules demand the thinnest dielectric films with highest thermal tolerance.
Power Management commands installed volume; Energy Storage is gaining share fastest amid regenerative braking adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate metallized film conversion capacity near EV assembly plants. China's dual carbon goals and NMPA localization mandates pull dielectric material sourcing inland. German automotive corridors and US Gulf Coast petrochemical clusters anchor feedstock supply.
China
CATL and BYD scale 800V battery production across Jiangsu and Zhejiang provinces. MIIT enforces GB standards for automotive electronics that cascade into capacitor ripple current specifications. Vacuum coating lines cluster in Suzhou and Ningbo as domestic converters displace imported metallized films.
Germany
Bosch, Continental, and ZF localize inverter production along the Baden-Württemberg automotive corridor. EU F-Gas Regulation phase-down mandates accelerate refrigerant transitions in vacuum metallization processes. Stuttgart and Karlsruhe host captive film specification negotiations between OEMs and Japanese resin suppliers.
United States
Tesla and Rivian compress procurement cycles to quarterly demand signals tied to Texas and California battery pack schedules. NHTSA mileage mandates and EPA battery safety standards cascade into AEC-Q200 qualification timelines. Gulf Coast petrochemical complexes supply biaxially oriented polypropylene feedstock to regional converters.
Japan
Toyota and Honda qualify multiple film sources to hedge against metallization equipment scarcity. METI-funded programs open specification windows for polyimide dielectrics matching solid-state battery thermal profiles. Nagoya and Osaka anchor biaxially oriented film dominance through Toray Industries supply chains.
India
Tata Motors and Mahindra Electric pull DC-link capacitor demand through Tamil Nadu and Gujarat assembly plants. PLI scheme incentives for automotive components attract film metallizers to establish conversion capacity near Chennai and Pune. BIS standards for automotive electronics extend qualification timelines for new market entrants.
EV Capacitor Films Market Competitive Landscape
Top-tier vendors anchor resin-to-film backward integration, while mid-tier converters compete on metallization precision and regional logistics. The vendor base separates into three strategic archetypes: petrochemical-integrated resin producers, specialized vacuum coating operators, and captive component divisions of inverter manufacturers. Capacity expansion and direct OEM-film converter relationships constitute the dominant competitive moves as procurement bypasses traditional distributors.
Among Japanese fabricators, Toray Industries and Panasonic occupy positions exemplifying resin-to-metallized-film vertical control. KEMET Corporation sits within the performance-tier specialist archetype, anchoring high-temperature DC-link design capabilities. These three entities represent the competitive spectrum from upstream material dominance through component-level specialization.
| Leading Market Players |
|---|
| Toray Industries |
| JPFL Films |
| Cosmo Films |
| Mitsubishi Chemical Corporation |
| Panasonic |
| TDK Corporation |
| Vishay Intertechnology |
| KEMET Corporation |
| Xiamen Faratronic |
| Others |
Pricing and Supply Chain Analysis
Performance-grade biaxially oriented polypropylene films command 40-60% premiums over commodity polyester dielectrics, a divergence that manifests in dual supply chain configurations: Japanese and German resin suppliers anchor premium tier production through captive metallization, while Chinese converters compete on spot-market feedstock arbitrage in the Yangtze River Delta. This tiered structure concentrates pricing power with vacuum coating operators facing 18-24 month equipment lead times, forcing automakers to accept long-term offtake terms or pay scarcity premiums for qualified film supply.
Pricing Analysis
Short-lead-time premiums for AEC-Q200 qualified films run 15-25% above standard contract pricing, while spot inventory of unqualified commodity grades trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates automotive-certified polypropylene from industrial-grade polyester and unmetallized base film. Pricing pressure stems from polypropylene resin volatility tied to Gulf Coast petrochemical output. Battery producers exhibit highest price sensitivity, while inverter manufacturers prioritize qualification security over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tesla and BYD, bypassing traditional component distributors. Biaxially oriented polypropylene feedstock concentrates in the US Gulf Coast, Saudi Arabia, and South Korea. Raw material dependencies include propylene monomer, aluminum-zinc alloy sputtering targets, and high-purity process gases. Single-source vulnerability sits with vacuum metallization equipment manufacturers in Germany and Japan. Distribution runs through regional film converters clustered near EV assembly plants in China, Germany, and the US.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV capacitor films market sits in a technology-transition phase as 800V silicon carbide inverters displace legacy 400V IGBT architectures, redrawing dielectric specifications and procurement relationships.
For Market Incumbents: Deepen backward integration into polypropylene resin production to hedge against Gulf Coast feedstock volatility. Secure captive vacuum coating capacity in China's Yangtze River Delta before domestic converters achieve AEC-Q200 qualification. This dual move defends margin pools against emerging Chinese metallizers while insulating supply from petrochemical price spikes.
For New Entrants and Emerging Players: The premium-to-economy price gap in India's nascent EV supply chain offers white-space entry. Target Tamil Nadu and Gujarat assembly corridors with localized metallization capacity under PLI scheme incentives. Pursue direct qualification with Mahindra Electric and Tata Motors rather than competing for tier-one inverter supplier slots.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized high-temperature film developers given solid-state battery thermal profile requirements. Long-term viability favors converters with polyimide dielectric capabilities over commodity polypropylene players. Watch NMPA localization enforcement intensity as the inflection signal for Chinese domestic substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Toray and Panasonic secure captive polypropylene supply against Gulf Coast volatility. |
| Vacuum Coating Capacity Expansion | Chinese converters in Suzhou and Ningbo displace imported metallized films per NMPA guidelines. |
| High-Temperature Dielectric Development | Polyimide formulations target solid-state battery thermal profiles in Japan's METI-funded programs. |
| Direct OEM Contract Negotiation | Bypassing distributors, Tesla and BYD lock specifications with Japanese resin suppliers. |
| AEC-Q200 Certification Investment | Extended 12-18 month timelines delay revenue recognition but secure automotive tier-one access. |
Research Methodology
Document review covered SEC 10-K filings, MIIT GB standard publications, EU F-Gas Regulation impact assessments, and automotive production databases, complemented by interviews with tier-one inverter procurement managers, vacuum coating equipment engineers, and polypropylene resin technical directors. Secondary validation drew from customs trade data, AEC-Q200 qualification registries, and petrochemical feedstock pricing indices. Bottom-up film consumption estimates triangulated against top-down EV production forecasts across the analysis window.
Segment-level outputs by product type, end user, technology, and application were generated through driver-elasticity modeling. CAGRs were derived from regression analysis against battery pack voltage migration timelines and inverter localization patterns. Key inputs included metallization equipment lead time trajectories, REACH substance restriction phase-in schedules, and solid-state battery thermal specification roadmaps.
Inputs from NMPA guideline releases and MIIT enforcement bulletins were available through the study window; gaps in proprietary OEM-film converter contract terms introduce uncertainty bands around direct procurement share estimates. Forecasts reflect assumptions regarding 800V platform proliferation speed and polypropylene resin capacity expansion in the Middle East. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Gallium Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Europium Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Indium Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Glass Wafer Market