
 US Supercapacitor Market | 2026-2036
US Supercapacitor Market Size, Share, and Industry Trends Forecast 2026-2036
US Supercapacitor Market Intelligence
Project finance for grid-scale energy storage is reconfiguring competitive entry in the US supercapacitor sector, lowering capital barriers for independent power producers and microgrid developers. Maxwell Technologies (Tesla) leverages its integrated automotive pipeline to anchor high-volume cell supply for electric drivetrain applications. Eaton Corporation sustains a differentiated position through captive power electronics distribution channels that control industrial and utility customer access. LS Materials competes on specialized activated carbon formulations that extend cycle life in demanding temperature environments.
A supercapacitor stores electrostatic energy at the electrode-electrolyte interface through electric double-layer formation, achieving power densities exceeding conventional batteries with cycle stability surpassing one million charge-discharge events. Electric Double Layer Capacitors dominate current manufacturing output due to mature carbon electrode supply chains and standardized cell geometries. Hybrid Capacitors are gaining fastest traction in motor drive systems where the combination of high power density and moderate energy storage bridges the gap between batteries and conventional capacitors. Grid Storage Solutions within the deployment type dimension concentrate margin pools as utilities procure long-duration modules for frequency regulation and renewable firming.
The Department of Energy enforces performance validation protocols for grid-connected storage assets, while the EPA tailors emissions accounting frameworks that favor fast-cycling supercapacitors over peaker combustion units in clean portfolio standards. NHTSA's evolving crashworthiness requirements for electric vehicles shape cell packaging and thermal management specifications that manufacturers must satisfy for automotive qualification. Stakeholders should monitor how IRA domestic content thresholds reshape supplier qualification criteria for federally subsidized projects.
Market Dynamics
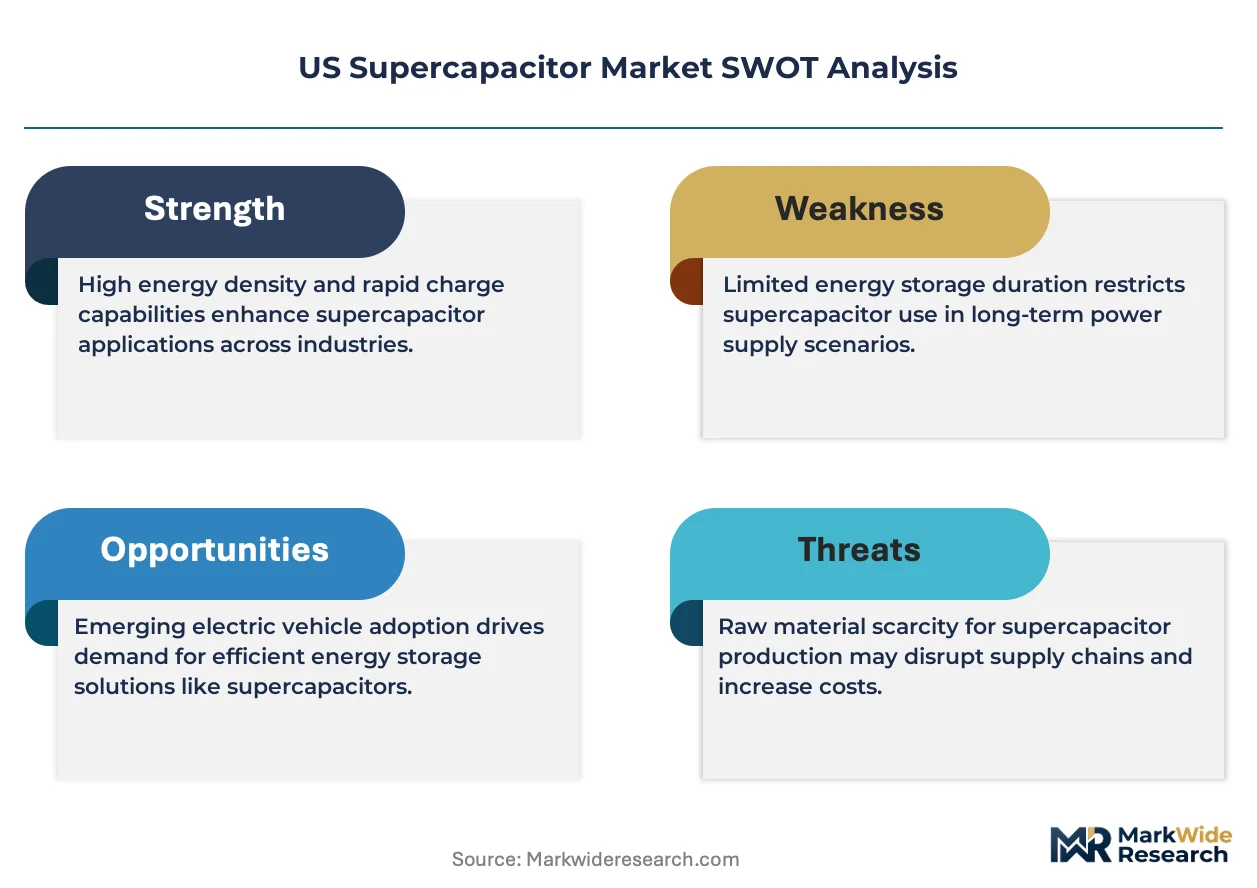
The US supercapacitor sector is reconfiguring around the Inflation Reduction Act's domestic content thresholds, which are forcing module suppliers to relocate cell production or forfeit federal tax credits on subsidized transit and grid storage deployments.
Growth Catalysts
- Regenerative braking mandates:California's electric transit corridors require fast-charge capability that lithium-ion batteries cannot deliver, pulling supercapacitor modules into bus fleet procurement specifications.
- IRA clean energy manufacturing credits:The tax credit structure for domestic cell production is accelerating capital commitment to electrode and electrolyte facilities in Texas and Arizona.
- Grid-scale frequency regulation:ERCOT's procurement protocols for renewable firming services favor supercapacitor response times over peaker combustion units.
Market Restraints
- Activated carbon supply concentration:High-purity carbon precursor sourcing concentrates in Southeast Asian processing facilities, exposing US cell manufacturers to shipping cost volatility and tariff exposure.
- Energy density ceiling:Electric double-layer capacitors face a fundamental physics boundary that limits standalone deployment in long-duration storage applications without hybrid battery pairing.
- NHTSA thermal runaway protocols:Crashworthiness qualification timelines for automotive cell packaging extend certification cycles by 18-24 months versus industrial-grade modules.
Strategic Opportunities
- Texas grid-scale storage corridors:ERCOT's interconnection queue backlog for lithium-ion projects creates a procurement window for supercapacitor-based frequency regulation assets with faster deployment timelines.
- Hybrid capacitor convergence:The pairing of pseudocapacitive materials with carbon electrodes is opening motor drive applications in heavy manufacturing where neither pure batteries nor conventional capacitors suffice.
- Industrial power electronics channels:Direct OEM relationships with variable frequency drive manufacturers bypass traditional battery distributor markups and capture margin pool compression.
Industry Challenges
- Electrochemist talent scarcity:The domestic labor pool for electrode formulation and electrolyte optimization remains thin, forcing manufacturers to recruit from battery and fuel cell sectors at premium compensation.
- Module-to-system integration complexity:Power conditioning and thermal management requirements vary sharply across transit, grid, and industrial end-uses, fragmenting engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Supercapacitor Market |
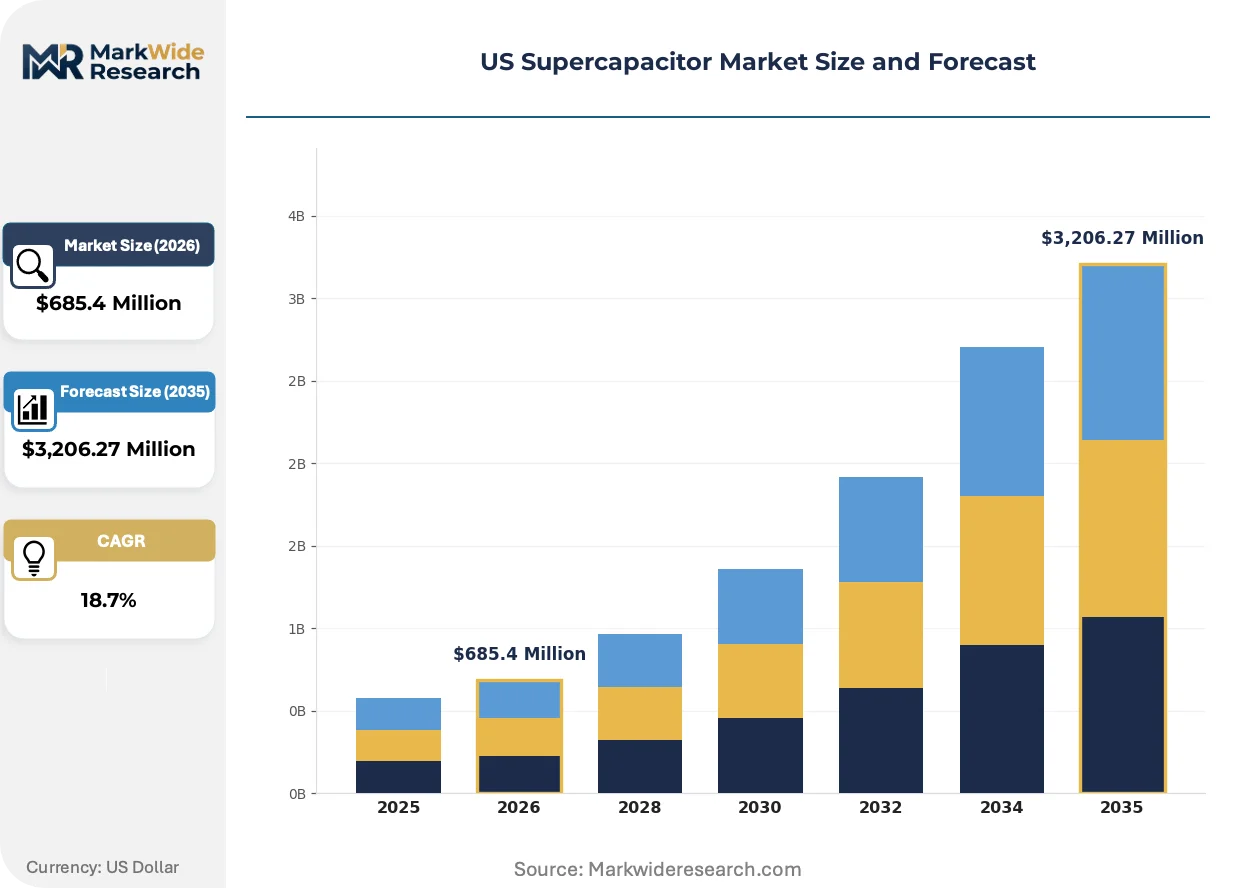
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Double Layer Capacitors, Hybrid Capacitors, Asymmetric Capacitors, Aqueous Electrolyte Capacitors Application: Energy Harvesting, Power Backup Systems, Motor Drive Systems, Lighting Systems, Consumer Electronics End User Industry: Transportation OEMs, Renewable Energy Firms, Consumer Electronics Manufacturers, Aerospace Integrators, Defense Contractors Deployment Type: Embedded Devices, Standalone Modules, Grid Storage Solutions, Portable Equipment, Industrial Machinery |
| Companies Covered | CAP-XX, LS Materials, Maxwell Technologies (Tesla), Loxus Inc., AVX Corporation, Eaton Corporation, Nippon Chemi-Con Corporation, TOKIN Corporation, Panasonic Corporation of North America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Supercapacitor Market Strategic Shifts & Innovations
Electrode material science and federal procurement rules are jointly rewriting competitive entry conditions, compressing the advantage window for pure-play carbon suppliers while elevating system integrators with captive power electronics capabilities.
Hybrid capacitor architectures are hybridizing the functional boundary between batteries and conventional capacitors. Pseudocapacitive metal oxides deposited on activated carbon substrates deliver intermediate energy density for motor drive systems. Heavy manufacturing OEMs are adopting these modules for regenerative braking in material handling equipment. The technology is hybridizing procurement categories that suppliers previously segmented by power versus energy metrics.
IRA domestic content thresholds are restructuring supplier qualification protocols. The Treasury Department's guidance on clean energy manufacturing tax credits requires 40% domestic value capture for full credit eligibility. Module assemblers must now source electrodes and electrolytes from qualified domestic facilities or sacrifice margin on federally subsidized transit and storage projects. California's electric bus procurement offices are already rejecting bids that cannot document compliant supply chains.
Buyer concentration in utility procurement is compressing vendor margins through master service agreements. Texas grid operators and California transit authorities are consolidating supercapacitor purchases under multi-year framework contracts that lock in volume commitments and technical specifications. Smaller module suppliers without captive power electronics integration capabilities are being relegated to subcomponent tiers or forced into OEM partnerships that erode direct customer relationships.
US Supercapacitor Market Segmentation
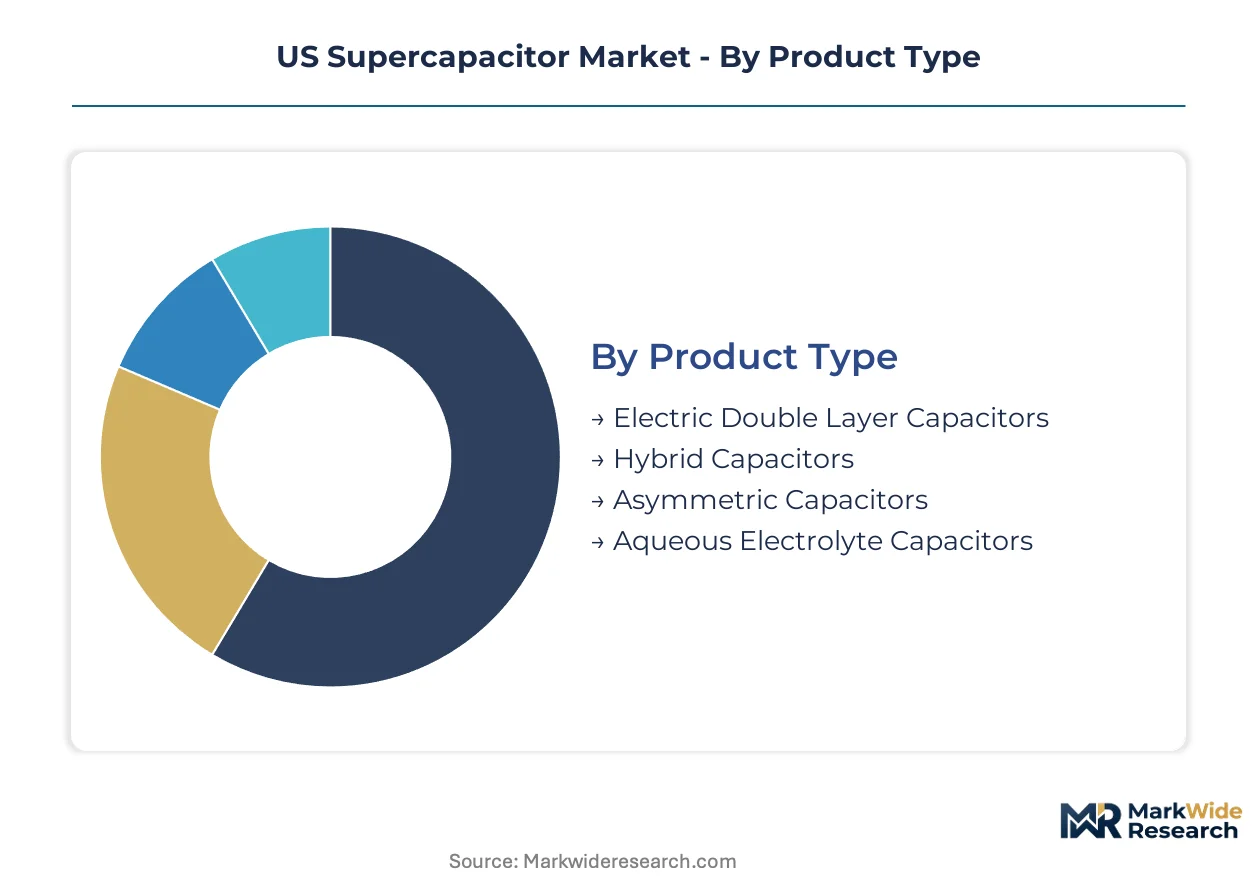
Supercapacitor procurement patterns diverge sharply across product architectures and deployment contexts. Each segmentation dimension carries distinct margin structures, qualification barriers, and growth trajectories that reshape supplier positioning.
Product Type:
Technology maturity separates segments by electrode composition and electrolyte chemistry, determining which applications each architecture can serve.
- Electric Double Layer Capacitors:These devices store charge through pure electrostatic separation at activated carbon interfaces without Faradaic reactions. Transportation OEMs in California's electric transit corridors specify EDLC modules for regenerative braking systems where cycle stability exceeds one million events.
- Hybrid Capacitors:Pseudocapacitive metal oxides deposited on carbon substrates deliver intermediate energy density. Motor drive manufacturers in heavy industry are adopting these units where neither pure batteries nor conventional capacitors meet power-energy requirements.
- Asymmetric Capacitors:Asymmetric electrode configurations pair battery-type anodes with capacitor-type cathodes. Defense contractors procure these for pulse power applications requiring extended discharge duration.
- Aqueous Electrolyte Capacitors:Water-based electrolyte systems eliminate flammability concerns in enclosed industrial environments. Food processing and pharmaceutical manufacturing facilities specify these for safety-critical material handling equipment.
Electric Double Layer Capacitors command the established base. The steepest expansion runs through Hybrid Capacitors.
Application:
Functional use cases determine power conditioning requirements and thermal management specifications across customer segments.
- Motor Drive Systems:Regenerative braking in material handling equipment and crane systems demands rapid charge acceptance. Texas manufacturing clusters are retrofitting variable frequency drives with supercapacitor modules to capture deceleration energy.
- Power Backup Systems:Uninterruptible power supplies for data centers and medical facilities require instantaneous switchover capability. Arizona's semiconductor fabrication plants specify these for voltage sag protection during grid disturbances.
- Energy Harvesting:Wireless sensor networks and IoT endpoints collect intermittent ambient energy. Industrial predictive maintenance systems deploy these for battery-free operation in remote monitoring applications.
- Lighting Systems:Emergency egress lighting and LED streetlight installations use compact supercapacitor packs. Municipal procurement in California cities favors these for maintenance-free operation over traditional battery backup.
- Consumer Electronics:Smart wearables and handheld devices integrate thin-form-factor cells. Limited energy density constrains standalone deployment to burst-power functions rather than primary energy storage.
Motor Drive Systems anchor current procurement volume. Power Backup Systems are climbing the fastest as data center construction accelerates.
End User Industry:
Customer concentration and qualification protocols vary dramatically across industrial verticals, fragmenting sales channel strategies.
- Transportation OEMs:Bus manufacturers and electric truck builders specify modules for fast-charge fleet operations. California's transit authorities mandate 10-year cycle life guarantees that exclude conventional battery alternatives.
- Renewable Energy Firms:Wind turbine OEMs and solar developers deploy supercapacitors for pitch control and inverter bridging. Texas wind corridors represent concentrated procurement for turbine blade regulation systems.
- Defense Contractors:Pulse power applications for railguns and directed energy weapons require specialized packaging. Extended NHTSA thermal runaway protocols add 18-24 months to automotive qualification timelines.
- Aerospace Integrators:Satellite power systems and aircraft emergency systems demand radiation-hardened cells. Volume constraints limit supplier participation to qualified heritage manufacturers.
- Consumer Electronics Manufacturers:Thin-form-factor requirements drive custom cell geometries. Price sensitivity forces module suppliers into high-volume, low-margin production arrangements.
Transportation OEMs dominate contract value. Renewable Energy Firms are gaining share fastest as grid-scale storage procurement expands.
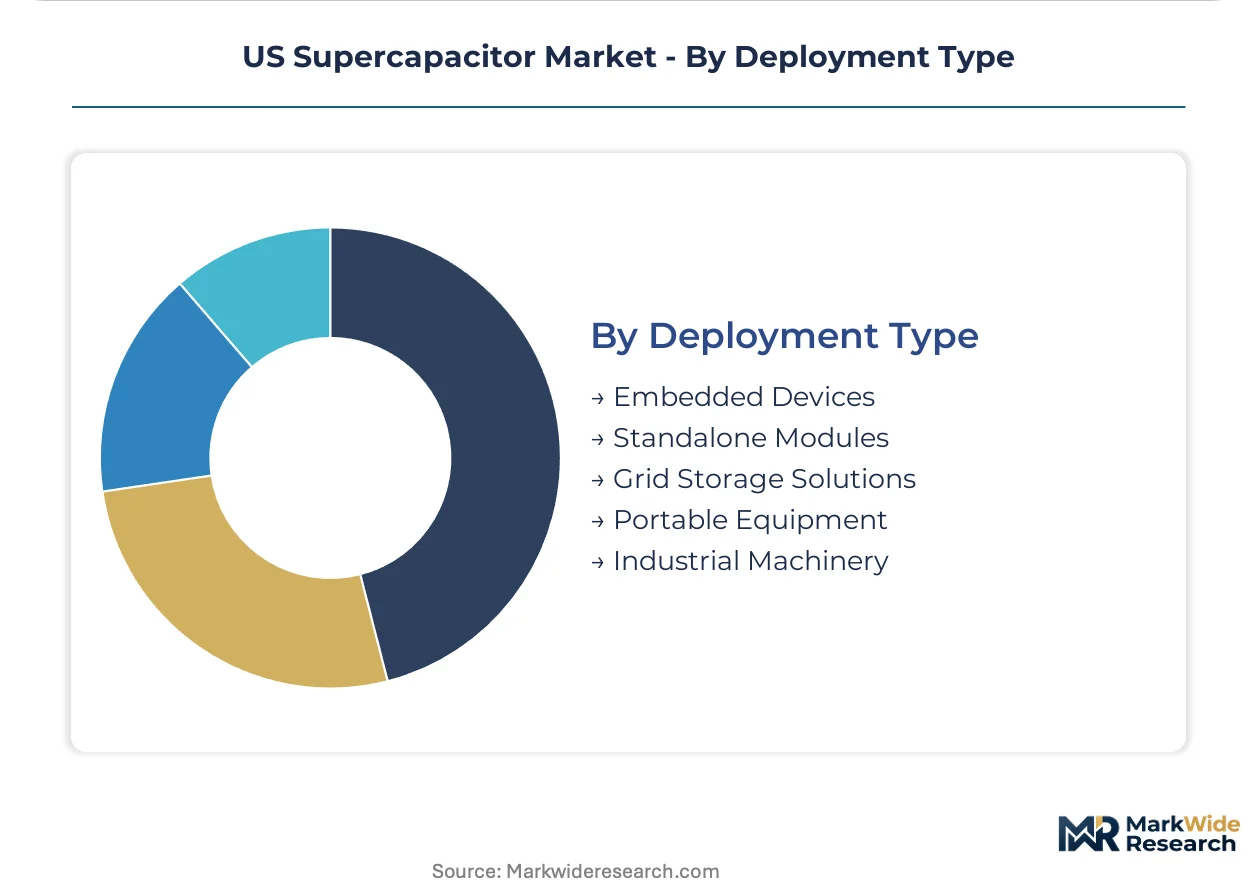
Deployment Type:
System integration depth determines whether suppliers capture module margin or cede value to power electronics integrators.
- Grid Storage Solutions:Utility-scale frequency regulation assets require containerized modules with integrated power conditioning. ERCOT's procurement protocols favor supercapacitor response times over peaker combustion for renewable firming services.
- Standalone Modules:Rack-mounted systems for industrial UPS and microgrid applications ship with standardized interfaces. System integrators add value through custom enclosure and thermal management design.
- Embedded Devices:PCB-mounted cells integrate directly into end-product designs. Consumer electronics and medical device manufacturers specify these for space-constrained applications.
- Industrial Machinery:Heavy equipment OEMs embed modules within variable frequency drive cabinets. Direct supplier relationships bypass traditional battery distributor markups.
- Portable Equipment:Handheld diagnostic tools and field instrumentation use replaceable cell packs. Service life requirements favor supercapacitors over rechargeable batteries in high-cycle applications.
Grid Storage Solutions concentrate the largest margin pools. Embedded Devices are expanding most quickly as IoT deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's domestic content thresholds are redistributing supercapacitor production capacity across US sub-regions. Module suppliers must locate electrode and electrolyte facilities within qualifying zones to capture federal tax credits on transit and grid storage deployments.
California
California's electric transit corridors drive procurement volume for regenerative braking modules. The California Air Resources Board enforces fleet electrification mandates that exclude conventional batteries from fast-charge bus specifications. Los Angeles and San Francisco Bay Area transit authorities are consolidating purchases under multi-year framework contracts with domestic content documentation requirements.
Texas
Texas hosts concentrated grid-scale storage development through ERCOT's renewable firming procurement protocols. The Public Utility Commission of Texas regulates interconnection standards that favor supercapacitor response times over peaker combustion units. Houston and Dallas-Fort Worth industrial clusters are retrofitting variable frequency drives with supercapacitor modules for manufacturing energy recovery.
Arizona
Arizona's semiconductor fabrication plants specify supercapacitor-based uninterruptible power supplies for voltage sag protection. The Arizona Corporation Commission oversees utility procurement rules affecting storage asset qualification. Phoenix-area data center construction is accelerating demand for instantaneous switchover backup systems with maintenance-free operation profiles.
Illinois
Illinois manufacturing bases deploy supercapacitor modules in material handling equipment and crane regenerative braking systems. The Illinois Commerce Commission administers grid interconnection standards for industrial storage assets. Chicago-area logistics hubs are adopting fast-charge supercapacitor packs for electric forklift fleets operating in cold storage environments.
New York
New York's congestion pricing zones and transit electrification targets pull supercapacitor modules into bus fleet procurement. The New York State Public Service Commission governs utility-scale storage incentive programs affecting technology selection. New York City transit authorities mandate 10-year cycle life guarantees that favor supercapacitor specifications over battery alternatives.
US Supercapacitor Market Key Industry Players
On the supply side, the industry is consolidating around integrated power electronics capabilities and captive electrode supply chains. Tiered competitive positioning separates system integrators with utility-scale project experience from component specialists focused on cell chemistry optimization. Three archetypes dominate: automotive-qualified module suppliers, grid-scale storage integrators, and industrial power electronics channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure domestic qualification for IRA-subsidized projects.
Within the automotive-qualified tier, Maxwell Technologies (Tesla) and Eaton Corporation anchor competitive positioning through integrated manufacturing pipelines and captive distribution networks. LS Materials occupies a specialist position in activated carbon formulations. Japanese manufacturers including Nippon Chemi-Con Corporation and Panasonic Corporation of North America exemplify heritage electronics conglomerates with established qualification protocols for industrial and consumer applications.
| Leading Market Players |
|---|
| CAP-XX |
| LS Materials |
| Maxwell Technologies (Tesla) |
| Loxus Inc. |
| AVX Corporation |
| Eaton Corporation |
| Nippon Chemi-Con Corporation |
| TOKIN Corporation |
| Panasonic Corporation of North America |
| Others |
Cost & Logistics Intelligence
Electrode facility undercapacity in Arizona and Texas is compressing supplier margins while amplifying pricing power for qualified domestic producers serving IRA-subsidized transit and grid storage contracts. This utilization squeeze forces module assemblers to absorb carbon precursor volatility or forfeit federal tax credits, tightening the feedback loop between supply security and bid competitiveness.
Pricing Analysis
Certification level (automotive-grade NHTSA qualification versus industrial UL listing) creates the primary spread between premium and standard module tiers. Project-based long-term offtake contracts dominate grid-scale procurement, while transactional per-unit sales persist in industrial retrofit markets. Price differentiation stems from domestic content documentation burden and captive power electronics integration depth. Cost compression in standard industrial modules is intensifying because Southeast Asian carbon suppliers face tariff exposure. Transit authorities with 10-year cycle life mandates show lowest price sensitivity; consumer electronics OEMs exhibit highest.
Supply Chain Analysis
High-purity activated carbon feedstock concentrates in Indonesian and Malaysian processing facilities, with secondary refining nodes in South Korea and Japan. US cell manufacturers draw from coconut shell and petroleum coke precursors, relying on electrolyte formulations anchored in German and Japanese chemical supply. Single-source vulnerability runs through Southeast Asian carbon precursor channels, exposing domestic module producers to shipping cost spikes and customs delays. Distribution runs through direct OEM relationships for automotive and grid integrators, with industrial channels feeding through power electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US supercapacitor sector functions as a defensive-moat market where IRA domestic content thresholds create regulatory entrenchment that locks out unqualified suppliers. Switching costs amplify as transit authorities and utilities consolidate procurement under multi-year framework contracts with embedded technical specifications.
For Market Incumbents: Entrench position through backward integration into electrode production facilities in Texas and Arizona to secure IRA qualification pathways. Capture margin compression from emerging Asian module suppliers by controlling power electronics integration capabilities that utilities now mandate. Lock in transit authority relationships with 10-year cycle life guarantee structures that exclude battery alternatives. For New Entrants and Emerging Players: Build out hybrid capacitor specialization for motor drive applications in heavy manufacturing, where neither pure battery nor conventional capacitor incumbents hold technical dominance. Target Texas grid-scale frequency regulation procurement windows created by ERCOT interconnection queue backlogs for lithium-ion projects. Enter through direct OEM relationships with variable frequency drive manufacturers, bypassing established battery distributor channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across grid-scale storage integration as containerized power conditioning requirements expand. Long-term viability centers on suppliers with captive domestic electrode supply and utility-scale project execution track records. Acquisition target archetype: mid-cap module assemblers with IRA-qualifying supply chains but lacking power electronics integration depth. Signal to watch: California transit authority bid rejection rates for non-compliant domestic content documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Electrode Facility Buildout | Captures IRA manufacturing tax credits and satisfies Treasury Department 40% domestic value thresholds for federal transit subsidies. |
| Power Electronics Integration Partnership | Locks in utility-scale margin pools as ERCOT procurement protocols favor containerized frequency regulation assets with captive conditioning. |
| Hybrid Capacitor R&D Expansion | Opens motor drive applications in Texas manufacturing clusters where regenerative braking retrofit demand outpaces pure EDLC capabilities. |
| Transit Authority Framework Contract | Secures volume commitments from California and New York agencies consolidating procurement under 10-year cycle life specifications. |
| Electrochemist Talent Acquisition Program | Addresses formulation scarcity forcing premium compensation draws from battery and fuel cell sectors for electrode optimization roles. |
Research Approach
A standing panel of utility procurement officers, transit authority fleet managers, power electronics OEM engineers, and electrochemist R&D directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FERC interconnection filings, EIA storage deployment databases, NHTSA automotive qualification records, and SEC manufacturing capex disclosures. Bottom-up module shipment estimates triangulated against top-down grid storage procurement announcements.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying IRA domestic content enforcement stringency. Segmentation dimensions included product architecture (EDLC, hybrid, asymmetric), deployment type (grid storage, standalone, embedded), and end-use industry (transportation OEM, renewable energy firm, defense contractor). CAGRs derived from installer pipeline data and utility interconnection queue analysis, with electrochemist labor market tightness and activated carbon tariff exposure as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Japanese electronics conglomerates or sudden IRA threshold relaxation would shift outcomes. Cross-checking against ERCOT interconnection queue progression and California Air Resources Board fleet electrification enforcement is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Microcontroller Socket Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
AC Adapter Market
Electronic Components
Operational Amplifier Market
Electronic Components
Braking Resistors Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
North America MLCC Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Wearable Display Device Materials Market