
 Digital Potentiometer Market | 2026-2036
Digital Potentiometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Potentiometer Market Analysis
The gap between analog and digital signal conditioning is narrowing as mixed-signal architectures displace pure analog front ends in precision control systems. Texas Instruments leverages its broad analog portfolio to anchor digital potentiometer offerings within system-level reference designs. Analog Devices specializes in high-resolution programmable devices for instrumentation and test equipment. ROHM Semiconductor competes through integrated manufacturing of resistive elements and CMOS control logic in Japan.
A digital potentiometer is a solid-state electronic component that emulates the function of a mechanical potentiometer using a resistive ladder network controlled by digital signals, typically offering 6-bit to 10-bit resolution with end-to-end resistances from 1 kΩ to 1 MΩ. It serves primarily to provide automated, repeatable, and remote-adjustable resistance values in circuits requiring calibration, volume control, or sensor trimming without mechanical wear. Consumer electronics applications dominate unit volume, though automotive controls represent the fastest-expanding margin pool as functional safety requirements drive qualified component demand. Resistive technology sustains the largest installed base, while capacitive and magnetic variants capture niche applications requiring lower temperature coefficients or galvanic isolation.
FDA oversight of medical devices incorporating digital potentiometers for patient-adjustable equipment shapes validation requirements for component traceability. EPA and RoHS frameworks restrict hazardous substances in electronic components, directly affecting resistive element compositions and plating chemistries. EU AI Act and emerging MEE guidelines in China are extending conformity obligations to smart adjustment systems with embedded algorithms. Stakeholders must monitor how functional safety standards evolve for programmable components in autonomous and medical systems.
Market Dynamics
Electric powertrain electrification is eliminating mechanical linkages across vehicle platforms, forcing control system designers to source qualified solid-state alternatives that meet ISO 26262 functional safety grades.
Growth Catalysts
- Automotive Functional Safety Mandates:Electric vehicle architectures require ISO 26262-compliant programmable components for throttle-by-wire and braking systems. Tier-1 suppliers in Germany and South Korea are qualifying digital potentiometers for ASIL-rated subsystems.
- REACH and RoHS Material Purity Rules:European ECHA enforcement is restricting cadmium and lead in resistive element compositions. Component manufacturers are reformulating thin-film processes to maintain conductivity under tighter substance thresholds.
- Precision Manufacturing Cluster Density:Shenzhen and Suzhou industrial corridors concentrate SMT assembly capacity for consumer electronics trim applications. Local sourcing advantages reduce qualification cycles for new programmable resistor designs.
Market Restraints
- Palladium and Ruthenium Price Volatility:Precious metal sputtering targets for thin-film resistive elements face supply pressure from South African mining concentration. Input cost swings compress margin stability for mid-volume producers.
- Thermal Drift Limitations:Silicon-based resistive ladders exhibit temperature coefficients of 50-150 ppm/°C. High-precision instrumentation buyers in aerospace and medical segments favor wirewound alternatives for stability-critical calibration circuits.
- Wafer Fab Capacity Allocation:Mature-node CMOS foundry capacity in Taiwan prioritizes automotive MCU and power management ICs. Digital potentiometer mask sets compete for 180nm-350nm line space against higher-margin mixed-signal products.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme disbursements for component sourcing are attracting programmable resistor assembly to Noida and Chennai corridors. Local value-add requirements favor captive resistor network production.
- Capacitive Sensing Convergence:Touch-panel calibration systems are hybridizing digital potentiometers with capacitive-to-digital converters. White goods OEMs in China are adopting combined signal conditioning blocks for humidity and pressure trim.
- Medical Device Traceability Mandates:FDA Unique Device Identification rules are elevating component-level serialization requirements. Programmable resistor suppliers with lot-level genealogy systems capture design wins in patient-adjustable equipment.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Competent analog layout engineers with CMOS switch expertise command premium compensation in Munich and Tokyo. HR pipelines from university programs favor digital VLSI specialization.
- AEC-Q100 Qualification Timelines:Full automotive grade certification requires 12-18 months of temperature cycling and ESD testing. Design-in windows for next-generation vehicle platforms close before qualification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Potentiometer Market |
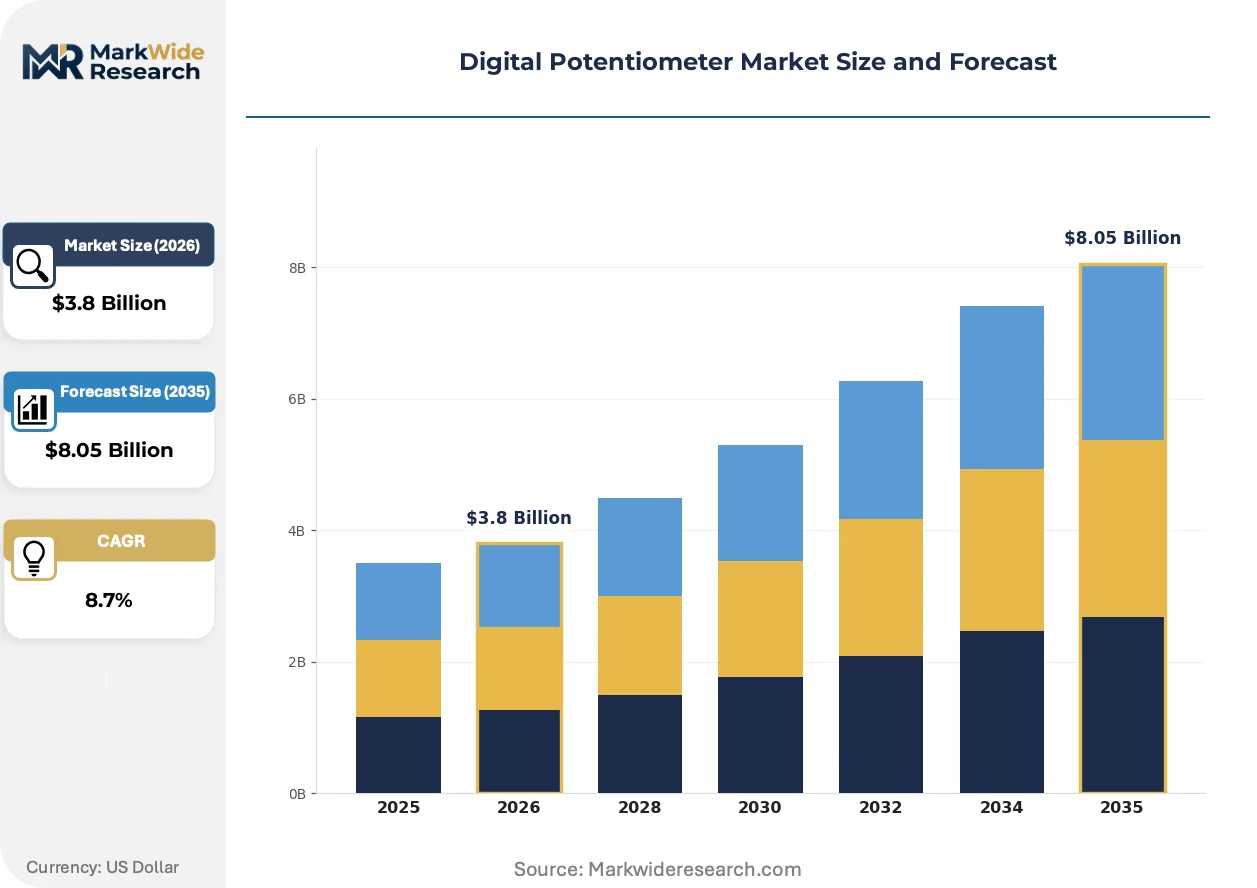
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Linear, Dual Linear, Digital Taper, Programmable Technology: Resistive, Capacitive, Magnetic, Optical Application: Consumer Electronics, Automotive Controls, Industrial Equipment, Audio Systems End User: OEMs, Aftermarket Providers, Research Institutions, Hobbyists |
| Companies Covered | Renesas Electronics, ON Semiconductor, Analog Devices, NXP Semiconductors, Vishay Intertechnology, Texas Instruments, STMicroelectronics, ROHM Semiconductor, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Potentiometer Market Emerging Trajectories
Signal conditioning architectures are abandoning pure analog front ends in favor of software-defined calibration loops. This shift elevates programmable components from peripheral trim elements to core system enablers.
Non-volatile digital potentiometers with integrated EEPROM are hybridizing mechanical reliability with digital programmability. Industrial automation OEMs in Germany are specifying these devices for field-recalibratable sensor interfaces. The technology is compressing maintenance intervals and enabling remote parameter adjustment without physical access.
China's GB standards for electronic component substance restrictions are tightening ahead of REACH phase-outs. MIIT enforcement is accelerating halogen-free substrate adoption in resistive element packaging. Domestic suppliers in Jiangsu province are requalifying product families under dual compliance frameworks to maintain export eligibility.
Consolidated procurement by automotive Tier-1s is compressing approved vendor lists to single-source arrangements for safety-critical subsystems. Bosch and Continental purchasing organizations in Stuttgart are mandating second-source qualification before design release. Supplier engineering teams face duplicated validation effort to maintain participation in platform bids.
Digital Potentiometer Market Segmentation
Digital potentiometer procurement patterns diverge sharply across application contexts. Consumer electronics buyers prioritize unit cost and supply continuity, while automotive Tier-1s impose qualification cycles that stretch eighteen months. Understanding segment-level trade-offs between speed-to-market and certification depth shapes portfolio allocation.
Product Type:
Cycle times compress from eighteen-month automotive qualifications to six-week consumer electronics ramps. Dual Linear devices command premium validation investment, while Programmable variants sustain longest design-in windows due to firmware dependencies.
- Single Linear:One resistive ladder with CMOS switch array provides basic voltage division. Shenzhen SMT corridors source these for white goods trim circuits where BOM cost sensitivity dominates supplier selection.
- Dual Linear:Two independent channels share a common digital interface, halving control line count. German automotive harness suppliers specify these for redundant throttle-by-wire architectures requiring ASIL decomposition.
- Digital Taper:Logarithmic resistance curves emulate audio volume perception. Professional mixing console OEMs in Nashville and Hamburg specify these for fader automation systems.
- Programmable:Non-volatile EEPROM retains wiper position across power cycles. Industrial sensor manufacturers in Suzhou adopt these for field-recalibratable transmitter circuits.
Single Linear dominates installed base. Dual Linear is where expansion concentrates.
Technology:
Cost tiers stratify sharply, with Resistive devices at economy pricing and Magnetic variants commanding 8-12x premiums for isolation-critical medical applications.
- Resistive:Thin-film or polysilicon ladders with MOSFET switches constitute the volume foundation. China's MIIT enforces halogen-free substrate mandates that reformulate packaging chemistries across Jiangsu production corridors.
- Capacitive:Charge redistribution networks eliminate DC current through the resistive element. Humidity sensor OEMs in South Korea integrate these for low-drift environmental monitoring front ends.
- Magnetic:Giant magnetoresistive elements provide galvanic isolation between control and signal paths. Patient-monitoring equipment manufacturers specify these for FDA-compliant isolation barriers.
- Optical:LED-photodetector pairs modulate effective resistance through light intensity. Niche adoption in explosive atmosphere instrumentation where spark-proof operation is mandatory.
Resistive technology anchors volume production. Magnetic variants capture margin expansion in medical safety applications.
Application:
Customer types fragment procurement patterns, with OEMs demanding multi-year supply agreements and hobbyist channels accepting spot-market availability.
- Consumer Electronics:Smartphones, tablets, and wearables require sub-millimeter packages. South Korean display driver IC houses integrate these for OLED gamma correction circuits.
- Automotive Controls:ISO 26262 functional safety grades govern throttle, braking, and steering subsystems. Bosch and Continental purchasing organizations in Stuttgart mandate second-source qualification before platform release.
- Industrial Equipment:Programmable logic controllers and motor drives need field-adjustable gain stages. German automation OEMs specify non-volatile variants to compress maintenance intervals.
- Audio Systems:Professional mixing consoles and consumer AV receivers demand logarithmic tapers. Nashville studio equipment manufacturers source dual-gang devices for stereo tracking.
Consumer Electronics sustains highest unit velocity. Automotive Controls is climbing the fastest.
End User:
Supply concentration varies dramatically, with OEMs consolidating to single-source arrangements for safety-critical platforms while hobbyist channels fragment across distributor catalogs.
- OEMs:Original equipment manufacturers in automotive and medical verticals impose AEC-Q100 and FDA traceability requirements. Lot-level genealogy systems determine supplier selection.
- Aftermarket Providers:Repair and retrofit channels prioritize pin-compatible drop-in replacements. Inventory breadth outweighs technical differentiation in distributor relationships.
- Research Institutions:University labs and national laboratories prototype novel sensor interfaces. Small-lot flexibility and technical documentation depth drive purchasing decisions.
- Hobbyists:Maker communities and educational electronics programs source through distributor catalogs. Price transparency and immediate availability dominate selection criteria.
OEMs command supply priority allocation. Research Institutions represent emerging specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive Tier-1s source qualified digital potentiometers from South Korean foundry partners, while Chinese SMT corridors feed consumer electronics assembly lines across Southeast Asia. This three-pole trade structure concentrates component qualification expertise in Stuttgart and Seoul, with Shenzhen and Suzhou anchoring volume production.
China
Electric vehicle powertrain electrification and white goods sensor calibration dominate procurement. MIIT enforces GB standards for halogen-free substrates that reformulate resistive element packaging. Jiangsu province suppliers in Suzhou and Wuxi requalify product families under dual REACH-GB compliance frameworks to maintain European export eligibility.
Germany
ISO 26262 functional safety mandates for throttle-by-wire and braking systems drive ASIL-rated component demand. ECHA REACH enforcement restricts cadmium and lead in thin-film resistive compositions. Stuttgart-based Bosch and Continental purchasing organizations mandate second-source qualification before platform release, compressing approved vendor lists.
South Korea
Display driver IC integration for OLED gamma correction and automotive harness redundancy requirements sustain dual demand channels. MFDS medical device traceability rules elevate component-level serialization standards. Seoul and Busan semiconductor corridors concentrate CMOS switch fabrication and resistive ladder wafer processing.
United States
Professional audio automation systems and patient-monitoring equipment with FDA UDI requirements shape procurement priorities. FDA oversight of medical devices elevates lot-level genealogy systems as supplier selection criteria. Nashville studio equipment manufacturers and Boston-area medical device OEMs specify logarithmic taper and galvanic isolation variants respectively.
Japan
Industrial sensor field-recalibration and precision instrumentation calibration circuits sustain niche demand. METI JIS standards govern resistive element temperature coefficient specifications. Tokyo and Nagoya manufacturing clusters integrate thin-film resistive element production with CMOS control logic fabrication.
Digital Potentiometer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Consolidated procurement by automotive Tier-1s compresses approved vendor lists to single-source arrangements for safety-critical subsystems, while consumer electronics channels fragment across distributor catalogs. Three archetypes dominate: broad-line analog portfolio houses, precision programmable device specialists, and integrated resistive-CMOS manufacturers. Competitive moves center on AEC-Q100 qualification completion and captive thin-film process development.
Within the broad-line analog tier, Texas Instruments and Analog Devices occupy positions anchored by system-level reference design ecosystems. ROHM Semiconductor exemplifies the integrated manufacturing archetype through captive resistive element and CMOS control logic production. These three companies represent distinct competitive vectors: portfolio breadth, precision specialization, and vertical manufacturing integration respectively.
| Leading Market Players |
|---|
| Renesas Electronics |
| ON Semiconductor |
| Analog Devices |
| NXP Semiconductors |
| Vishay Intertechnology |
| Texas Instruments |
| STMicroelectronics |
| ROHM Semiconductor |
| Microchip Technology |
| Others |
Supply Flow & Price Mechanics
Mature-node CMOS foundry undercapacity in Taiwan is forcing digital potentiometer mask sets to compete for 180nm-350nm line space against higher-margin automotive MCUs, compressing supplier margins and elongating lead-time premiums for qualified components.
Pricing Analysis
Prior-generation 6-bit resistive devices trade at commodity spot levels while current-generation 8-bit automotive-qualified variants command 3-4x premiums and next-generation non-volatile EEPROM-integrated products sustain project-based licensing structures. Three-tier pricing structure across AEC-Q100 certified, industrial-grade, and consumer-economy levels separates ISO 26262-compliant ASIL-rated components from standard trim applications. Cost compression in consumer-grade single linear devices is intensifying because Shenzhen SMT corridors prioritize BOM cost minimization over performance margins. White goods OEMs exhibit highest price sensitivity, while German automotive Tier-1s accept premium positioning for second-source qualified safety-critical subsystems.
Supply Chain Analysis
Export control restrictions on advanced CMOS process technology limit foundry access for certain precision switch designs, forcing supply chain reconfiguration around accessible mature nodes. Taiwan, South Korea, and Japan anchor wafer fabrication for resistive ladder networks and CMOS switch arrays. Palladium and ruthenium sputtering targets for thin-film resistive elements draw from South African mining concentration, while halogen-free substrate materials feed from Jiangsu province chemical corridors. Single-source vulnerability concentrates in automotive Tier-1 approved vendor lists where Bosch and Continental mandate sole-source arrangements before platform release. Distribution runs through authorized component distributors serving OEM direct procurement and spot-market channels for aftermarket repair.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain electrification is disrupting mechanical potentiometer incumbent positions, creating acquisition windows for programmable component specialists ahead of ISO 26262 qualification completion cycles.
For Market Incumbents: Build captive thin-film process moats through backward integration into resistive element manufacturing to defend against margin erosion from precious metal price volatility. Accelerate AEC-Q100 qualification pipelines for dual linear architectures before Stuttgart-based Tier-1 design-in windows close. Prioritize second-source validation partnerships with South Korean foundry corridors to secure automotive platform participation. For New Entrants and Emerging Players: Pursue India PLI scheme incentives for component assembly localization in Noida and Chennai corridors where domestic value-add requirements favor captive resistor network production. Target industrial automation sensor calibration segments in Germany where field-recalibratable non-volatile devices face less consolidated procurement than automotive safety systems. Lead with combined signal conditioning blocks integrating digital potentiometers with capacitive-to-digital converters for white goods OEM technical specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-qualified digital potentiometer sub-segments as AEC-Q100 testing timelines extend and dual-source qualification requirements duplicate engineering investment. Five-to-ten year viability favors integrated manufacturers with captive resistive element and CMOS control logic production rather than fabless design houses exposed to foundry allocation competition. Monitor MIIT enforcement acceleration of GB standards halogen-free mandates as signal for Jiangsu province supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Qualification Completion | Unlocks design-in access to Bosch and Continental platform releases in Stuttgart. |
| Backward Integration into Thin-Film Resistive Elements | Secures margin control against palladium and ruthenium price volatility from South African supply. |
| India PLI Scheme Localization | Captures component assembly incentives in Noida and Chennai corridors for export eligibility. |
| Dual-Source Qualification Partnerships | Satisfies Tier-1 purchasing mandates before single-source platform commitments solidify. |
| Non-Volatile EEPROM Product Line Expansion | Addresses German industrial automation demand for field-recalibratable sensor interfaces. |
Methodological Framework
Initial hypotheses were tested against primary input from automotive Tier-1 procurement managers, industrial automation OEM platform engineers, semiconductor foundry planning officers, and medical device regulatory affairs leads and refined through secondary validation. Primary fieldwork combined structured interviews with distributor channel partners and CMOS switch design specialists. Secondary sources included SEC 10-K filings from broad-line analog portfolio houses, ECHA REACH substance restriction enforcement records, MIIT GB standards publication databases, and IHS Markit vehicle production data. Bottom-up segment sizing triangulated against top-down macroeconomic demand elasticity estimates.
Demand-supply balance modeling anchored forecast construction across the analysis window, with segmentation dimensions spanning product type resolution grades, technology families, application verticals, and end-user procurement archetypes. CAGRs derived from segment-level volume elasticity coefficients applied to OEM platform ramp schedules and replacement cycle assumptions. Forecast inputs incorporated electric vehicle powertrain electrification penetration curves and FDA medical device traceability mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or precious metal mining output would shift the trajectory. Forecasts reflect documented assumptions regarding foundry capacity allocation priorities and regulatory enforcement intensity. Material shifts in ISO 26262 functional safety grade interpretation or REACH substance restriction phase-out schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Audio Capacitor Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Metal Composite Power Inductor Market
Electronic Components
Passive Attenuator Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Acoustic Diaphragm Market
Electronic Components
Audio CODEC Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Chip Shield Market
Electronic Components
Tower Mounted Amplifier Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
VPX SBC Market
Electronic Components
Global Circuit Protection Market