
 Radiology Services Market | 2026-2036
Radiology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Radiology Services Market Intelligence
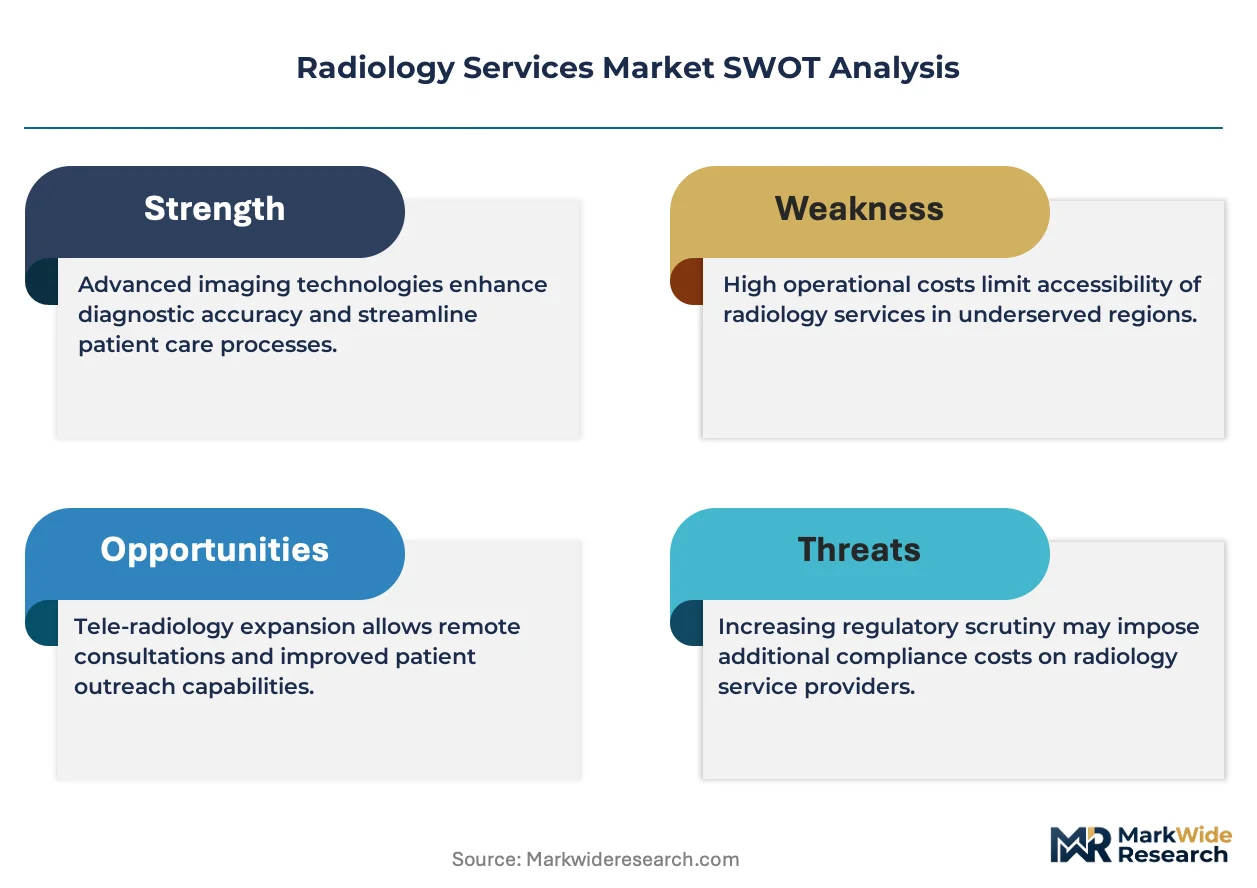
HIPAA is broadening the cost-of-entry calculus for new radiology service platforms by mandating encrypted data transmission, audit trails, and business associate agreements that smaller operators struggle to implement. RadNet sustains one of the largest outpatient imaging footprints across the United States through dense metropolitan clustering. Radiology Partners leverages its physician partnership model to control subspecialty reads in competitive hospital service line agreements. vRad anchors overnight and emergency teleradiology coverage for health systems lacking in-house overnight staffing.
Radiology services encompass the clinical interpretation of medical images and the performance of image-guided therapeutic procedures, utilizing ionizing radiation, magnetic fields, or acoustic energy to generate diagnostic data with spatial resolution thresholds measured in millimeters. These services enable disease detection, treatment planning, and interventional guidance across virtually all medical specialties. Diagnostic imaging commands the largest revenue pool among service types, while tele-radiology represents the fastest-expanding delivery modality as health systems outsource off-hours coverage. Magnetic resonance imaging and computed tomography generate the highest per-procedure reimbursement, though ultrasound retains volume leadership in primary care and obstetric applications.
The FDA governs imaging equipment performance standards and diagnostic accuracy claims, while HIPAA structures patient data portability constraints that shape platform architecture decisions for service providers. State-level certificate-of-need regulations in numerous US jurisdictions limit equipment duplication and influence where independent imaging centers can compete. Stakeholders must monitor how CMS reimbursement rate adjustments for hospital outpatient versus freestanding imaging sites redirect patient volume and capital deployment across delivery settings.
Market Dynamics
Radiologist workforce scarcity is compressing service delivery timelines and accelerating teleradiology platform deployment across health systems. CMS reimbursement differentials between hospital outpatient and freestanding imaging sites are redirecting capital toward independent diagnostic centers.
Growth Catalysts
- CMS Site-Neutral Payment Policies:Medicare reimbursement parity between hospital-based and freestanding imaging centers is diverting patient volume toward lower-cost outpatient facilities in the United States.
- Artificial Intelligence-Assisted Diagnostic Tools:FDA-cleared algorithms for pulmonary nodule detection and intracranial hemorrhage flagging are reducing radiologist interpretation time by automating preliminary triage workflows.
- Subspecialty Read Concentration:Neuroradiology and pediatric radiology expertise is clustering in metropolitan academic medical centers, creating outsourcing demand from community hospitals lacking on-site specialists.
Market Restraints
- Certificate-of-Need Regulations:Thirty-five US states maintain CON laws that restrict new imaging equipment placement, protecting incumbent providers from competitive entry in protected markets.
- Helium Supply Volatility:Magnetic resonance imaging systems depend on liquid helium for superconducting magnet cooling, and export restrictions from Qatar and Russia are destabilizing input costs.
- Interventional Radiologist Training Pipeline:The six-year integrated residency pathway produces fewer than 150 new specialists annually, constraining expansion of image-guided therapeutic services.
Strategic Opportunities
- Rural Health Clinic Satellite Networks:Federally qualified health centers in Montana, North Dakota, and Alaska lack on-site radiology coverage and represent untapped demand for asynchronous teleradiology platforms.
- Quantitative Imaging Biomarker Standards:The Radiological Society of North America is establishing QIB protocols for oncology response assessment, creating new service revenue streams in clinical trial imaging.
- AI-Augmented Workflow Convergence:Integration of natural language processing for report generation with computer vision for image analysis is unifying diagnostic pipelines into single-vendor ecosystems.
Industry Challenges
- HIPAA Business Associate Agreement Complexity:Teleradiology platforms must execute and maintain BAAs with every contracted health system, creating administrative friction that slows contract velocity and increases legal overhead.
- Legacy PACS Interoperability:Picture archiving and communication systems from GE, Philips, and Fujifilm use proprietary data formats that resist seamless integration with cloud-native diagnostic platforms.
- Malpractice Insurance Escalation:Missed diagnosis claims in emergency radiology are driving premium increases for overnight coverage providers, compressing margins in the highest-volume service segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiology Services Market |
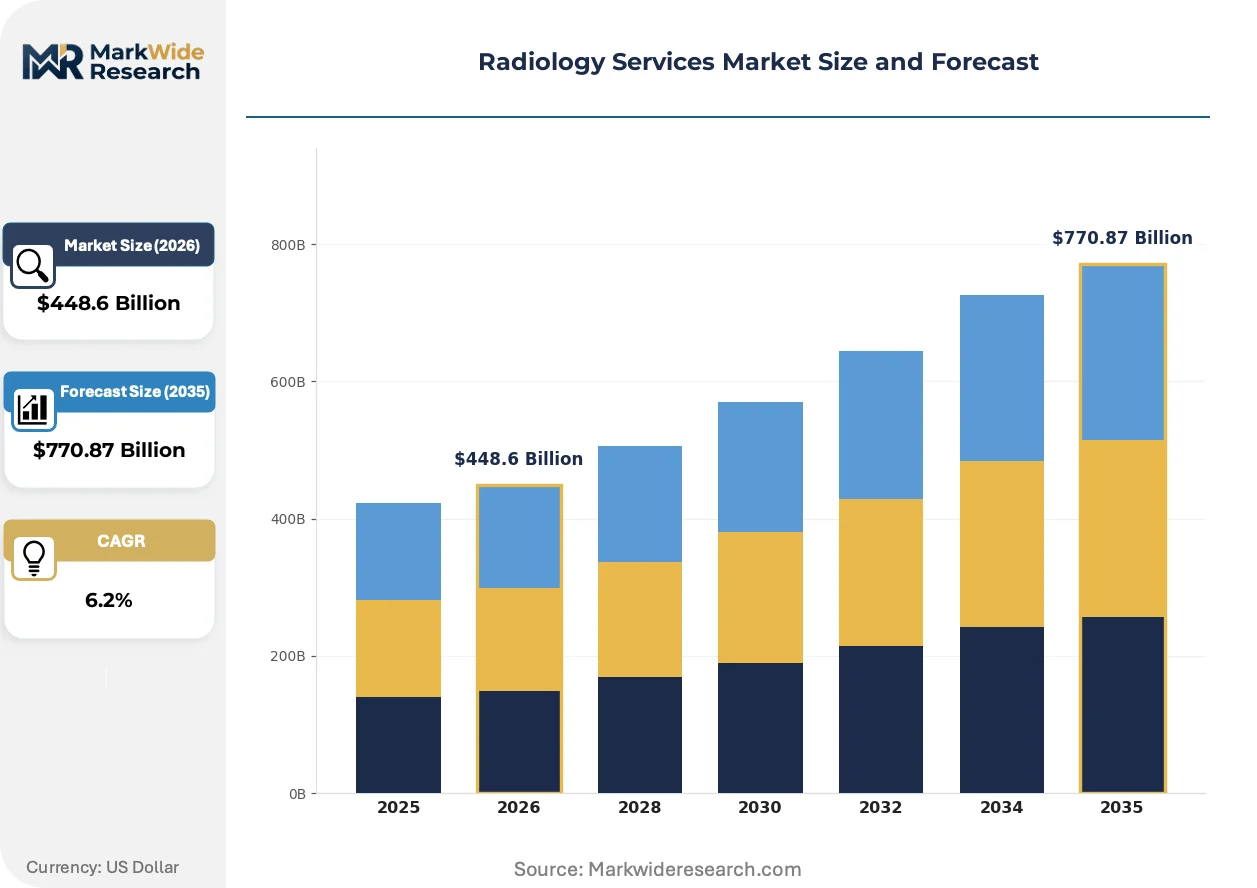
| Market Size in 2026 | $448.6 Billion |
| Market Size in 2035 | $770.87 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Imaging, Interventional Radiology, Nuclear Medicine, Radiation Therapy, Tele-Radiology Technology: Magnetic Resonance Imaging, Computed Tomography, Ultrasound, X-Ray, Positron Emission Tomography End User: Hospitals, Diagnostic Centers, Specialized Clinics, Imaging Laboratories, Outpatient Facilities Application: Oncology Assessment, Cardiovascular Evaluation, Musculoskeletal Analysis, Neurological Imaging, Pulmonary Screening |
| Companies Covered | Rayus Radiology, ONRAD, RadNet, US Radiology Specialists, ALM Teleradiology, Radiology Partners, Akumin, LucidHealth, vRad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiology Services Market Strategic Shifts & Innovations
Diagnostic imaging workflows are converging around cloud-native architectures that dissolve traditional boundaries between acquisition, interpretation, and distribution. Three developments are compressing the value chain and redistributing competitive advantage.
Vendor-neutral archive technology is unifying imaging data from disparate modalities into centralized repositories accessible across health system networks. Large integrated delivery networks in Texas and Florida are consolidating PACS infrastructure to reduce storage redundancy. This consolidation is compressing the market for standalone archiving hardware and elevating software-layer competition.
The FDA's enforcement of premarket submission requirements for AI-enabled diagnostic devices is filtering the commercial landscape for algorithm developers. Radiological software now faces 510(k) clearance pathways that demand clinical validation studies. European manufacturers pursuing US market entry are restructuring quality management systems to satisfy FDA documentation standards.
Hospital purchasing committees are unbundling radiology professional services from technical component billing, enabling direct contracting with physician groups. This separation is displacing traditional hospital-employed radiologist models in the southeastern United States. Academic medical centers in North Carolina and Georgia are responding by launching captive teleradiology subsidiaries to retain revenue.
Radiology Services Market Segmentation
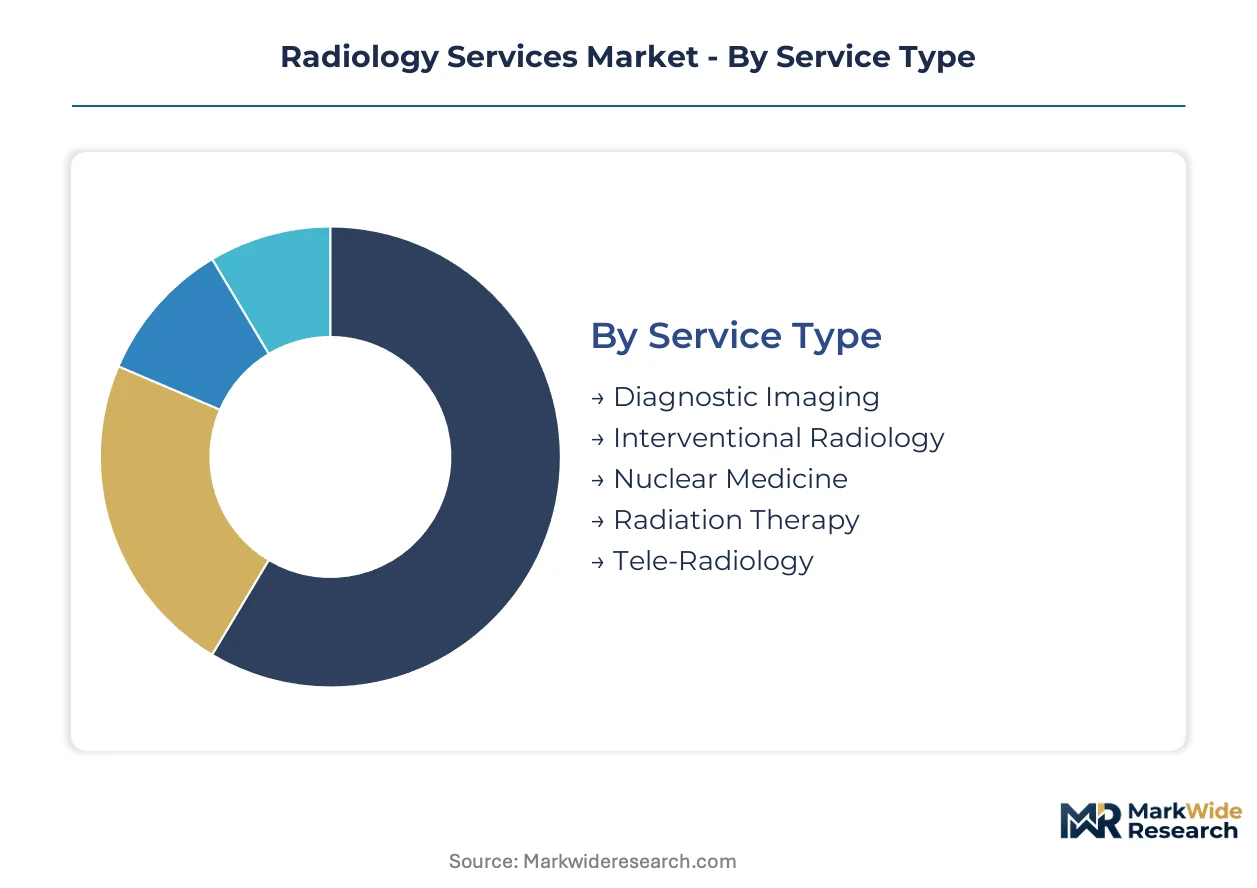
Radiology services fragment across multiple technical and operational dimensions that determine reimbursement rates, capital intensity, and competitive positioning. Understanding these segment boundaries reveals where margin concentrates and where technology shifts are redrawing market boundaries.
Service Type:
Supply concentration varies sharply across service modalities, with capital-heavy equipment dictating where independent operators can compete against hospital systems.
- Diagnostic Imaging:Encompasses CT, MRI, ultrasound, and X-ray interpretation for disease detection and monitoring. Hospital outpatient departments in the United States absorb the majority of high-acuity volume, though freestanding centers are capturing stable patient flows through CMS site-neutral payment advantages.
- Tele-Radiology:Remote interpretation services delivered via secure networks, enabling overnight and subspecialty coverage. Rural health systems in Montana and Alaska depend on these platforms for 24-hour neuroradiology and pediatric reads unavailable locally.
- Interventional Radiology:Image-guided therapeutic procedures including biopsies, drainages, and vascular interventions. The six-year training pipeline constrains specialist supply, protecting incumbent hospital-based practices.
- Nuclear Medicine:Diagnostic and therapeutic applications using radiopharmaceuticals, including PET imaging and radioembolization. Cyclotron availability and radiotracer half-lives limit service points to major metropolitan clusters.
- Radiation Therapy:External beam and brachytherapy services for oncology treatment. Linear accelerator costs and shielding requirements concentrate supply in hospital-affiliated centers.
Diagnostic imaging absorbs the bulk of installed capacity; tele-radiology is expanding most quickly.
Technology:
Cost tiers separate modalities by capital outlay, helium dependency, and reimbursement differential, creating distinct competitive dynamics for equipment manufacturers and service providers.
- Magnetic Resonance Imaging:Utilizes superconducting magnets and radiofrequency coils to generate high-resolution soft tissue images without ionizing radiation. Liquid helium cooling requirements and export restrictions from Qatar and Russia are destabilizing operating economics for high-field systems.
- Computed Tomography:X-ray-based cross-sectional imaging with rapid acquisition speeds for emergency and trauma applications. Emergency departments in the United States deploy these systems for pulmonary embolism and intracranial hemorrhage triage.
- Ultrasound:Acoustic imaging for real-time guidance and obstetric monitoring. Primary care networks favor this modality for its portability and absence of radiation exposure concerns.
- X-Ray:Conventional radiography for skeletal and chest imaging. Volume leadership in screening applications supports thin margins that favor high-throughput operators.
- Positron Emission Tomography:Functional imaging using radiolabeled tracers for oncology staging and neurology evaluation. Cyclotron proximity requirements restrict deployment to academic medical centers.
MRI and CT claim the highest reimbursement per procedure; ultrasound dominates by examination volume.
End User:
Customer type determines contracting complexity, with hospital systems demanding integrated professional-technical bundles while independent centers seek unbundled physician services.
- Hospitals:Inpatient and emergency imaging with 24-hour staffing requirements. Academic medical centers in North Carolina and Georgia are launching captive teleradiology subsidiaries to retain revenue.
- Diagnostic Centers:Freestanding facilities specializing in outpatient imaging with scheduled appointments. Medicare site-neutral policies are redirecting capital toward this channel in the United States.
- Specialized Clinics:Orthopedic, women's health, and oncology-focused practices with dedicated imaging suites. These operators prioritize musculoskeletal MRI and breast imaging workflows.
- Imaging Laboratories:High-volume processing centers serving multiple referring sites. Vendor-neutral archive consolidation is compressing standalone hardware demand.
- Outpatient Facilities:Ambulatory surgery centers and urgent care clinics with point-of-care imaging. RadNet's metropolitan clustering strategy targets this segment.
Hospitals retain the deepest installed base; diagnostic centers are gaining share fastest.
Application:
Clinical use case shapes subspecialty expertise requirements and AI algorithm deployment priorities.
- Oncology Assessment:Staging, response monitoring, and radiation planning for cancer patients. RSNA quantitative imaging biomarker protocols are creating new clinical trial service revenue.
- Neurological Imaging:Stroke, trauma, and degenerative disease evaluation with time-critical interpretation demands. FDA-cleared AI algorithms for intracranial hemorrhage detection are automating emergency triage.
- Cardiovascular Evaluation:Coronary CT angiography and cardiac MRI for ischemia and structural assessment. Subspecialty reads cluster in metropolitan academic centers.
- Musculoskeletal Analysis:Sports injury, arthritis, and orthopedic surgical planning imaging. High volume supports dedicated MSK radiologist employment.
- Pulmonary Screening:Lung cancer CT screening and COVID-19 follow-up protocols. FDA-cleared pulmonary nodule detection algorithms are reducing radiologist interpretation time.
Oncology assessment commands the highest subspecialty premiums; neurological imaging shows the steepest AI adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in the United States concentrate radiology infrastructure investment through tax-deferred capital gains mechanisms, while Singapore's Biomedical Sciences Initiative anchors Asia-Pacific imaging platform development.
United States
Medicare site-neutral payment policies redirect patient volume toward freestanding diagnostic centers in Texas and Florida. The FDA enforces 510(k) clearance pathways for AI-enabled diagnostic devices. RadNet's metropolitan clustering strategy targets dense outpatient markets across Los Angeles, New York, and Dallas-Fort Worth.
Germany
Outpatient imaging demand concentrates in Bavaria and North Rhine-Westphalia amid aging demographics. The EU Medical Device Regulation (MDR) imposes clinical validation requirements on radiological software. Siemens Healthineers anchors Munich's medical imaging industrial cluster with equipment manufacturing and service integration.
United Kingdom
NHS England's imaging networks consolidate teleradiology procurement across integrated care systems. The Care Quality Commission inspects diagnostic accuracy standards in independent sector providers. London's academic medical centers cluster neuroradiology subspecialty expertise, creating outsourcing demand from regional hospitals.
Japan
Super-aging demographics expand oncology and neurological imaging volumes in Kanto and Kansai regions. The PMDA regulates AI diagnostic software through premarket approval pathways. Tokyo's university hospitals concentrate PET-CT cyclotron infrastructure, limiting nuclear medicine service points to major metropolitan clusters.
Australia
Rural health workforce shortages drive teleradiology adoption across Queensland and Western Australia. The TGA oversees medical device software registration including AI-enabled imaging algorithms. Sydney and Melbourne anchor subspecialty radiology networks that provide overnight coverage to regional hospitals lacking on-site staffing.
Radiology Services Market Key Industry Players
United States operators anchor the outpatient imaging tier; European equipment manufacturers hold the technology supply tier. Market structure fragments across three distinct competitive layers: hospital-affiliated radiology groups, independent diagnostic center chains, and pure-play teleradiology platforms. Strategic archetypes include metropolitan density specialists, subspecialty read aggregators, and overnight coverage providers. Dominant competitive moves encompass physician practice acquisitions and cloud-native platform deployment.
Among US-based service providers, RadNet, Radiology Partners, and vRad exemplify contrasting scale strategies. RadNet occupies a position within the metropolitan clustering archetype through dense outpatient center networks. Radiology Partners sits within the physician partnership model, aggregating subspecialty expertise for hospital service line agreements. vRad anchors the emergency teleradiology tier, representing the overnight coverage specialization that health systems outsource for 24-hour neuroradiology and trauma reads.
| Leading Market Players |
|---|
| Rayus Radiology |
| ONRAD |
| RadNet |
| US Radiology Specialists |
| ALM Teleradiology |
| Radiology Partners |
| Akumin |
| LucidHealth |
| vRad |
| Others |
Cost & Logistics Intelligence
CMS site-neutral payment mandates in the United States are compressing reimbursement differentials between hospital outpatient and freestanding imaging centers, forcing equipment manufacturers to recalibrate pricing strategies toward outpatient-focused configurations and service bundling. This demand-side compression cascades through the supply chain as buyers prioritize total cost-of-ownership metrics over upfront capital expenditure.
Pricing Analysis
Short lead-time premiums dominate equipment procurement as health systems facing radiologist staffing gaps pay expedited delivery surcharges for MRI and CT systems. Three-tier pricing structure across premium, standard, and economy levels reflects field strength gradients, with helium-cooled superconducting magnets commanding top tier. Cost compression in the standard tier is intensifying because OEMs are absorbing tariff exposure on Chinese-sourced gradient coils. Hospital systems show least price sensitivity for emergency replacement units, while independent diagnostic centers negotiate aggressively on extended warranty terms.
Supply Chain Analysis
Dual-sourcing requirements from US health system purchasing committees are compelling OEMs to qualify secondary suppliers for superconducting wire and radiofrequency coil assemblies beyond dominant Japanese and German sources. Liquid helium supply draws from Qatar, Russia, and Algeria, with export restrictions creating input cost volatility. Single-source vulnerability concentrates in high-field magnet manufacturing anchored in Japan and Germany. Distribution runs through regional equipment distributors with certified biomedical engineering capabilities for installation and preventive maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiology services operate as a cost-of-compliance market where HIPAA business associate agreement infrastructure and FDA 510(k) clearance pathways create substantial barrier-to-entry moats for accredited platforms. This regulatory scaffolding favors incumbent players with dedicated compliance architecture.
For Market Incumbents: Extend captive teleradiology subsidiary strategies to retain hospital service line revenue as purchasing committees unbundle professional from technical billing. Consolidate metropolitan imaging center density to exploit CMS site-neutral payment arbitrage. Counter Radiology Partners' physician partnership model by locking exclusive neuroradiology reads with academic medical centers in Texas and Florida.
For New Entrants and Emerging Players: AI-augmented workflow platforms offer the most penetrable wedge for cloud-native diagnostic startups lacking legacy PACS infrastructure. Target rural health clinic satellite networks in Montana, North Dakota, and Alaska with asynchronous teleradiology offerings. Pursue direct contracting with federally qualified health centers bypassing hospital system procurement committees entirely.
For Investors and Strategic Acquirers: The window for entry favors physician partnership aggregators with subspecialty concentration in neuroradiology and pediatric radiology. Long-term viability hinges on consolidation plays that achieve density economics in top-20 metropolitan statistical areas. Watch FDA enforcement patterns on AI-enabled device premarket submissions as the signal for algorithm developer platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive professional services agreements with IDNs in Texas and Florida secure volume commitments. |
| AI Algorithm FDA Submission | 510(k) clearance for intracranial hemorrhage detection unlocks emergency radiology workflow integration. |
| Metropolitan Center Acquisition | RadNet-style clustering in Los Angeles and Dallas-Fort Worth exploits site-neutral payment arbitrage. |
| Cloud-Native PACS Deployment | Vendor-neutral archive consolidation displaces GE and Philips legacy hardware in integrated networks. |
| Rural Teleradiology Network | Asynchronous coverage platforms capture overnight demand from Alaska and Montana health systems. |
Research Approach
Independent corroboration across radiology practice administrators, hospital purchasing committee members, biomedical equipment procurement leads, and teleradiology platform executives underwrites the qualitative findings. Primary interviews with GPO contracts managers and FDA regulatory affairs specialists combined with secondary validation from CMS Medicare reimbursement databases, FDA 510(k) clearance records, and hospital procurement system disclosures. Bottom-up imaging center capacity modeling triangulated against top-down health system expenditure tracking.
Comparable-period anchoring to historical Medicare utilization data and commercial payer claims patterns established the forecast baseline across the projection horizon. Segmentation dimensions encompassed service modality, technology platform, end-user facility type, and geographic reimbursement cluster. CAGRs derived from procedure volume elasticity to demographic aging trends and capital expenditure cycle analysis. Helium supply volatility and radiologist training pipeline constraints fed scenario-weighted projections.
Several conditions sit outside the modeled scope, including unanticipated Certificate-of-Need regulatory repeals, breakthrough AI diagnostic algorithms bypassing radiologist interpretation entirely, and acute helium supply disruption from Qatar export embargoes. Deviation in CMS site-neutral payment policy implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Specialty PACS Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Europe Mobile Tomography Market