
 Australia Digital Radiology Market | 2026-2036
Australia Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Digital Radiology Market Insights
Buyer concentration among public hospital networks in Australia is hardening as state health departments consolidate radiology procurement under centralized frameworks. GE Healthcare leverages its installed base of imaging systems to sustain recurring service revenue across Queensland and Western Australia. Siemens Healthineers anchors its position through R&D intensity in detector technology, while Fujifilm Holdings Corporation differentiates via specialized digital X-ray portfolios tailored to outpatient workflows.
Digital radiology encompasses the capture, processing, storage, and transmission of diagnostic images using electronic detectors rather than analog film, with flat-panel detectors achieving spatial resolution down to 139 micrometers for musculoskeletal applications. Its primary purpose is to enable rapid image availability, lower radiation dosing, and seamless integration with hospital information systems. Computed radiography retains significant share in budget-constrained regional facilities, yet digital X-ray systems represent the fastest-growing product category as replacement demand accelerates. Cloud-based delivery modes are expanding fastest among diagnostic centers seeking scalable picture archiving, while artificial intelligence within the technology dimension commands premium positioning as radiologist workflow automation gains traction.
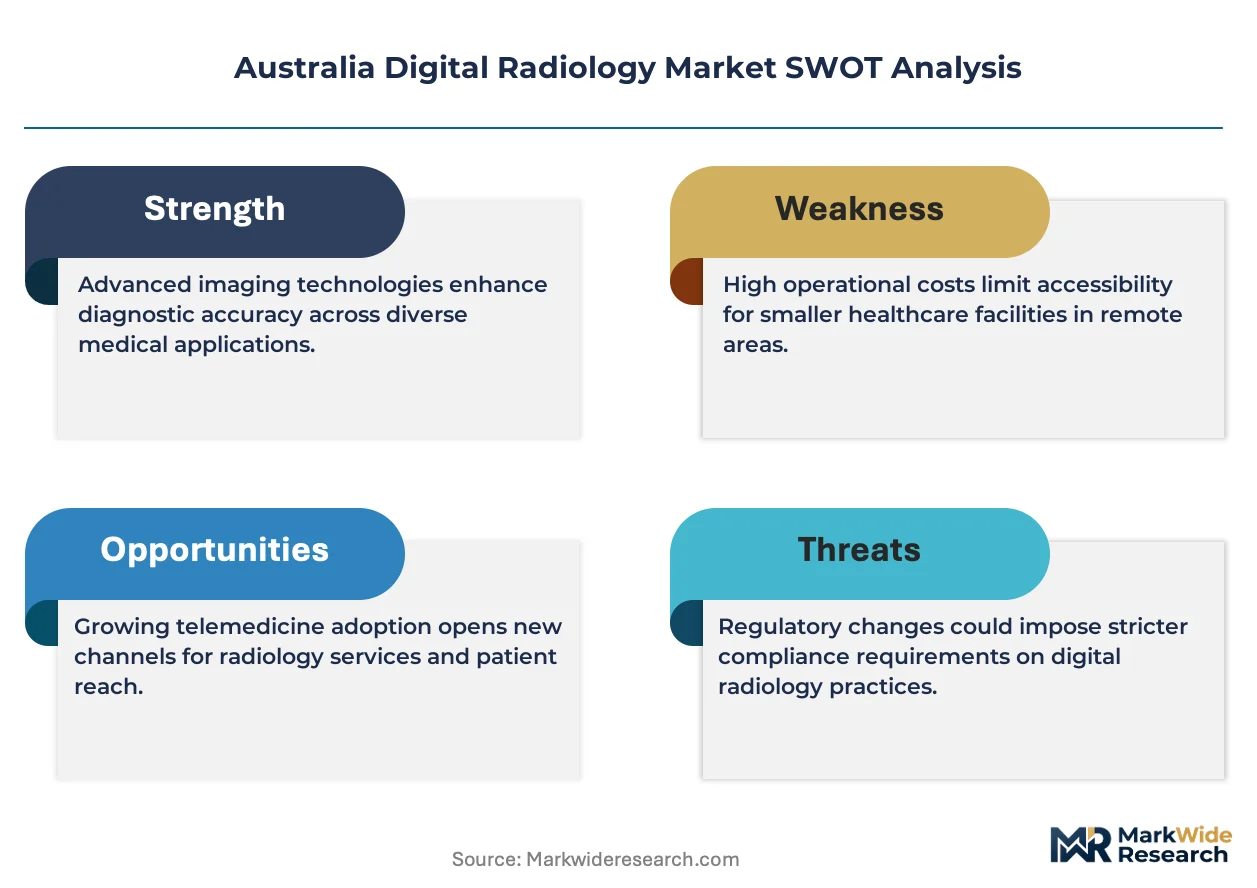
TGA medical device regulations govern product registration and post-market surveillance for all digital radiology equipment distributed in Australia, while the Australian Radiation Protection and Nuclear Safety Agency sets mandatory dose standards that manufacturers must embed in system design. State-based health technology assessment processes further shape hospital purchasing timelines and vendor qualification requirements. Stakeholders must monitor evolving Medicare Benefits Schedule revisions and state capital works programs to anticipate procurement windows and align product development with funded clinical indications.
Market Dynamics
State health department consolidation of radiology procurement is hardening buyer power across New South Wales and Victoria, compressing vendor margins while accelerating replacement cycles for aging analog infrastructure in metropolitan hospital networks.
Growth Catalysts
- Medicare Benefits Schedule revisions:Expanded reimbursement for diagnostic imaging procedures incentivizes hospital capital investment in digital X-ray systems across public health networks.
- Flat-panel detector resolution advances:Spatial resolution improvements down to 139 micrometers for musculoskeletal applications drive clinical upgrade demand from orthopedic departments.
- Queensland regional hospital expansion:State capital works programs targeting rural healthcare infrastructure create procurement windows for computed radiography replacements.
Market Restraints
- TGA post-market surveillance costs:Mandatory adverse event reporting and periodic safety updates impose ongoing compliance expenditure on equipment distributors.
- Detector manufacturing concentration:Supply of amorphous selenium and cesium iodide scintillators concentrates among Asian specialty chemical producers, exposing Australian vendors to input volatility.
- Computed radiography residual installed base:Budget-constrained regional facilities in Western Australia and South Australia delay full digital transitions, fragmenting service requirements.
Strategic Opportunities
- Tasmanian rural health networks:Underpenetrated diagnostic imaging infrastructure in Hobart and Launceston regional hospitals offers first-mover positioning for mobile digital X-ray deployments.
- Cloud-based PACS convergence:Integration of artificial intelligence workflow tools with scalable picture archiving creates premium service tiers for diagnostic centers.
- ARTG expedited review pathways:TGA priority registration for software-as-a-medical-device accelerates market entry for AI-enabled image analysis platforms.
Industry Challenges
- ARANSA dose compliance engineering:Embedding mandatory radiation protection standards into system design requires specialized regulatory affairs expertise that concentrates among Melbourne and Sydney consultancies.
- Legacy HIS integration complexity:Interoperability with state-specific hospital information systems in Queensland and Victoria demands customized interface development, extending implementation timelines.
- Radiologist workforce distribution:Specialist concentration in metropolitan centers limits same-day reporting capacity for regional deployments, constraining throughput optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Digital Radiology Market |
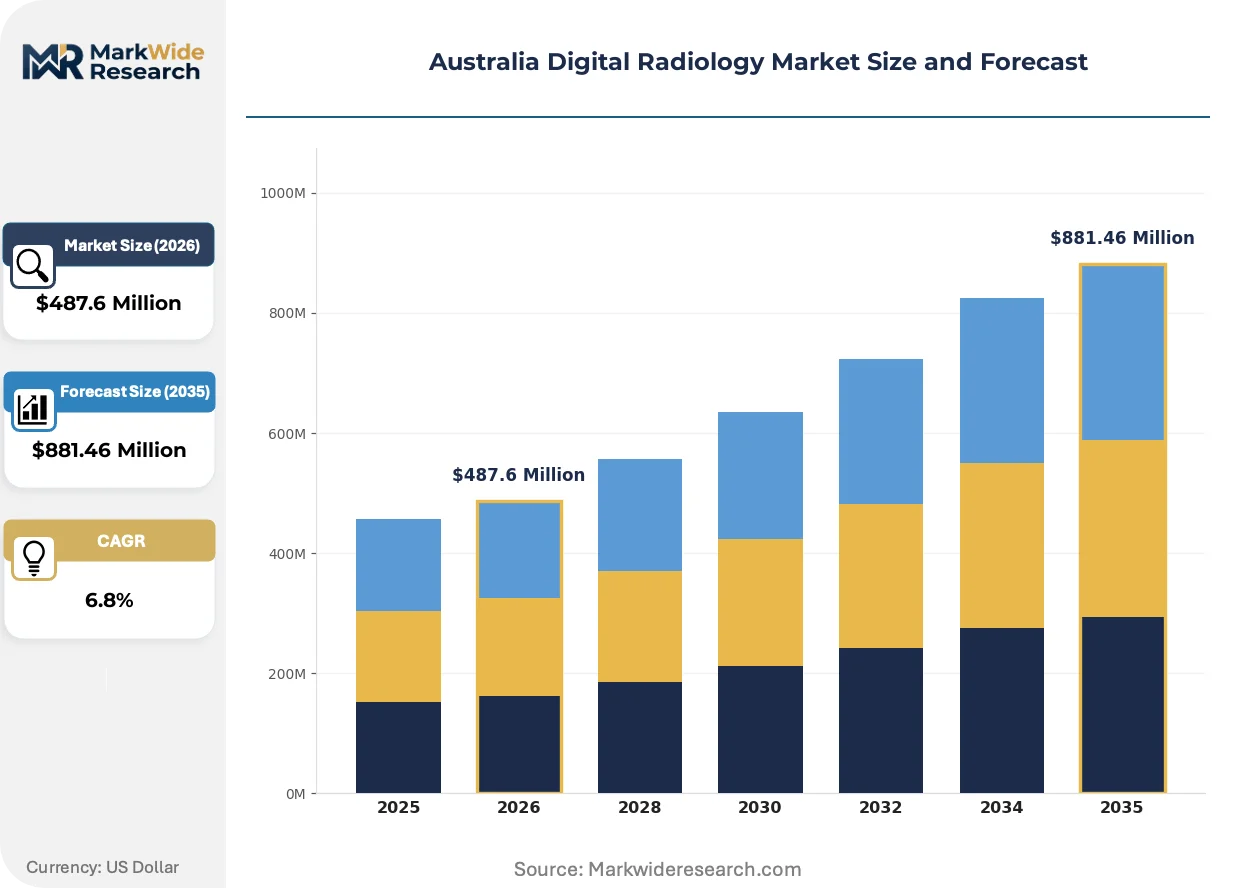
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Digital X-Ray, Digital Fluoroscopy, Mobile X-Ray Delivery Mode: Cloud-based, On-premise, Hybrid, Remote Access End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Academic Institutions Technology: 2D Imaging, 3D Imaging, Artificial Intelligence, Portable Systems |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Fujifilm Holdings Corporation, Carestream Health, Canon Medical Systems Corporation, I-MED Radiology Network, Sonic Healthcare, Everlight Radiology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Digital Radiology Market Trends and Innovations
Artificial intelligence integration is electrifying radiologist workflow automation, while cloud-native infrastructure and consolidated procurement frameworks reshape how diagnostic imaging capabilities reach Australian patients.
Dual-energy subtraction X-ray is electrifying tissue differentiation capabilities in chest and orthopedic imaging. Major metropolitan hospitals in Sydney and Melbourne are piloting these systems for trauma and pulmonary departments. The technology is electrifying demand for premium detector configurations that command higher service contract values.
TGA software-as-a-medical-device guidance is tightening validation requirements for AI-enabled diagnostic tools. Manufacturers must demonstrate clinical performance across Australian patient populations before ARTG inclusion. Diagnostic centers in Victoria are responding by demanding vendor-supplied clinical evidence packages that accelerate local adoption decisions.
State health department framework agreements are compressing vendor negotiation cycles and standardizing equipment specifications across hospital networks. Traditional distributor relationships with individual radiology departments are giving way to centralized procurement panels in New South Wales and Queensland. This pattern is most visible in capital works programs where equipment standardization reduces training and maintenance complexity.
Australia Digital Radiology Market Segmentation
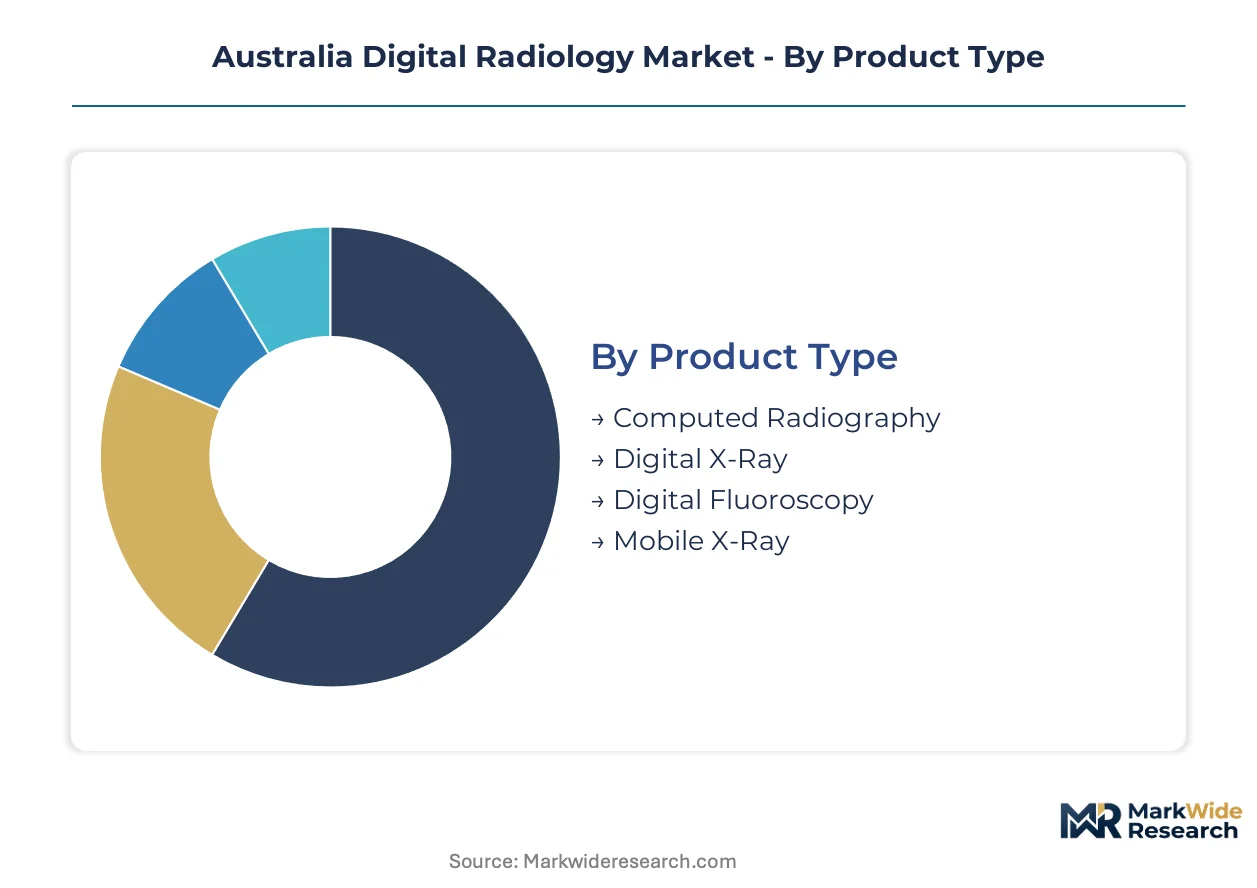
Segmentation in Australian digital radiology reveals how procurement consolidation, workflow specialization, and detector technology maturation create divergent investment profiles across product categories and delivery architectures. Understanding these divides enables vendors to align development roadmaps with state health department funding cycles and TGA registration pathways.
Product Type:
Standardization pressures from centralized state procurement frameworks clash with customization demands from specialized clinical departments across this category.
- Computed Radiography:Photostimulable phosphor plate systems capture latent images for laser scanning digitization. Demand persists in Western Australia and South Australia regional facilities where capital constraints delay full digital transitions, fragmenting vendor service obligations.
- Digital X-Ray:Direct-capture flat-panel detector systems achieve spatial resolution down to 139 micrometers for musculoskeletal applications. New South Wales and Victoria metropolitan hospital networks drive replacement demand as aging analog infrastructure reaches end-of-life, with orthopedic departments commanding premium configurations.
- Digital Fluoroscopy:Dynamic X-ray imaging systems enable real-time guidance for interventional procedures. Cardiology and gastroenterology departments in Queensland public hospitals concentrate procurement.
- Mobile X-Ray:Battery-powered wheeled units with wireless detector connectivity serve intensive care and emergency workflows. Tasmanian rural health networks represent underpenetrated first-mover territory.
Most installed capacity flows through Digital X-Ray systems. Expansion is steepest in Mobile X-Ray deployments.
Delivery Mode:
Cost tier stratification separates enterprise hospital networks from independent diagnostic centers across deployment architectures.
- Cloud-based:Scalable picture archiving with subscription economics. Diagnostic centers in Victoria seeking AI workflow integration drive fastest uptake.
- On-premise:Dedicated server infrastructure behind hospital firewalls. Queensland Health centralized frameworks mandate this architecture for cybersecurity compliance.
- Hybrid:Local caching with cloud burst capacity for peak demand. New South Wales metropolitan networks pilot this model for cost optimization.
- Remote Access:Teleradiology connectivity for regional reporting. Workforce distribution constraints in South Australia create dependency on this mode.
On-premise systems anchor current hospital procurement. Cloud-based delivery is climbing the fastest among independent operators.
End User:
Customer type determines purchasing authority structure and replacement cycle timing across Australian healthcare.
- Hospitals:Public hospital networks in New South Wales and Victoria consolidate radiology procurement under state health department frameworks, compressing vendor negotiation cycles while accelerating equipment standardization.
- Diagnostic Centers:Independent imaging facilities prioritize throughput optimization and AI-enabled workflow automation. Medicare Benefits Schedule revisions directly shape their capital investment timing.
- Outpatient Clinics:Specialist referral practices require compact footprint systems. Fujifilm's specialized digital X-ray portfolios target this workflow.
- Academic Institutions:Teaching hospitals combine clinical service with research protocols. TGA ARTG expedited review pathways for software-as-a-medical-device accelerate their technology adoption.
Hospitals command the dominant procurement volume. Diagnostic Centers are gaining share fastest as outpatient migration continues.
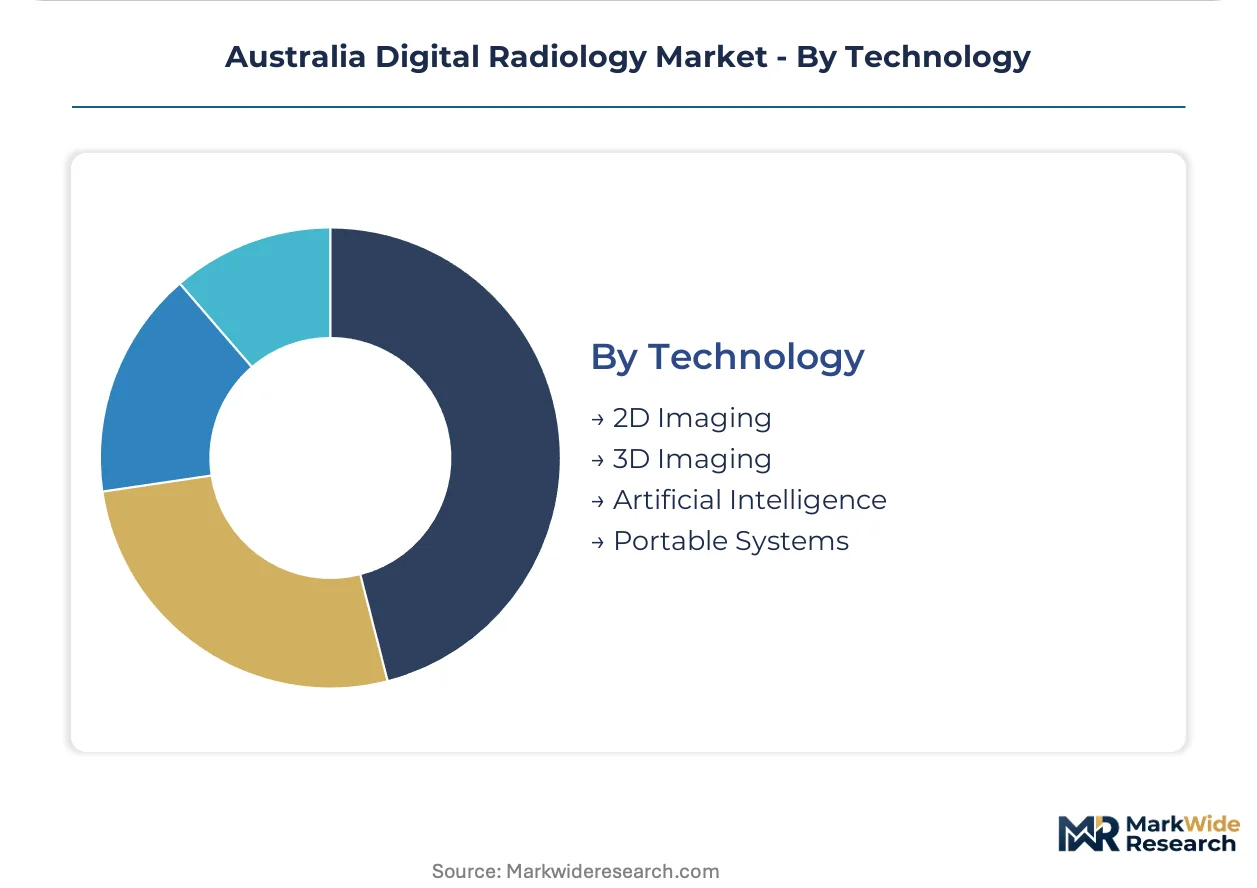
Technology:
Maturity gradients separate established imaging modalities from emerging AI-enabled platforms across this dimension.
- 2D Imaging:Conventional planar radiography with static detector acquisition. Remains the workhorse for general radiographic departments in budget-constrained facilities.
- 3D Imaging:Tomosynthesis and cone-beam computed tomography for volumetric reconstruction. Major metropolitan hospitals in Sydney pilot these for trauma and orthopedic applications.
- Artificial Intelligence:Machine learning algorithms for image analysis and workflow prioritization. TGA software-as-a-medical-device guidance tightens validation requirements, demanding clinical evidence packages.
- Portable Systems:Battery-operated units with wireless detector pairing. Rural health networks in Tasmania and Queensland regional expansion programs create deployment opportunities.
2D Imaging carries the largest installed base. Artificial Intelligence platforms show the steepest expansion trajectory as radiologist workforce constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and New Zealand present divergent procurement dynamics despite geographic proximity, with Australian state health department consolidation contrasting against New Zealand's district health board fragmentation. Both markets operate under Westminster-derived regulatory frameworks yet exhibit distinct reimbursement and capital allocation patterns.
New South Wales
Metropolitan hospital networks in Sydney and Newcastle drive replacement demand for aging analog infrastructure across radiology departments. NSW Health's centralized procurement frameworks compress vendor negotiation cycles while mandating equipment standardization across Local Health Districts. The Sydney Local Health District anchors procurement volume through major teaching hospitals integrating AI-enabled workflow tools.
Victoria
Orthopedic departments in Melbourne metropolitan hospitals command premium flat-panel detector configurations with spatial resolution down to 139 micrometers. The state's health technology assessment processes shape purchasing timelines through rigorous vendor qualification requirements. Alfred Health and Austin Health networks concentrate procurement authority, accelerating digital X-ray deployment across trauma and musculoskeletal units.
Queensland
Regional hospital expansion programs create procurement windows for computed radiography replacements in rural facilities from Townsville to Toowoomba. Queensland Health mandates on-premise PACS architecture for cybersecurity compliance across public networks. The Sunshine Coast and Gold Coast health districts pilot hybrid cloud-local caching models for cost optimization.
Western Australia
Budget-constrained regional facilities delay full digital transitions, fragmenting vendor service obligations across vast geographic distances. The state's mining sector generates occupational health imaging demand through corporate diagnostic contracts. Perth metropolitan hospitals anchor procurement volume while Pilbara and Kimberley regions depend on mobile X-ray deployments.
South Australia
Radiologist workforce distribution constraints intensify dependency on teleradiology connectivity for regional reporting across the Adelaide Hills and Fleurieu Peninsula. SA Health's capital works programs target equipment standardization across metropolitan and rural facilities. The Queen Elizabeth Hospital and Royal Adelaide Hospital networks concentrate advanced imaging procurement authority.
Australia Digital Radiology Market Competitive Landscape
North American and European producers anchor one tier; Asia-Pacific specialists hold differentiated positions in detector component supply. Market structure exhibits moderate consolidation among full-system integrators while detector manufacturing concentrates among specialty chemical producers. Three archetypes dominate: integrated imaging platform vendors, specialized detector technology suppliers, and diagnostic service network operators. Competitive moves center on R&D intensity in detector resolution and strategic partnerships with state health departments for framework agreement positioning.
Within the integrated platform tier, GE Healthcare and Siemens Healthineers exemplify archetypes leveraging installed base relationships for recurring service revenue. Fujifilm Holdings Corporation occupies a differentiated position through specialized digital X-ray portfolios. These three entities represent the dominant competitive anchors shaping procurement dynamics across Australian state health networks, with each sitting within distinct strategic postures regarding workflow specialization and technology integration.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Canon Medical Systems Corporation |
| I-MED Radiology Network |
| Sonic Healthcare |
| Everlight Radiology |
| Others |
Pricing and Supply Chain Analysis
State health department procurement consolidation has concentrated buyer power among sovereign-funded hospital networks, compressing vendor margins while enforcing standardized equipment specifications that limit pricing differentiation across New South Wales and Victoria health districts.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for amorphous selenium and cesium iodide scintillators, feeding cost compression through detector manufacturing tiers. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled flat-panel configurations from computed radiography systems and mobile units. Public hospital networks exhibit highest price sensitivity due to centralized framework agreements, while academic medical centers absorb premium positioning for research-capable platforms. Pricing pressure stems from TGA post-market surveillance cost recovery requirements that distributors embed in service contracts.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne anchor hub-and-spoke patterns that extend service coverage to Western Australia and Queensland regional hospitals. Manufacturing concentrates in Japan, South Korea, and Germany for detector substrates and precision electronics, with Australian vendors drawing from Asian specialty chemical producers for scintillator materials. Single-source vulnerability characterizes amorphous selenium supply chains, exposing equipment distributors to input volatility. Distribution runs through authorized service partners holding TGA medical device sponsor licenses, ensuring regulatory compliance across state health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where TGA software-as-a-medical-device guidance revisions accelerate procurement cycles for AI-enabled diagnostic platforms across Australian hospital networks.
For Market Incumbents: Hedge against centralized procurement margin compression by deepening service contract penetration in Queensland and Western Australia regional facilities. Secure ARTG expedited review pathway qualifications for software companion offerings before Medicare Benefits Schedule revisions lock in vendor selection criteria. Counter emerging AI-native entrants through detector technology R&D intensity in musculoskeletal resolution segments.
For New Entrants and Emerging Players: Begin with Tasmanian rural health networks where mobile X-ray infrastructure remains underpenetrated and procurement decisions sit at individual hospital level rather than state framework panels. Target diagnostic centers in Victoria seeking cloud-based PACS with AI workflow integration as the most penetrable segment. Pursue TGA priority registration partnerships with established medical device sponsors to bypass direct sponsor infrastructure requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional diagnostic service operators holding long-term Queensland Health contracts but lacking AI-enabled workflow capabilities. Five-to-ten year viability hinges on Medicare reimbursement policy continuity rather than equipment replacement cycles alone. Monitor ARTG inclusion decisions for software-as-a-medical-device platforms as the inflection signal for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Expedited Review Pathway Pursuit | Accelerates market entry for AI-enabled image analysis platforms ahead of Medicare schedule revisions. |
| Cloud-Native PACS Development | Captures diagnostic center demand in Victoria seeking scalable AI workflow integration. |
| Regional Hospital Service Contract Expansion | Defends margin position in Queensland and Western Australia against centralized procurement consolidation. |
| Detector Resolution R&D Investment | Sustains premium positioning in Sydney and Melbourne orthopedic department upgrade cycles. |
| Mobile X-Ray First-Mover Deployment | Secures positioning in Tasmanian rural networks before state health department framework expansion. |
Research Methodology
Coverage spans New South Wales, Victoria, Queensland, Western Australia, and South Australia, with primary inputs from each state health department procurement framework. The analysis combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads with secondary validation from TGA ARTG registration databases, Medicare Benefits Schedule revision records, and state capital works program disclosures. Bottom-up equipment unit economics triangulate against top-down health expenditure flows.
Rate-of-change decomposition separates volume effects from price mix shifts across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user category, and technology maturity tier, with detector resolution specifications and TGA registration status as healthcare-specific forecast inputs. CAGRs derive from logistic diffusion curves fitted to analog infrastructure replacement patterns and AI adoption S-cycles.
Several conditions sit outside the modeled scope, including sovereign tariff adjustments on semiconductor components and unannounced TGA guidance revisions. Forecasts reflect documented assumptions regarding Medicare reimbursement continuity and state health department procurement centralization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Open System MRI Market