
 India Digital Radiology Market | 2026-2036
India Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Radiology Market Insights
The capability gap between high-end imaging R&D spenders and assembly-dependent distributors is collapsing as import substitution policies tighten. Siemens Healthineers AG leverages its Bengaluru engineering center to localize MRI component production. GE Healthcare sustains installed-base dominance through service contracts across Apollo and Max hospital networks. Fujifilm Holdings Corporation differentiates via dry imaging chemistry that reduces recurring consumable costs for mid-tier diagnostic centers.
India digital radiology encompasses computed and direct radiography systems, ultrasound modalities, magnetic resonance imaging equipment, and computed tomography platforms that convert anatomical signals into digital images for clinical diagnosis; these systems employ detector arrays with spatial resolution typically exceeding 2.5 line pairs per millimeter to capture tissue contrast for radiologist interpretation. CT scanners command the steepest capital allocation among product types as trauma centers and oncology departments prioritize rapid volumetric acquisition. Mobile radiography systems expand fastest within the technology dimension as point-of-care units deploy into intensive care settings and rural health camps where fixed-room installation proves impractical.
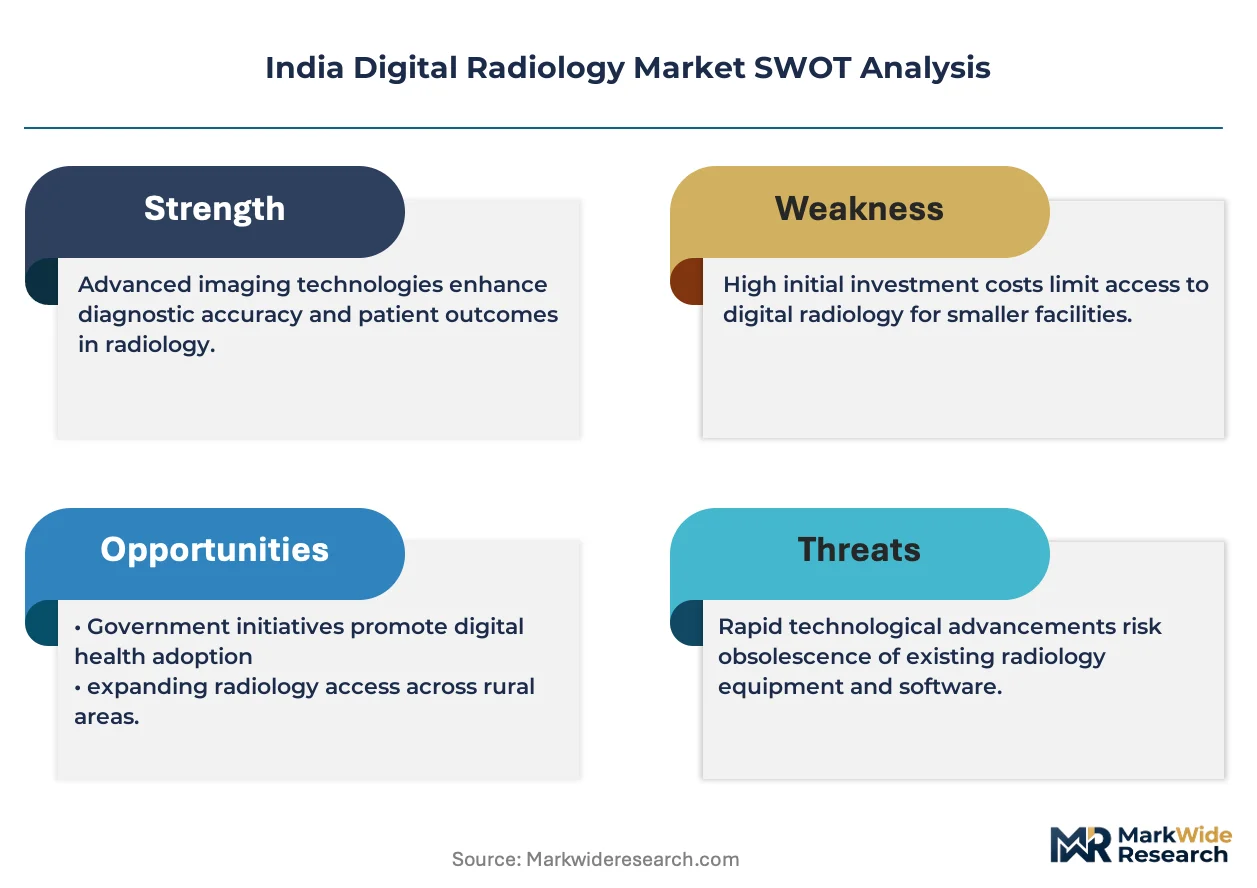
India's Central Drugs Standard Control Organisation mandates import registration and clinical performance validation for all Class C and Class D medical devices including digital X-ray and CT platforms, while the Bureau of Indian Standards enforces electromagnetic compatibility and radiation safety protocols under IS 7620. The PLI scheme for medical devices further redirects procurement toward domestic manufacturing by offering tiered production-linked incentives to original equipment manufacturers establishing local assembly. Stakeholders must monitor CDSCO's impending transition to risk-based device classification and alignment with Medical Device Rules amendments that will reshape market access timelines for multinational suppliers.
Market Dynamics
Import substitution mandates under India's PLI scheme for medical devices are compressing margins for pure distributors while rewarding engineering-intensive localization. Component sourcing patterns now pivot toward domestic vendors capable of detector array assembly and magnet fabrication.
Growth Catalysts
- Production-Linked Incentive tiers:CDSCO-registered OEMs establishing Bengaluru or Hyderabad manufacturing facilities qualify for 5-20% output-linked rebates, accelerating MRI gradient coil and CT detector domestic production.
- Tertiary-care hospital expansion:Corporate chains including Apollo and Max Healthcare are consolidating radiology procurement across Mumbai, Delhi, and Bangalore metro clusters under centralized capital allocation committees.
- Computed tomography trauma protocols:Emergency medicine departments now mandate sub-minute volumetric acquisition for stroke and trauma triage, driving replacement cycles for aging single-slice installations.
Market Restraints
- Superconducting magnet supply concentration:Liquid helium-cooled magnet fabrication remains concentrated among three global suppliers, exposing Indian assemblers to input cost volatility and shipping lead times exceeding 90 days.
- CDSCO import registration timelines:Class C and Class D device approvals require 12-18 month clinical validation cycles, creating regulatory friction for novel detector technologies seeking market access.
- Fixed-room installation economics:Shielding requirements and civil infrastructure costs for MRI suites exceed mobile radiography deployments by 8-10x, limiting penetration in district hospital budgets.
Strategic Opportunities
- Point-of-care mobile radiography:Intensive care units and rural health camps in Uttar Pradesh and Bihar present underpenetrated demand for battery-powered wireless detector systems requiring minimal infrastructure.
- Artificial intelligence reconstruction:Deep learning-based noise reduction is converging with low-dose CT protocols, enabling diagnostic confidence at reduced radiation exposure for pediatric oncology applications.
- Hub-and-spoke teleradiology networks:Diagnostic chains are deploying centralized interpretation capacity across tier-2 and tier-3 cities, creating channel innovation that decouples image acquisition from radiologist location.
Industry Challenges
- Clinical engineering talent scarcity:MRI and CT field service requires specialized training in cryogen handling and radiofrequency calibration, with accredited technician programs graduating fewer than 400 specialists annually against installed base expansion.
- PACS-EMR integration complexity:Legacy hospital information systems from disparate vendors create interoperability friction during digital radiology deployment, extending implementation timelines and requiring custom middleware development.
- Radiation safety officer certification:BIS IS 7620 compliance mandates facility-level radiation safety officers, with certification bottlenecks delaying commissioning for 15-20% of new installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Radiology Market |
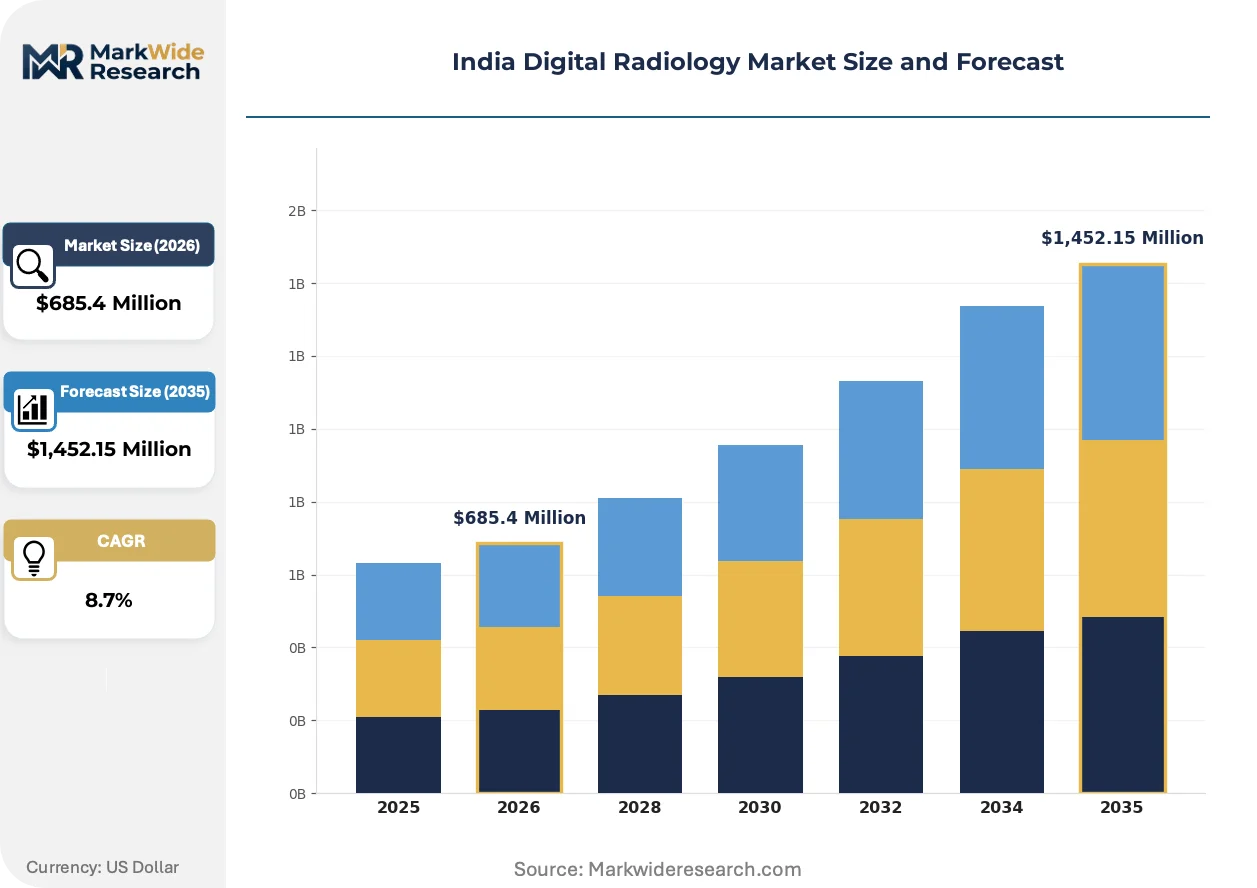
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, Ultrasound Systems, MRI Machines, CT Scanners End User: Hospitals, Diagnostic Centers, Research Laboratories, Specialty Clinics Technology: Direct Radiography, Computed Radiography, Mobile Radiography, 3D Imaging Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips NV, Fujifilm Holdings Corporation, Carestream Health, Canon Medical Systems, Shimadzu, Hitachi Ltd, Varex Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Radiology Market Trends and Innovations
Detector technology evolution and regulatory classification reforms are compressing equipment replacement cycles while redistributing value capture toward software-enabled service models. Three forces dominate this transition.
Flat-panel digital radiography detectors employing cesium iodide scintillator layers are displacing computed radiography cassette systems in mid-tier diagnostic centers. Corporate hospital procurement committees now specify direct radiography as baseline configuration for new installations. This displacement is compressing aftermarket service revenue for legacy cassette processor manufacturers while expanding detector refurbishment business lines.
CDSCO's impending transition to risk-based device classification under amended Medical Device Rules will recalibrate registration pathways for software-as-medical-device applications. AI-enabled image reconstruction algorithms previously exempt will face Class C scrutiny, extending validation timelines. Radiology OEMs with Bengaluru-based regulatory affairs teams are pre-positioning clinical evidence packages to maintain market access continuity.
After-sales service contracts are unbundling from equipment financing packages as hospital finance committees scrutinize total cost of ownership. Third-party service aggregators in Delhi and Chennai are capturing maintenance revenue through independent spare part sourcing and remote diagnostics platforms. This disintermediation is most visible among mid-tier diagnostic centers operating GE and Siemens installed bases outside corporate chain networks.
India Digital Radiology Market Segmentation
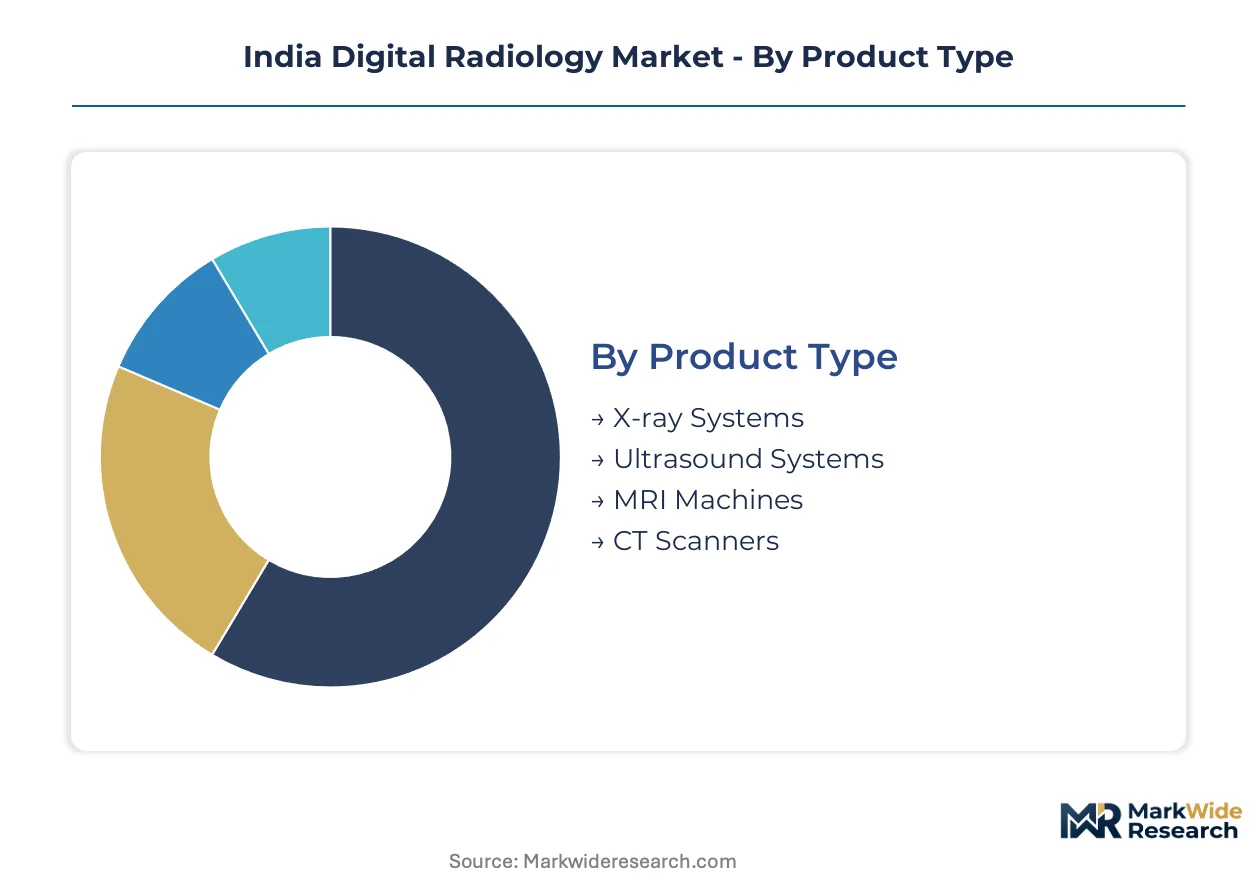
Procurement patterns across India's digital radiology market fragment sharply by capital intensity, clinical workflow integration, and regulatory classification under CDSCO's device risk tiers. Margin capture concentrates where domestic assembly meets precision diagnostics demand.
Product Type:
Margin pools concentrate in modalities requiring superconducting magnet fabrication and detector array calibration, where localization incentives reshape supplier economics.
- CT Scanners:Sub-minute volumetric acquisition systems employ multi-slice detector arrays with sub-millimeter spatial resolution. Trauma centers in Mumbai and Delhi drive replacement cycles as emergency medicine protocols mandate rapid stroke triage capabilities. Shielding infrastructure requirements limit district hospital penetration.
- MRI Machines:Superconducting systems with 1.5T and 3T field strengths utilize liquid helium-cooled magnet assemblies. Corporate hospital chains consolidate procurement across Bengaluru and Hyderabad clusters, though magnet supply concentration among three global fabricators exposes assemblers to input cost volatility.
- X-ray Systems:Fixed and mobile configurations span general radiography suites.
- Ultrasound Systems:Portable and cart-based platforms serve obstetrics and cardiac screening workflows.
CT Scanners holds installed capacity. MRI Machines is rotating up the share rankings.
End User:
Customer concentration varies by procurement sophistication, with centralized capital committees at corporate chains diverging from fragmented district hospital budgets.
- Hospitals:Tertiary-care institutions in Mumbai, Delhi, and Bangalore deploy integrated PACS-EMR architectures requiring custom middleware development. Apollo and Max Healthcare networks consolidate radiology procurement under centralized committees, compressing vendor negotiation cycles.
- Diagnostic Centers:Mid-tier chains in tier-2 cities deploy hub-and-spoke teleradiology networks decoupling image acquisition from radiologist location. Third-party service aggregators capture maintenance revenue through independent spare part sourcing.
- Research Laboratories:Academic medical centers require high-field MRI for spectroscopy protocols.
- Specialty Clinics:Orthopedic and cardiac focused facilities prioritize ultrasound and mobile radiography.
Hospitals command procurement volume leadership. Diagnostic Centers is expanding most quickly through channel innovation.
Technology:
Detector evolution and AI reconstruction algorithms are compressing replacement cycles while redistributing value toward software-enabled service models.
- Direct Radiography:Flat-panel detectors employing cesium iodide scintillator layers displace computed radiography cassette systems. Corporate hospital procurement committees now specify direct radiography as baseline configuration, compressing aftermarket service revenue for legacy processor manufacturers.
- Mobile Radiography:Battery-powered wireless detector systems deploy into intensive care settings and rural health camps in Uttar Pradesh and Bihar where fixed-room installation proves impractical. Point-of-care units are climbing the fastest among technology segments.
- Computed Radiography:Cassette-based systems persist in budget-constrained district facilities.
- 3D Imaging:Tomosynthesis and volumetric reconstruction platforms serve orthopedic and mammography applications.
Direct Radiography holds installed capacity. Mobile Radiography is rotating up the share rankings.
Application:
Clinical workflow specialization drives modality preference, with oncology and trauma protocols commanding premium acquisition specifications.
- Oncology:Low-dose CT protocols with deep learning-based noise reduction enable diagnostic confidence at reduced radiation exposure for pediatric applications. CDSCO's impending risk-based classification will recalibrate registration pathways for AI reconstruction algorithms.
- Orthopedics:Weight-bearing CT and digital radiography systems with specialized reconstruction algorithms serve joint replacement planning. Demand concentrates in corporate hospital sports medicine departments.
- Cardiology:ECG-gated CT angiography and cardiac MRI require temporal resolution optimization.
- Neurology:Functional MRI and diffusion tensor imaging support neurosurgical planning protocols.
Oncology holds installed capacity. Orthopedics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Maharashtra and Karnataka where tertiary-care hospital procurement committees extract volume discounts, while Uttar Pradesh and Bihar diagnostic centers absorb premium markups on mobile radiography systems due to infrastructure constraints and fragmented demand.
Maharashtra
Mumbai's corporate hospital chains consolidate radiology procurement under centralized capital allocation committees, compressing vendor negotiation cycles for CT and MRI installations. CDSCO mandates import registration and clinical validation for Class C and Class D devices entering this cluster. Siemens Healthineers leverages its Bengaluru engineering center to supply gradient coils to assemblers serving Maharashtra's metro hospitals.
Karnataka
Bengaluru anchors domestic manufacturing incentives under the PLI scheme for medical devices, with OEMs qualifying for output-linked rebates between 5-20 percent. BIS enforces electromagnetic compatibility and radiation safety protocols under IS 7620 for all locally assembled platforms. Hyderabad's magnet fabrication vendors feed into Karnataka-based MRI system integrators, though liquid helium supply remains concentrated among three global sources.
Delhi-NCR
Tertiary-care institutions in Delhi deploy integrated PACS-EMR architectures requiring custom middleware development, extending implementation timelines. CDSCO's impending transition to risk-based device classification under amended Medical Device Rules will recalibrate registration pathways for AI reconstruction algorithms. Max Healthcare networks consolidate radiology procurement across Delhi and adjacent NCR cities under unified technical specifications.
Tamil Nadu
Chennai's third-party service aggregators capture maintenance revenue through independent spare part sourcing and remote diagnostics platforms, disintermediating OEM service contracts. BIS radiation safety officer certification bottlenecks delay commissioning for 15-20 percent of new installations in this cluster. Corporate diagnostic chains deploy hub-and-spoke teleradiology networks from Chennai into tier-2 cities across southern states.
Uttar Pradesh
Rural health camps and intensive care units in Uttar Pradesh present underpenetrated demand for battery-powered wireless detector systems requiring minimal infrastructure. PLI scheme incentives redirect procurement toward domestic manufacturing, though district hospital budgets remain constrained by fixed-room installation economics. Point-of-care mobile radiography climbs fastest in this sub-region where fixed-room shielding costs exceed mobile deployments by 8-10x.
India Digital Radiology Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that combine equipment manufacturing with captive service networks. Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips NV anchor the premium tier through installed-base dominance and long-term service contracts. The vendor base separates into three strategic archetypes: integrated OEMs with domestic assembly operations, specialized detector fabricators supplying subsystems, and third-party service aggregators capturing aftermarket maintenance. Competitive moves center on backward integration into magnet and detector component production, plus geographic expansion of teleradiology interpretation networks.
Among Germany-based diversified health technology groups, Siemens Healthineers AG exemplifies the integrated OEM archetype through its Bengaluru engineering center localization. GE Healthcare, a US-based conglomerate, anchors the premium-tier service contract model across Apollo and Max hospital networks. Fujifilm Holdings Corporation, a Japanese imaging specialist, occupies a differentiation position through dry imaging chemistry that reduces recurring consumable costs for mid-tier diagnostic centers.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips NV |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Canon Medical Systems |
| Shimadzu |
| Hitachi Ltd |
| Varex Imaging |
| Others |
Pricing and Supply Chain Analysis
Import substitution of superconducting magnets by domestic gradient coil fabrication simultaneously relocates supply geography toward Bengaluru-Hyderabad clusters and compresses pricing premiums for MRI systems previously anchored to German and Japanese magnet imports. CDSCO's PLI tier rebates accelerate this shift by rewarding output-linked localization with 5-20 percent rebates that offset the 8-10x infrastructure cost premium of fixed-room installations.
Pricing Analysis
Configured-to-order MRI systems with 3T field strength and custom gradient specifications command 40-60 percent premiums over standard 1.5T configurations with fixed protocol packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnet field strength, detector array resolution, and after-sales service bundling. Cost compression in mid-tier diagnostic centers is intensifying because third-party service aggregators in Delhi and Chennai disintermediate OEM maintenance contracts. Corporate hospital chains with centralized procurement committees exhibit lowest price sensitivity, while district hospitals in Uttar Pradesh and Bihar face acute budget constraints on fixed-room shielding investments.
Supply Chain Analysis
Inventory cycles exceeding 90 days for liquid helium-cooled magnet assemblies expose Indian system integrators to input cost volatility and commissioning delays. Superconducting magnet fabrication concentrates in Germany, Japan, and the United States, while detector array scintillator materials source from South Korea and Taiwan. Single-source vulnerability sits with the three global magnet suppliers that feed Bengaluru and Hyderabad assembly operations. Distribution runs through corporate hospital procurement committees in Mumbai and Delhi, mid-tier diagnostic chains in tier-2 cities, and third-party service aggregators capturing aftermarket maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's digital radiology market represents an early-cycle expansion story as point-of-care mobile radiography penetration in intensive care and rural health settings remains below 15 percent of addressable demand. PLI scheme incentives and CDSCO localization mandates create durable tailwinds for domestic assembly investments.
For Market Incumbents: Secure installed-base dominance through captive service networks and long-term parts availability commitments that third-party aggregators cannot replicate. Deepen backward integration into detector array calibration and gradient coil production at Bengaluru engineering centers to offset magnet supply concentration risk. Defend against emerging teleradiology networks by embedding AI reconstruction algorithms within equipment financing packages. For New Entrants and Emerging Players: Lead with battery-powered wireless detector systems targeting Uttar Pradesh and Bihar rural health camps where fixed-room installation economics fail. Capture share in hub-and-spoke teleradiology interpretation networks across tier-2 cities that decouple image acquisition from radiologist location. Prioritize CDSCO regulatory affairs capabilities to navigate impending risk-based device classification transitions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic chains operating mid-tier radiology networks outside Apollo and Max corporate umbrellas. Five-to-ten year viability hinges on software-enabled service revenue capture and AI reconstruction algorithm differentiation. Monitor CDSCO registration timelines for Class C and Class D devices as inflection indicators for market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Risk-Based Classification Alignment | Pre-positions AI reconstruction algorithms for Class C scrutiny under amended Medical Device Rules. |
| Magnet Supply Diversification Partnership | Reduces single-source vulnerability from German and Japanese superconducting fabricators. |
| Mobile Radiography Channel Expansion | Captures underpenetrated demand in Uttar Pradesh and Bihar rural health infrastructure. |
| Teleradiology Network Deployment | Decouples image acquisition from radiologist location across tier-2 and tier-3 cities. |
| Third-Party Service Aggregation Platform | Disintermediates OEM maintenance contracts through independent spare part sourcing. |
Research Methodology
A spread of perspectives from hospital procurement committee directors, biomedical engineering heads, CDSCO regulatory affairs specialists, and third-party service aggregator operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against BIS standards documentation, CDSCO device registration databases, and PLI scheme disbursement records. Bottom-up equipment installation tracking and top-down healthcare infrastructure spend estimates were triangulated to anchor market sizing.
Segmentation dimensions modeled span product type, end user category, technology platform, and clinical application across the analysis window. CAGRs were derived from fitted growth curves applied to disclosed procurement volumes and import substitution trajectories. Forecast inputs incorporated PLI incentive tier utilization rates and CDSCO registration pipeline velocity for Class C and Class D devices.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding or accelerated CDSCO regulatory reform timelines would require recalibration. Forecasts reflect documented assumptions regarding magnet supply continuity and helium price stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
US Contrast Media Market
Medical Imaging
Preclinical Ultrasound Systems Market