
 China Magnetic Resonance Imaging Market | 2026-2036
China Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Magnetic Resonance Imaging Market Outlook
High-field MRI specification tiers is collapsing the gap between imported and domestic system performance. Siemens Healthineers leverages its superconducting magnet supply chain to sustain premium positioning in top-tier hospitals. United Imaging Healthcare anchors its growth on self-developed 3.0T platforms with proprietary gradient coil technology. Neusoft Medical Systems Co Ltd competes through integrated PACS-MRI workflow solutions tailored for China's hospital information system architectures.
Magnetic Resonance Imaging deploys superconducting or permanent magnets to generate static magnetic fields between 0.2 and 7.0 Tesla, utilizing radiofrequency pulses and gradient coils to excite hydrogen nuclei and reconstruct tomographic images based on relaxation time differences. The technology serves diagnostic radiology, intraoperative navigation, and research neuroimaging by delivering non-ionizing soft-tissue contrast superior to computed tomography. Closed MRI systems dominate installed base value due to their higher field strength and signal-to-noise ratios, while functional MRI applications in pre-surgical brain mapping represent the fastest-growing demand segment as neurosurgical departments expand across China's Class A hospitals. Hybrid MRI technology combining positron emission tomography or linear accelerator guidance captures concentrated margin pools from oncology and radiation therapy departments seeking real-time imaging during intervention.
NMPA's Class III medical device registration requirements and GB standards for electromagnetic compatibility shape product development timelines and clinical trial obligations for domestic and foreign manufacturers alike. The National Healthcare Security Administration's diagnostic reimbursement catalogs directly influence hospital procurement priorities and system utilization rates across provinces. China's dual carbon goals from MEE are forcing magnet cooling system redesigns toward helium conservation and closed-cycle cryogen architectures. Stakeholders must monitor provincial centralized procurement pilots for medical imaging equipment, as these programs threaten to commoditize mid-field system pricing while creating volume commitments that favor manufacturers with scalable domestic production footprints.
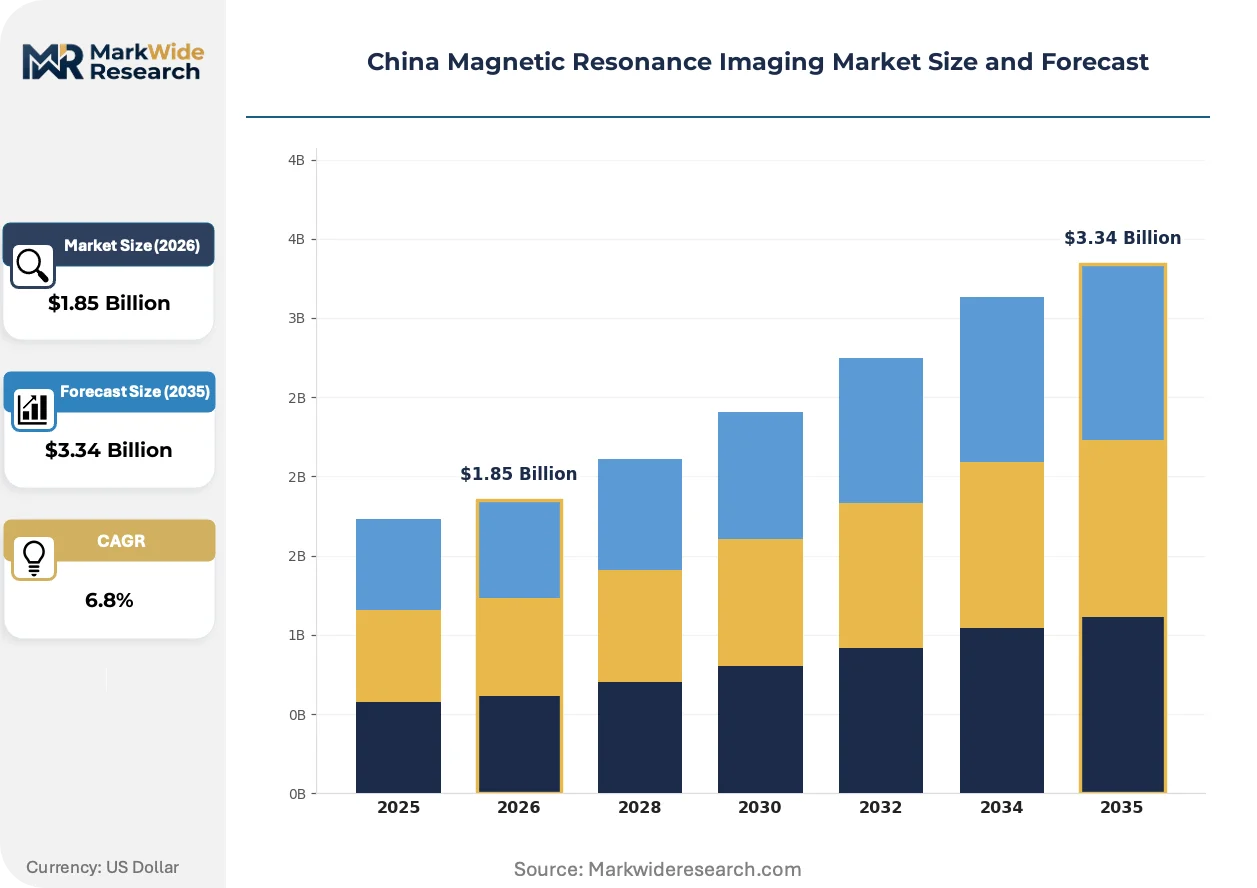
Market Dynamics
NMPA's compressed Class III review timelines are accelerating domestic manufacturer market entry while helium conservation mandates from MEE force magnet cooling system redesigns across installed base refresh cycles.
Growth Catalysts
- Yangtze River Delta hospital cluster:Tier-3 hospitals in Shanghai, Jiangsu, and Zhejiang are expanding neurosurgical departments and driving concentrated demand for high-field diagnostic systems.
- Dual carbon goals:MEE mandates on helium conservation are pushing domestic manufacturers toward closed-cycle cryogen architectures that reduce operational dependency on imported helium supplies.
- GB electromagnetic compatibility standards:Harmonized technical requirements are streamlining product development timelines for domestic MRI platforms seeking NMPA registration.
Market Restraints
- Superconducting magnet supply concentration:Premium field strength systems remain dependent on specialized magnet suppliers concentrated in Germany and Japan, creating input bottlenecks for domestic manufacturers scaling production.
- Helium price volatility:Global helium supply constraints are elevating operational costs for hospitals running conventional cryogen-cooled systems without closed-cycle recovery.
- Class III clinical trial obligations:NMPA's mandatory multi-site trials for novel field strengths extend registration timelines and elevate pre-market capital requirements for system innovators.
Strategic Opportunities
- Hybrid PET-MRI oncology installations:Real-time imaging during radiation therapy represents underpenetrated demand from oncology departments in provincial Class A hospitals seeking margin expansion.
- PACS-MRI workflow integration:Hospital information system architectures in China favor vendors delivering seamless radiology-IT convergence, opening differentiation paths for domestic software-hardware bundles.
- Provincial centralized procurement pilots:Volume commitment programs favor manufacturers with scalable domestic production footprints and localized service networks.
Industry Challenges
- Gradient coil engineering talent scarcity:Domestic manufacturers face recruitment bottlenecks for physicists capable of optimizing proprietary coil designs for 3.0T platform performance parity with imported systems.
- Legacy system integration complexity:Hospital procurement committees prioritize backward compatibility with existing radiology information systems, elevating software adaptation costs for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Magnetic Resonance Imaging Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Application: Neurology, Orthopedics, Cardiology, Oncology End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Centers Technology: Classic MRI, Hybrid MRI, High-Field MRI, Low-Field MRI |
| Companies Covered | Canon Medical Systems Corporation, Neusoft Medical Systems Co Ltd, Siemens Healthineers, United Imaging Healthcare, Shenzhen Anke High-tech Co Ltd, GE Healthcare, Shenzhen Basda Medical Apparatus Co Ltd, Jiangsu Magspin Instrument Co Ltd, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Magnetic Resonance Imaging Market Strategic Shifts
Functional MRI applications are expanding beyond research into routine pre-surgical planning, while regulatory pressure on helium consumption and procurement centralization are reshaping competitive positioning.
Gradient coil technology is bifurcating the performance gap between imported and domestic 3.0T platforms. Provincial hospital procurement committees are accelerating adoption of domestically engineered systems with proprietary coil architectures. This capability convergence is compressing premium pricing power for legacy superconducting magnet suppliers while elevating service responsiveness as a competitive differentiator.
NMPA's streamlined Class III medical device review process is compressing approval timelines from domestic manufacturers. The regulatory shift reduces time-to-market penalties for innovators developing novel field strengths or hybrid configurations. Domestic MRI platforms with complete technical documentation packages are capturing expanded share in tier-2 and tier-3 hospital procurement cycles.
Hospital procurement committees are unbundling after-sales service contracts from equipment sales, forcing manufacturers to compete on discrete service pricing and response time guarantees. Provincial health commissions are mandating transparent lifecycle cost disclosures that elevate total cost of ownership visibility. This behavioral shift is most pronounced in Jiangsu and Zhejiang, where centralized procurement pilots require separate evaluation of maintenance, upgrade, and decommissioning cost structures.
China Magnetic Resonance Imaging Market Segmentation
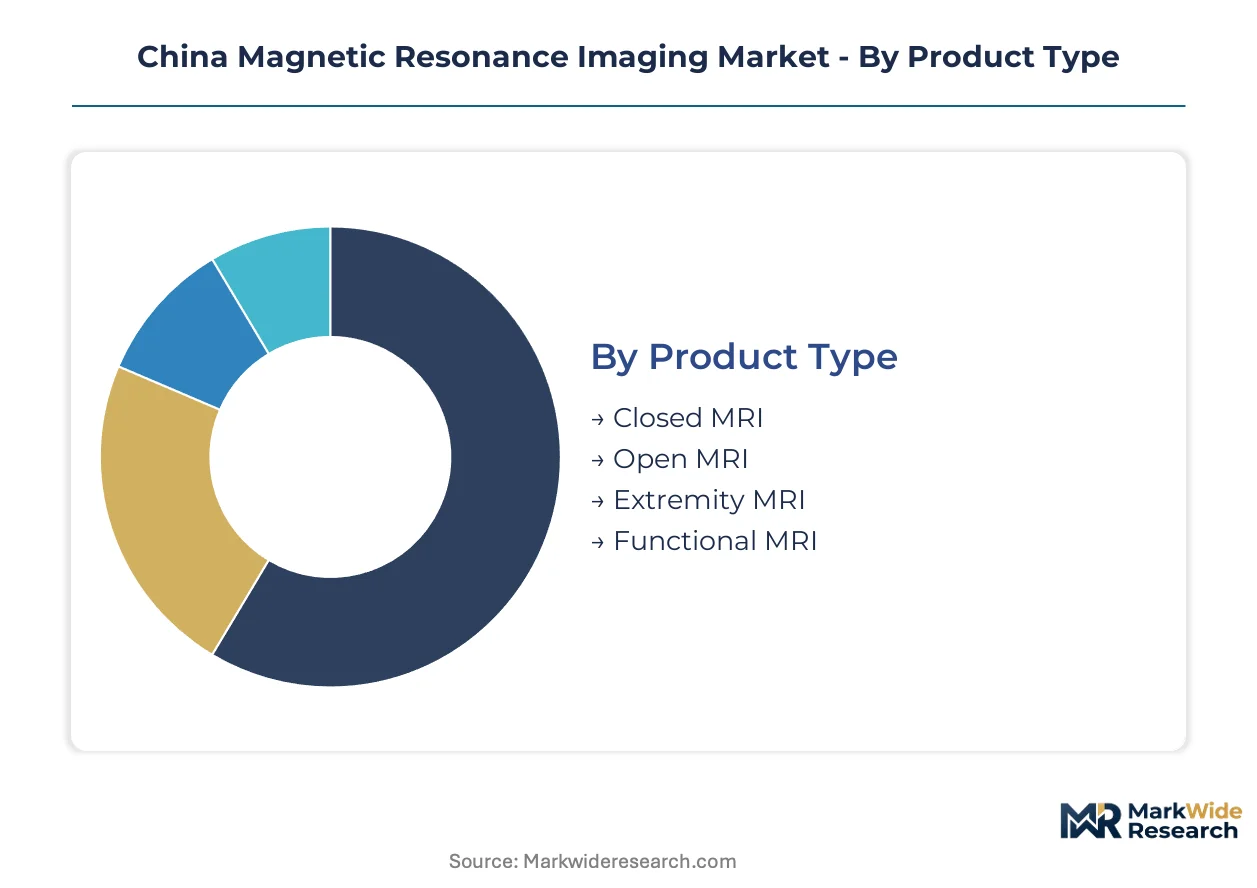
Magnetic resonance imaging in China fragments across equipment architecture, clinical application, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
Domestic production concentrates on closed and open configurations, while functional MRI platforms remain import-dependent due to gradient coil complexity.
- Closed MRI:Superconducting magnets generate field strengths from 1.5T to 3.0T within cylindrical bore designs. Demand clusters in Shanghai and Jiangsu Tier-3 hospitals expanding neurosurgical departments, with NMPA's compressed Class III timelines accelerating domestic manufacturer entry.
- Open MRI:Permanent magnet or resistive designs with vertical or horizontal gap geometries accommodate claustrophobic patients and bariatric cases. Provincial hospitals in Zhejiang favor these systems for orthopedic throughput where field strength requirements are modest.
- Extremity MRI:Dedicated limb-scanning platforms with compact footprints target outpatient diagnostic centers.
- Functional MRI:Blood-oxygen-level-dependent imaging for pre-surgical brain mapping requires specialized gradient performance.
Closed MRI commands the established base. The steepest expansion runs through functional MRI.
Application:
Clinical use cases split between high-volume screening workflows and complex interventional guidance where reimbursement rates justify capital intensity.
- Neurology:Brain and spinal cord imaging exploits MRI's superior soft-tissue contrast against CT. Yangtze River Delta hospital clusters drive concentrated procurement as neurosurgical departments expand across Class A facilities.
- Oncology:Tumor characterization and treatment response monitoring leverage multi-parametric sequences. Hybrid PET-MRI installations in provincial capitals capture margin pools from radiation therapy departments seeking real-time guidance.
- Orthopedics:Musculoskeletal trauma and joint replacement planning generates routine throughput.
- Cardiology:Cardiac MRI remains underpenetrated due to motion artifact complexity and specialized training requirements.
Neurology anchors current installed value. Oncology applications are climbing the fastest as hybrid configurations penetrate provincial markets.
End User:
Procurement authority and reimbursement access create sharp segmentation in customer economics and sales cycle duration.
- Hospitals:Tier-3 facilities in provincial capitals wield centralized procurement budgets and access to National Healthcare Security Administration reimbursement catalogs. These buyers prioritize 3.0T field strength and PACS integration.
- Diagnostic Centers:Independent imaging facilities compete on throughput and turnaround time, favoring 1.5T platforms with rapid sequence protocols.
- Research Institutes:Academic medical centers demand 7.0T experimental systems for neuroimaging protocols.
- Imaging Centers:Chain-operated outpatient facilities concentrate in urban clusters with self-pay patient bases.
Hospitals dominate capital deployment. Diagnostic centers are gaining share fastest as outpatient imaging unbundles from inpatient facilities.
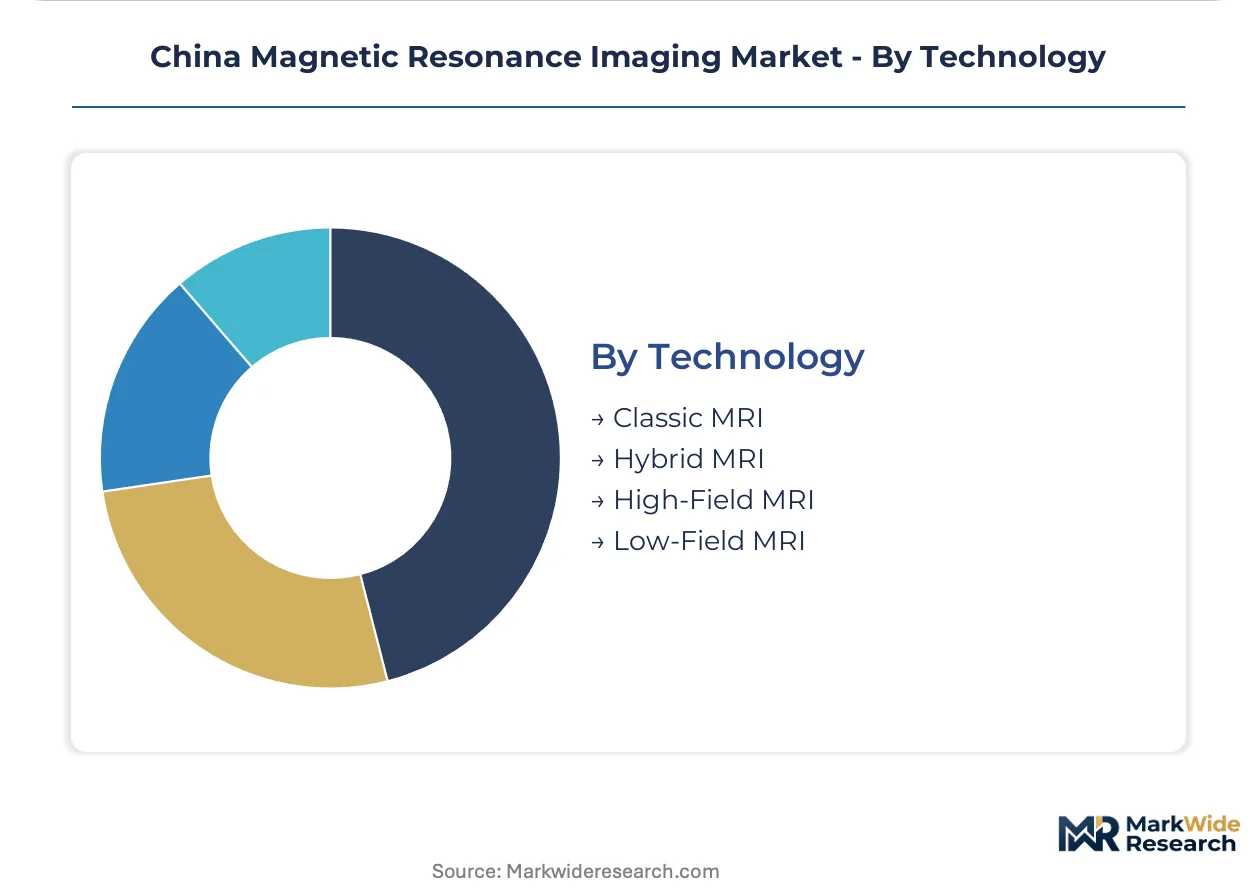
Technology:
Field strength and system architecture determine helium dependency, cooling complexity, and regulatory classification under NMPA guidelines.
- High-Field MRI:Systems at 3.0T and above deliver signal-to-noise ratios essential for functional neuroimaging. Domestic manufacturers like United Imaging Healthcare anchor growth on proprietary gradient coil platforms that narrow performance gaps with imported equipment.
- Hybrid MRI:PET-MRI and LINAC-MRI configurations fuse metabolic or therapeutic modalities with anatomical imaging. Oncology departments in Jiangsu and Zhejiang pilot these installations despite premium pricing.
- Classic MRI:Conventional superconducting systems without modality fusion dominate refresh cycles.
- Low-Field MRI:Permanent magnet designs below 0.5T serve rural hospitals with limited infrastructure.
Classic MRI sustains the installed base. Hybrid configurations are expanding most quickly as provincial hospitals pursue margin expansion in radiation therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconducting magnet fabrication concentrates in Germany and Japan, creating input dependencies for Chinese manufacturers scaling domestic production. Provincial health commissions across China are piloting centralized procurement programs that favor localized service networks and scalable manufacturing footprints.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang host the densest concentration of Tier-3 hospitals expanding neurosurgical departments and driving 3.0T system procurement. NMPA's streamlined Class III review timelines accelerate domestic manufacturer market entry in this cluster. Nanjing and Hangzhou medical centers anchor hybrid PET-MRI pilot installations for radiation therapy guidance.
Beijing-Tianjin-Hebei
Academic medical centers in Beijing demand 7.0T experimental systems for neuroimaging research protocols. SAMR procurement guidelines favor domestic manufacturers with complete technical documentation packages. Tianjin port infrastructure facilitates superconducting magnet import logistics for system integrators.
Sichuan-Chongqing
Western China hospital networks prioritize 1.5T platforms with rapid sequence protocols for high-volume screening workflows. MEE dual carbon goals push magnet cooling system redesigns toward helium conservation in this region. Chengdu anchors diagnostic center expansion serving self-pay patient bases.
Shandong Peninsula
Provincial hospitals in Jinan and Qingdao favor open MRI configurations for orthopedic throughput where field strength requirements remain modest. GB electromagnetic compatibility standards streamline product development timelines for domestic platforms seeking NMPA registration. Local manufacturing parks attract gradient coil engineering talent.
China Magnetic Resonance Imaging Market Competitive Environment
Concentration sits with diversified medical technology conglomerates possessing captive superconducting magnet supply chains. Siemens Healthineers and GE Healthcare occupy premium positioning in top-tier hospitals through magnet technology control. Three archetypes define competitive structure: integrated multinationals with magnet fabrication capabilities, domestic champions with proprietary gradient coil platforms, and regional specialists with PACS-integrated workflow solutions. Strategic moves center on provincial centralized procurement participation and closed-cycle cryogen architecture development.
Within the domestic champion tier, United Imaging Healthcare and Neusoft Medical Systems Co Ltd exemplify manufacturers narrowing performance gaps with imported systems through self-developed 3.0T platforms. Siemens Healthineers represents the integrated multinational archetype sustaining premium positioning via superconducting magnet supply chain control. Shenzhen Anke High-tech Co Ltd and Shenzhen Basda Medical Apparatus Co Ltd occupy positions among regional specialists serving hospital information system integration requirements.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Neusoft Medical Systems Co Ltd |
| Siemens Healthineers |
| United Imaging Healthcare |
| Shenzhen Anke High-tech Co Ltd |
| GE Healthcare |
| Shenzhen Basda Medical Apparatus Co Ltd |
| Jiangsu Magspin Instrument Co Ltd |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
NMPA's Class III medical device certification gates both supplier qualification and price differentiation simultaneously. Tier-3 hospital procurement committees in the Yangtze River Delta use NMPA registration status as the primary filter for vendor eligibility, while field strength tiers and gradient coil provenance determine negotiated price bands within qualified vendor pools.
Pricing Analysis
NMPA's Class III review timelines dictate the pricing tier structure across domestic and imported system portfolios. Three-tier pricing structure across premium, standard, and economy levels separates 7.0T research systems from 3.0T diagnostic platforms and 1.5T screening workhorses, with certification grade and after-sales service bundling as the primary differentiation drivers. Cost compression in mid-field segments is intensifying because provincial centralized procurement pilots mandate transparent lifecycle cost disclosures. Diagnostic centers exhibit the highest price sensitivity due to throughput-dependent margin structures, while neurosurgical departments in Class A hospitals demonstrate the lowest sensitivity given reimbursement rate insulation.
Supply Chain Analysis
Strategic stockpiling of superconducting magnets and helium reserves dominates inventory strategy across domestic MRI manufacturers facing supply volatility. Superconducting magnet fabrication concentrates in Germany and Japan, while gradient coil engineering talent clusters in the United States and select European research centers. Raw material dependencies rest on niobium-titanium superconducting wire, liquid helium for cryogen cooling, and high-purity copper for gradient windings. Single-source vulnerability from concentrated magnet suppliers creates structural risk for domestic manufacturers scaling production. Distribution runs through provincial health commission procurement platforms and hospital GPO contracts with tiered service level agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment. NMPA's compressed Class III timelines advantage incumbents with established clinical trial infrastructure and technical documentation libraries, erecting switching costs that deter rapid competitive displacement.
For Market Incumbents: Compound defensive positioning through captive superconducting magnet supply arrangements and proprietary gradient coil R&D pipelines. Siemens Healthineers and GE Healthcare should deepen backward integration into cryogen recovery systems to offset MEE helium conservation mandates. Threat from United Imaging Healthcare's 3.0T platform parity demands accelerated service responsiveness investments in Jiangsu and Zhejiang procurement zones.
For New Entrants and Emerging Players: After-sales service unbundling represents the most penetrable service-layer gap where legacy multinationals under-serve provincial hospital networks. Target diagnostic center chains in Sichuan-Chongqing with rapid-sequence 1.5T platforms and transparent per-scan pricing models. Go-to-market execution should emphasize PACS-HIS integration capabilities that match Neusoft Medical Systems' workflow architecture.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid PET-MRI sub-segments due to modality fusion complexity and specialized shielding requirements. Long-term viability favors manufacturers with closed-cycle cryogen architectures and scalable domestic production footprints. Acquisition target archetype: regional specialists with hospital information system integration capabilities and established provincial service networks. Signal to watch: provincial centralized procurement pilot expansion beyond Jiangsu and Zhejiang into Shandong and Sichuan.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Cycle Cryogen Architecture Development | MEE dual carbon mandates force helium conservation redesigns across installed base refresh cycles. |
| Proprietary Gradient Coil Platform Investment | Domestic manufacturers narrow performance gaps with imported 3.0T systems through self-developed coil engineering. |
| Provincial Centralized Procurement Participation | Volume commitment programs in Jiangsu and Zhejiang favor scalable domestic manufacturing footprints. |
| PACS-MRI Workflow Integration | Hospital information system architectures in China prioritize seamless radiology-IT convergence capabilities. |
| Hybrid PET-MRI Oncology Installation | Radiation therapy departments in provincial Class A hospitals seek real-time imaging guidance for margin expansion. |
Study Parameters
Operator-level perspectives from hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and NMPA regulatory affairs specialists anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from NMPA Class III registration databases, provincial health commission procurement disclosures, hospital equipment tender records, and GB standards documentation. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure modeling provided triangulation across data sources.
Sensitivity analysis framed the quantitative approach across the projection horizon. Segmentation dimensions modeled include field strength tier, system architecture, clinical application, end-user category, and regional hospital cluster. CAGRs derived from equipment replacement cycle analysis, neurosurgical department expansion rates, and reimbursement catalog inclusion trajectories. Forecast inputs incorporated superconducting magnet import dependency ratios and helium price volatility indices.
Underlying assumptions cover NMPA review timeline stability, provincial procurement pilot continuity, and superconducting magnet supply chain resilience, with deviation risk concentrated in regulatory acceleration or supply disruption scenarios. Revision becomes warranted when centralized procurement program geographic coverage crosses threshold expansion into western provincial markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Contrast Media Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
North America Digital Radiology Market