
 Mobile Computed Tomography Scanners Market | 2026-2036
Mobile Computed Tomography Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Computed Tomography Scanners Market Outlook
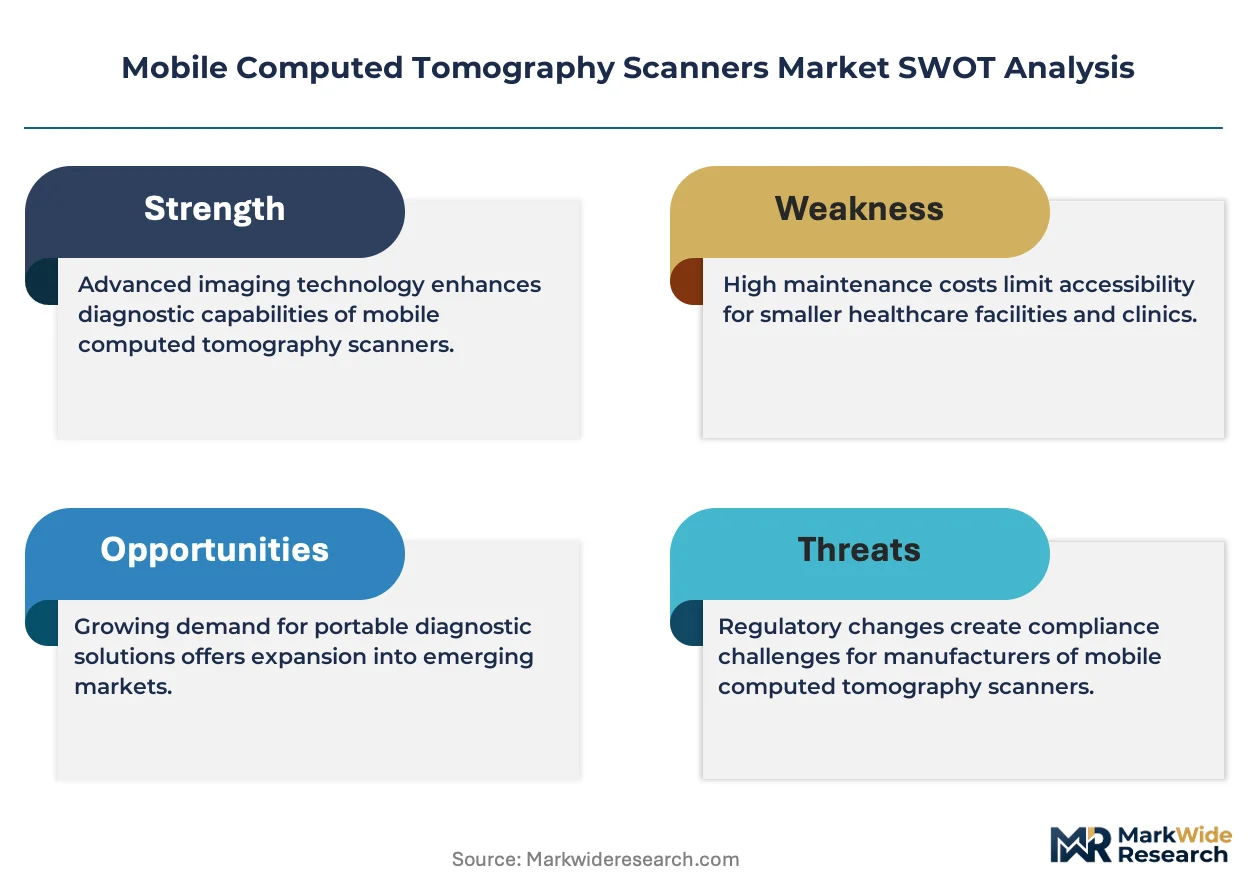
Software-defined reconstruction licensing is rebalancing how OEMs monetize mobile CT platforms, shifting revenue from hardware shipments to recurring analytics subscriptions. Siemens Healthineers leverages its digital twin infrastructure to sustain service attach rates across installed truck-based systems. GE Healthcare anchors its mobile portfolio on AI-enabled spectral imaging packages that reduce radiologist interpretation time. NeuroLogica Corporation specializes in compact, battery-powered head CT units designed for ambulance and emergency department deployment.
Mobile computed tomography scanners are self-contained imaging systems mounted on vehicles or designed for transport, typically producing cross-sectional anatomical images with spatial resolution down to sub-millimeter slice thickness and tube voltages ranging from 80 to 140 kVp. Their primary purpose is to deliver diagnostic-grade CT capability at point-of-care locations lacking fixed infrastructure, including disaster zones, military theaters, and rural emergency departments. Portable CT scanners command premium pricing due to battery-operated gantry designs that eliminate site preparation costs, while photon counting CT represents the fastest-growing technology segment as detector material advances promise dose reduction alongside improved tissue characterization. Emergency Medical Services applications are gaining structural importance as pre-hospital stroke assessment protocols expand reimbursement eligibility for mobile neuroimaging.
FDA 510(k) premarket notification requirements govern device safety and efficacy for U.S. mobile CT commercialization, while EU MDR certification mandates clinical evidence for portable systems sold under CE marking across European member states. Japan's PMDA enforces QMS conformity assessments that extend approval timelines for truck-mounted scanners relative to fixed-room equivalents. Stakeholders must monitor evolving reimbursement codes for pre-hospital CT imaging, as coverage decisions by national health technology assessment bodies will determine whether mobile deployment models achieve sustainable unit economics outside emergency neurology.
Market Dynamics
Photon counting detector arrays are compressing dose-exposure thresholds while expanding tissue differentiation capabilities, forcing OEMs to redesign gantry architectures around cadmium zinc telluride substrates rather than legacy scintillator-photodiode sandwiches.
Growth Catalysts
- Pre-hospital stroke protocols:Emergency Medical Services fleets in the United States are integrating mobile CT units into ambulance-based triage workflows. Reimbursement eligibility expansion under CMS stroke care guidelines accelerates capital deployment.
- FDA 510(k) streamlining:The FDA's premarket notification pathway for portable neurological imaging systems reduces commercialization timelines. Device manufacturers leverage predicate device databases to accelerate clearance for truck-mounted platforms.
- German interventional radiology density:University hospitals in Germany operate the highest concentration of mobile CT units for intraoperative imaging. Academic medical centers drive replacement cycles through research-funded procurement.
Market Restraints
- Helium dependency:Superconducting magnet cooling requirements tie mobile CT economics to volatile helium supply chains. Cryogen scarcity in Qatar and Russia constrains production scheduling for high-field systems.
- EU MDR clinical evidence mandates:The European Union Medical Device Regulation requires prospective clinical data for CE marking of portable CT systems. Small manufacturers face capital barriers to compiling technical documentation.
- Fixed-room substitution:Hospital-based CT suites with 128-slice capabilities absorb volume that mobile units might otherwise capture. Radiology departments prioritize throughput over point-of-care flexibility.
Strategic Opportunities
- Rural emergency department penetration:Critical access hospitals in the United States lack on-site CT capacity. Mobile deployment models address geographic imaging deserts without infrastructure investment.
- Battery-powered ambulance integration:Lithium-ion gantry designs eliminate generator noise and vibration constraints. Emergency vehicles gain diagnostic-grade neuroimaging without engine-idle requirements.
- Software-defined reconstruction licensing:OEMs monetize installed hardware through recurring analytics subscriptions. Cloud-based image processing shifts revenue from capital sales to recurring service attach.
Industry Challenges
- Radiation physicist staffing:Mobile CT operations require certified medical physicists for shielding verification and dose optimization. Rural deployment sites struggle to secure qualified personnel.
- Cross-state licensing complexity:Interstate transport of radioactive calibration sources triggers varying state-level regulations. Fleet operators navigate fragmented compliance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Computed Tomography Scanners Market |
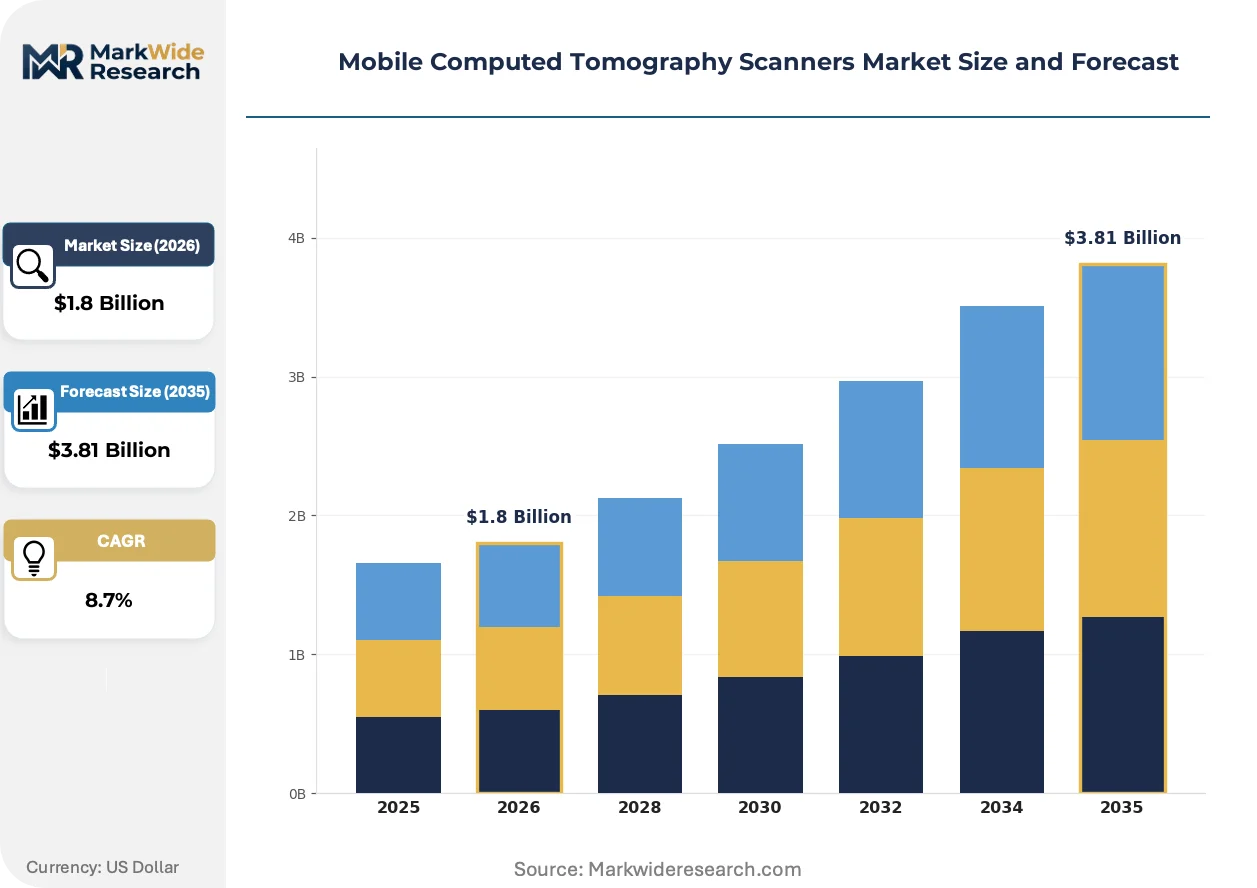
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed CT Scanners, Portable CT Scanners, Dual Energy CT Scanners, Cone Beam CT Scanners End User: Hospitals, Diagnostic Centers, Research Institutions, Emergency Medical Services Technology: Spiral CT, Helical CT, Digital Tomosynthesis, Photon Counting CT Application: Oncology, Neurology, Cardiovascular, Trauma Assessment |
| Companies Covered | Koninklijke Philips N.V., NeuroLogica Corporation, GE Healthcare, Hitachi Ltd., Shenzhen Anke High-Tech, Siemens Healthineers, United Imaging Healthcare, Neusoft Medical Systems, Canon Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Computed Tomography Scanners Market Strategic Shifts
Detector material science and reconstruction algorithm licensing are compressing the traditional hardware-software boundary. OEMs now compete on analytics attach rates rather than slice count alone.
Photon counting CT is unifying spectral imaging with single-source acquisition. Academic medical centers in Germany and the United States are piloting cadmium zinc telluride detector arrays for simultaneous multi-energy tissue characterization. The technology is unifying previously separate contrast-enhanced and non-contrast workflows into single-scan protocols.
Japan's PMDA has extended QMS conformity assessment timelines for truck-mounted scanners relative to fixed-room equivalents. Device manufacturers face 18-24 month approval gaps that compress first-mover advantages. Domestic OEMs with established PMDA relationships capture disproportionate share of hospital procurement cycles.
Subscription-based reconstruction licensing is displacing perpetual software ownership. Hospital procurement departments in the United States now evaluate total cost of ownership across 7-year service contracts rather than upfront capital expenditure. Radiology administrators prioritize vendors with cloud-native image processing and remote protocol update capabilities.
Mobile Computed Tomography Scanners Market Segmentation
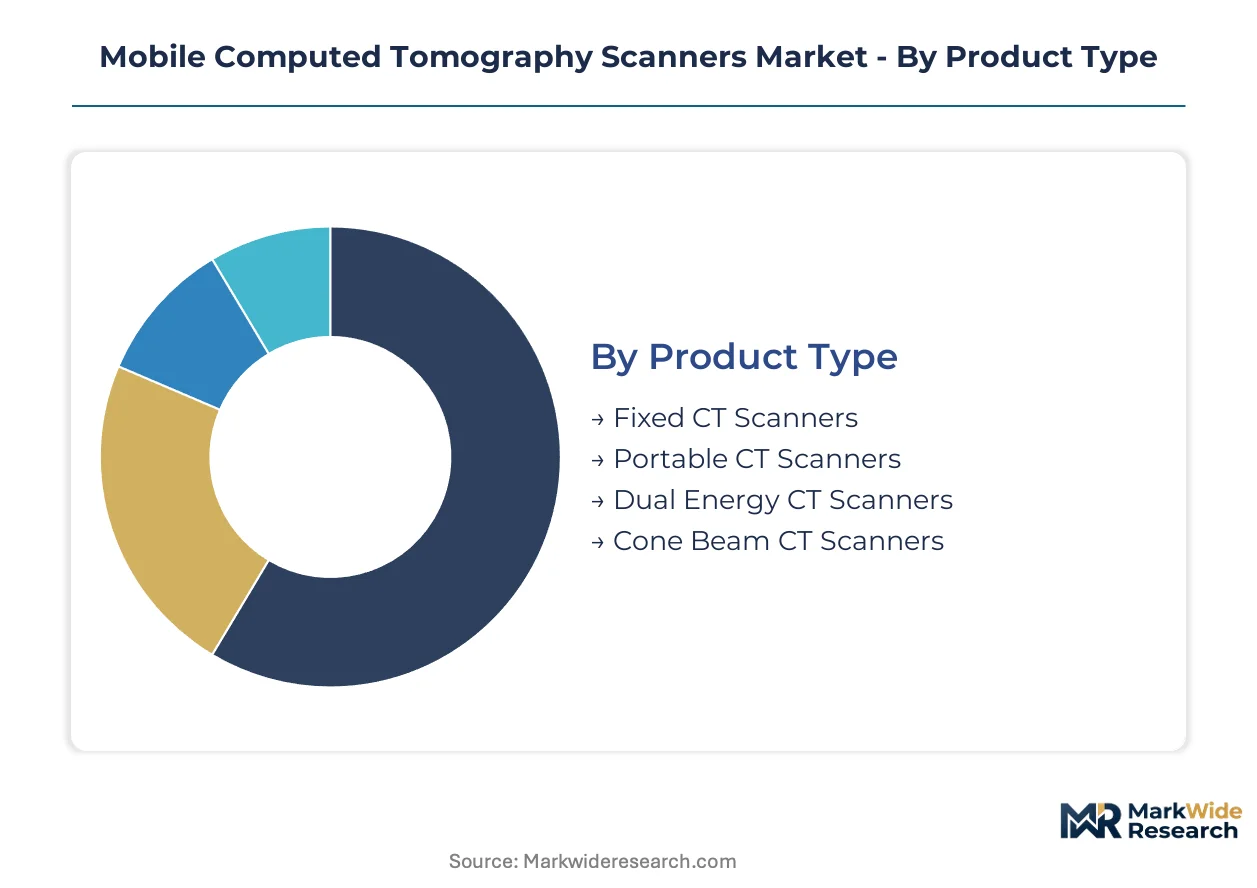
Mobile CT scanner segmentation reveals how regulatory pathways and reimbursement eligibility fragment across deployment models. Product architecture, clinical setting, detector technology, and disease application each carry distinct certification burdens and capital intensity profiles that shape procurement decisions.
Product Type:
FDA 510(k) clearance timelines vary substantially across mobility tiers, with portable systems facing shorter predicate-device pathways than truck-mounted platforms requiring vehicle safety certifications.
- Fixed CT Scanners:Truck-mounted gantry systems with integrated shielding and climate control. University hospitals in Germany deploy these for intraoperative imaging, driving replacement cycles through research-funded procurement.
- Portable CT Scanners:Battery-powered head units with lithium-ion gantry designs eliminating generator noise constraints. Emergency Medical Services fleets in the United States integrate these for pre-hospital stroke triage under expanded CMS reimbursement guidelines.
- Dual Energy CT Scanners:Spectral imaging platforms requiring enhanced radiation physicist staffing for protocol optimization.
- Cone Beam CT Scanners:Compact systems with flat-panel detectors suited for extremity imaging in critical access settings.
Fixed CT scanners sit at the top of the volume ranking, with portable CT scanners climbing the fastest.
End User:
Capital availability and reimbursement sophistication separate customer tiers, with academic medical centers absorbing premium photon-counting systems while rural sites prioritize lease-based deployment models.
- Hospitals:Tertiary centers with 24/7 interventional radiology coverage and in-house medical physics departments. These sites justify high-field systems through throughput volume and complex case mix.
- Diagnostic Centers:Outpatient imaging chains with standardized protocols and centralized quality assurance. Their procurement favors vendor service contracts over capital ownership.
- Research Institutions:Academic sites requiring CE marking under EU MDR for clinical trial deployment, extending documentation burdens relative to standard commercial clearance.
- Emergency Medical Services:Fleet operators navigating cross-state licensing complexity for radioactive calibration source transport. Pre-hospital stroke protocols are expanding reimbursement eligibility for ambulance-based neuroimaging.
Hospitals command the largest installed base, while Emergency Medical Services represents the steepest expansion trajectory.
Technology:
Detector material science is compressing dose-exposure thresholds, with cadmium zinc telluride substrates displacing legacy scintillator-photodiode architectures in premium segments.
- Spiral CT:Continuous rotation acquisition with slip-ring gantry designs. These systems dominate replacement cycles in established hospital radiology departments.
- Helical CT:Overlapping slice acquisition enabling volumetric reconstruction. Diagnostic centers favor these for throughput efficiency in high-volume outpatient settings.
- Digital Tomosynthesis:Limited-angle acquisition with lower dose profiles. Research institutions pilot these for orthopedic applications requiring metal artifact reduction.
- Photon Counting CT:Cadmium zinc telluride detector arrays enabling simultaneous multi-energy tissue characterization. Academic medical centers in Germany and the United States are piloting single-scan protocols unifying contrast-enhanced and non-contrast workflows.
Spiral CT maintains volume leadership, with photon counting CT gaining share fastest among technology tiers.
Application:
Reimbursement code density varies sharply by clinical domain, with stroke neurology commanding dedicated mobile imaging codes that cardiovascular and oncology applications lack.
- Oncology:Staging and treatment response assessment requiring contrast-enhanced multiphase protocols. These workflows demand higher tube output and extended scan ranges.
- Neurology:Pre-hospital stroke triage with time-critical decision thresholds. Emergency Medical Services protocols in the United States are driving mobile CT deployment for ambulance-based imaging.
- Cardiovascular:Coronary calcium scoring and angiography requiring cardiac gating capabilities. These applications remain concentrated in fixed-room installations due to temporal resolution requirements.
- Trauma Assessment:Whole-body survey imaging in disaster zones and military theaters. Portable systems with rapid deployment protocols serve field hospitals lacking infrastructure investment.
Neurology leads procedure volume among mobile deployments, with trauma assessment expanding most quickly in defense and disaster response procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany operates the densest concentration of truck-mounted CT units globally, while the United States drives ambulance-based deployment through CMS reimbursement expansion for pre-hospital stroke triage.
United States
Emergency Medical Services fleets in California and Texas are integrating battery-powered head CT units for ambulance-based stroke assessment. FDA 510(k) clearance pathways for portable neurological imaging systems accelerate commercialization timelines for device manufacturers. Academic medical centers in Boston and Houston pilot photon counting detector arrays for intraoperative imaging applications.
Germany
University hospitals in Bavaria and North Rhine-Westphalia operate the highest concentration of mobile CT units for interventional radiology procedures. EU MDR certification mandates prospective clinical evidence for CE marking of portable systems sold across European member states. The Munich and Heidelberg clusters drive replacement cycles through research-funded procurement of truck-mounted platforms.
Japan
Domestic OEMs with established PMDA relationships capture disproportionate share of hospital procurement cycles for mobile gantry systems. Japan's PMDA enforces QMS conformity assessments that extend approval timelines for truck-mounted scanners relative to fixed-room equivalents. The Tokyo-Osaka corridor concentrates demand for compact CT units designed for emergency department deployment.
China
Domestic manufacturers in Shenzhen and Beijing scale production of portable CT platforms for rural hospital penetration. NMPA regulatory pathways govern device safety and efficacy for commercialization of mobile imaging systems. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing capacity for battery-operated gantry designs.
United Kingdom
NHS trusts in London and Manchester deploy mobile CT units to address geographic imaging deserts in critical access settings. MHRA regulations align with EU MDR requirements for clinical evidence supporting portable system deployment. The Cambridge-Oxford-London triangle drives research applications for photon counting detector technology in academic medical centers.
Mobile Computed Tomography Scanners Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with diversified health technology conglomerates anchoring premium-tier hospital procurement while regional fabricators capture price-sensitive rural deployments. The vendor base organizes around three strategic archetypes: integrated imaging conglomerates with digital twin infrastructure, compact-system specialists focused on battery-powered ambulance integration, and emerging-market manufacturers scaling cost-optimized portable platforms. Competitive dynamics center on M&A activity consolidating detector material supply chains and strategic partnerships licensing cloud-native reconstruction algorithms.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare occupy positions exemplifying the integrated-service archetype, while NeuroLogica Corporation represents the compact-specialist tier focused on point-of-care neurological applications. Chinese manufacturers including Shenzhen Anke High-Tech and United Imaging Healthcare sit within the emerging-market scale tier, leveraging domestic supply chain density to address cost-sensitive procurement in Asia-Pacific and Latin American markets. These three archetypes—integrated conglomerate, compact specialist, and regional scale player—define competitive positioning across the technology spectrum from photon counting premium systems to battery-powered ambulance units.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| NeuroLogica Corporation |
| GE Healthcare |
| Hitachi Ltd. |
| Shenzhen Anke High-Tech |
| Siemens Healthineers |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Canon Medical Systems |
| Others |
Value Chain & Pricing Dynamics
EU MDR clinical evidence mandates for CE marking are gating qualified supply access and premium-tier pricing power, as manufacturers face capital barriers to technical documentation that smaller competitors cannot surmount. This regulatory filter concentrates premium pricing among incumbent OEMs with established European compliance infrastructure while forcing price-sensitive buyers toward Chinese portable platforms with streamlined domestic certification pathways.
Pricing Analysis
Capacity additions in China are reshaping price floors for battery-powered portable CT units, compressing margins for mid-tier manufacturers in South Korea and Japan. Pricing stratifies across premium photon-counting systems, standard helical CT platforms, and economy-tier cone-beam configurations, with differentiation driven by detector material grade and FDA 510(k) versus CE marking certification level. Cost compression in the economy tier is intensifying because Shenzhen-based manufacturers leverage domestic lithium-ion supply chains. Emergency Medical Services fleets exhibit highest price sensitivity due to reimbursement uncertainty, while German university hospitals show least sensitivity given research-funded procurement cycles.
Supply Chain Analysis
Medical physicist certification requirements in Germany and the United States constrain qualified workforce availability for gantry assembly and calibration protocols. Manufacturing concentrates in China, Germany, and Japan, with cadmium zinc telluride substrates, superconducting magnets, and lithium-ion battery packs anchoring component dependencies. Single-source vulnerability runs through Qatar and Russia for helium cryogen supply, threatening production scheduling for high-field systems. Distribution feeds from OEM direct sales for hospital systems and third-party medical device distributors for rural emergency department penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-defined reconstruction licensing shifting revenue from capital sales to recurring analytics subscriptions. OEMs capturing cloud-native image processing attach rates will widen profitability spreads against hardware-only competitors.
For Market Incumbents: Extend digital twin infrastructure investments to sustain service attach rates across installed truck-based systems, countering emerging Chinese manufacturers scaling cost-optimized portable platforms. Prioritize backward integration into cadmium zinc telluride detector supply chains to secure photon counting CT component access before academic medical center replacement cycles accelerate.
For New Entrants and Emerging Players: Battery-powered ambulance integration represents the most penetrable white-space target, with CMS reimbursement expansion for pre-hospital stroke triage creating procurement tailwinds. Target critical access hospitals in the United States lacking on-site CT capacity through lease-based deployment models with remote protocol update capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for compact-system specialists because fragmented regional service networks create attach-rate arbitrage opportunities for consolidated platforms. Five-to-ten year viability hinges on cloud-native reconstruction algorithm licensing penetration displacing perpetual software ownership. Watch FDA 510(k) clearance velocity for portable neurological imaging systems as the inflection indicator for first-mover advantage durability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Portable neurological imaging systems gain faster commercialization timelines through predicate device databases. |
| CE Marking Pathway Investment | EU MDR clinical evidence mandates require prospective data compilation for European market access. |
| Hospital System Partnership | German university hospitals drive replacement cycles through research-funded truck-mounted platform procurement. |
| Software Companion Development | Cloud-native image processing shifts OEM revenue from capital sales to recurring analytics subscriptions. |
| Reimbursement Strategy | CMS stroke care guidelines determine sustainable unit economics for ambulance-based mobile CT deployment. |
Study Parameters
Bottom-up Emergency Medical Services fleet modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and EMS fleet operations directors combined with secondary validation against FDA 510(k) clearance databases, CMS reimbursement code filings, and EU MDR technical documentation registries. Triangulation across these sources ensures volume estimates align with procurement cycle visibility and regulatory pathway timelines.
Historical trendline analysis of truck-mounted and portable CT unit deployments established baseline penetration patterns across the projection horizon. The analytical framework segments by mobility tier, detector technology, end-user setting, and regional regulatory cluster, with CAGRs derived from replacement cycle timing and reimbursement eligibility expansion trajectories. Photon counting CT adoption curves and battery-powered gantry cost-down trajectories inform technology transition assumptions throughout the modeling period.
The model holds under stable helium supply chain conditions and consistent FDA 510(k) review timelines; deviation in cryogen scarcity events or EU MDR documentation burden escalation would shift installed base forecasts and OEM profitability profiles. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
United States Mammography Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Contrast Media Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Portable MRI Market