
 Global Veterinary X-Ray Market | 2026-2036
Global Veterinary X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary X-Ray Market Foresight
ISO 13485 certification for veterinary medical devices is bifurcating the competitive landscape between qualified manufacturers and marginal suppliers. IDEXX Laboratories leverages its integrated diagnostics platform to dominate North American veterinary clinic channels. FUJIFILM Holdings Corporation anchors its position through proprietary flat panel detector technology and deep R&D investment. Carestream Health competes by sustaining a broad product portfolio spanning both analog and digital modalities.
Veterinary X-ray systems generate diagnostic images of animal musculoskeletal, thoracic, and abdominal structures using ionizing radiation, with digital variants employing cesium iodide or gadolinium oxysulfide scintillator layers on thin-film transistor arrays to achieve spatial resolution below 150 micrometers. Flat panel detectors are displacing computed radiography in veterinary clinics due to faster image acquisition and elimination of cassette handling, while portable X-ray units are capturing growing share among equine and large animal practitioners who require field-deployable imaging. Digital X-ray systems command premium pricing but deliver superior workflow efficiency and DICOM compatibility that justifies replacement cycles in high-volume animal hospitals.
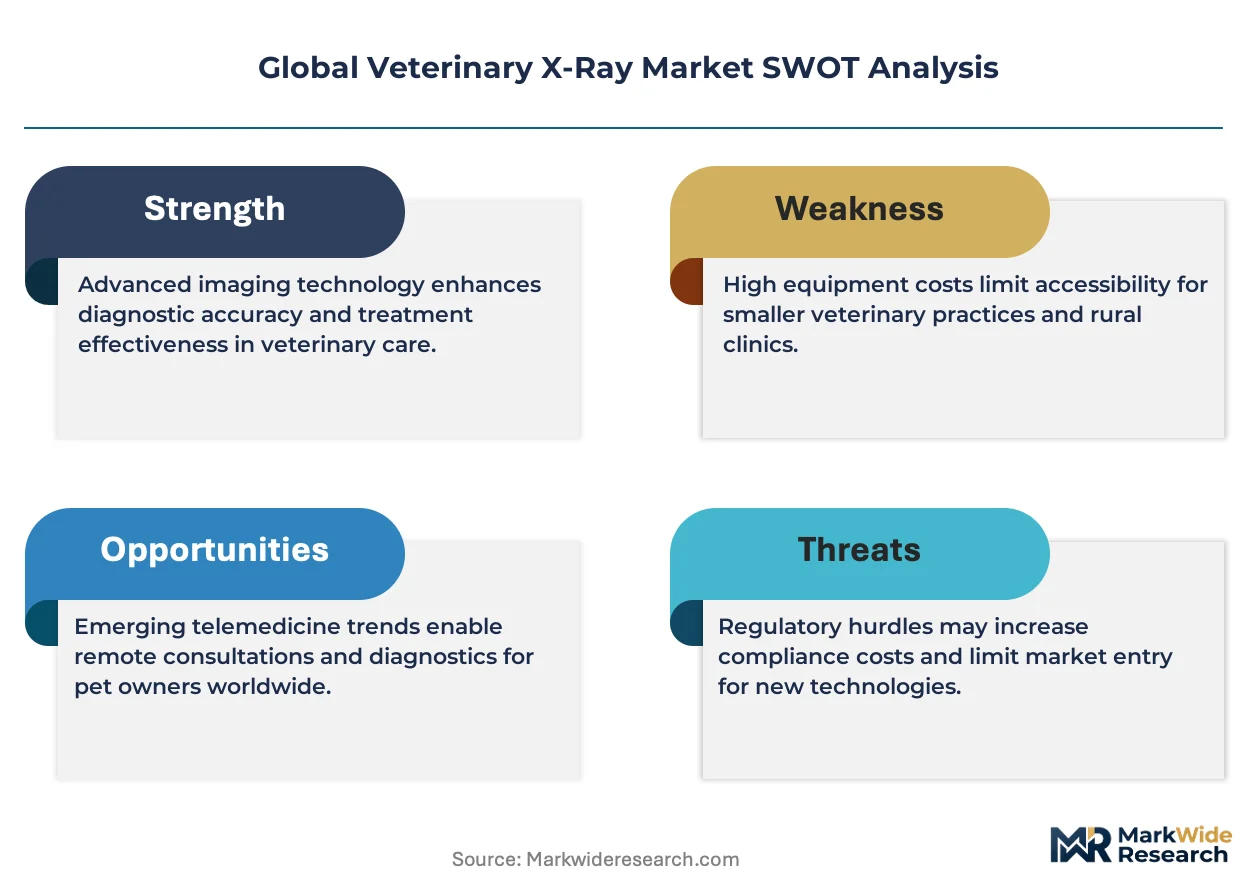
FDA Center for Veterinary Medicine oversees device safety labeling, while CE marking under the EU Medical Device Regulation governs European market access, and Japan's PMDA enforces QMS conformity for imported imaging equipment. These frameworks elevate compliance costs for entrants but protect incumbent manufacturers with established quality systems. Stakeholders must monitor evolving software-as-a-medical-device classifications for AI-enhanced image interpretation tools that are entering veterinary workflows.
Market Dynamics
Digital flat panel detectors are compressing replacement cycles across veterinary clinics as image acquisition speed becomes the decisive procurement criterion for high-volume animal hospitals.
Growth Catalysts
- Companion animal ownership expansion:Rising pet household penetration in the United States and Germany is forcing referral networks to upgrade imaging capacity. Small animal practices are prioritizing capital expenditure on digital radiography suites.
- FDA Center for Veterinary Medicine oversight:Tightened safety labeling requirements for ionizing radiation devices are filtering out marginal suppliers. Quality thresholds are consolidating procurement toward certified manufacturers with established quality management systems.
- Equine field imaging demand:Portable X-ray units are capturing share among large animal practitioners requiring deployable musculoskeletal diagnostics. Battery-powered systems with wireless image transmission are penetrating rural veterinary service territories.
Market Restraints
- Cesium iodide scintillator supply concentration:Raw material processing for flat panel detectors concentrates among Asian chemical suppliers. Price volatility in rare earth compounds is compressing margins for detector assembly manufacturers.
- CE marking compliance burden:EU Medical Device Regulation technical documentation requirements are extending market entry timelines for non-European manufacturers. Notified body capacity constraints are creating certification backlogs.
- Computed radiography residual installed base:Cassette-based systems in cost-sensitive clinics are delaying full digital conversion. Replacement inertia in solo practices is elongating equipment depreciation schedules.
Strategic Opportunities
- AI-enhanced image interpretation:Software-as-a-medical-device classifications for veterinary radiology algorithms are opening regulatory pathways. Machine learning tools for automated pathology detection are entering clinical workflows.
- Japan's PMDA QMS conformity pathways:Streamlined quality management system recognition for imported imaging equipment is reducing market access friction. Foreign manufacturers with ISO 13485 certification are accelerating approval timelines.
- Telemedicine-integrated imaging:DICOM-compatible systems with cloud storage are enabling remote specialist consultation. Teleradiology platforms are creating new service revenue streams for equipment vendors.
Industry Challenges
- Veterinary radiographer certification scarcity:Formal training programs for animal-specific imaging protocols remain limited in most countries. Clinics are absorbing on-site education costs for technician competency development.
- Legacy analog system integration:Hybrid workflows combining film-based archives with digital PACS infrastructure are creating data management complexity. Migration tools for historical image libraries are underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary X-Ray Market |
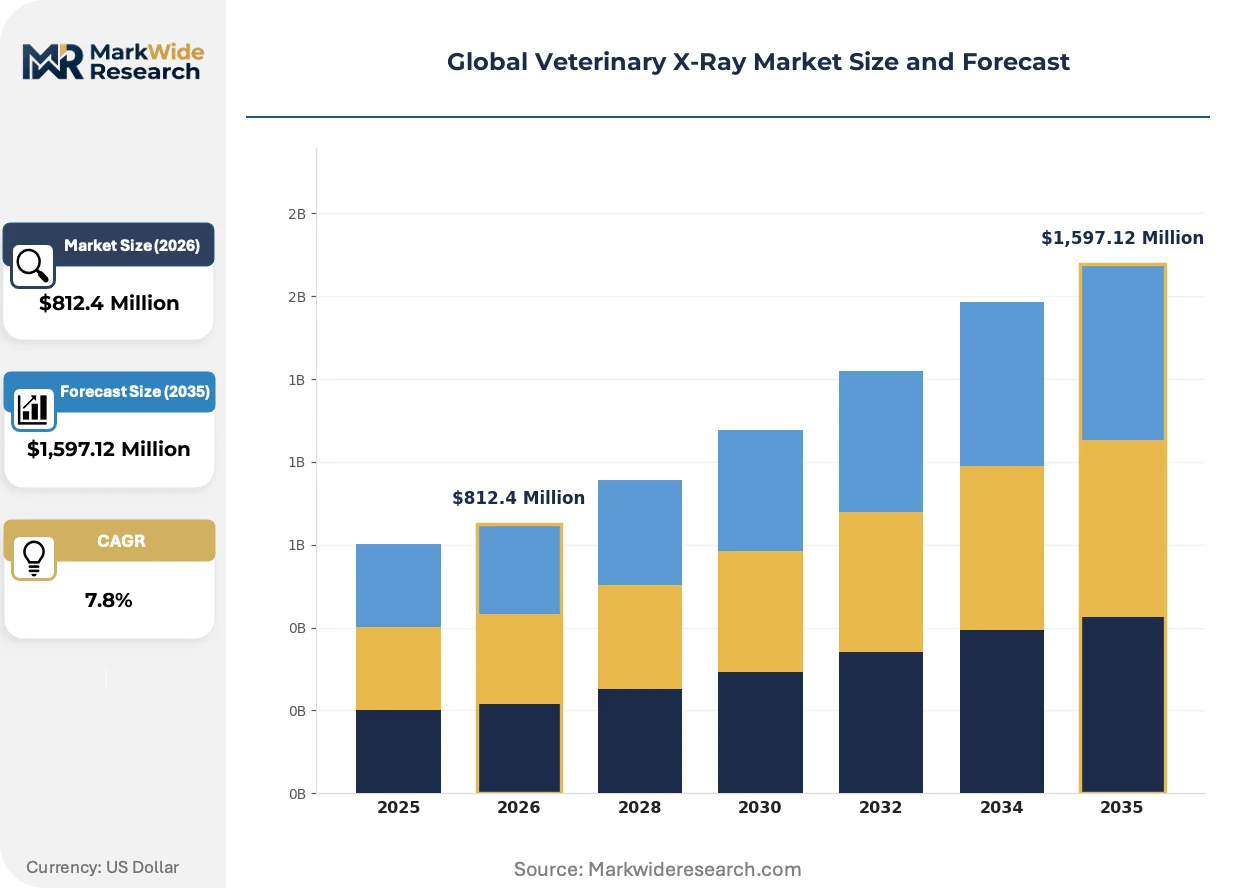
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,597.12 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog X-Ray, Digital X-Ray, Portable X-Ray, Fixed X-Ray Application: Small Animal Imaging, Large Animal Imaging, Equine Diagnosis, Exotic Animal Care End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Diagnostic Labs Technology: Computed Radiography, Flat Panel Detectors, Charge-Coupled Device, CMOS Digital Sensors, Image Intensifiers |
| Companies Covered | IDEXX Laboratories, FUJIFILM Holdings Corporation, Carestream Health, Mindray Bio-Medical Electronics Co., Ltd., Canon Medical Systems Corporation, Agfa-Gevaert Group, Siemens Healthineers, GE Healthcare, Sedecal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary X-Ray Market Shifts & Advancements
Workflow automation and artificial intelligence are restructuring how veterinary clinics capture, interpret, and archive diagnostic images, compressing the gap between image acquisition and clinical decision.
Direct deposition cesium iodide flat panel detectors are decomposing the cost-performance tradeoff that previously favored computed radiography in mid-tier clinics. High-volume animal hospitals in the United States are adopting these systems to eliminate cassette handling delays. The technology is decomposing equipment replacement cycles from seven-year intervals toward four-year refresh schedules.
EU Medical Device Regulation software classification guidance is forcing veterinary AI developers to formalize clinical validation protocols. Algorithm-based pathology detection tools now face conformity assessment requirements previously reserved for hardware devices. European veterinary software vendors are restructuring quality management systems to accommodate notified body oversight.
Subscription-based equipment access models are displacing outright purchase contracts in North American corporate veterinary groups. Lease-to-own structures with bundled maintenance and software updates are capturing share among multi-site clinic operators. This financing shift is most visible in United States consolidation networks where capital efficiency metrics dominate procurement committees.
Global Veterinary X-Ray Market Segmentation
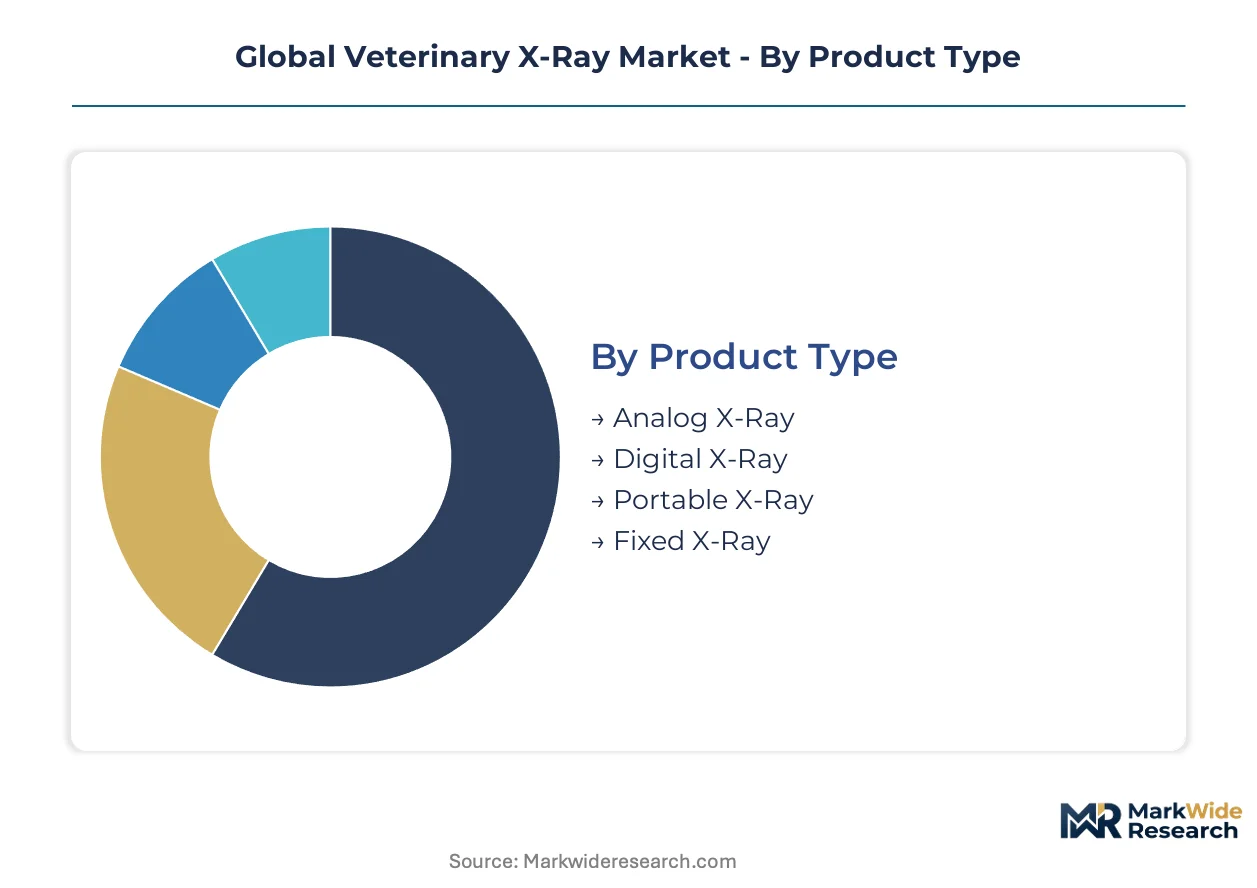
Veterinary X-ray procurement channels diverge sharply by equipment mobility and image acquisition speed. Referral networks prioritize workflow throughput while field practitioners demand battery-powered portability.
Product Type:
Digital systems flow through corporate veterinary group purchasing organizations, while analog and portable units distribute through regional equipment dealers serving independent practices.
- Digital X-Ray:Flat panel detector systems with cesium iodide or gadolinium oxysulfide scintillator layers achieve spatial resolution below 150 micrometers. United States referral hospitals are forcing replacement cycles toward four-year intervals as image acquisition speed becomes decisive for procurement committees.
- Portable X-Ray:Battery-powered units with wireless image transmission enable field-deployable musculoskeletal diagnostics. Equine practitioners in rural territories are capturing these systems to replace clinic-bound referrals.
- Analog X-Ray:Film-based systems persist in cost-sensitive solo practices where capital constraints delay digital conversion.
- Fixed X-Ray:Ceiling-suspended or floor-mounted installations dominate high-volume animal hospitals with dedicated radiography suites.
Digital X-ray dominates installed base in corporate networks. Portable X-ray is where expansion concentrates among large animal specialists.
Application:
Companion animal volume concentrates imaging demand in urban corridors, while equine and exotic applications fragment across specialized referral centers.
- Small Animal Imaging:Dogs and cats generate the procedural volume that justifies digital radiography capital expenditure. Germany's urban pet ownership density is forcing clinic networks to upgrade thoracic and abdominal imaging capacity.
- Equine Diagnosis:Racehorse and sport horse populations require portable musculoskeletal imaging at training facilities. Japan's equine veterinary services are adopting wireless transmission systems for trackside diagnosis.
- Large Animal Imaging:Cattle and production animal diagnostics concentrate in agricultural regions where mobile veterinary units serve dispersed herds.
- Exotic Animal Care:Avian, reptile, and small mammal imaging demands specialized positioning equipment and modified exposure protocols.
Small animal imaging commands the revenue base. Equine diagnosis is climbing the fastest as portable technology penetrates field practice.
End User:
Procurement authority separates corporate-owned hospital chains from independent clinic owner-operators, with research and diagnostic lab channels requiring specialized compliance documentation.
- Veterinary Clinics:Independent and small-group practices prioritize cost-efficient computed radiography or entry-level digital systems. CE marking compliance burdens are filtering procurement toward established quality system manufacturers.
- Animal Hospitals:High-volume referral centers demand DICOM-compatible PACS integration and AI-enhanced workflow tools. IDEXX's integrated diagnostics platform dominates this channel in North America.
- Research Institutes:Preclinical imaging applications require specialized calibration and regulatory documentation for scientific publication standards.
- Diagnostic Labs:Centralized teleradiology services are creating outsourced interpretation demand that shapes equipment specification requirements.
Animal hospitals dominate premium equipment absorption. Veterinary clinics represent the deepest volume pool for mid-tier digital conversion.
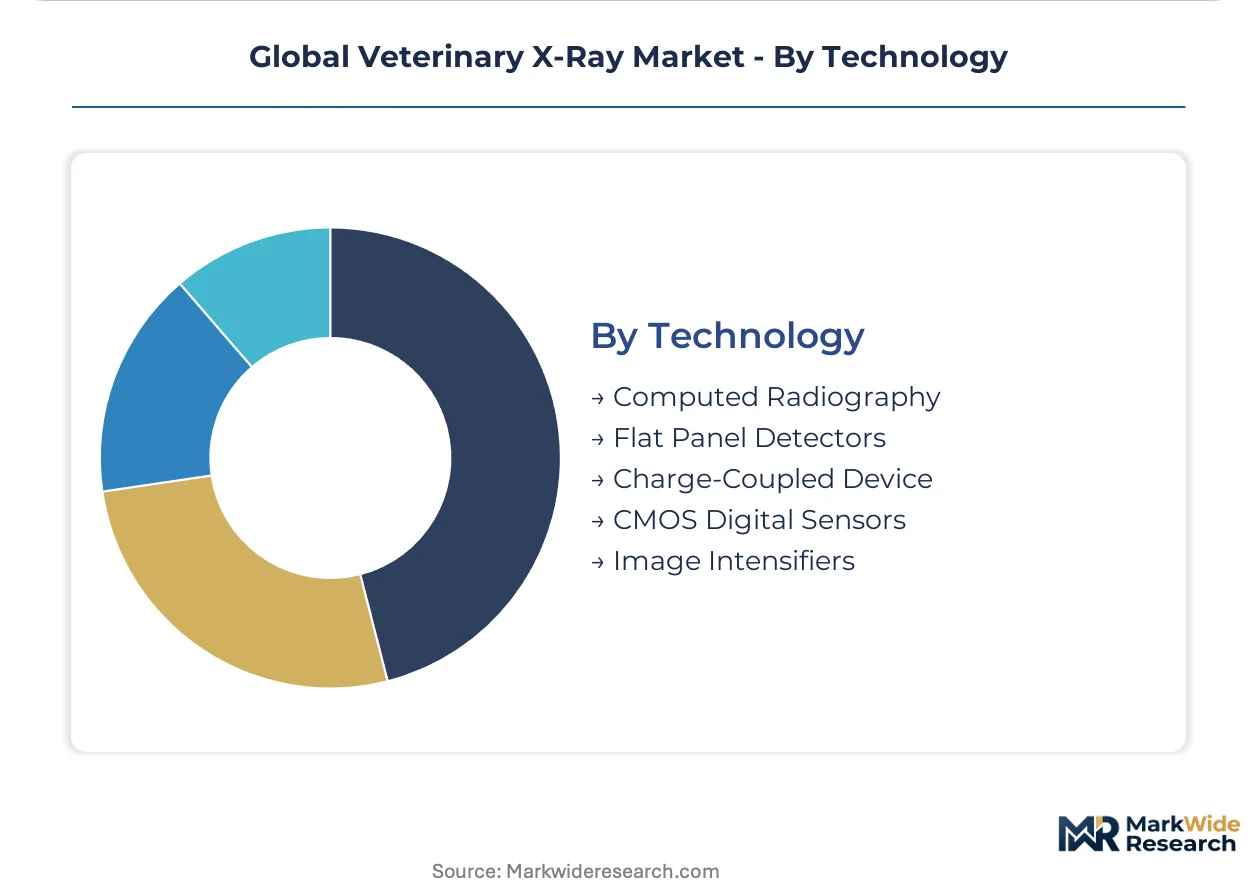
Technology:
Detector architecture determines price positioning and replacement timing, with direct deposition methods displacing legacy cassette-based workflows.
- Flat Panel Detectors:Direct deposition cesium iodide layers on thin-film transistor arrays eliminate cassette handling delays. United States high-volume hospitals are decomposing seven-year replacement cycles toward four-year refresh schedules.
- Computed Radiography:Photostimulable phosphor cassettes persist in cost-sensitive installations where digital flat panel premiums remain prohibitive.
- CMOS Digital Sensors:Complementary metal-oxide-semiconductor technology enables lower-cost digital entry points for small practice conversion.
- Charge-Coupled Device:CCD-based systems retain niche presence in dental and intraoral veterinary applications.
- Image Intensifiers:Legacy fluoroscopy components are phasing out of new equipment specifications as flat panel alternatives mature.
Flat panel detectors are gaining share fastest across all end-user tiers. Computed radiography retains residual installed base in price-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate veterinary groups in the United States concentrate procurement authority for premium digital systems, while independent practices in Germany and Japan drive mid-tier conversion demand.
United States
Referral network consolidation is forcing equipment standardization across multi-site clinic operators. FDA Center for Veterinary Medicine oversight filters procurement toward ISO 13485-certified manufacturers with established quality management systems. Corporate groups in Texas and Florida are deploying subscription-based equipment access models to optimize capital efficiency metrics.
Germany
Urban pet ownership density in Munich and Hamburg is compelling clinic networks to upgrade thoracic and abdominal imaging capacity. CE marking under the EU Medical Device Regulation extends market entry timelines for non-European manufacturers. The Baden-Württemberg veterinary equipment cluster is concentrating detector assembly operations for continental distribution.
Japan
Equine veterinary services at Tokyo and Osaka racecourses are adopting wireless transmission systems for trackside musculoskeletal diagnosis. PMDA QMS conformity pathways streamline approval timelines for foreign manufacturers with ISO 13485 certification. The Chubu region around Nagoya hosts imaging equipment distributors serving domestic animal hospital chains.
United Kingdom
Small animal practice consolidation in Greater London is accelerating digital radiography replacement cycles. The country's national veterinary regulator enforces device safety labeling parallel to EU MDR frameworks during post-Brexit transition periods. Manchester and Birmingham veterinary teaching hospitals are piloting AI-enhanced image interpretation workflows.
Australia
Equine and large animal practitioners in Queensland and New South Wales are capturing portable X-ray units for field-deployable diagnostics. The Therapeutic Goods Administration aligns veterinary device oversight with human medical equipment standards. Sydney's corporate veterinary groups are integrating teleradiology platforms with DICOM-compatible cloud storage systems.
Global Veterinary X-Ray Market Competitive Landscape
Player mix skews toward diversified medical imaging conglomerates with veterinary divisions alongside specialized diagnostic equipment manufacturers. Tiered competitive structure separates integrated diagnostics platforms from component suppliers and regional system integrators. Dominant archetypes include full-stack platform operators, detector technology specialists, and portable equipment fabricators. Competitive moves concentrate on strategic partnerships for software integration and geographic licensing agreements for regulatory market access.
Within the integrated platform tier, IDEXX Laboratories and FUJIFILM Holdings Corporation exemplify divergent approaches to veterinary channel dominance. IDEXX anchors North American referral hospital networks through diagnostics ecosystem lock-in, while FUJIFILM leverages proprietary flat panel detector R&D to sustain premium positioning. Carestream Health occupies a position spanning analog legacy support and digital transition pathways, reflecting the market's bifurcated installed base reality.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Mindray Bio-Medical Electronics Co., Ltd. |
| Canon Medical Systems Corporation |
| Agfa-Gevaert Group |
| Siemens Healthineers |
| GE Healthcare |
| Sedecal |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates veterinary X-ray market participation while simultaneously stratifying price tiers across qualified and marginal supplier tiers. CE marking and FDA Center for Veterinary Medicine compliance costs compress margins for entrants but protect incumbent pricing power in premium channels.
Pricing Analysis
Cost-plus contracts with rare earth compound indexation dominate detector assembly procurement. Three-tier pricing structure across premium flat panel systems, standard computed radiography suites, and economy analog configurations reflects certification grade and after-sales bundling differentiation. Pricing pressure stems from cesium iodide scintillator supply volatility among Asian chemical processors. Independent veterinary clinics exhibit acute price sensitivity, while corporate hospital chains absorb premium digital premiums for workflow throughput gains.
Supply Chain Analysis
Japan and South Korea anchor thin-film transistor array fabrication for flat panel detector cores. Cesium iodide crystal growth, gadolinium oxysulfide phosphor processing, and CMOS sensor wafer production feed assembly operations. Single-source vulnerability concentrates in photostimulable phosphor cassette manufacturing. Distribution runs through corporate veterinary group purchasing organizations in North America and regional equipment dealer networks serving independent practices in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enhanced veterinary radiology software is disrupting diagnostic workflows as EU Medical Device Regulation software classifications force clinical validation investments. This regulatory inflection compresses time-to-market for algorithm developers while elevating barriers for undercapitalized entrants.
For Market Incumbents: Shield referral hospital relationships by accelerating DICOM-compatible cloud platform integration before teleradiology vendors capture interpretation revenue streams. Deepen backward integration into cesium iodide crystal processing to mitigate raw material price volatility from Asian suppliers. Prioritize ISO 13485 certification maintenance as CE marking technical documentation requirements extend competitor entry timelines.
For New Entrants and Emerging Players: Lead with portable X-ray units targeting equine field practitioners in rural territories where battery-powered wireless systems remain underpenetrated. Exploit Japan's PMDA QMS conformity pathway for streamlined approval of ISO 13485-certified manufacturers. Position through subscription-based equipment access models to bypass capital expenditure constraints among multi-site clinic operators.
For Investors and Strategic Acquirers: EU Medical Device Regulation software classification guidance reshapes the acquisition landscape by forcing quality management system investments among veterinary AI developers. Five-to-ten year viability favors targets with established notified body relationships and clinical validation datasets. Monitor FDA Center for Veterinary Medicine software-as-a-medical-device enforcement patterns as inflection indicators for algorithm-based pathology detection valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter procurement toward established quality system manufacturers. |
| Hospital System Partnership | Corporate veterinary group purchasing organizations concentrate authority for premium digital system procurement. |
| Software Companion Development | AI-enhanced image interpretation tools face conformity assessment requirements previously reserved for hardware devices. |
| Backward Integration | Captive cesium iodide scintillator processing mitigates margin compression from Asian chemical supplier concentration. |
| Geographic Expansion | Japan's PMDA QMS conformity pathways accelerate approval timelines for foreign manufacturers with ISO 13485 certification. |
Research Methodology
Initial hypotheses were tested against primary input from veterinary radiologists, biomedical equipment procurement managers, GPO contracts administrators, and detector assembly engineers and refined through secondary validation. Veterinary hospital procurement databases, FDA Center for Veterinary Medicine device listings, EU MDR notified body certification records, and customs trade data for imaging equipment imports provided triangulation anchors. Bottom-up equipment shipment analysis and top-down referral network capacity modeling converged on segment-level estimates.
Variance decomposition across product type, application, technology architecture, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from replacement cycle compression trends and companion animal ownership expansion patterns across the projection horizon. Detector technology migration curves and teleradiology platform penetration rates supplied veterinary-specific forecast inputs.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight, EU Medical Device Regulation enforcement, and Japan PMDA QMS recognition pathways; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in AI software classification guidance and rare earth compound supply conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
China Mammography Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market