
 Preclinical Imaging (in-VIVO) Market | 2026-2036
Preclinical Imaging (in-VIVO) Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical Imaging (in-VIVO) Market Outlook
A shortage of veterinary radiologists and imaging physicists trained in multimodal preclinical protocols is collapsing installation timelines at major research centers. Bruker Corporation leverages its cryogen-free MRI technology to sustain leadership in high-field small-animal systems. Revvity, Inc. anchors its position through integrated optical and PET workflows designed for pharmaceutical screening pipelines.
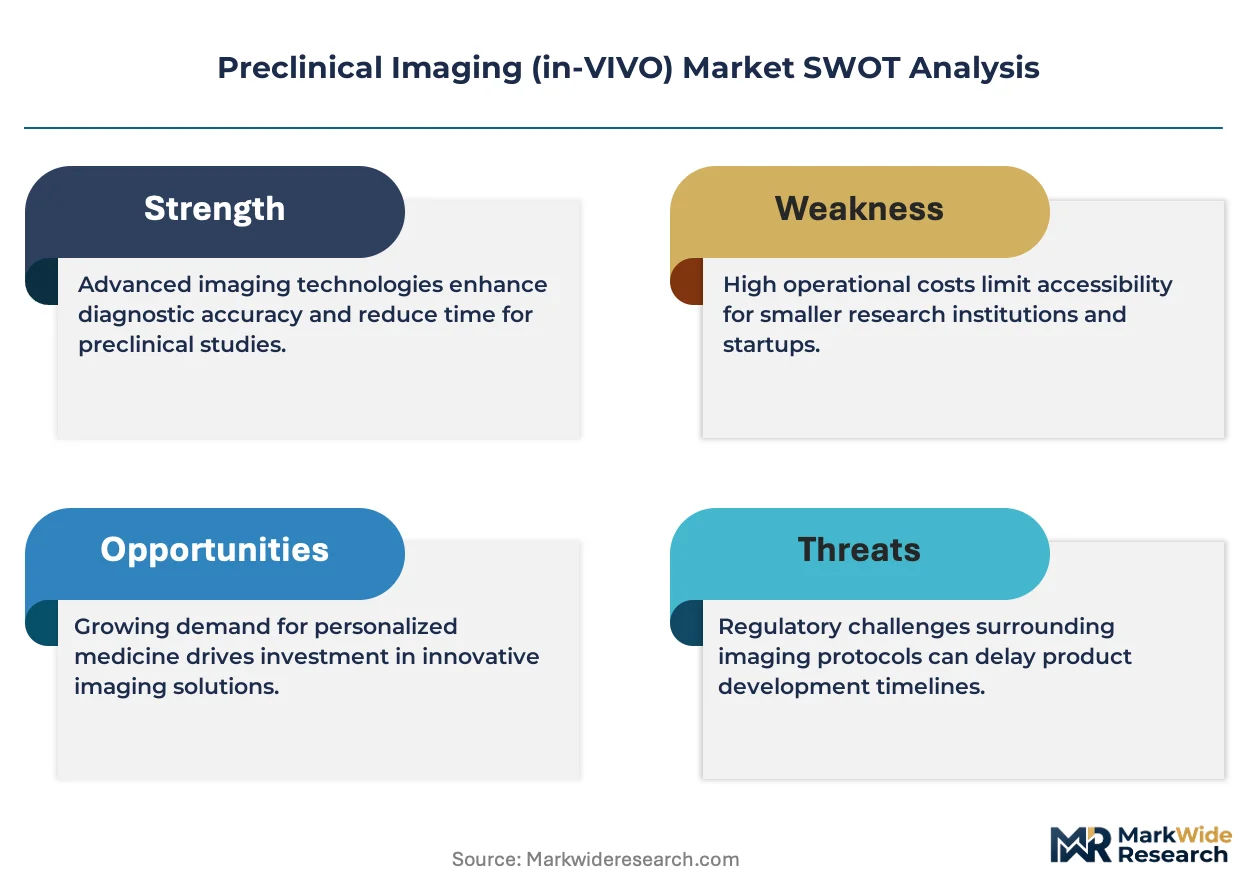
Preclinical imaging (in-vivo) encompasses non-invasive visualization systems—typically operating at spatial resolutions below 100 micrometers for micro-CT and employing radiotracer doses in the microcurie range for PET—used to monitor disease progression, therapeutic response, and biological processes in living animal models prior to human trials. Optical imaging bioluminescence systems dominate installed base volumes due to lower capital thresholds, while hybrid PET-MRI configurations command the deepest margin pools among technology categories. Pharmaceutical companies represent the most concentrated end-user segment, though contract research organizations are expanding capacity fastest as sponsors outsource longitudinal imaging studies.
FDA 21 CFR Part 11 compliance requirements shape equipment validation protocols and data integrity standards for studies supporting IND submissions. The EU MDR and EMA guidelines on non-clinical imaging biomarkers further condition market access for vendors seeking European pharmaceutical customers. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards apply to hardware components in direct animal contact. Stakeholders must weigh capital deployment against the accelerating shift toward AI-assisted image reconstruction and cloud-based multi-site data sharing architectures.
Market Dynamics
Multimodal imaging platform consolidation is compressing vendor margins while elevating technical barriers to entry, as pharmaceutical sponsors demand integrated PET-MRI-optical workflows that single-modality suppliers cannot assemble.
Growth Catalysts
- Oncology Imaging Consortia:NIH-funded networks in the United States are standardizing longitudinal imaging protocols, creating pull-through demand for compatible hardware and software ecosystems across academic medical centers.
- EMA Biomarker Guidelines:The European Medicines Agency's framework for qualifying imaging biomarkers in drug development is validating preclinical data for regulatory submissions, expanding addressable use cases for contract research organizations.
- Cryogen-Free MRI:Elimination of liquid helium dependency is reducing operational overhead and site preparation costs, accelerating replacement cycles at facilities constrained by infrastructure limitations.
Market Restraints
- Helium Supply Volatility:Conventional high-field MRI systems remain exposed to rare gas price shocks and export restrictions, particularly affecting installations in regions without cryogen-free alternatives.
- Concentrated Component Sourcing:Scintillation crystal production for PET detectors clusters in East Asian suppliers, creating single-source vulnerability for hybrid system manufacturers.
- IEC 60601 Electrical Safety:Certification timelines for modified hardware configurations extend validation cycles, delaying revenue recognition for customized installations.
Strategic Opportunities
- AI-Assisted Reconstruction:Machine learning algorithms reducing scan times and radiation doses are creating differentiation for vendors integrating NVIDIA or AMD computational architectures into acquisition workstations.
- Cloud Multi-Site Architectures:Federated data sharing platforms enable pharmaceutical sponsors to pool longitudinal studies across CRO networks, opening subscription revenue streams beyond equipment sales.
- India Contract Research Expansion:CDSCO-aligned preclinical facilities in Hyderabad and Bangalore are investing in optical imaging capacity to capture outsourced toxicology studies from Western sponsors.
Industry Challenges
- Veterinary Radiologist Scarcity:Training programs for imaging physicists specializing in small-animal protocols have not expanded to match installation growth, extending commissioning timelines at major research centers.
- FDA 21 CFR Part 11 Validation:Electronic records compliance for IND-supporting studies requires extensive documentation of software version control and audit trails, consuming technical support resources.
- Legacy System Integration:Pharmaceutical screening pipelines running on decade-old optical platforms face workflow friction when incorporating newer multimodal data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical Imaging (in-VIVO) Market |
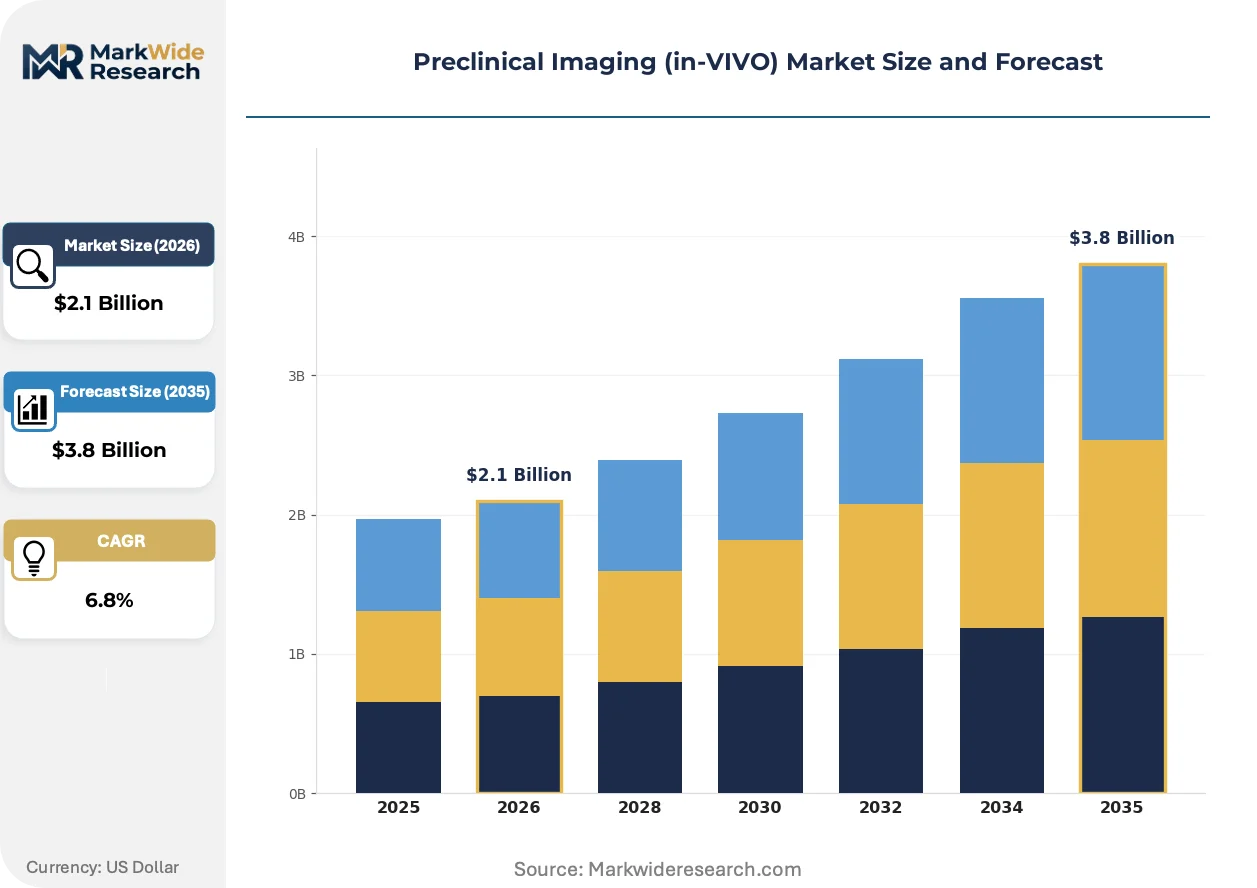
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Resonance Imaging, Micro-CT, PET, Optical Imaging Application: Drug Discovery, Cancer Research, Cardiovascular Studies, Neurological Disorders Technology: Bioluminescence, Fluorescence, Radiotracers, Hybrid Systems End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | Bruker Corporation, Revvity, Inc., FUJIFILM VisualSonics, Mediso Ltd., PerkinElmer, Inc., MILabs B.V., MR Solutions Ltd, Aspect Imaging, TriFoil Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical Imaging (in-VIVO) Market Strategic Shifts
Computational imaging and regulatory data standards are converging to redefine how preclinical evidence is generated, validated, and transmitted to drug sponsors.
Photonics-based detection arrays are supplanting conventional charge-coupled device sensors in bioluminescence imaging systems, delivering superior quantum efficiency for low-light molecular probe detection. Academic core facilities and pharmaceutical screening divisions are retrofitting existing optical platforms with these solid-state alternatives to extend instrument service life. The shift is compressing replacement cycles for legacy camera systems while elevating performance baselines for new installations.
The FDA's 21 CFR Part 11 framework is hardening data integrity requirements for electronic records supporting IND submissions, mandating audit trails and access controls that reshape software development priorities. Equipment vendors are embedding compliance-ready validation documentation into product releases to accelerate pharmaceutical customer procurement. United States-based CROs report extended vendor qualification timelines as a direct consequence of these documentation demands.
Pharmaceutical sponsors are unbundling longitudinal imaging studies from full-service toxicology contracts, awarding discrete imaging milestones to specialized CROs with dedicated optical or PET capacity. This disaggregation is fragmenting procurement authority across sponsor organizations, with imaging-specific RFPs now circulating separately from broader IND-enabling study packages. The pattern is most pronounced among mid-cap biotechnology firms in the Boston and San Diego clusters seeking cost transparency.
Preclinical Imaging (in-VIVO) Market Segmentation
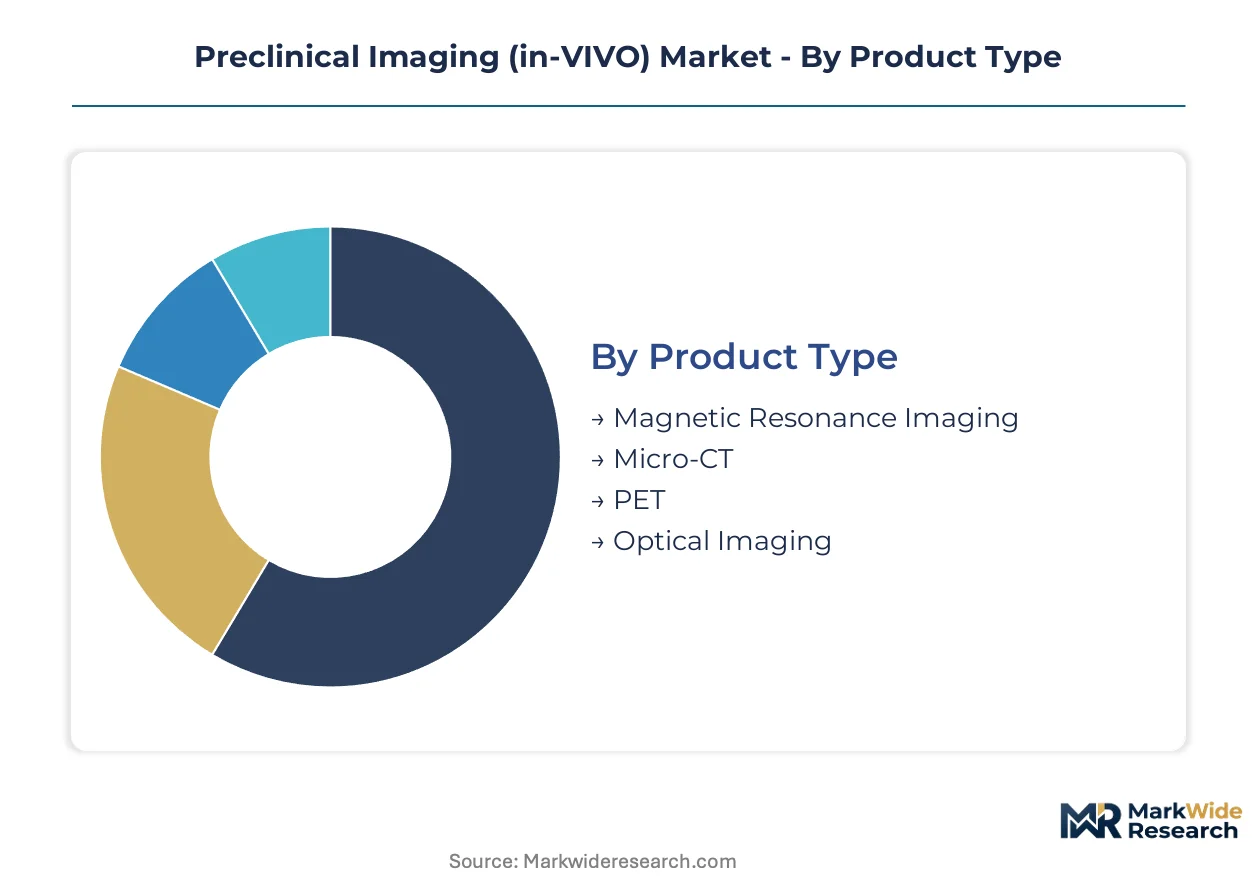
Preclinical imaging segmentation reveals divergent margin structures across hardware modalities and customer archetypes. Pharmaceutical procurement patterns and academic funding flows create distinct demand profiles that reshape vendor prioritization.
Product Type:
Hybrid configurations command the deepest margin pools within hardware categories, while single-modality systems compete on capital efficiency and site accessibility.
- Magnetic Resonance Imaging:Cryogen-free high-field systems eliminate liquid helium dependency, reducing operational overhead at facilities constrained by infrastructure limitations. Academic medical centers in the United States are standardizing longitudinal protocols around compatible MRI ecosystems, pulling through replacement demand.
- Optical Imaging:Bioluminescence platforms dominate installed base volumes due to lower capital thresholds, though photonics-based detection arrays are supplanting conventional charge-coupled device sensors. Pharmaceutical screening divisions retrofit existing platforms to extend instrument service life.
- Micro-CT:Spatial resolutions below 100 micrometers enable skeletal and soft-tissue visualization without radiotracer administration.
- PET:Radiotracer doses in the microcurie range require scintillation crystal detectors vulnerable to East Asian supply concentration.
Optical imaging holds installed capacity. Hybrid systems are rotating up the share rankings.
Application:
Oncology workflows generate the most concentrated procurement authority, while neurological applications attract disproportionate NIH funding relative to commercial pharmaceutical spending.
- Cancer Research:Longitudinal tumor monitoring protocols demand multimodal PET-MRI-optical workflows that single-modality suppliers cannot assemble. NIH-funded networks in the United States are standardizing imaging biomarkers for regulatory submission.
- Drug Discovery:Pharmaceutical sponsors unbundle imaging milestones from full-service toxicology contracts, awarding discrete studies to specialized CROs. Mid-cap biotechnology firms in Boston and San Diego clusters drive cost transparency demands.
- Neurological Disorders:Brain imaging protocols require specialized small-animal coil configurations and anesthesia monitoring systems.
- Cardiovascular Studies:Cardiac gating and high-temporal-resolution acquisition modes address murine heart rate constraints.
Cancer research anchors current procurement volumes. Drug discovery is climbing the fastest as sponsors disaggregate imaging from toxicology packages.
Technology:
Detection modality determines sensitivity thresholds and reagent cost structures, with bioluminescence offering lowest per-scan variable costs and hybrid systems demanding highest technical integration.
- Hybrid Systems:PET-MRI configurations integrate anatomical and functional data streams, commanding premium pricing and extended validation cycles. FDA 21 CFR Part 11 compliance requirements reshape software development priorities for electronic records supporting IND submissions.
- Bioluminescence:ATP-dependent luciferase reactions enable low-light molecular probe detection without external excitation. Solid-state photonics arrays deliver superior quantum efficiency for academic core facilities.
- Fluorescence:External excitation sources enable multiplexed reporter detection with higher signal-to-noise ratios than bioluminescence.
- Radiotracers:Cyclotron-dependent isotope production constrains site-level availability and creates regulatory compliance overhead.
Bioluminescence maintains the broadest installed base. Hybrid systems are gaining share fastest as pharmaceutical sponsors consolidate multimodal workflows.
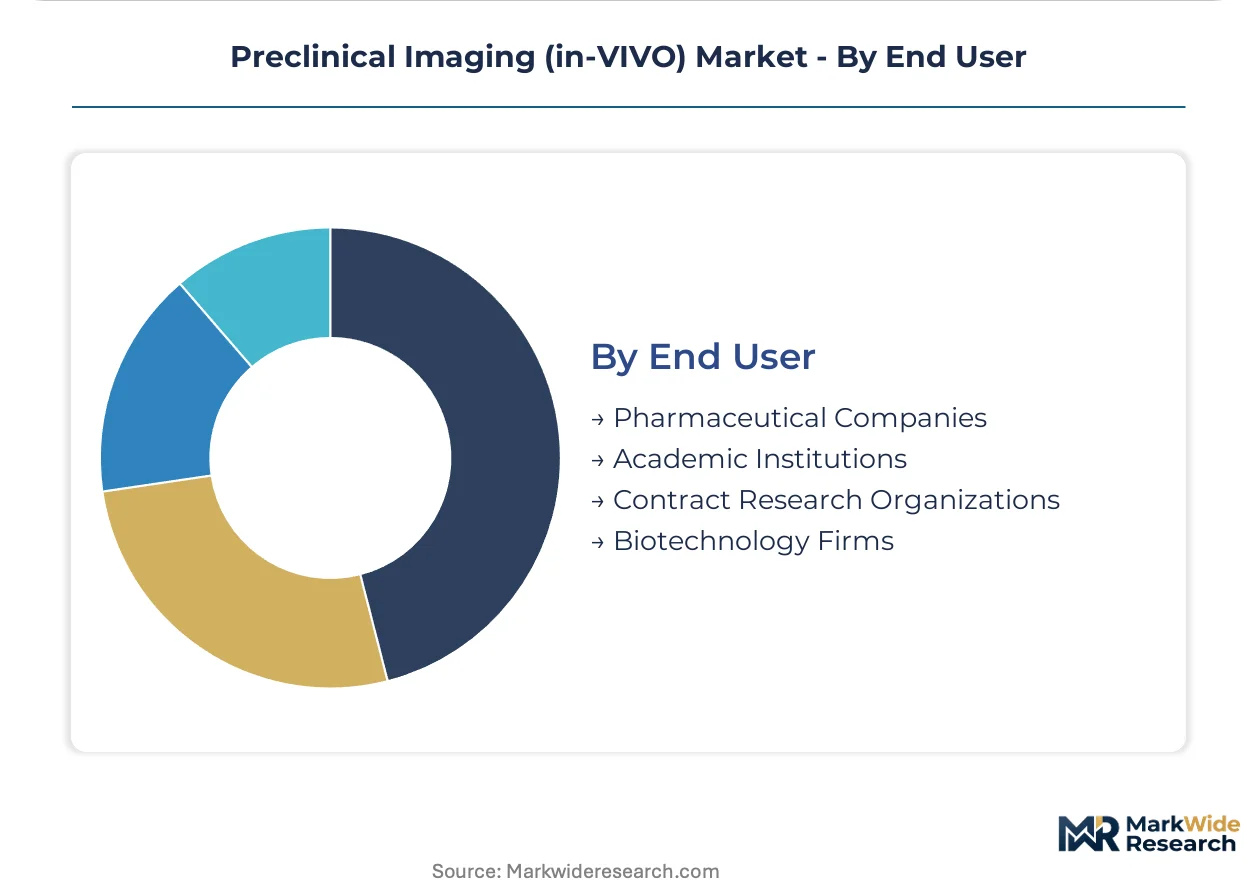
End User:
Pharmaceutical companies concentrate capital deployment authority, while contract research organizations expand capacity fastest as sponsors outsource longitudinal studies.
- Pharmaceutical Companies:Screening pipelines running on decade-old optical platforms face workflow friction when incorporating newer multimodal data formats. Cloud multi-site architectures enable federated data sharing across internal and external study networks.
- Contract Research Organizations:Specialized imaging CROs capture discrete milestones unbundled from full-service toxicology contracts. CDSCO-aligned facilities in Hyderabad and Bangalore invest in optical capacity to capture Western sponsor outsourcing.
- Academic Institutions:Core facilities balance service revenue against grant-funded translational research priorities.
- Biotechnology Firms:Capital constraints favor optical imaging platforms with lower site preparation requirements.
Pharmaceutical companies retain the largest equipment budgets. Contract research organizations are rotating up the share rankings through imaging-specific service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preclinical imaging consumption patterns diverge sharply between geographies: United States facilities prioritize multimodal PET-MRI workflows for regulatory submission, while emerging research hubs in Asia emphasize cost-efficient optical platforms for high-throughput screening.
United States
NIH-funded oncology and neurology imaging consortia drive concentrated procurement of high-field small-animal MRI systems. The FDA's 21 CFR Part 11 electronic records requirements tighten validation standards for IND-supporting studies. Boston and San Diego biotechnology clusters unbundle imaging milestones from full-service toxicology contracts, awarding discrete studies to specialized CROs.
Germany
Academic medical centers expand cryogen-free MRI installations to eliminate liquid helium dependency. The EU MDR conditions market access for vendors seeking pharmaceutical customers with stringent device validation protocols. Heidelberg and Munich research institutes standardize longitudinal imaging biomarkers for EMA regulatory submissions.
China
Domestic pharmaceutical R&D expansion fuels demand for integrated optical and micro-CT platforms at lower capital thresholds. NMPA guidelines on preclinical imaging data quality reshape equipment procurement specifications. Shanghai and Suzhou biotech parks invest in multimodal imaging capacity to support innovative drug development pipelines.
India
CDSCO-aligned contract research facilities in Hyderabad and Bangalore capture outsourced toxicology studies from Western sponsors through optical imaging capacity expansion. Central government PLI scheme incentives accelerate domestic manufacturing of imaging components. The Telangana life sciences corridor concentrates preclinical service provider investments.
United Kingdom
Academic core facilities balance grant-funded translational research against service revenue from pharmaceutical partnerships. MHRA alignment with EMA biomarker qualification frameworks validates preclinical data for regulatory submissions. The Cambridge-London corridor hosts concentrated imaging physics expertise for small-animal protocol development.
Preclinical Imaging (in-VIVO) Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multimodal platform consolidation compressing margins while elevating technical barriers. The upper tier commands premium positioning through hybrid PET-MRI-optical workflows that single-modality suppliers cannot assemble. Specialist players compete on capital efficiency and site accessibility for academic customers. Dominant competitive moves include cryogen-free technology licensing and cloud-based multi-site data sharing partnerships.
Within the integrated systems tier, Bruker Corporation and Revvity, Inc. exemplify contrasting strategic positions. Bruker leverages German engineering heritage in high-field magnetic resonance instrumentation. Revvity occupies a position spanning integrated optical and PET workflows designed for pharmaceutical screening pipelines. FUJIFILM VisualSonics represents the specialized imaging modality approach, anchoring a tier focused on premium ultrasound-based preclinical visualization.
| Leading Market Players |
|---|
| Bruker Corporation |
| Revvity, Inc. |
| FUJIFILM VisualSonics |
| Mediso Ltd. |
| PerkinElmer, Inc. |
| MILabs B.V. |
| MR Solutions Ltd |
| Aspect Imaging |
| TriFoil Imaging |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 11 validation requirements gate both supplier qualification timelines and price differentiation between compliant and non-compliant equipment tiers, compressing margins for vendors unable to embed audit-ready documentation into standard product releases.
Pricing Analysis
Contract structures favor long-term service agreements bundled with hardware procurement over spot purchases, particularly for hybrid PET-MRI systems requiring extended validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated configurations with embedded compliance documentation from basic optical platforms. Cost compression in mid-tier bioluminescence systems intensifies as photonics-based detection arrays displace legacy charge-coupled device sensors. Academic core facilities exhibit highest price sensitivity due to grant-funded capital constraints, while pharmaceutical sponsors prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Inbound logistics costs for scintillation crystals from East Asian suppliers fluctuate with container availability on transpacific trade lanes, elevating landed costs for PET detector manufacturers. Scintillation crystal production concentrates in Japan and China, while cryogen-free magnet manufacturing anchors in Germany and the United States. Component sourcing draws from helium recovery systems, solid-state photonics arrays, and specialized small-animal coil configurations. Single-source vulnerability for lutetium-based scintillation materials creates exposure to export licensing delays. Distribution runs through authorized service networks rather than direct OEM relationships, extending commissioning timelines at research centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: FDA and EMA validation requirements create switching costs that lock pharmaceutical sponsors into established vendor ecosystems.
For Market Incumbents: Shield installed base revenue by embedding AI-assisted reconstruction capabilities into existing multimodal platforms, neutralizing threat from computational imaging startups. Deepen backward integration into cryogen-free magnet technology to capture margin pools eroding from helium price volatility. Prioritize cloud multi-site architecture partnerships with contract research organizations to extend subscription revenue beyond equipment replacement cycles. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for software-as-a-medical-device modules offer lowest regulatory barrier to entry. White-space concentrates in India CDSCO-aligned facilities seeking cost-efficient optical imaging capacity for Western sponsor outsourcing. Target biotechnology firms in Boston and San Diego clusters with modular bioluminescence platforms requiring minimal site preparation. Go-to-market leverage rests on per-scan pricing models displacing capital-intensive equipment procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across optical imaging sub-segments as solid-state photonics arrays commoditize detection hardware. Long-term viability favors vendors with recurring software revenue streams and regulatory validation moats. Acquisition targets should display hybrid system integration capabilities and established FDA master file documentation. Signal to monitor: pharmaceutical sponsor consolidation of imaging procurement authority under centralized vendor management functions.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free MRI Technology Licensing | Eliminates helium dependency for Bruker Corporation and accelerates replacement cycles at infrastructure-constrained academic centers. |
| Cloud Multi-Site Data Architecture | Enables Revvity, Inc. to capture subscription revenue from pharmaceutical sponsors pooling longitudinal studies across CRO networks. |
| AI-Assisted Image Reconstruction Integration | Differentiates vendors embedding NVIDIA computational architectures into acquisition workstations for reduced scan times. |
| CDSCO-Aligned Facility Partnership | Positions optical imaging suppliers to capture outsourced toxicology studies from Western sponsors in Hyderabad and Bangalore. |
| EMA Biomarker Qualification Documentation | Validates preclinical data for regulatory submissions at Heidelberg and Munich research institutes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA qualification guidance documents, and NIH funding disbursement records. Primary interviews engaged preclinical imaging physicists, pharmaceutical regulatory affairs leads, contract research organization procurement managers, and academic core facility directors. Secondary validation drew from IEC 60601 certification databases, ISO 10993 biocompatibility testing registries, and equipment installation records at major research centers. Bottom-up unit economics triangulate against top-down NIH and pharmaceutical R&D expenditure flows.
Segmentation dimensions modeled span product type, application, technology, and end user across the analysis window. Analytical framework incorporates modality-specific replacement cycles, grant funding trajectories, and regulatory validation timeline assumptions. CAGRs derive from installed base growth projections and average selling price trends by configuration tier. Forecast inputs include helium supply elasticity coefficients and pharmaceutical outsourcing propensity indices.
Underlying assumptions cover NIH funding continuity, helium market stabilization, and EMA biomarker framework permanence, with deviation risk concentrated in export restriction escalations for scintillation crystal materials. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mammography Workstation Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market