
 Healthcare Regulatory Affairs Outsourcing Market | 2026-2036
Healthcare Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Regulatory Affairs Outsourcing Market Intelligence
Premium-tier regulatory consulting is collapsing into broader outsourcing bundles as sponsors seek integrated submission-to-approval pathways. IQVIA leverages its real-world evidence infrastructure to anchor multi-market authorization strategies. Charles River Laboratories sustains competitive positioning through captive toxicology data that streamlines regulatory packages. WuXi AppTec dominates Asia-Pacific filing volumes with localized CMC expertise and dedicated regional teams.
Healthcare regulatory affairs outsourcing encompasses the delegation of compliance, submission, and liaison activities to specialized third-party providers managing documentation integrity, dossier compilation, and health authority negotiations on behalf of product sponsors. The practice centers on ensuring market access through scientifically rigorous filings that satisfy chemistry-manufacturing-controls standards and post-market surveillance obligations across jurisdictions. Submission management occupies the largest revenue share among service types due to the labor intensity of new drug applications and variation filings. Cloud-based platforms represent the fastest-expanding delivery model as distributed teams require real-time document collaboration and audit trail transparency. Pharmaceutical companies remain the dominant client type, though biotechnology firms are deepening their outsourcing penetration as pipeline complexity outpaces internal regulatory capacity.
FDA, EMA, and the EU MDR framework collectively shape demand by escalating documentation requirements and shortening response windows for sponsor queries. The EU AI Act introduces additional algorithmic transparency mandates that medical device manufacturers must address through specialized regulatory partners. Stakeholders must evaluate whether their outsourcing partners possess simultaneous FDA and EMA inspection readiness as dual-track filings become standard for novel therapies.
Market Dynamics
Specialty pharmaceutical manufacturers are fragmenting their regulatory workflows across multiple external partners as submission complexity outpaces internal capacity expansion. The EU MDR rollout and FDA's digital health guidance are compressing sponsor response windows while expanding documentation requirements.
Growth Catalysts
- EMA parallel scientific advice:Sponsors leverage simultaneous FDA-EMA consultation pathways to compress development timelines for novel therapies. Dual-track filings reduce sequential regulatory risk.
- Biotechnology pipeline expansion:Cell and gene therapy developers lack captive regulatory infrastructure, mandating external partnership for chemistry-manufacturing-controls dossier compilation.
- Cloud-based submission platforms:Distributed regulatory teams require real-time document collaboration and immutable audit trails, accelerating platform adoption across mid-cap sponsors.
Market Restraints
- Inspection readiness divergence:Outsourcing partners rarely maintain simultaneous FDA and EMA inspection standards, creating compliance gaps for sponsors pursuing dual-market authorization.
- Specialized talent scarcity:Regulatory strategists with cross-jurisdictional biologics experience command premium compensation, inflating service provider cost structures.
- Data sovereignty requirements:China's NMPA and Saudi Arabia's SFDA mandate local data residency for clinical trial submissions, fragmenting global outsourcing arrangements.
Strategic Opportunities
- EU AI Act compliance services:Medical device manufacturers require algorithmic transparency documentation for machine learning-enabled diagnostics, opening specialized advisory revenue streams.
- Post-market surveillance outsourcing:MDR-mandated vigilance reporting and periodic safety update submissions exceed sponsor internal bandwidth across Germany, France, and Italy.
- Real-world evidence integration:Convergence of electronic health record interoperability standards and regulatory science frameworks enables novel approval pathway support services.
Industry Challenges
- Legacy system integration:Sponsors maintain decades-old document management infrastructure that resists API-based connectivity with modern regulatory platforms.
- Quality agreement negotiation:Defining audit rights, data ownership, and liability allocation between sponsor and outsourcing partner extends contract finalization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Regulatory Affairs Outsourcing Market |
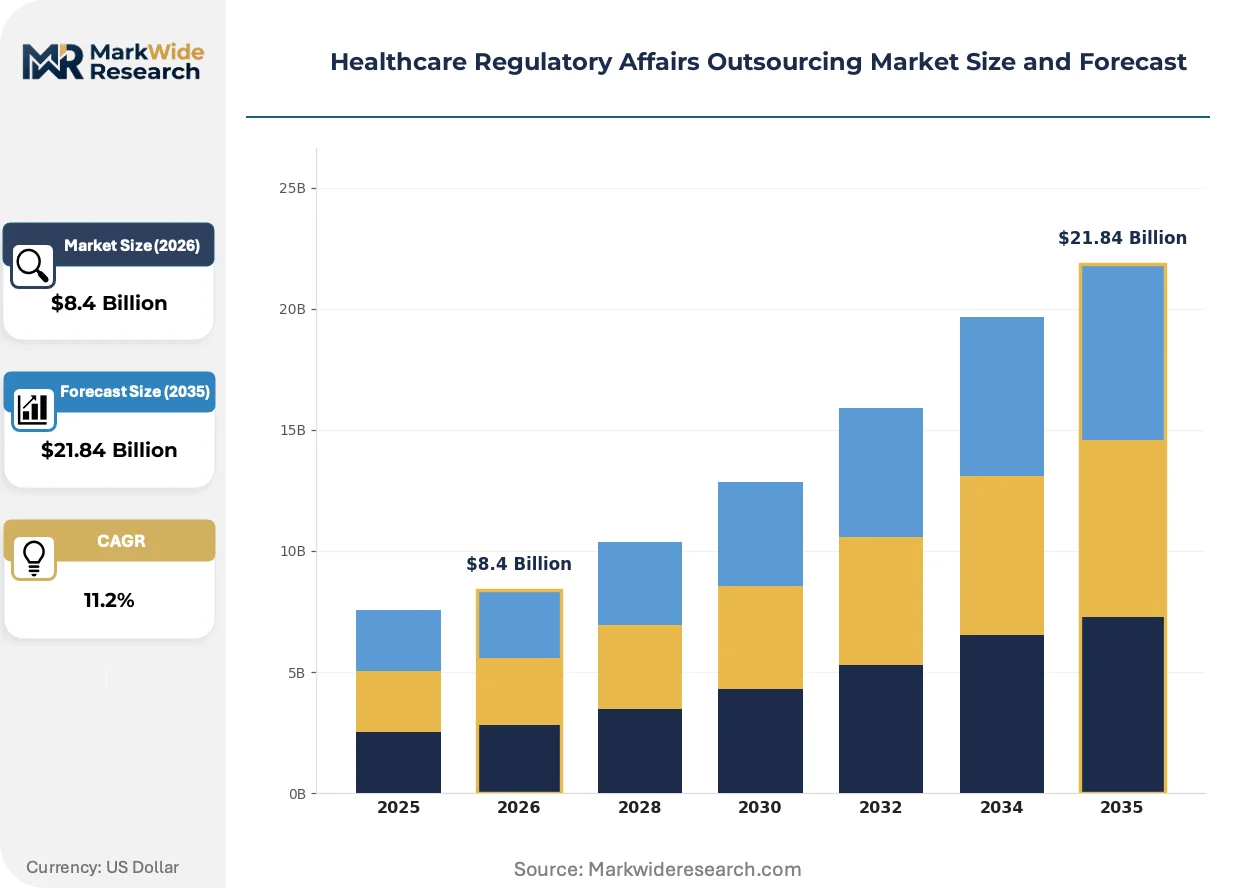
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Submission Management, Compliance Monitoring, Labeling Support, Audit Preparation, Risk Assessment Client Type: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Generic Drug Makers, Contract Research Organizations Therapy Area: Cardiology, Neurology, Oncology, Endocrinology, Pulmonology Delivery Model: Onshore, Offshore, Hybrid, Cloud-Based Platforms, Dedicated Teams |
| Companies Covered | Charles River Laboratories, WuXi AppTec, IQVIA, Medpace, Syneos Health, Parexel International Corporation, Labcorp, Covance, ICON plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Regulatory Affairs Outsourcing Market Strategic Shifts & Innovations
Regulatory affairs outsourcing is pivoting from transactional document preparation toward integrated submission-to-approval partnerships. Technology convergence and policy acceleration are compressing traditional service boundaries.
Artificial intelligence is decomposing manual dossier compilation workflows. Natural language processing tools extract and structure clinical data from unstructured source documents, reducing labor intensity in new drug application preparation. Large pharmaceutical sponsors deploy these capabilities for variation filing automation, while biotechnology firms rely on outsourcing partners for AI-enabled gap analysis prior to health authority submission.
The EU AI Act introduces mandatory algorithmic transparency documentation for software-as-a-medical-device products. Manufacturers must submit technical documentation describing training data provenance, model architecture, and performance validation protocols. Germany's notified body infrastructure is expanding assessment capacity to address this surge in conformity evaluation demand.
Sponsor procurement of regulatory services is fragmenting from single-source arrangements toward modular best-of-breed contracting. Biotechnology firms unbundle chemistry-manufacturing-controls writing, health authority meeting preparation, and post-approval maintenance across specialized providers. This pattern concentrates in Boston and San Francisco, where dense sponsor populations support niche regulatory consultancy ecosystems.
Healthcare Regulatory Affairs Outsourcing Market Segmentation
Regulatory outsourcing procurement fragments across multiple decision axes. Sponsors select service configurations based on submission complexity, internal capability gaps, and jurisdiction-specific compliance burdens.
Service Type:
Margin pools concentrate in labor-intensive submission preparation and health authority negotiation activities.
- Submission Management:Dossier compilation for new drug applications and variation filings demands specialized writers with cross-jurisdictional experience. Oncology and cell therapy developers in Germany and Massachusetts drive concentration here as pipeline complexity outpaces internal regulatory capacity.
- Compliance Monitoring:Ongoing vigilance for chemistry-manufacturing-controls changes and post-approval commitments requires continuous regulatory surveillance. Medical device manufacturers navigating EU MDR periodic safety update obligations in Italy and France are deepening outsourcing penetration for this function.
- Labeling Support:Package insert harmonization across FDA, EMA, and PMDA jurisdictions.
- Audit Preparation:Mock inspections and deficiency response strategy for health authority readiness.
- Risk Assessment:Benefit-risk documentation for novel therapy submissions.
Submission Management holds installed capacity. Compliance Monitoring is rotating up the share rankings.
Client Type:
Pharmaceutical sponsors generate the highest contract values, though biotechnology firms exhibit steeper outsourcing adoption curves.
- Pharmaceutical Companies:Large sponsors maintain captive regulatory infrastructure but unbundle specialized functions like EU MDR technical documentation and Saudi SFDA local filing requirements. Pfizer and Roche operations in Switzerland and Germany concentrate demand for modular regulatory partnerships.
- Biotechnology Firms:Cell and gene therapy developers lack submission experience and mandate full-service regulatory partnerships from IND through approval. Boston and San Francisco clusters exhibit dense outsourcing penetration as pipeline expansion outpaces hiring.
- Medical Device Manufacturers:Software-as-a-medical-device developers seeking EU AI Act compliance documentation.
- Generic Drug Makers:Abbreviated new drug application specialists requiring variation filing automation.
- Contract Research Organizations:Integrated service providers expanding regulatory advisory capabilities.
Pharmaceutical Companies anchor current revenue. Biotechnology Firms are climbing the fastest.
Therapy Area:
Oncology commands premium pricing due to accelerated approval pathway complexity and companion diagnostic coordination requirements.
- Oncology:Breakthrough therapy designation submissions and oncology center of excellence engagement strategies demand specialized regulatory strategists. FDA and EMA parallel scientific advice utilization concentrates in Boston, Basel, and Cambridge UK clusters.
- Neurology:Rare disease designation applications and pediatric investigation plan negotiations require orphan drug expertise. Amyotrophic lateral sclerosis and gene therapy developers in California and Germany drive niche advisory demand.
- Cardiology:Large outcome trial regulatory packages and device-drug combination submissions.
- Endocrinology:Biosimilar interchangeability documentation and insulin switching studies.
- Pulmonology:Inhaler device equivalence testing and respiratory combination product filings.
Oncology maintains pricing power. Neurology is gaining share fastest.
Delivery Model:
Cloud-based platforms are expanding most quickly as distributed regulatory teams require real-time collaboration infrastructure.
- Cloud-Based Platforms:Document management systems with immutable audit trails and health authority portal integration enable mid-cap sponsor regulatory independence. IQVIA and Veeva deployments across Germany, France, and the United Kingdom accelerate platform adoption.
- Dedicated Teams:Embedded regulatory staff assigned to single sponsor programs provide continuity for complex biologics submissions. Cell therapy developers in Maryland and North Carolina prefer this model for CMC dossier compilation.
- Onshore:US and EU-based staff for FDA and EMA face-to-face meeting preparation.
- Offshore:India and Philippines delivery centers for cost-sensitive variation filing support.
- Hybrid:Blended onshore-offshore teams for 24-hour submission cycle coverage.
Cloud-Based Platforms capture new contract flow. Dedicated Teams defend incumbent relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for regulatory outsourcing varies sharply by market maturity. Sponsors in established markets absorb premium pricing for integrated submission-to-approval pathways. Emerging-market buyers prioritize cost efficiency and local regulatory presence over bundled advisory services.
United States
FDA's digital health guidance and breakthrough therapy designation pathways concentrate demand in Massachusetts and California. Cell therapy developers in Boston and San Francisco outsource complete regulatory infrastructure from IND through approval. The FDA's compressed response windows for sponsor queries accelerate cloud-based platform adoption.
Germany
EU MDR rollout and notified body capacity constraints drive post-market surveillance outsourcing. Munich and Heidelberg biotech clusters expand regulatory partnerships for chemistry-manufacturing-controls dossier compilation. Germany's medical device manufacturers face MDR-mandated vigilance reporting obligations that exceed internal bandwidth.
China
NMPA data residency requirements fragment global outsourcing arrangements for multinational sponsors. Shanghai and Beijing regulatory consultancies build localized CMC expertise to serve domestic biopharma growth. The NMPA's evolving digital submission standards create demand for specialized technical documentation partners.
Switzerland
Swissmedic's alignment with EMA procedures enables Basel and Zurich sponsors to leverage dual-track filing strategies. Roche and Novartis operations concentrate demand for modular regulatory partnerships spanning EU and US markets. Switzerland's precision medicine focus drives specialized advisory needs for companion diagnostic coordination.
United Kingdom
MHRA's post-Brexit regulatory independence reshapes submission strategies for London and Cambridge sponsors. Parallel FDA-MHRA scientific advice utilization compresses development timelines for novel therapies. UK biotechnology firms deepen outsourcing penetration as pipeline expansion outpaces internal regulatory hiring.
Healthcare Regulatory Affairs Outsourcing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the regulatory outsourcing landscape. Full-service CROs anchor premium pricing through integrated real-world evidence and submission management capabilities. Mid-tier specialists compete on modular service unbundling and therapeutic area depth. The market structure rewards simultaneous FDA-EMA inspection readiness and cloud-based platform infrastructure. Consolidation pressure intensifies as sponsors demand single partners for multi-jurisdictional filings.
Within the integrated service tier, IQVIA and Charles River Laboratories exemplify divergent competitive positioning. IQVIA leverages its data infrastructure to anchor multi-market authorization strategies. Charles River Laboratories sustains positioning through captive toxicology capabilities that streamline regulatory package compilation. WuXi AppTec occupies a distinct geography-focused position with Asia-Pacific filing volume concentration.
| Leading Market Players |
|---|
| Charles River Laboratories |
| WuXi AppTec |
| IQVIA |
| Medpace |
| Syneos Health |
| Parexel International Corporation |
| Labcorp |
| Covance |
| ICON plc |
| Others |
Cost & Logistics Intelligence
Platform scale economies in cloud-based regulatory document management concentrate vendor bargaining power and compress price floors for mid-cap sponsors. FDA and EMA inspection-ready capacity utilization rates above eighty percent sustain premium pricing for dual-jurisdiction submission bundles.
Pricing Analysis
EU MDR and FDA digital health guidance dictate the pricing tier structure across the Healthcare Regulatory Affairs Outsourcing Market. Three-tier pricing structure across premium, standard, and economy levels segments by inspection-readiness certification and therapeutic area complexity. Price differentiation hinges on simultaneous FDA-EMA audit capability and real-world evidence integration depth. Cost compression in the economy tier is intensifying because India and Philippines delivery centers expand variation-filing automation. Biotechnology firms exhibit highest price sensitivity; large pharmaceutical sponsors absorb premiums for integrated submission-to-approval pathways.
Supply Chain Analysis
Germany and Switzerland anchor regulatory talent production for EU MDR technical documentation and notified body liaison services. The supply chain draws from specialized regulatory strategists with cross-jurisdictional biologics experience, cloud-based document management infrastructure, and captive toxicology data repositories. Single-source vulnerability concentrates in FDA-EMA dual-inspection-ready consultant pools. Distribution runs through direct enterprise contracting with mid-tier sponsors and platform-enabled self-service modules for standardized filings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based platform interoperability with health authority portals marks a platform-economics inflection, rewarding vendors who anchor sponsor workflows through integrated submission management ecosystems.
For Market Incumbents: Shield installed base relationships by embedding proprietary real-world evidence infrastructure into multi-market authorization strategies. Build simultaneous FDA-EMA inspection-ready capacity in Germany and Switzerland to defend against modular unbundling by specialized boutiques. Prioritize API-based connectivity with legacy sponsor document management systems to raise switching costs.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track advisory services open white-space penetration in Boston and San Francisco cell therapy clusters. EU AI Act algorithmic transparency documentation for software-as-a-medical-device manufacturers represents the most penetrable segment. Pursue best-of-breed modular contracting with mid-cap biotechnology firms unbundling chemistry-manufacturing-controls writing from health authority meeting preparation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-enabled regulatory service providers with health authority portal integration capabilities. Long-term viability rests on cloud infrastructure ownership and data interoperability standards adoption. Acquisition target archetype: specialized EU MDR post-market surveillance boutiques in Germany, France, and Italy. Signal to watch: NMPA data residency mandates fragmenting global outsourcing arrangements into localized joint ventures.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | IQVIA and Veeva deployments across Germany, France, and the United Kingdom accelerate mid-cap sponsor regulatory independence. |
| Dual-Track Filing Capability | Simultaneous FDA-EMA inspection readiness reduces sequential regulatory risk for novel therapy developers in Basel and Boston. |
| EU AI Act Compliance Services | Algorithmic transparency documentation for machine learning-enabled diagnostics opens specialized advisory revenue streams. |
| Real-World Evidence Infrastructure | Electronic health record interoperability standards enable novel approval pathway support services for oncology submissions. |
| Localized NMPA Partnership | Shanghai and Beijing regulatory consultancies build captive CMC expertise to serve domestic biopharma growth. |
Research Approach
Initial hypotheses were tested against primary input from regulatory affairs leads, drug development executives, formulary directors, and health authority liaison specialists and refined through secondary validation. Primary fieldwork combined structured interviews with FDA and EMA submission managers, biotechnology firm regulatory heads, and notified body assessment directors. Secondary sources encompassed FDA filings, EMA submission databases, ClinicalTrials.gov records, and EU MDR vigilance reporting repositories. Bottom-up service-type demand modeling and top-down market sizing triangulated volume and value estimates.
Variance decomposition across service type, client type, therapy area, delivery model, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare R&D expenditure trends. Forecast inputs incorporated biotechnology pipeline expansion rates, EU MDR transition timelines, and cloud platform adoption curves across mid-cap sponsors. Outputs reflect modeled trajectories across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA parallel scientific advice utilization or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding inspection readiness standard convergence and data sovereignty fragmentation patterns. Recalibration cycles align with material shifts in health authority digital submission standards and notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market