
 Europe Mobile Tomography Market | 2026-2036
Europe Mobile Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Tomography Market Insights
Manufacturing capacity across Germany and the Netherlands is shifting toward modular mobile imaging platforms designed for rapid deployment. Siemens Healthineers leverages its established service network to dominate fleet-based contracts across German university hospitals. GE Healthcare sustains competitive positioning through backward integration into detector technology and proprietary reconstruction software. Koninklijke Philips NV differentiates via hybrid imaging architectures that combine CT with interventional guidance capabilities.
Mobile tomography encompasses transportable diagnostic imaging systems mounted on vehicles or designed for relocation between clinical sites, typically featuring self-contained power systems, climate-controlled environments, and vibration-dampened gantries to preserve image fidelity during transit. These systems deliver diagnostic-grade imaging to underserved populations, disaster zones, and facilities undergoing infrastructure renovation. CT Scanner configurations command the largest installed base due to shorter exam times and lower per-scan operational costs relative to MRI alternatives. Digital Imaging technology represents the fastest-expanding segment as facilities replace analog detector arrays with solid-state photon-counting sensors. Magnetic Resonance mobile units retain premium positioning in neurology and musculoskeletal applications where soft-tissue contrast determines diagnostic utility.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies in Germany and France intensifying scrutiny of electromagnetic compatibility and radiation safety documentation for mobile platforms. The EU Green Deal and F-Gas Regulation are pressuring manufacturers to eliminate sulfur hexafluoride insulation in high-voltage CT components, accelerating redesign cycles. Stakeholders must monitor how national reimbursement authorities in France, Italy, and Spain classify mobile imaging relative to fixed-installation services, as this determination shapes contract economics for fleet operators and hospital procurement committees.
Market Dynamics
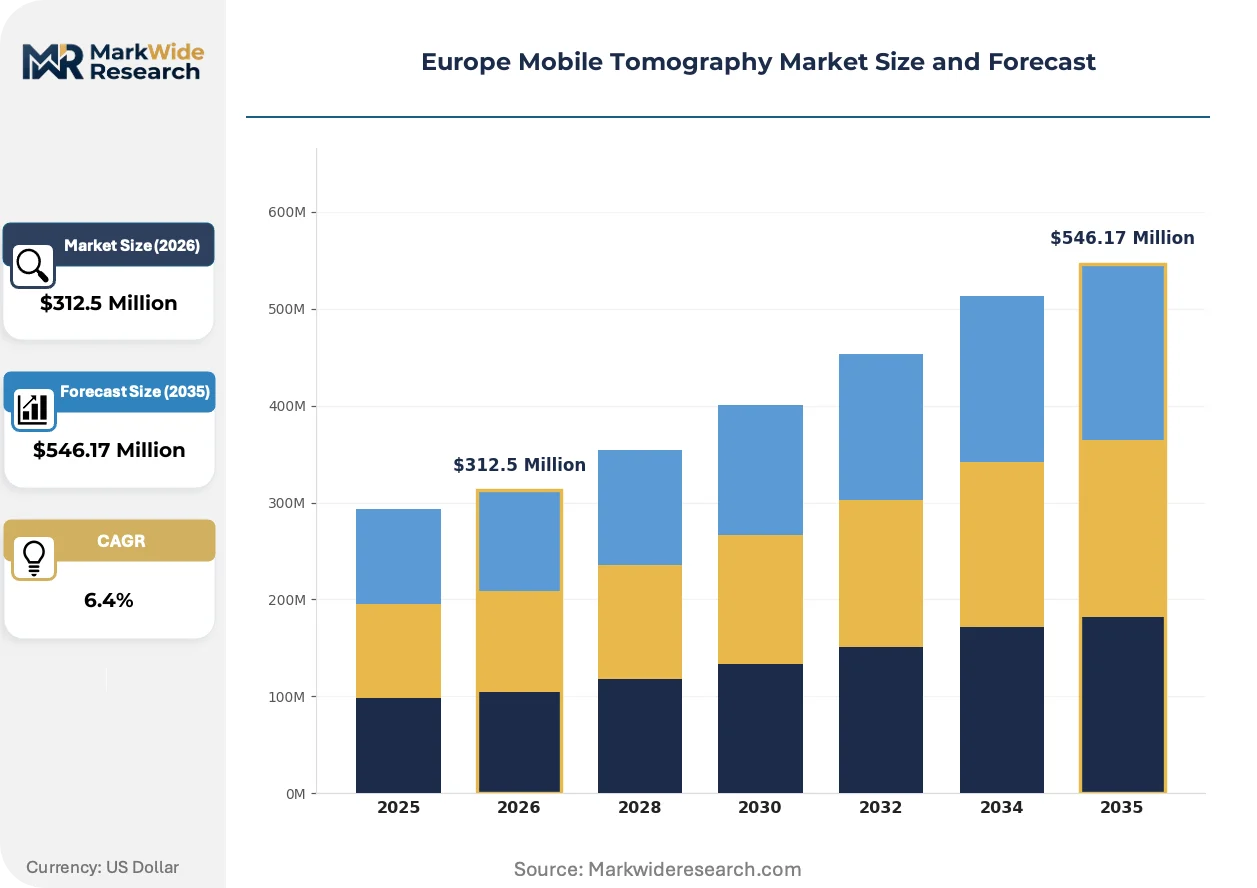
The EU Medical Device Regulation (MDR) is compressing certification timelines for mobile imaging platforms while German university hospitals accelerate fleet procurement to address surgical waiting lists. This regulatory-demand tension is restructuring vendor-hospital contracting toward performance-guaranteed service models.
Growth Catalysts
- Surgical Backlog Clearance Mandates:German regional health authorities are funding mobile CT deployments to reduce elective procedure queues in Bavaria and North Rhine-Westphalia.
- CE Marking Acceleration:Notified bodies in France and Germany have streamlined conformity assessment pathways for modular mobile platforms with pre-validated subsystems.
- Photon-Counting Detector Maturation:Solid-state sensor arrays are replacing analog detectors, cutting per-scan radiation dose and expanding eligible patient populations.
Market Restraints
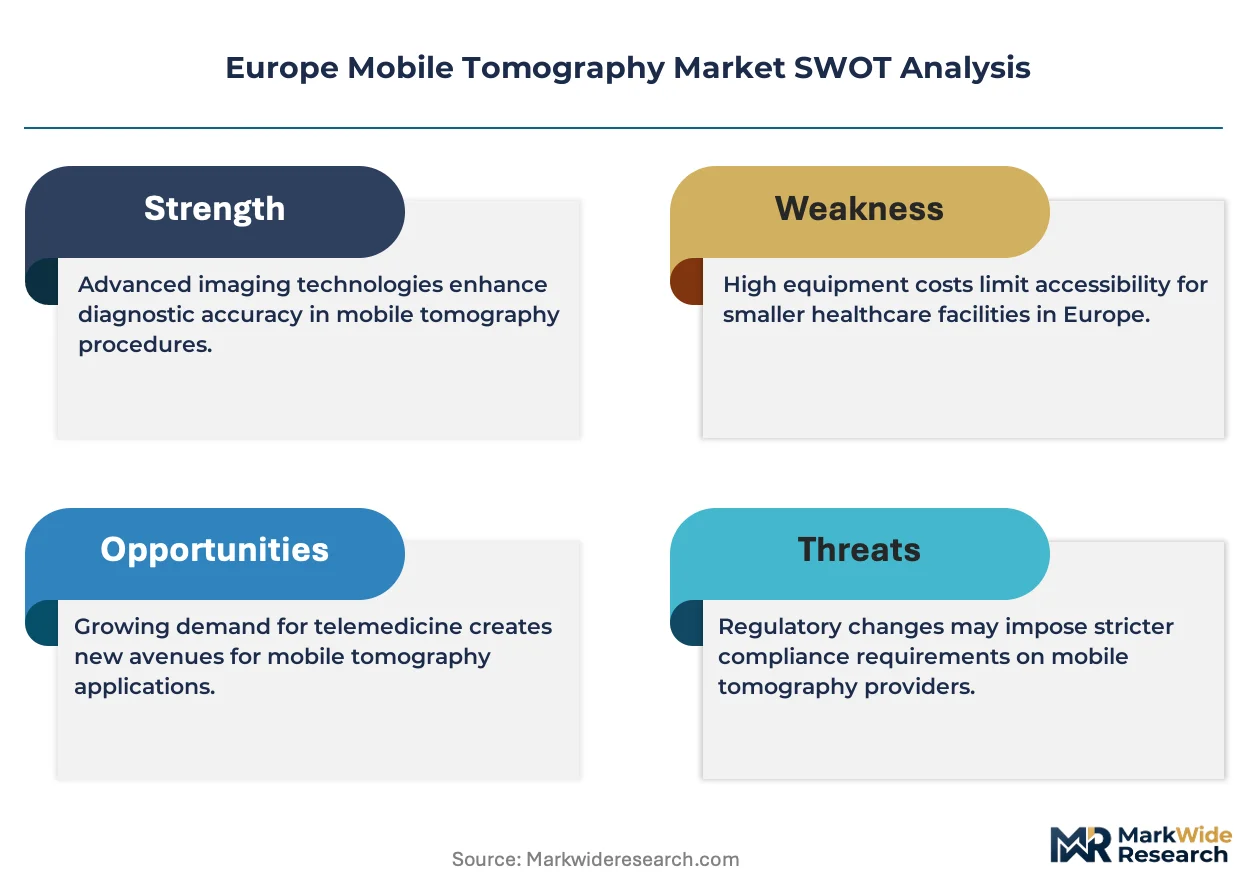
- Specialized Component Concentration:High-voltage CT transformers and helium-cooled MRI magnets depend on a concentrated supplier base in southern Germany and Switzerland.
- F-Gas Compliance Costs:The EU F-Gas Regulation is forcing redesign of sulfur hexafluoride-insulated components, adding eighteen to twenty-four months to product development cycles.
- Fixed-Installation Preference:French and Italian reimbursement authorities classify mobile imaging at lower tariff rates than permanent installations, compressing fleet operator margins.
Strategic Opportunities
- Eastern European Infrastructure Gaps:Poland and Romania present fleet expansion potential where rural hospital networks lack capital budgets for fixed CT suites.
- Hybrid Interventional Platforms:Convergence of mobile CT with fluoroscopic guidance is opening intraoperative imaging contracts in German and Dutch cardiac surgery centers.
- Green Public Procurement:The EU Green Deal is creating preferential tender scoring for mobile units with recyclable gantry materials and reduced transport emissions.
Industry Challenges
- Electromagnetic Compatibility Certification:Mobile platforms must demonstrate interference resilience across variable power grids in transit, extending validation timelines.
- Cross-Border Service Integration:Fleet operators struggle to harmonize maintenance protocols across German, French, and Benelux regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Tomography Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanner, MRI Scanner, PET Scanner, Ultrasound Scanner Technology: Digital Imaging, Magnetic Resonance, Computed Tomography, Hybrid Imaging End User: Hospitals, Clinics, Imaging Centers, Emergency Services Delivery Mode: Mobile Units, Fixed Units, Portable Devices, Others |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems, Hitachi Medical Systems, Medtronic, FUJIFILM Holdings Corporation, Esaote SPA, United Imaging Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Tomography Market Trends and Innovations
Artificial intelligence reconstruction algorithms and photon-counting detector architectures are converging to redefine image acquisition economics. These advances are compressing exam durations while expanding diagnostic utility in point-of-care settings.
Photon-counting CT detectors are automating spectral imaging workflows previously requiring dual-source scanner configurations. German university hospitals are adopting these sensors for cardiac and pediatric applications where dose reduction determines protocol feasibility. The technology is automating real-time material decomposition, eliminating post-processing bottlenecks that previously constrained mobile unit throughput.
The EU F-Gas Regulation is mandating elimination of sulfur hexafluoride insulation in high-voltage CT components by 2030. Manufacturers are redesigning power electronics around vacuum interrupters and dry-type transformers to maintain dielectric performance. Mobile platform suppliers with German manufacturing footprints are accelerating prototype testing to secure notified body approval before the compliance deadline.
Spanish and Italian hospital procurement committees are unbundling equipment purchase from maintenance and radiologist interpretation services. Fleet operators are responding with per-scan pricing models that shift capital risk from cash-constrained facilities to vendor balance sheets. This restructuring is most visible in Andalusia and Sicily where regional health systems lack centralized imaging infrastructure budgets.
Europe Mobile Tomography Market Segmentation
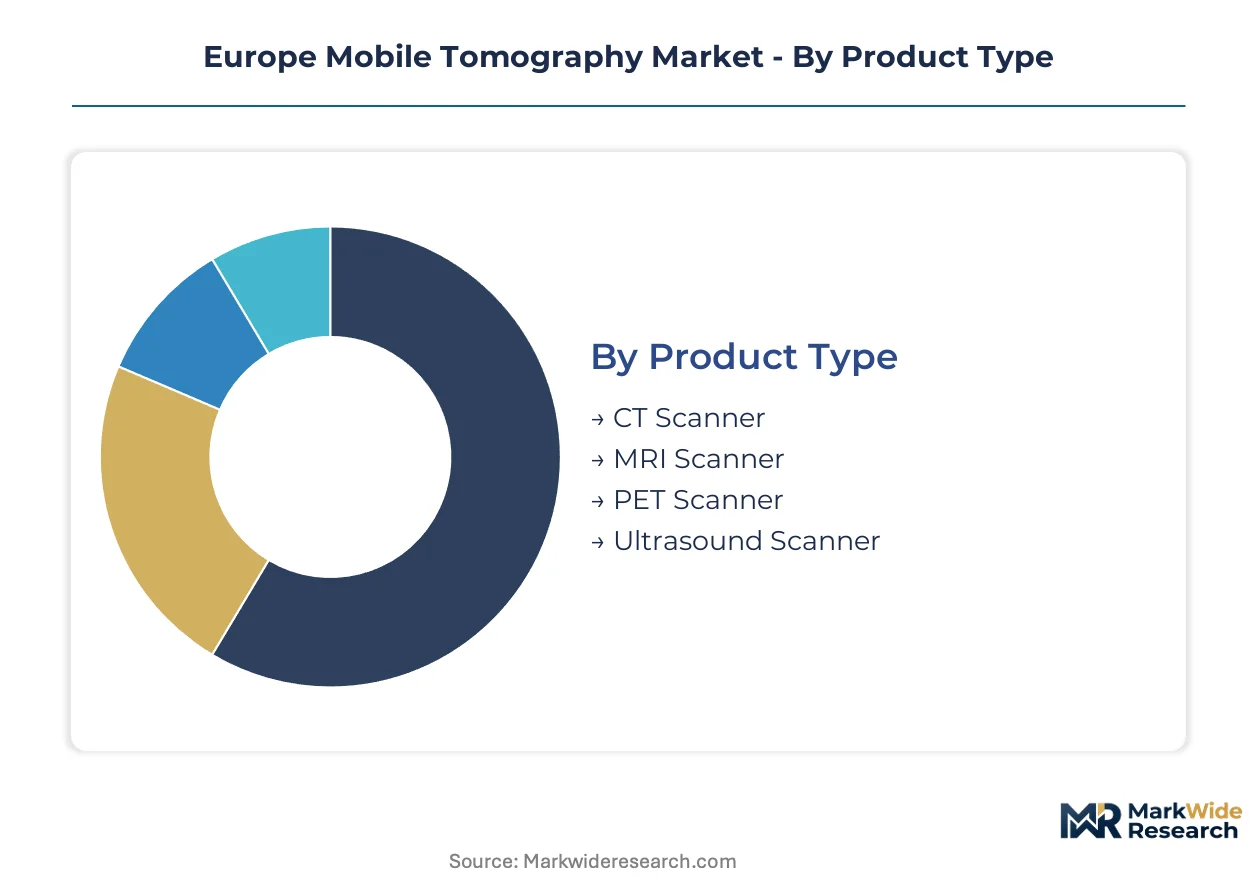
Mobile tomography procurement in Europe splits across equipment configurations, underlying physics, clinical settings, and deployment logistics. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape vendor strategy across German, French, and Benelux health systems.
Product Type:
Customization intensity varies sharply across modalities, from standardized CT platforms to bespoke MRI configurations requiring site-specific shielding validation.
- CT Scanner:Self-contained gantry systems with vibration-dampened mounts preserve sub-millimeter spatial fidelity during transit. German university hospitals in Bavaria and North Rhine-Westphalia are expanding fleet contracts to clear surgical backlogs, with regional health authorities funding rapid-deployment configurations.
- MRI Scanner:Superconducting magnet platforms demand liquid helium supply chains and Faraday cage compatibility checks at each clinical site. Demand concentrates in Dutch and Swiss neurology networks where soft-tissue contrast protocols justify higher per-scan operational costs.
- PET Scanner:Radiotracer logistics constrain mobility; cyclotron proximity determines viable service radius.
- Ultrasound Scanner:Compact probe-based systems dominate emergency service tenders in rural Poland and Romania.
Most installed capacity flows through CT Scanner configurations. Expansion is steepest in MRI Scanner segments where academic medical centers prioritize spectral soft-tissue protocols.
Technology:
Cost tiers separate legacy analog architectures from premium photon-counting and hybrid modalities, with reimbursement rates in France and Italy compressing mid-tier adoption.
- Digital Imaging:Solid-state photon-counting detector arrays automate spectral decomposition without dual-source hardware. German cardiac centers are retrofitting mobile fleets with these sensors to cut pediatric radiation exposure while maintaining diagnostic throughput.
- Computed Tomography:Conventional energy-integrating detectors retain share in price-sensitive Southern European tenders where capital budgets prioritize scan volume over dose optimization.
- Magnetic Resonance:Helium-cooled superconducting systems command premium positioning in musculoskeletal and neurovascular applications.
- Hybrid Imaging:PET-CT and SPECT-CT convergence targets oncology staging workflows in Belgian and Dutch comprehensive cancer centers.
Digital Imaging commands the highest margin tier per unit. Photon-counting maturation is gaining share fastest as MDR-compliant platforms reach notified body approval.
End User:
Customer type determines contract structure, from capital purchase committees at academic hospitals to per-scan leasing models for cash-constrained rural clinics.
- Hospitals:German university hospitals dominate fleet procurement through performance-guaranteed service contracts spanning equipment, maintenance, and radiologist interpretation.
- Clinics:Independent diagnostic centers in Andalusia and Sicily are unbundling purchase from service, shifting capital risk to vendor balance sheets.
- Imaging Centers:Benelux networks operate centralized scheduling across multiple mobile units to maximize gantry utilization.
- Emergency Services:Civil defense and military medical corps in Eastern Europe specify ruggedized platforms with autonomous power systems.
Hospitals anchor procurement volume. Emergency Services are expanding most quickly as disaster preparedness mandates tighten across EU member states.
Delivery Mode:
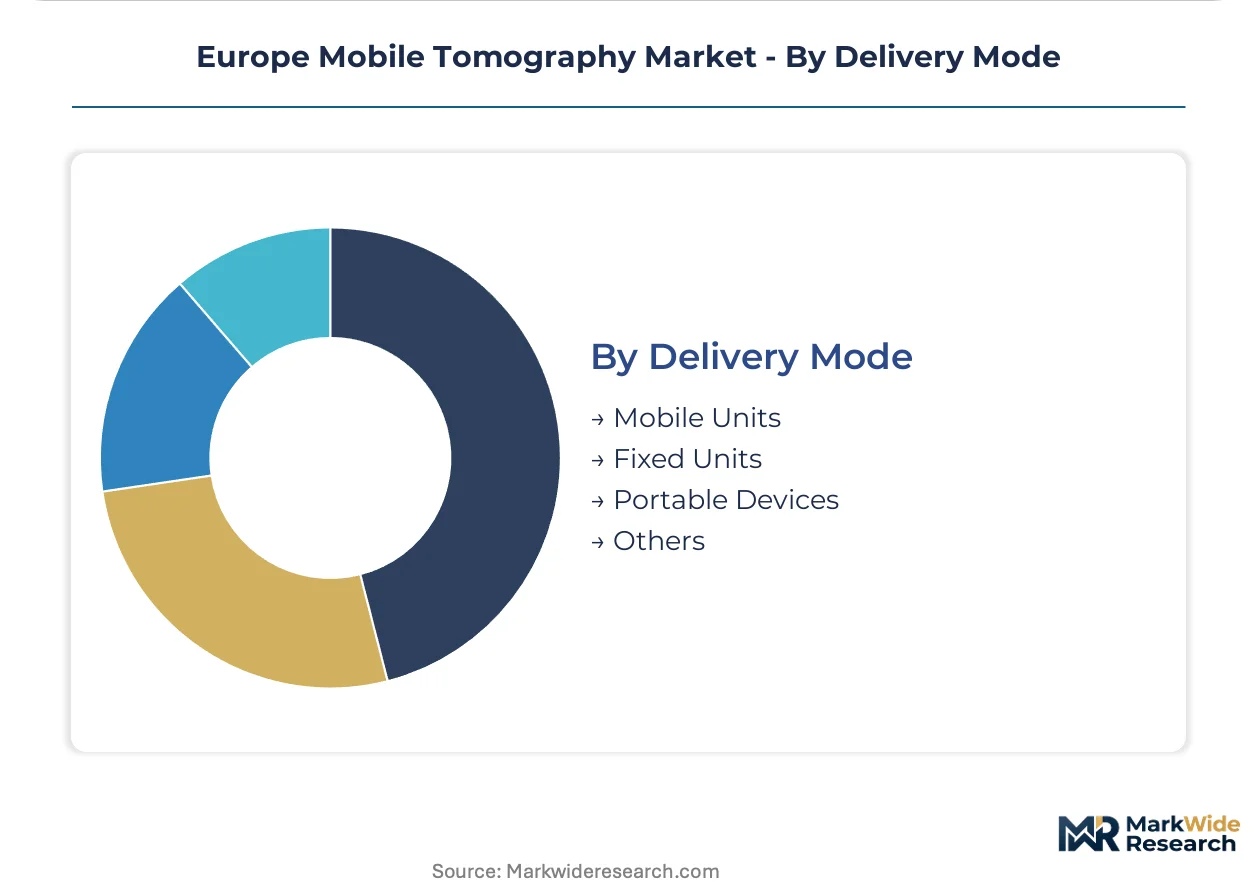
Volume concentration sits with vehicle-mounted units, while portable configurations address point-of-care gaps in infrastructure-limited settings.
- Mobile Units:Truck-mounted gantries with climate-controlled cabins serve rotating schedules across hospital networks. Siemens Healthineers and GE Healthcare dominate German fleet contracts through integrated service networks.
- Fixed Units:Modular platforms designed for rapid relocation between clinical sites suit renovation projects in aging French hospital infrastructure.
- Portable Devices:Battery-powered CT and ultrasound systems target battlefield and disaster zone deployment specifications from Italian and Spanish civil protection agencies.
- Others:Containerized configurations for temporary field hospitals address refugee health crises at EU external borders.
Mobile Units carry the dominant installed base. Portable Devices are climbing the fastest as defense and civil protection budgets expand across Southern and Eastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for mobile imaging systems is migrating toward jurisdictions with streamlined notified body pathways, compressing certification timelines by eight to fourteen months relative to jurisdictions with heavier documentation burdens.
Germany
Bavarian and North Rhine-Westphalian health authorities are funding rapid-deployment CT fleets to clear surgical backlogs exceeding eighteen months. The EU MDR's tightened electromagnetic compatibility requirements are accelerating consolidation of notified body capacity in Berlin and Munich. Siemens Healthineers anchors production in Erlangen while expanding service networks across university hospital clusters.
France
Regional health agencies in Île-de-France and Auvergne-Rhône-Alpes are unbundling equipment procurement from radiologist interpretation services. ANSM intensifies scrutiny of radiation safety documentation for mobile platforms, extending validation timelines for non-modular configurations. Paris-based fleet operators are piloting per-scan pricing models to shift capital risk from cash-constrained public hospitals.
Netherlands
Benelux imaging networks operate centralized scheduling systems across rotating mobile units to maximize gantry utilization above eighty-five percent. The EU Green Deal's public procurement scoring rewards recyclable gantry materials and reduced transport emissions. Eindhoven-region manufacturers are redesigning power electronics around vacuum interrupters to eliminate sulfur hexafluoride insulation before the 2030 F-Gas deadline.
Italy
Sicilian and Calabrian regional health systems lack centralized imaging infrastructure budgets, driving demand for vendor-financed mobile deployments. Italian reimbursement authorities classify mobile imaging at lower tariff rates than permanent installations, compressing fleet operator margins. Milan-based procurement committees are negotiating performance-guaranteed service contracts spanning equipment, maintenance, and remote interpretation.
Poland
Rural hospital networks in Lesser Poland and Silesia lack capital budgets for fixed CT suites, creating fleet expansion opportunities for Western European operators. Polish civil protection agencies are specifying ruggedized portable platforms with autonomous power systems for disaster preparedness mandates. Warsaw-based distributors are establishing maintenance hubs to reduce cross-border service integration friction.
Europe Mobile Tomography Market Competitive Landscape
German producers anchor the premium-tier service-contract segment; Dutch and Belgian specialists hold the modular platform niche. Vendor-hospital relationships consolidate around performance-guaranteed models where equipment, maintenance, and interpretation bundle into per-scan economics. Three archetypes dominate: diversified imaging conglomerates with captive detector technology, mid-scale fleet operators with regional service density, and niche portable-device fabricators targeting defense tenders. Competitive moves center on backward integration into photon-counting sensors and strategic partnerships with university hospitals for clinical validation.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare exemplify the service-network archetype, leveraging established footprints to dominate fleet-based contracts. Koninklijke Philips NV occupies a position within the hybrid-imaging tier, differentiating through convergence of CT with interventional guidance capabilities. These three anchors illustrate how scale-driven players compress procurement cycles through pre-validated subsystem platforms and integrated financing structures.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems |
| Hitachi Medical Systems |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Esaote SPA |
| United Imaging Healthcare |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access for mobile tomography manufacturers redesigning high-voltage CT components around vacuum interrupters and dry-type transformers. This environmental mandate compresses development timelines while elevating compliance costs, forcing tiered pricing stratification between MDR-certified modular platforms and legacy configurations facing obsolescence.
Pricing Analysis
Distributor margins for mobile imaging platforms typically range from twelve to eighteen percent before hospital procurement committees negotiate fleet-based service bundles. Three-tier pricing structure across premium photon-counting configurations, standard energy-integrating detectors, and economy analog platforms reflects CE marking tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because Spanish and Italian regional health systems unbundle equipment purchase from radiologist interpretation. Public hospitals in Southern Europe exhibit highest price sensitivity; German university hospitals with performance-guaranteed contracts show lowest sensitivity due to centralized infrastructure budgets.
Supply Chain Analysis
Refurbishment flows for helium-cooled MRI magnets and high-voltage CT transformers concentrate reverse logistics networks in southern Germany and Switzerland, extending asset lifecycles for fleet operators. Manufacturing draws from concentrated supplier bases in Germany, the Netherlands, and Switzerland for superconducting wire, solid-state detector arrays, and precision gantry bearings. Single-source vulnerability sits with liquid helium supply chains tethered to Qatar and Algeria export terminals. Distribution runs through integrated service networks anchored by Siemens Healthineers and GE Healthcare, with regional fleet operators managing rotating schedules across hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Mobile Tomography Market functions as a regulatory compounder where the EU MDR's tightened electromagnetic compatibility requirements and F-Gas elimination mandates are accelerating replacement demand across German and Benelux hospital networks.
For Market Incumbents: To counter margin compression from unbundled procurement models in Southern Europe, deepen backward integration into photon-counting detector fabrication and secure notified body pre-validation for modular subsystems. Anchor capacity expansion in Eindhoven-region manufacturing hubs to exploit streamlined Dutch certification pathways and Green Deal procurement scoring advantages. For New Entrants and Emerging Players: The premium-to-economy price-point gap in mobile MRI configurations presents white-space opportunity for mid-tier vendors offering helium-recycling service bundles. Target rural Polish and Romanian hospital networks lacking capital budgets for fixed CT suites, penetrating through per-scan leasing models with Warsaw-based maintenance hub support. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fleet operators with dense Benelux service networks but limited photon-counting retrofit capabilities. Long-term viability hinges on MDR compliance completion and university hospital validation partnerships. Watch German regional health authority funding announcements for Bavaria and North Rhine-Westphalia as inflection indicators for fleet expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Streamlined conformity assessment for modular platforms compresses German hospital procurement cycles by eight to fourteen months. |
| Hospital System Partnership | Performance-guaranteed service contracts with Bavarian university hospitals lock in multi-year fleet utilization above eighty-five percent. |
| Green Manufacturing Transition | Vacuum interrupter redesign eliminates sulfur hexafluoride insulation ahead of EU F-Gas Regulation deadlines. |
| Software Companion Development | AI reconstruction algorithms automate spectral decomposition, expanding pediatric and cardiac protocol eligibility. |
| Reimbursement Strategy | Advocacy for tariff parity between mobile and fixed-installation imaging in France and Italy protects fleet operator margins. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, fleet operations directors, and notified body representatives with secondary validation against EMA device registration databases, German hospital procurement records, and Benelux GPO contract disclosures. Bottom-up installation base modeling and top-down healthcare expenditure triangulation anchored volume estimates.
Segment-weighting applied differential growth assumptions across product type, technology tier, end-user category, and delivery mode dimensions over the projection horizon. CAGRs derived from logistic adoption curves fitted to photon-counting detector penetration rates and MDR compliance transition timelines. Forecast inputs incorporated surgical backlog clearance mandates from Bavarian and North Rhine-Westphalian health authorities and F-Gas redesign completion schedules.
Caveats apply where reimbursement reclassification in France or Italy, helium supply disruption, or electromagnetic compatibility certification delays could materially shift the outlook. Forecasts reflect documented assumptions regarding MDR notified body capacity and regional health authority funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Open System MRI Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Mammography Detectors Market