
 Specialty PACS Market | 2026-2036
Specialty PACS Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty PACS Market Outlook
Hospital networks are bifurcating from independent imaging centers as the dominant buyer archetype for enterprise-grade Specialty PACS deployments. Siemens Healthineers leverages its installed base of imaging modalities to bundle PACS contracts with hardware refresh cycles. GE HealthCare anchors its competitive position through deep integration with electronic health record ecosystems. Sectra AB differentiates via cybersecurity-hardened architectures that appeal to defense and government healthcare providers.
Specialty PACS denotes dedicated picture archiving and communication systems engineered for clinical domains beyond general radiology, typically supporting DICOM image ingestion at throughput rates exceeding 10,000 studies daily while enabling multi-site image distribution across federated networks. Radiology applications retain the largest installed base, though pathology segments exhibit the steepest adoption trajectory as whole-slide imaging digitization accelerates. Cloud-based deployment models capture growing preference among mid-sized imaging centers seeking to avoid capital-intensive server infrastructure, while hybrid architectures dominate in health systems requiring local latency for emergency reads.
FDA 510(k) pathways govern software-as-a-medical-device classifications for AI analytics modules, compelling vendors to validate clinical performance against predicate devices. HIPAA security rule provisions mandate encryption standards for image transmission that influence cloud provider selection and data residency decisions. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms, as regulatory clarity will determine which technology investments achieve scalable market access.
Market Dynamics
Hospital procurement departments now mandate cloud-native architectures in RFPs, forcing incumbent vendors to reengineer monolithic codebases while AI validation timelines compress product release cycles.
Growth Catalysts
- HIPAA Security Rule updates:Encryption mandates for image transmission accelerate replacement of legacy on-premise systems in United States health systems.
- Whole-slide imaging digitization:Pathology laboratories in Germany and Japan deploy high-throughput scanners requiring petabyte-scale storage architectures.
- Oncology workflow integration:Hospital networks consolidate imaging, genomics, and treatment planning into unified platforms.
Market Restraints
- Specialized radiologist shortage:Teleradiology service concentration in India creates dependency risk for overnight reads in Western markets.
- FDA 510(k) pathway complexity:Adaptive AI algorithm submissions face predicate device matching challenges that extend clearance timelines.
- Legacy DICOM incompatibility:Decades-old image formats resist seamless migration to cloud-native object storage.
Strategic Opportunities
- Defense healthcare networks:Cybersecurity-hardened architectures open procurement pathways in government facilities requiring air-gapped deployments.
- Hybrid cloud orchestration:Federated learning across hospital networks enables AI model training without centralizing protected health information.
- EU AI Act compliance services:Conformity assessment requirements for high-risk medical software create advisory revenue streams.
Industry Challenges
- Interoperability engineer scarcity:HL7 FHIR integration expertise commands premium compensation that mid-sized vendors struggle to match.
- Multi-site data residency:Health systems spanning Germany, Switzerland, and Austria navigate conflicting national cloud sovereignty requirements.
- AI drift monitoring:Continuous validation protocols for deployed algorithms demand operational infrastructure most imaging centers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty PACS Market |
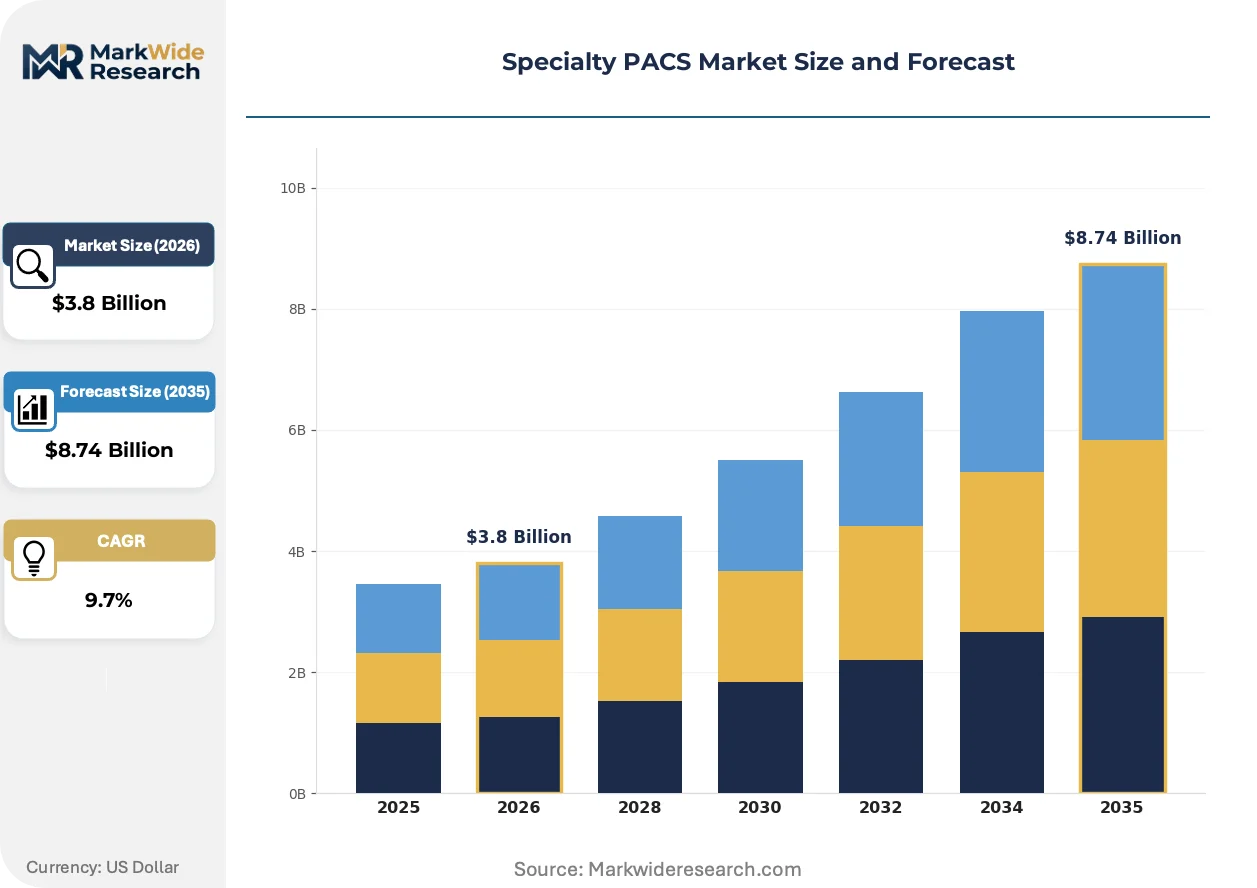
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Radiology, Cardiology, Oncology, Pathology Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS End User: Hospitals, Imaging Centers, Clinics, Research Institutes Technology: DICOM, HL7, Cloud Computing, AI Analytics |
| Companies Covered | Siemens Healthineers, GE HealthCare, Sectra AB, FUJIFILM Holdings Corporation, Koninklijke Philips N.V., Agfa-Gevaert Group, Merative, IBM Corporation, INFINITT Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty PACS Market Strategic Shifts
Containerized microservices architectures are fragmenting the monolithic PACS stack, enabling modular procurement and accelerating vendor substitution. Three developments dominate strategic planning.
Native cloud object storage is supplanting traditional NAS-based DICOM archives in mid-sized imaging centers. Radiology groups with 50-200 daily studies now bypass capital-intensive SAN procurement entirely. This shift compresses hardware refresh cycles from seven years to software-defined capacity scaling.
FDA guidance on predetermined change control plans for machine learning-enabled devices is reshaping product development roadmaps. Vendors must prospectively define algorithm modification boundaries before commercialization. United States-based AI module developers front-load clinical validation costs to secure scalable market access.
Subscription-based enterprise licensing is displacing perpetual ownership models in hospital network procurement. Chief information officers prioritize operational expenditure predictability over depreciation schedules. This preference concentrates most visibly in United States integrated delivery networks consolidating imaging operations across acquired community hospitals.
Specialty PACS Market Segmentation
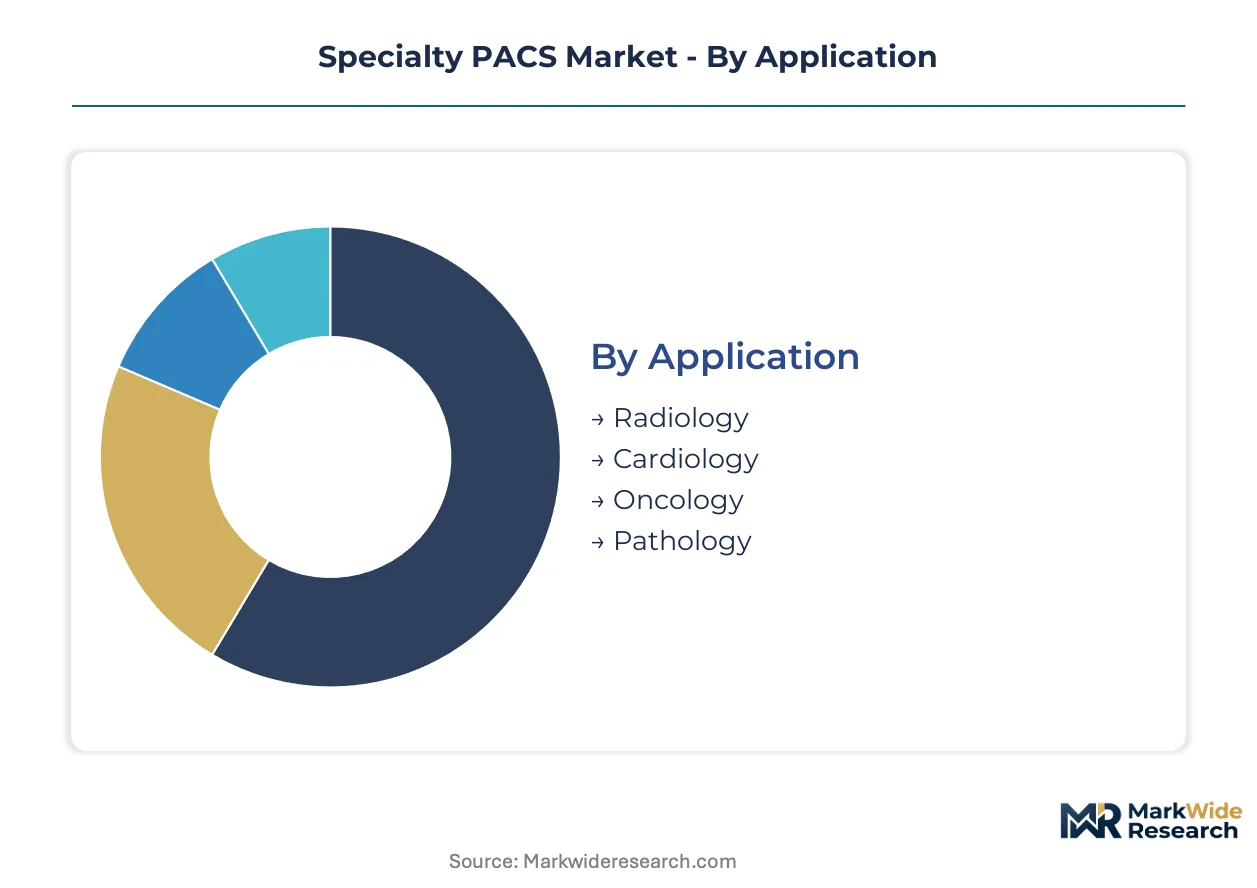
Specialty PACS segmentation reveals distinct margin architectures across clinical domains and infrastructure choices. Procurement patterns diverge sharply between capital-intensive hospital networks and operational-expenditure-focused imaging centers.
Application:
Margin pools concentrate in oncology and cardiology workflows where multi-modal integration commands premium pricing.
- Radiology:Retains the largest installed base with DICOM throughput exceeding 10,000 studies daily in major hospital networks. Demand concentrates in United States health systems modernizing legacy archives, driven by HIPAA encryption mandates forcing infrastructure replacement.
- Oncology:Integrates imaging, genomics, and treatment planning into unified platforms. Hospital networks in Germany and Japan accelerate adoption as precision medicine protocols require seamless data fusion across specialties.
- Cardiology:Supports hemodynamic data integration with echocardiography and catheterization imaging. United States cardiovascular service lines prioritize vendor-neutral archive compatibility.
- Pathology:Whole-slide imaging digitization accelerates in German and Japanese laboratories requiring petabyte-scale storage architectures for high-throughput scanners.
The dominant share belongs to radiology, while pathology is closing the gap fastest.
Deployment Model:
Cost tier stratification separates enterprise health systems from mid-sized imaging centers based on infrastructure ownership preferences.
- Cloud-Based:Eliminates capital-intensive server procurement for mid-sized imaging centers. United States radiology groups with 50-200 daily studies now bypass SAN hardware entirely, compressing refresh cycles from seven years to software-defined scaling.
- Hybrid:Dominates in health systems requiring local latency for emergency reads while archiving to cloud object storage. German and Swiss hospital networks navigate conflicting national cloud sovereignty requirements through federated architectures.
- On-Premise:Persists in defense and government healthcare facilities requiring air-gapped deployments. Cybersecurity-hardened architectures command procurement premiums in these restricted environments.
- SaaS:Subscription licensing displaces perpetual ownership in United States integrated delivery networks consolidating acquired community hospitals. Chief information officers prioritize operational expenditure predictability.
Hybrid architectures capture the dominant deployment share, with cloud-based models expanding most quickly among independent imaging centers.
End User:
Customer type determines contract scale and integration complexity, with hospital networks bifurcating from independent buyers.
- Hospitals:Enterprise-grade deployments mandate cloud-native architectures in RFPs, forcing incumbent vendors to reengineer monolithic codebases. United States hospital procurement departments now require AI-ready infrastructure as standard.
- Imaging Centers:Mid-sized groups favor cloud object storage to avoid capital-intensive infrastructure. These buyers prioritize DICOM ingestion throughput and multi-site distribution capabilities.
- Clinics:Smaller-scale deployments emphasize ease of integration with existing electronic health record ecosystems. GE HealthCare anchors competitive position through deep EHR connectivity in this segment.
- Research Institutes:Federated learning requirements drive demand for hybrid cloud orchestration enabling AI model training without centralizing protected health information.
Hospitals command the dominant share, though research institutes are climbing the fastest as academic medical centers expand imaging biobank initiatives.
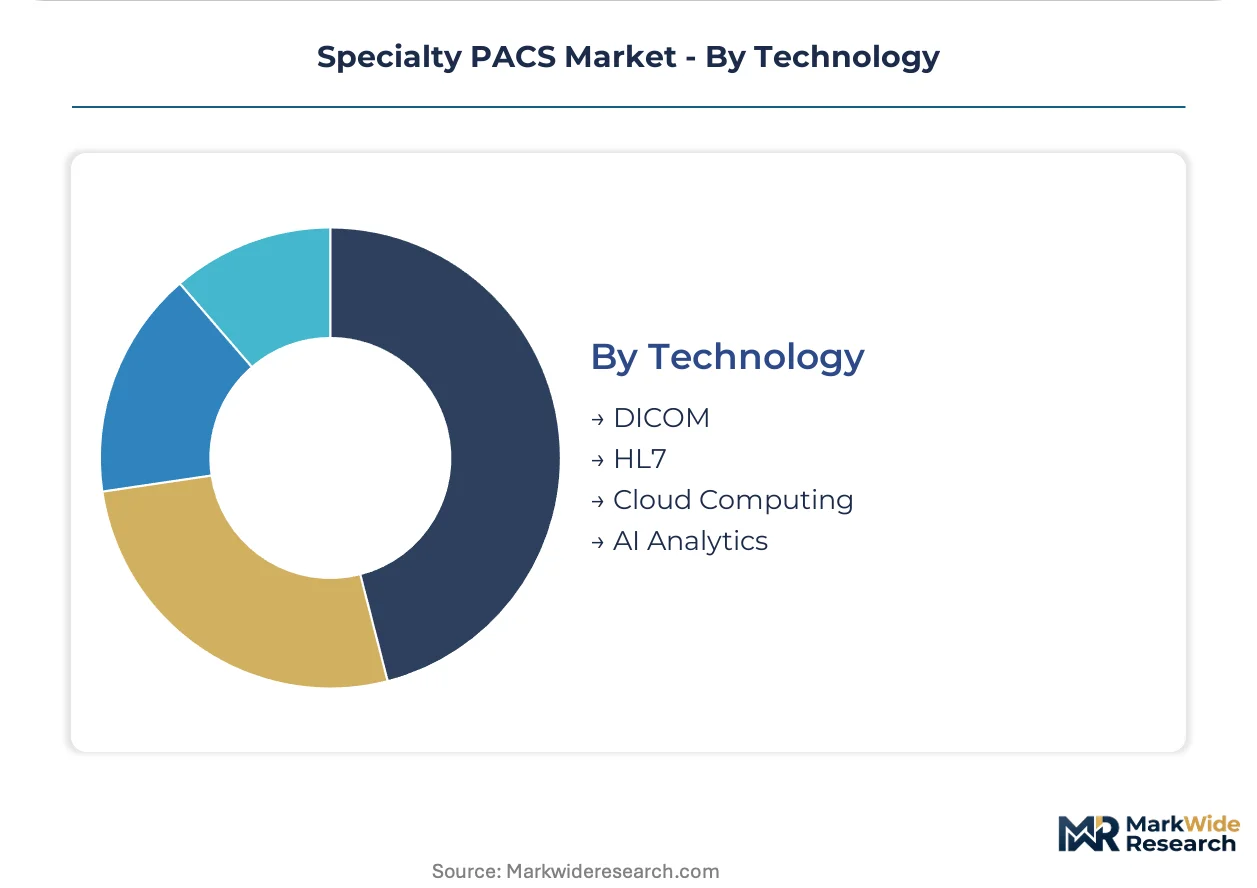
Technology:
Technology maturity curves separate established interoperability standards from emerging AI validation requirements.
- DICOM:Decades-old image formats resist seamless migration to cloud-native object storage, creating integration bottlenecks for legacy archive consolidation.
- HL7:FHIR integration expertise commands premium compensation that mid-sized vendors struggle to match, creating capability scarcity in interoperability engineering.
- Cloud Computing:Native object storage supplants traditional NAS-based archives, enabling modular procurement and accelerating vendor substitution through containerized microservices.
- AI Analytics:FDA 510(k) pathway complexity extends clearance timelines for adaptive algorithms. United States-based developers front-load clinical validation costs to secure scalable market access under predetermined change control plans.
DICOM retains the dominant foundational share, with AI analytics gaining share fastest as regulatory clarity emerges for machine learning-enabled devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German imaging equipment manufacturers supply hospital networks across the United States and Japan, establishing a transatlantic trade corridor for precision diagnostic infrastructure. This export flow concentrates in markets modernizing legacy radiology archives under stringent data protection mandates.
United States
Hospital procurement departments mandate cloud-native architectures in enterprise RFPs, accelerating replacement of on-premise DICOM archives. HIPAA Security Rule encryption requirements for image transmission reshape vendor selection criteria. Major health systems in Texas and California consolidate imaging operations across acquired community hospitals, prioritizing operational expenditure predictability over capital ownership.
Germany
Pathology laboratories deploy high-throughput whole-slide imaging scanners requiring petabyte-scale storage architectures. EU AI Act conformity assessment requirements for high-risk medical software create advisory revenue streams for compliance specialists. Industrial clusters in Bavaria and Baden-Württemberg host precision medicine initiatives integrating genomics with diagnostic imaging workflows.
Japan
Hospital networks accelerate adoption of oncology workflow platforms as precision medicine protocols demand seamless data fusion across specialties. METI digital health initiatives support cloud infrastructure investment in academic medical centers. Tokyo and Osaka metropolitan areas concentrate imaging biobank initiatives driving federated learning requirements.
Switzerland
Health systems navigate conflicting national cloud sovereignty requirements through hybrid architectures spanning German and Austrian borders. Swissmedic regulatory frameworks govern software-as-a-medical-device classifications for AI analytics modules. Zurich and Geneva clusters specialize in cybersecurity-hardened deployments for defense and government healthcare providers.
India
Teleradiology service concentration creates dependency risk for overnight reads in Western markets, amplifying radiologist shortage constraints. CDSCO medical device regulations influence AI-assisted diagnostic tool validation timelines. Bangalore and Hyderabad technology corridors develop interoperability engineering capabilities for HL7 FHIR integration.
Specialty PACS Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities, creating a tiered market structure where scale advantages meet niche expertise. Siemens Healthineers leverages its installed base of imaging modalities to bundle PACS contracts with hardware refresh cycles. Three strategic archetypes dominate: modality-integrated conglomerates, cybersecurity-hardened specialists, and cloud-native platform vendors. Competitive moves concentrate on M&A for AI analytics capabilities and strategic partnerships for EHR ecosystem integration.
Among European-based healthcare technology providers, Sectra AB exemplifies the cybersecurity-specialist archetype through hardened architectures appealing to defense and government facilities. Siemens Healthineers anchors the modality-integrated tier, while GE HealthCare occupies a position emphasizing electronic health record connectivity. These three entities represent distinct competitive vectors rather than direct substitutes, with each archetype capturing procurement pathways aligned to specific infrastructure legacies and risk tolerances.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Sectra AB |
| FUJIFILM Holdings Corporation |
| Koninklijke Philips N.V. |
| Agfa-Gevaert Group |
| Merative |
| IBM Corporation |
| INFINITT Europe GmbH |
| Others |
Value Chain & Pricing Dynamics
Cloud-native object storage substitution for traditional NAS-based DICOM archives simultaneously shifts hardware procurement geography toward hyperscaler data center regions and compresses capital expenditure cycles from seven-year depreciation schedules to software-defined operational scaling.
Pricing Analysis
Next-generation containerized microservices architectures command 40-60% subscription premiums over legacy monolithic PACS deployments, while prior-generation on-premise licenses face residual value erosion. Three-tier pricing structure across premium cybersecurity-hardened, standard cloud-native, and economy SaaS tiers reflects FDA 510(k) certification status and data residency guarantee levels. Cost compression in the standard tier intensifies as mid-sized imaging centers consolidate procurement through GPO contracts. Independent imaging centers exhibit highest price sensitivity, while defense healthcare networks demonstrate lowest elasticity due to air-gapped deployment mandates.
Supply Chain Analysis
Transpacific container availability constraints and port congestion at Los Angeles-Long Beach elevate inbound logistics costs for German-manufactured imaging modalities destined for United States hospital networks. Component sourcing concentrates in Germany for precision optics, Taiwan for semiconductor memory modules, and United States for encryption chipsets. Supply chain vulnerability rests on single-source dependency for high-throughput whole-slide imaging scanners from Bavarian industrial clusters. Distribution runs through modality-integrated conglomerates bundling hardware refresh cycles with PACS licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where HIPAA Security Rule compliance entrenchment and DICOM archive switching costs protect incumbent positions against displacement.
For Market Incumbents: Consolidate AI analytics capabilities through targeted capability acquisitions before FDA predetermined change control plans harden competitive barriers. Deepen backward integration into cloud infrastructure partnerships to capture operational expenditure flows from hospital network consolidations. Defend against cloud-native platform vendors by anchoring EHR ecosystem connectivity.
For New Entrants and Emerging Players: Differentiate on cybersecurity-hardened architectures targeting defense and government healthcare procurement pathways Sectra AB has validated. Penetrate mid-sized pathology laboratories in Germany and Japan requiring petabyte-scale storage architectures underserved by modality-integrated incumbents. Pursue federated learning orchestration partnerships with academic medical centers as beachhead entry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed teleradiology service platforms concentrated in India facing radiologist shortage constraints. Long-term viability favors vendors with FDA 510(k) clearance pipelines and EU AI Act conformity assessment capabilities. Monitor FDA guidance finalization on adaptive AI algorithms as inflection signal for scalable market access winners.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predetermined change control plans secure scalable United States market access for AI modules. |
| Hybrid Cloud Architecture Deployment | Federated learning enables German-Swiss hospital network collaboration without centralizing PHI. |
| Cybersecurity Hardening Certification | Defense healthcare procurement pathways in Switzerland command air-gapped deployment premiums. |
| Whole-Slide Imaging Integration | Pathology digitization in Japanese laboratories drives petabyte-scale storage contract expansion. |
| EHR Ecosystem Partnership | Deep GE HealthCare connectivity anchors clinic segment procurement against modular competitors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement directors, PACS administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement registries, and hyperscaler healthcare cloud capex disclosures. Bottom-up deployment model sizing triangulated against top-down health system IT budget aggregates.
Across the projection horizon, the analytical framework modeled segmentation across application type, deployment architecture, end-user scale, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, cloud migration velocity, and AI module attach rate assumptions. Forecast inputs incorporated HIPAA Security Rule enforcement timelines and EU AI Act conformity assessment rollout patterns.
Material uncertainties — FDA adaptive AI guidance revisions, radiologist shortage escalation, cloud sovereignty requirement fragmentation — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
X-Ray Film Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Industrial X-Ray Machine Market