
 Radar Security Market | 2026-2036
Radar Security Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Security Market Intelligence
A shift from single-source procurement to multi-vendor strategies is decoupling system integration from hardware manufacturing. This allows buyers to select best-in-class components from different suppliers. Thales Group leverages its broad portfolio to provide comprehensive, integrated security solutions. In contrast, Hensoldt specializes in high-performance sensor technologies, while RTX Corporation focuses on advanced radar systems for aerospace and defense clients.
Radar security utilizes radio-frequency energy to detect, track, and classify objects for surveillance and threat assessment. These systems operate in specific frequency bands, such as the X-band for high resolution, providing robust all-weather performance. Phased Array Radar technology leads new deployments due to its superior multi-target tracking capabilities, critical for border security applications. While defense departments constitute the largest end-user base, demand from commercial enterprises for asset protection is expanding rapidly.
Regulatory frameworks, including spectrum allocation rules from the US FCC and emissions standards under Europe's CE marking, dictate market access and system design. In parallel, military procurement mandates adherence to standards like NATO STANAG for interoperability among allied forces. System performance against small, low-signature unmanned aerial vehicles is becoming a primary differentiator. Success hinges on navigating complex export controls while innovating to counter these evolving aerial threats.
Market Dynamics
The proliferation of small, low-signature unmanned aerial vehicles (UAVs) is the central force redefining radar security requirements. This shift compels innovation beyond traditional perimeter defense, demanding systems capable of detecting and classifying agile aerial threats across complex environments like urban centers and critical infrastructure sites.
Growth Catalysts
- Critical Infrastructure Mandates:Government directives in nations like Saudi Arabia and India are compelling operators of energy, transport, and public venues to upgrade security infrastructure, directly boosting radar system procurement for site protection.
- AI and Sensor Fusion:The integration of artificial intelligence algorithms with Phased Array Radar systems enhances target classification and reduces false alarm rates, making these advanced systems more viable for commercial and urban deployments.
- Border Surveillance Modernization:Heightened geopolitical tensions are driving large-scale border security projects, particularly in Eastern Europe and South Asia, which rely on long-range radar networks for persistent, all-weather monitoring.
Market Restraints
- High System Costs:The significant capital expenditure for advanced Phased Array Radar systems, including installation and integration, limits adoption for smaller commercial enterprises and municipalities with constrained security budgets.
- Spectrum Allocation Constraints:Competition for radio-frequency spectrum, governed by bodies like the US FCC and Europe's radio equipment directives, restricts available bands for new radar deployments, complicating system design and market entry.
- Clutter and False Alarms:In dense urban or natural environments, ground clutter and non-threatening objects like birds can generate high false alarm rates, challenging the reliability of automated threat detection systems.
Strategic Opportunities
- Commercial Drone Detection:The emerging market for protecting private venues, corporate campuses, and event spaces from unauthorized drone activity presents a growth vector for compact, lower-cost radar systems.
- GaN Semiconductor Integration:Adopting Gallium Nitride (GaN) semiconductors in radar transmitters offers opportunities to develop more powerful, efficient, and compact systems, opening new applications in mobile security.
- Southeast Asian Infrastructure Projects:Rapid development of new airports and seaports in countries like Vietnam and Indonesia creates greenfield opportunities for integrated radar security solutions, bypassing legacy system constraints.
Industry Challenges
- Complex Export Controls:Navigating stringent export regulations, such as the US International Traffic in Arms Regulations (ITAR), for advanced radar technologies creates significant administrative overhead and can delay sales to international customers.
- System Integration Complexity:Ensuring interoperability between new radar sensors and existing command-and-control platforms, especially under frameworks like NATO STANAG, requires specialized integration expertise that is in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Security Market |
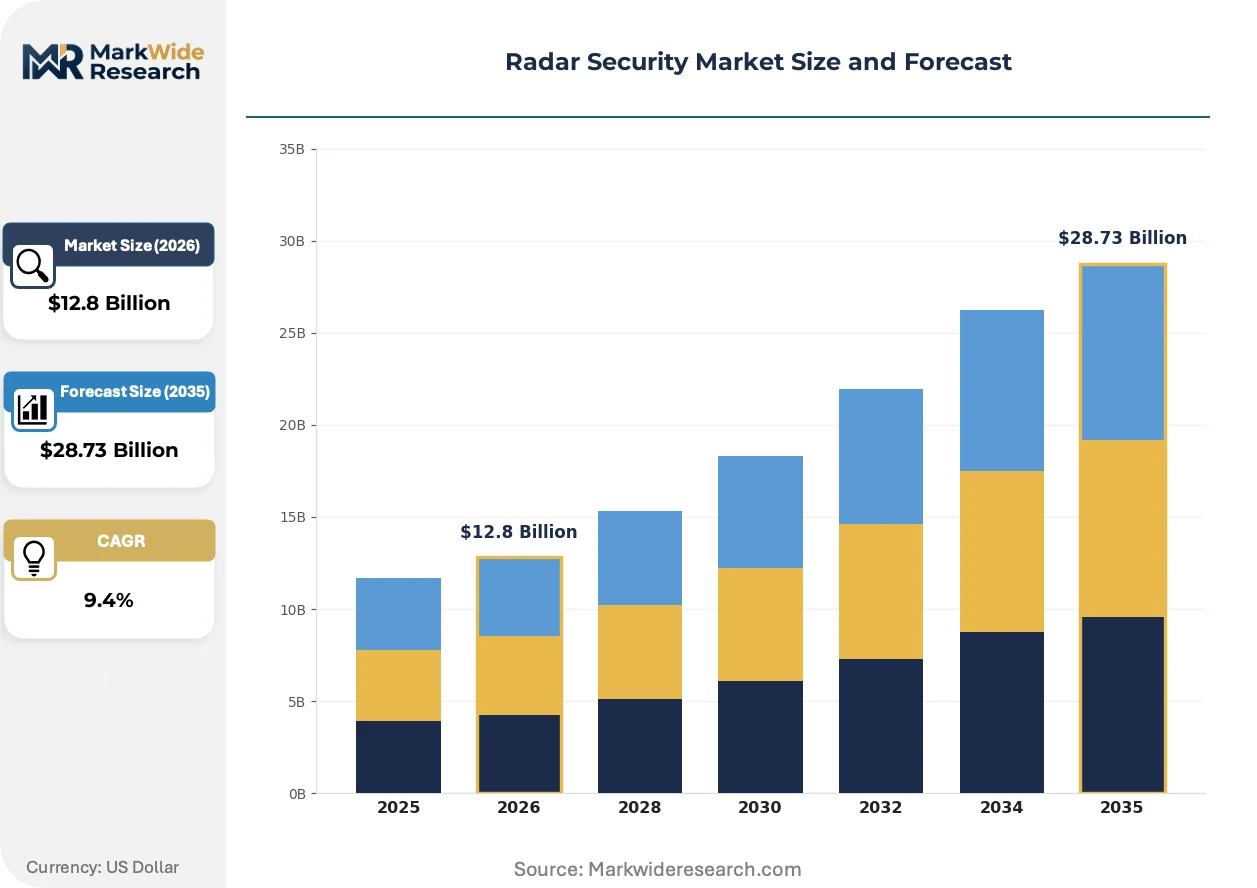
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pulse-Doppler Radar, Frequency Modulated Continuous Wave, Phased Array Radar, Synthetic Aperture Radar, Continuous Wave Radar Application: Perimeter Surveillance, Intrusion Detection, Asset Protection, Critical Infrastructure Monitoring, Border Security End User: Government Agencies, Commercial Enterprises, Defense Departments, Transportation Authorities, Event Management Firms Deployment: Fixed Installation, Mobile Units, Portable Devices, Networked Systems, Integrated Security Solutions |
| Companies Covered | RTX Corporation, Lockheed Martin, Thales Group, Northrop Grumman, BAE Systems, Leonardo S.p.A., Elbit Systems, L3Harris Technologies, Hensoldt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Security Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric performance to software-defined capabilities and system intelligence. This transition prioritizes adaptability, multi-layered data fusion, and countering asymmetric threats over raw detection range alone.
Phased Array Radar, with its electronically steered beams, provides superior multi-target tracking and rapid scanning capabilities compared to mechanically scanned antennas. Defense departments and critical infrastructure operators are rapidly adopting this technology for complex surveillance scenarios. The flexibility and software-defined nature of Phased Array technology is overtaking the single-function design of traditional radar systems, enabling dynamic threat response.
Interoperability mandates, such as NATO's STANAG 4609 for motion imagery or STANAG 4586 for UAV control, are influencing system design. These standards compel manufacturers to build systems with open architectures that can communicate across allied forces and with third-party platforms. The defense segment is most affected, with compliance becoming a prerequisite for participation in multinational procurement programs.
A move toward multi-vendor sourcing strategies is decoupling the purchase of radar hardware from system integration services. This disaggregation allows buyers to select best-in-class sensors, command-and-control software, and effector systems from different suppliers. This trend is most visible in large government tenders for border and coastal surveillance, where customization and avoiding vendor lock-in are priorities.
Radar Security Market Segmentation
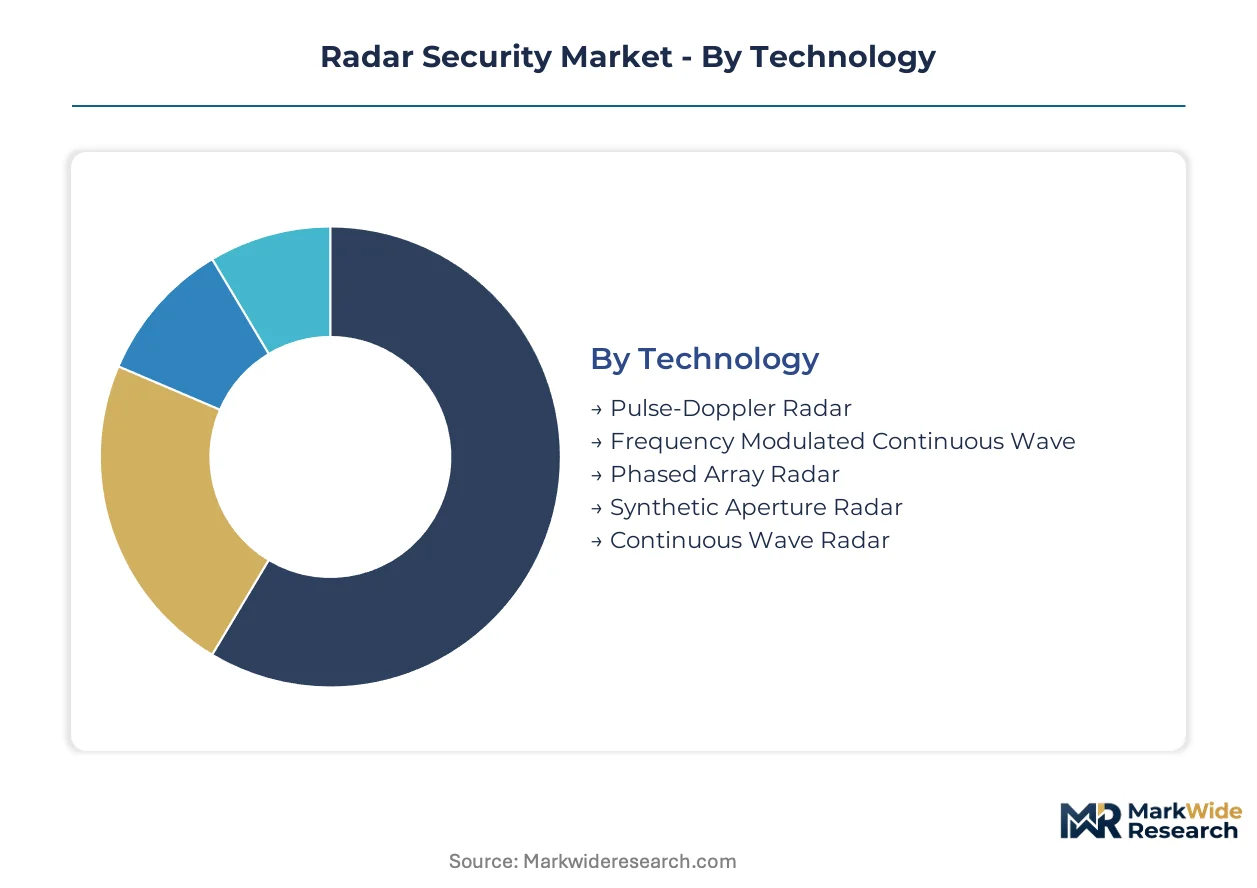
The Radar Security Market's segmentation reflects the diverse technological approaches, operational requirements, and end-user demands driving its expansion. Understanding these distinct segments is crucial for identifying areas of concentrated investment and emerging opportunities across the threat landscape.
Technology:
Supply concentration in radar security technology reflects specialized manufacturing capabilities for distinct operational requirements.
- Phased Array Radar:Electronically steered beams provide superior multi-target tracking and rapid scanning capabilities. Defense departments and critical infrastructure operators adopt this technology for complex surveillance in nations like India and Saudi Arabia.
- Pulse-Doppler Radar:Utilizes the Doppler effect to distinguish moving targets from stationary clutter, offering enhanced detection in complex environments. Transportation authorities employ these systems for air traffic control and vehicle monitoring.
- Frequency Modulated Continuous Wave:Employs continuous radio waves with varying frequency for precise short-range detection and altimetry.
- Synthetic Aperture Radar:Generates high-resolution images of ground surfaces from moving platforms, valuable for reconnaissance and mapping.
- Continuous Wave Radar:Transmits an uninterrupted radio signal, primarily used for measuring speed and range in simpler, cost-effective applications.
Pulse-Doppler Radar absorbs the bulk of installed capacity; Phased Array Radar is expanding most quickly.
Application:
The varied applications of radar security systems address distinct operational needs across diverse sectors.
- Border Security:Involves long-range detection and tracking of unauthorized crossings across national boundaries, often relying on persistent, all-weather networks. Heightened geopolitical tensions in Eastern Europe and South Asia are driving significant deployments.
- Critical Infrastructure Monitoring:Focuses on protecting vital assets like energy grids, transportation hubs, and public venues from physical threats and unauthorized access. Government mandates in nations like Saudi Arabia and India compel upgrades in this area.
- Perimeter Surveillance:Establishes virtual fences around designated areas, detecting movement and classifying objects entering or leaving.
- Intrusion Detection:Pinpoints unauthorized entry into restricted zones, often integrated with alarms and response systems for immediate action.
- Asset Protection:Safeguards high-value movable or stationary assets against theft or damage, particularly for commercial enterprises.
Demand for Perimeter Surveillance remains foundational, while Border Security shows significant upward momentum.
End User:
Customer types for radar security solutions range from national defense to private sector entities, each with unique procurement processes.
- Defense Departments:Constitute the largest end-user base, procuring advanced radar systems for national security, border protection, and military operations. Adherence to NATO STANAG standards is critical for interoperability among allied forces.
- Commercial Enterprises:Exhibit rapidly expanding demand for asset protection, particularly for private venues, corporate campuses, and event spaces. This segment seeks compact, lower-cost radar systems for drone detection.
- Government Agencies:Utilize radar for public safety, law enforcement, and critical infrastructure protection beyond direct defense applications.
- Transportation Authorities:Deploy radar for air traffic control, port security, and railway monitoring to ensure safe and efficient operations.
- Event Management Firms:Increasingly adopt radar for temporary security at large gatherings, detecting potential aerial threats like unauthorized drones.
Defense Departments represent the bedrock of the market, with Commercial Enterprises demonstrating robust expansion.
Deployment:
Deployment configurations vary significantly in complexity and cost, from standalone units to comprehensive integrated platforms.
- Integrated Security Solutions:Combine radar sensors with command-and-control software, effectors, and other security layers into a cohesive system. Southeast Asian infrastructure projects, such as new airports, create greenfield opportunities for these solutions.
- Fixed Installation:Involves permanently mounted radar systems at strategic locations for continuous, long-term surveillance. Critical infrastructure sites and national borders primarily utilize these robust, all-weather deployments.
- Mobile Units:Radar systems mounted on vehicles or vessels, providing flexible and responsive surveillance capabilities for dynamic environments.
- Portable Devices:Compact, easily transportable radar units for rapid deployment in temporary security zones or tactical scenarios.
- Networked Systems:Connect multiple radar units and sensors across a wide area, enabling comprehensive coverage and centralized threat assessment.
While Fixed Installation maintains its established presence, Integrated Security Solutions is rapidly gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for sophisticated radar security systems, driven by its extensive defense budget and critical infrastructure protection needs. This region, alongside other key global economies, exhibits varied adoption patterns influenced by geopolitical priorities and technological readiness.
United States
Defense spending and border security initiatives are primary demand drivers for advanced radar systems in the United States. The US FCC dictates spectrum allocation rules, influencing system design and deployment. Major defense contractors in Virginia and Maryland lead innovation in advanced radar technologies.
India
Government mandates for critical infrastructure upgrades and border surveillance modernization propel radar security procurement in India. The Indian government's "Make in India" initiative and defense procurement policies encourage domestic manufacturing. Bengaluru and Hyderabad serve as key hubs for defense R&D and manufacturing.
Saudi Arabia
Critical infrastructure mandates, particularly for energy facilities and urban security, drive significant investment in radar security within Saudi Arabia. Government directives for security upgrades compel operators to adopt advanced surveillance solutions. The NEOM project and Riyadh are focal points for large-scale security technology integration.
Germany
European border security requirements and defense modernization efforts under NATO commitments influence radar system demand in Germany. CE marking for emissions standards guides product development for market access. Bavaria, home to companies like Hensoldt, is a significant center for high-performance sensor technology development.
Japan
Maritime surveillance and defense modernization programs are key demand drivers for radar security systems across Japan. The Ministry of Economy, Trade and Industry (METI) supports advanced technology development, while strict export controls shape market participation. Tokyo's research institutions and Mitsubishi Electric's defense divisions contribute to radar innovation.
Radar Security Market Key Industry Players
Global majors compete with regional champions across the radar security market, creating a tiered competitive environment. The market structure exhibits a blend of consolidation among top-tier defense contractors and fragmentation among specialized sensor manufacturers. Three strategic archetypes define this space: integrated solution providers, high-performance sensor specialists, and advanced radar system developers. Portfolio diversification and strategic partnerships are dominant competitive moves among these players.
Specialists in advanced radar systems, such as RTX Corporation, exemplify innovation in aerospace and defense applications. Thales Group represents the comprehensive, integrated security solutions archetype, leveraging its broad technology portfolio. Hensoldt, a European-based firm, occupies a position as a high-performance sensor technology specialist, focusing on critical detection capabilities.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin |
| Thales Group |
| Northrop Grumman |
| BAE Systems |
| Leonardo S.p.A. |
| Elbit Systems |
| L3Harris Technologies |
| Hensoldt |
| Others |
Cost & Logistics Intelligence
Sovereign-backed defense contractors and large integrated solution providers dictate supply behavior and pricing discipline within the radar security market. Their significant R&D investments and long-term government contracts shape market dynamics.
Pricing Analysis
Warranty and service bundling often differentiates radar security solutions, with comprehensive packages unbundled for specific project requirements. Project-based and long-term contract pricing models dominate, especially for defense departments and critical infrastructure operators. Customization for specific threat profiles and adherence to NATO STANAG standards drive significant price differentiation. Pricing softness stems from government budget constraints and the shift towards multi-vendor sourcing strategies, while commercial enterprises exhibit higher price sensitivity compared to defense departments.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by defense procurement bodies, driving diversification in the radar security supply chain. Supply concentration for advanced radar systems centers on the United States, Germany, and Japan. The industry relies on specialized RF components and Gallium Nitride (GaN) semiconductors for high-performance transmitters. Complex export controls, such as US ITAR, represent a structural risk, while distribution runs primarily through direct sales to government agencies and large commercial enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radar security market is fundamentally a cost-of-compliance story, where adherence to standards like NATO STANAG creates a significant barrier-to-entry moat for new participants. This ensures interoperability but demands substantial investment.
For Market Incumbents: Deepen investments in AI and sensor fusion capabilities to maintain a technological edge against evolving aerial threats. Acquire specialized firms excelling in compact radar systems for commercial drone detection. This counters the threat posed by small, low-signature unmanned aerial vehicles. Prioritize R&D in Gallium Nitride (GaN) semiconductors for more compact and efficient system development.
For New Entrants and Emerging Players: Enter via the rapidly expanding commercial drone detection market by offering compact, lower-cost radar systems. Focus on protecting private venues and corporate campuses from unauthorized drone activity. Southeast Asian infrastructure projects present greenfield opportunities for integrated solutions, bypassing legacy system constraints. Develop modular, easily deployable solutions to simplify integration for commercial clients.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized sensor technology firms in Europe, particularly those with strong intellectual property in Phased Array Radar. The market exhibits long-term viability, driven by persistent defense spending and critical infrastructure protection needs over the next decade. Seek out agile system integrators capable of navigating complex interoperability requirements like NATO STANAG. Increased government mandates for critical infrastructure protection in nations like India and Saudi Arabia would signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-based Compact Radar Launch | This enables more powerful and efficient systems for mobile security applications, expanding commercial market reach. |
| AI Integration Partnerships | Collaborations with AI specialists enhance target classification and reduce false alarms for critical infrastructure monitoring. |
| Southeast Asian Market Entry | Targeting greenfield airport and seaport projects in Vietnam creates new opportunities bypassing legacy system constraints. |
| NATO STANAG Certification | Achieving this standard ensures interoperability for defense departments, unlocking multinational procurement programs for allied forces. |
| Acquisition of Drone Detection Specialist | Acquiring firms with expertise in countering small UAVs strengthens capabilities for commercial asset protection. |
Research Approach
Independent corroboration across defense procurement officers, critical infrastructure security managers, and radar engineers underwrites the qualitative findings. Primary insights stemmed from interviews with these stakeholders, alongside commercial security integrators. Secondary validation involved analyzing government defense budgets, FCC spectrum allocation records, and company annual reports. A combination of bottom-up and top-down approaches ensured robust data triangulation.
Rate-of-change decomposition quantifies market evolution across the analysis window, modeling key segment dynamics. The analytical framework considered technology, application, end-user, deployment, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future demand. Key inputs included defense spending trends and the proliferation rates of small unmanned aerial vehicles.
Revisions become necessary when significant geopolitical shifts or unexpected regulatory changes materialize, impacting market access. Forecasts reflect underlying assumptions regarding defense budgets and technological adoption rates. Deviation in geopolitical stability or spectrum allocation policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Destructible Security Labels Market