
 Alarm Monitoring [Central Stations] Software Market | 2026-2036
Alarm Monitoring [Central Stations] Software Market Size, Share, and Industry Trends Forecast 2026-2036
Alarm Monitoring [Central Stations] Software Market Outlook
Buyer concentration among multi-site commercial security providers is restructuring procurement patterns across the alarm monitoring software sector. Successware leverages its vertical specialization in central station workflows to sustain recurring revenue from enterprise accounts. MKS Systems anchors its position through deep integration with legacy hardware ecosystems. SureView competes on real-time video verification capabilities that reduce false dispatch rates for municipal clients.
Alarm Monitoring [Central Stations] Software encompasses command-center applications that process signals from intrusion, fire, and environmental sensors, typically requiring 99.999% uptime architectures with sub-15-second alarm processing latency. The primary commercial purpose centers on converting raw sensor events into validated dispatch decisions that minimize liability exposure for monitoring operators. Cloud-based platforms capture the fastest expansion as central stations abandon capital-intensive server farms for subscription scalability. On-premises solutions retain dominance in government agency deployments where data sovereignty requirements block external hosting. Hybrid systems occupy a narrowing middle ground as bandwidth infrastructure matures in developed markets.
UL standards in the United States mandate redundant signal paths and automated failover protocols that elevate software certification costs for entrants. FCC Part 90 regulations governing radio-frequency alarm transmissions constrain protocol choices for cellular and mesh backup channels. ETSI compliance frameworks in Europe impose encryption standards that fragment product development across Atlantic markets. Stakeholders must weigh cloud migration timelines against the operational risk of stranding on-premises technical debt as subscriber expectations shift toward mobile-first interfaces.
Market Dynamics
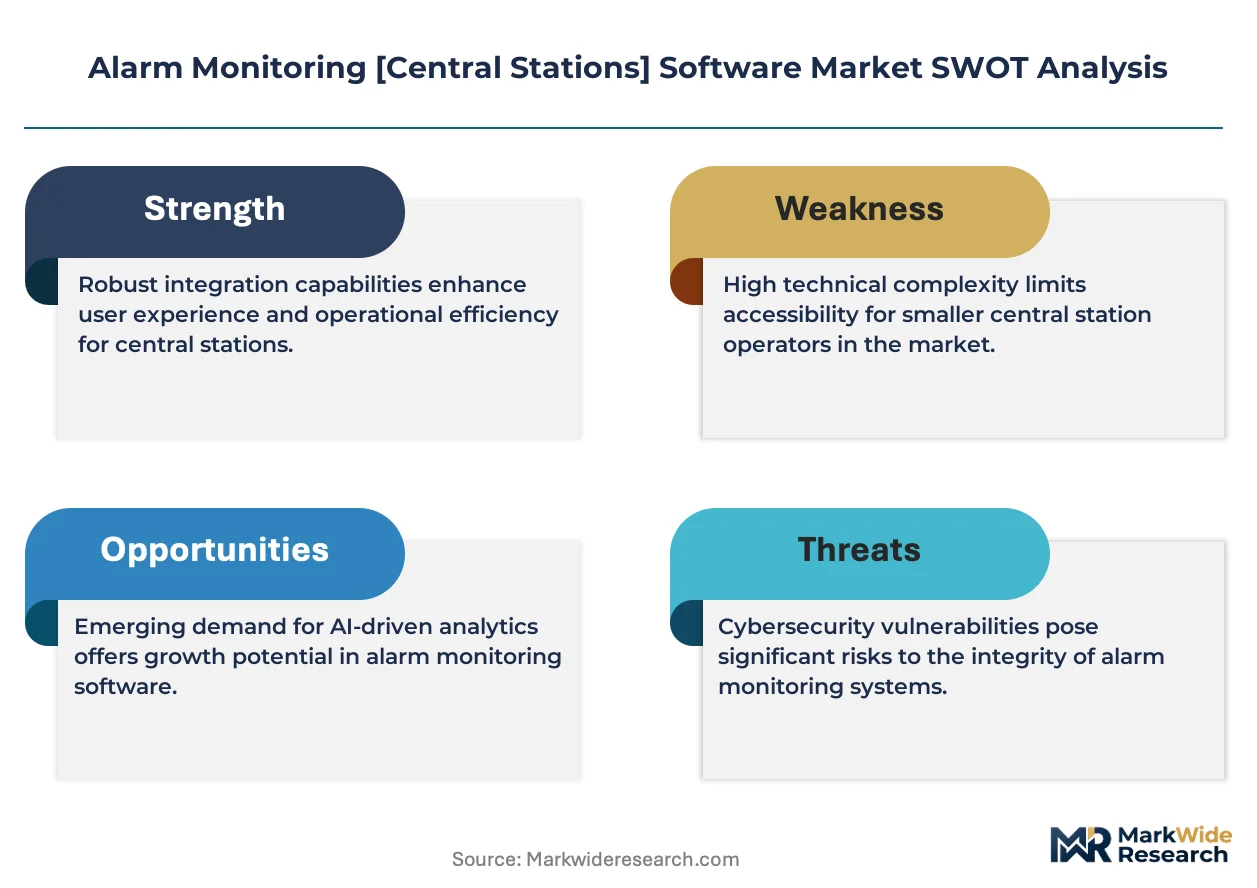
Cloud migration is compressing capital deployment cycles for central station operators while UL 827 certification mandates force redundant infrastructure investments that favor established software vendors with compliance track records.
Growth Catalysts
- UL 827 Redundancy Mandates:North American central stations must maintain dual-path signal routing and automated failover systems, forcing legacy hardware replacements and software procurement from certified vendors.
- Cellular Mesh Backup Protocols:FCC Part 90 radio-frequency regulations are accelerating adoption of encrypted cellular and mesh network alternatives to traditional POTS lines for alarm transmission reliability.
- Multi-Site Commercial Portfolios:Consolidated security providers operating across distributed real estate assets are standardizing on unified monitoring platforms to reduce per-site operational overhead.
Market Restraints
- Certification Cost Barriers:UL and ETSI compliance testing for redundant architectures imposes six-figure validation expenses that exclude emerging software vendors from enterprise procurement shortlists.
- Legacy Hardware Entrenchment:Central stations with sunk investments in on-premises server farms face technical debt stranding risks as bandwidth infrastructure matures and cloud alternatives achieve parity.
- Data Sovereignty Fragmentation:Government agency deployments in Germany and Japan remain blocked from external hosting by national security frameworks, constraining addressable market for pure-cloud platforms.
Strategic Opportunities
- AI-Enabled Video Verification:Machine learning convergence with real-time video analytics is creating white space for platforms that reduce false dispatch rates below municipal police department thresholds.
- Mobile-First Interface Expectations:Subscriber demand for smartphone-accessible alarm status and arming controls is opening channel innovation for white-label consumer applications.
- Hybrid Deployment Architectures:Edge-computing gateways that process sensor data locally before cloud transmission address latency requirements for fire alarm systems while satisfying data residency constraints.
Industry Challenges
- Specialized Technician Scarcity:Central stations face acute shortages of engineers qualified in both legacy panel integration and cloud-native platform administration.
- Protocol Standardization Delays:Competing encrypted transmission standards between cellular carriers and mesh network providers complicate multi-vendor interoperability testing.
- Integration Complexity:Middleware development for bridging 1990s-era contact ID protocols with modern REST APIs consumes disproportionate R&D resources relative to feature differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alarm Monitoring [Central Stations] Software Market |
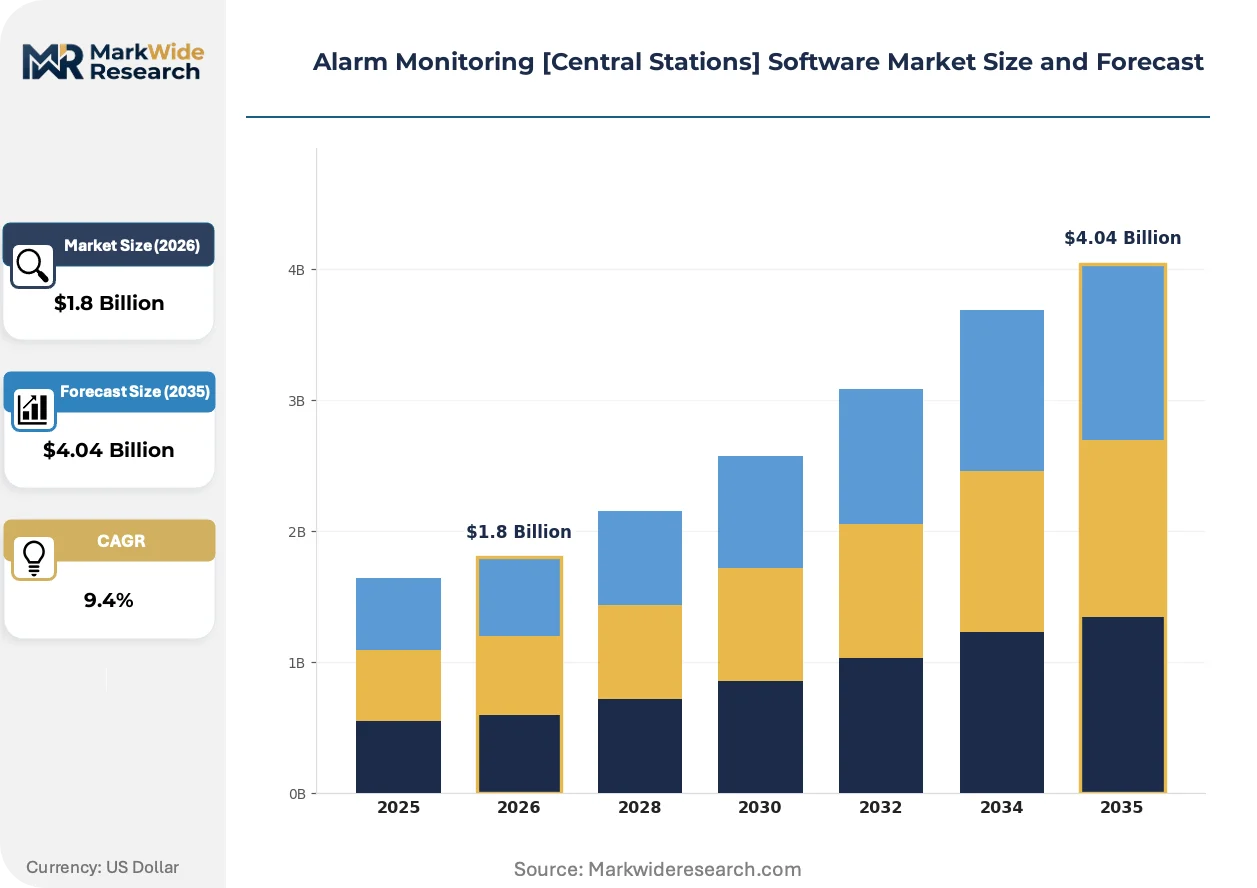
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hosted Solutions, On-Premises Solutions, Cloud-Based Platforms, Hybrid Systems End User: Residential Customers, Commercial Buildings, Industrial Facilities, Government Agencies Installation: DIY Installation, Professional Installation, Remote Monitoring, Self-Monitoring Service Type: Monitoring Services, Maintenance Services, Technical Support, System Integration |
| Companies Covered | Successware, Digimatrix, SureView, MKS Systems, Alcensoft, iViewNow, AlarmBase, Patriot Systems, Connectio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alarm Monitoring [Central Stations] Software Market Strategic Shifts
Real-time video verification is compressing dispatch decision timelines while artificial intelligence integration and mobile-native interfaces are redefining operator workflows across central station architectures.
AI-powered video analytics is electrifying alarm validation workflows by overlaying object detection on live camera feeds to distinguish actual intrusion events from environmental false triggers. Municipal police departments in the United States are mandating such verification before dispatch response. The technology is compressing liability exposure for monitoring operators while elevating platform stickiness.
FCC Part 90 radio-frequency regulations are constraining cellular backup channel selections for alarm transmissions, forcing software vendors to certify across multiple carrier networks. Central stations must maintain redundant paths under UL standards, complicating procurement decisions. European ETSI encryption requirements fragment product development, compelling Atlantic market specialization.
Subscription-based platform economics are displacing perpetual license models as central stations abandon capital-intensive server deployments. Multi-site commercial security providers favor operational expenditure structures aligned with recurring revenue forecasting. Germany and Japan exhibit strongest resistance due to legacy infrastructure amortization schedules and data sovereignty preferences.
Alarm Monitoring [Central Stations] Software Market Segmentation
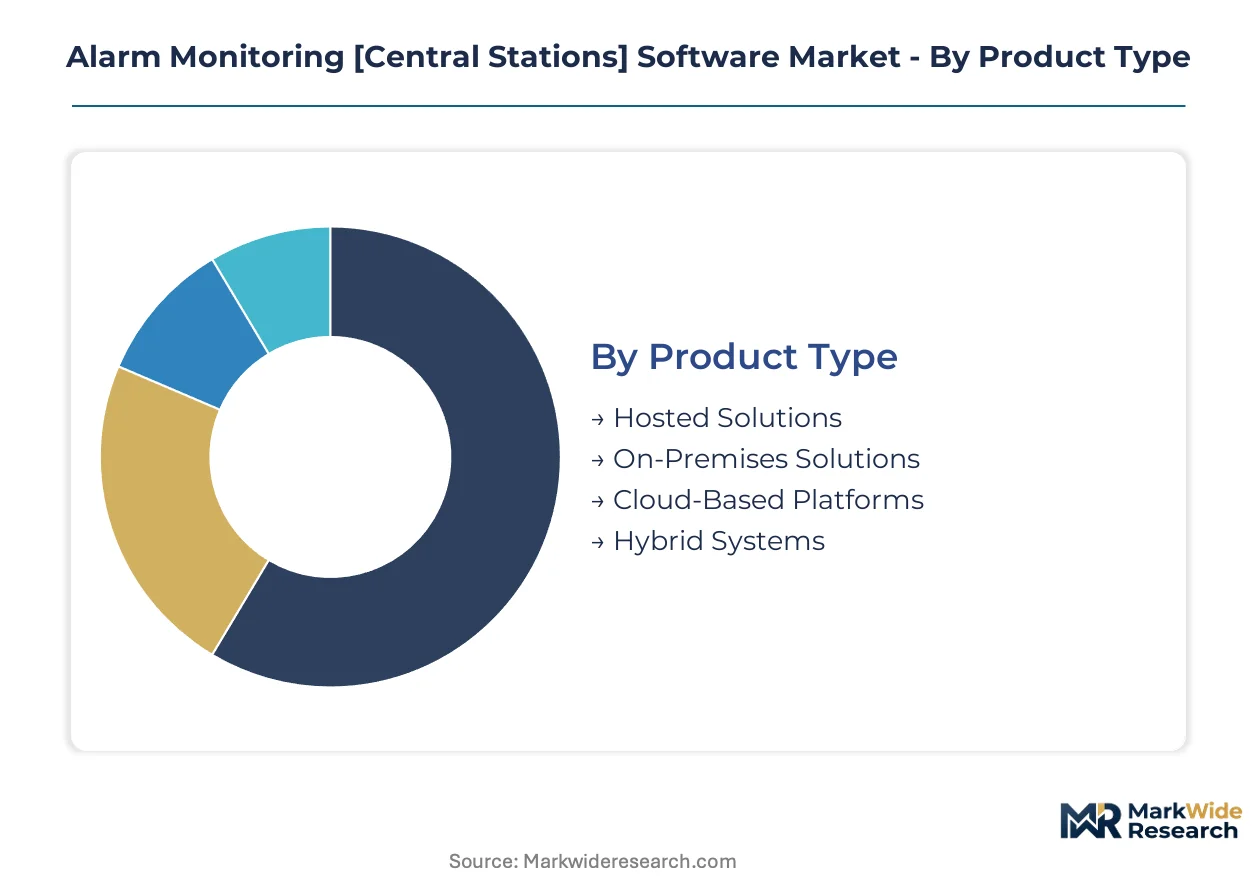
Segmentation in alarm monitoring software reveals how deployment architectures, user requirements, and service models create distinct procurement patterns. Each dimension exposes different cost structures, compliance burdens, and integration complexity that shape vendor competitive positioning.
Product Type:
Standalone platforms dominate enterprise central stations while embedded modules serve smaller operators with limited IT resources.
- Hosted Solutions:Third-party managed infrastructure delivers 99.999% uptime SLAs through geographically distributed data centers. Demand clusters among mid-sized central stations in Germany seeking to avoid capital expenditure without surrendering data sovereignty.
- On-Premises Solutions:Local server deployments retain full operational control over alarm processing pipelines and encryption key management. Government agencies in Japan mandate these configurations under national cybersecurity frameworks that prohibit external data transmission.
- Cloud-Based Platforms:Native SaaS architectures enable elastic scaling during demand spikes from severe weather events or security incidents.
- Hybrid Systems:Edge gateways process latency-critical fire alarms locally while non-urgent events transmit to cloud analytics engines.
Volume placements concentrate in On-Premises Solutions; the faster expansion belongs to Cloud-Based Platforms.
End User:
Cost tier differentiation separates premium compliance-grade deployments from economy self-service configurations.
- Commercial Buildings:Multi-site portfolios require unified dashboards spanning intrusion, fire, and environmental monitoring across distributed assets. UL 827 certification mandates drive procurement from vendors with proven redundant failover implementations in the United States.
- Government Agencies:Classified facility monitoring demands air-gapped networks with hardware security modules and audited access logs. Defense installations in the United States and critical infrastructure operators in Japan represent the most stringent requirement profiles.
- Residential Customers:Smartphone-centric interfaces and simplified arming/disarming workflows dominate purchasing criteria.
- Industrial Facilities:Integration with SCADA systems and hazardous area compliance expands software scope beyond conventional security applications.
Commercial Buildings generate the highest absolute deployment volumes; Government Agencies command the steepest expansion trajectory as critical infrastructure protection budgets accelerate.
Installation:
Customer technical sophistication determines whether vendors capture margin through professional services or scale through automated provisioning.
- Professional Installation:Certified technicians configure panel integrations, test signal paths, and validate UL compliance documentation. Commercial central stations in the United States require these deployments to satisfy insurance underwriting requirements.
- Remote Monitoring:Central station operators manage subscriber systems through persistent VPN connections enabling firmware updates and diagnostic polling.
- DIY Installation:Pre-configured hardware kits with QR-code provisioning reduce activation friction for residential subscribers.
- Self-Monitoring:Direct-to-smartphone alerting bypasses central station fees entirely, appealing to cost-sensitive residential segments.
Professional Installation retains the largest installed base; Remote Monitoring is climbing the fastest as bandwidth infrastructure matures.
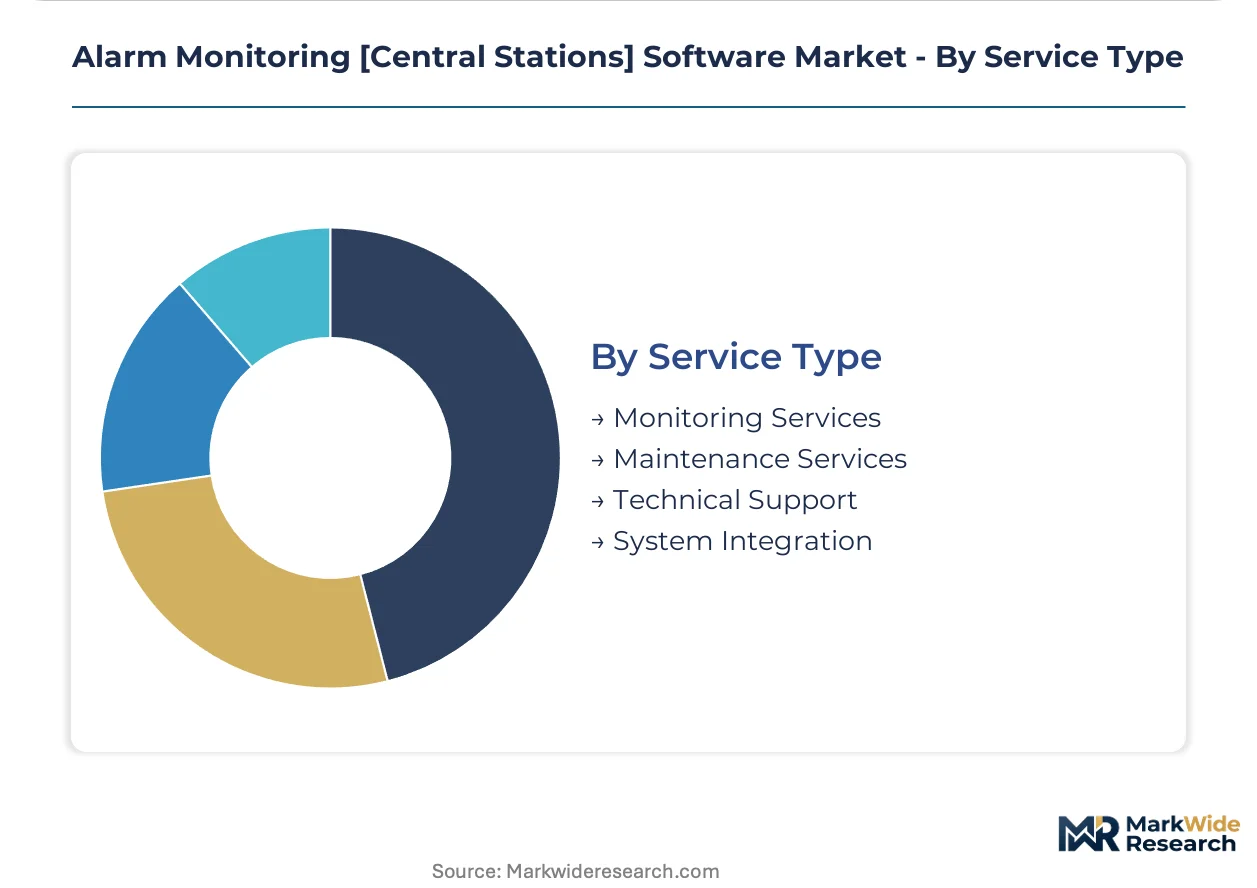
Service Type:
Margin structure varies dramatically between recurring monitoring revenue and episodic technical interventions.
- Monitoring Services:Per-subscriber monthly fees generate predictable cash flows with 85%+ gross margins for established central stations. Municipal police verification requirements in the United States are elevating video-analytics-enabled tiers above basic signal relay.
- System Integration:Custom middleware development bridges legacy contact ID protocols with modern REST APIs and cloud data lakes. Enterprise security providers operating across mixed-vendor hardware estates require these services most intensively.
- Maintenance Services:Preventive hardware inspections and battery replacement scheduling extend subscriber lifetime value.
- Technical Support:Tiered response SLAs separate premium enterprise accounts from standard commercial coverage.
Monitoring Services dominate recurring revenue composition; System Integration is gaining share fastest as legacy modernization cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's data center corridors anchor North American cloud infrastructure deployment for central station platforms. Frankfurt's financial district drives redundant failover demand. Tokyo's dense urban monitoring networks shape latency requirements.
United States
Multi-site commercial security providers and municipal police verification mandates propel software procurement. FCC Part 90 radio-frequency regulations constrain cellular backup channel selections for alarm transmissions. Dallas-Fort Worth's central station cluster sees rapid cloud migration as bandwidth infrastructure matures.
Germany
Industrial facility monitoring and data sovereignty preferences sustain on-premises solution demand. ETSI encryption standards impose compliance burdens that fragment Atlantic product development. Bavaria's manufacturing belt resists external hosting under national cybersecurity frameworks.
Japan
Government agency deployments and critical infrastructure protection budgets accelerate stringent requirement profiles. METI cybersecurity guidelines mandate air-gapped networks for classified facilities. Tokyo-Yokohama's dense metropolitan monitoring networks prioritize sub-15-second alarm processing latency.
United Kingdom
Commercial building portfolios and insurance underwriting requirements drive professional installation services. GDPR data residency rules complicate cloud platform adoption for sensitive deployments. London's financial district demands unified dashboards spanning intrusion, fire, and environmental monitoring.
Canada
Remote monitoring expansion and bandwidth infrastructure maturation enable distributed central station architectures. Health Canada cybersecurity guidance influences government procurement specifications. Toronto-Waterloo's technology corridor attracts SaaS platform development for North American markets.
Alarm Monitoring [Central Stations] Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-enabled verification niches. The vendor base concentrates around three tiers: legacy hardware-integrated incumbents, cloud-native challengers, and vertical specialists. Strategic archetypes include UL certification-track incumbents, mobile-first interface innovators, and hybrid deployment architects. Competitive moves center on redundant infrastructure partnerships and middleware modernization capabilities.
Within the vertical specialization tier, Successware and MKS Systems exemplify divergent positioning strategies. SureView occupies a position among video verification specialists. These three entities anchor the competitive spectrum from legacy integration to real-time analytics, representing how procurement patterns split between compliance-grade reliability and innovation-driven feature sets.
| Leading Market Players |
|---|
| Successware |
| Digimatrix |
| SureView |
| MKS Systems |
| Alcensoft |
| iViewNow |
| AlarmBase |
| Patriot Systems |
| Connectio |
| Others |
Value Chain & Pricing Dynamics
Multi-site commercial security providers consolidating procurement across distributed portfolios are squeezing vendor margins and forcing supply chain reconfigurations toward subscription-ready fulfillment models. UL 827 certification mandates for redundant failover systems elevate compliance costs that concentrate pricing power among established software vendors with proven certification track records.
Pricing Analysis
Warranty and service bundling separates premium tiers from stripped-down SaaS offerings, with UL-certified redundant architectures commanding sustained premiums over basic signal relay packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic deployment complexity, with government agencies in Japan and Germany showing lowest price sensitivity due to data sovereignty requirements. Pricing pressure stems from cellular carrier competition for backup channel contracts under FCC Part 90 constraints. DIY residential segments exhibit highest price sensitivity, driving unbundled self-monitoring alternatives.
Supply Chain Analysis
Freight and logistics costs for edge-computing gateway hardware concentrate supply chain leverage in Taiwan, South Korea, and China, where semiconductor fabrication and electronics assembly clusters dominate. Cloud infrastructure provisioning draws from hyperscaler data center networks in the United States, Germany, and Japan, with raw material dependencies spanning silicon wafers, rare earth magnets for sensors, and lithium battery cells. Single-source vulnerability in cellular modem chipsets creates procurement risk for redundant signal path compliance. Distribution runs through certified systems integrators and direct-to-central-station vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UL 827 certification bottlenecks constrain vendor capacity expansion, propping pricing premiums for compliant architectures and creating supply-constrained procurement queues for enterprise central stations.
For Market Incumbents: Deepen vertical specialization in video verification analytics to defend against AI-native challengers encroaching on municipal police verification contracts. Anchor capacity expansion in Dallas-Fort Worth and Frankfurt data center corridors to capture cloud migration demand while maintaining UL certification continuity. Fortify middleware development capabilities to bridge legacy contact ID protocols with modern REST APIs, as integration complexity remains the primary switching cost for enterprise accounts. For New Entrants and Emerging Players: White-label mobile application channels offer the most penetrable route into residential self-monitoring segments underserved by incumbent central station workflows. Target mid-sized German commercial operators seeking hosted solutions that satisfy data sovereignty without capital-intensive on-premises deployment. Pursue partnership-based go-to-market models with cellular carriers seeking FCC Part 90 compliant software certification to accelerate market access. For Investors and Strategic Acquirers: The window for entry favors hybrid deployment architects with proven edge-to-cloud latency optimization and existing UL 827 compliance documentation. Long-term viability hinges on consolidation plays that aggregate certification assets and subscriber bases across fragmented regional operators. Monitor municipal police department verification mandate adoption curves as the primary inflection signal for video-analytics platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Video Verification Integration | Municipal police departments in the United States mandate verification before dispatch response. |
| Hybrid Deployment Architecture Development | Edge gateways address fire alarm latency requirements while satisfying Japan METI data residency constraints. |
| Cellular Mesh Backup Certification | FCC Part 90 compliance enables redundant signal paths required under UL 827 standards. |
| Mobile-First Interface Launch | Smartphone-centric subscriber controls open white-label consumer application revenue streams. |
| Middleware Modernization Acquisition | Legacy contact ID protocol bridges reduce R&D drain and accelerate enterprise account switching. |
Study Parameters
Multi-period observation of central station procurement patterns, UL certification timelines, and cellular backup protocol adoption anchored the trend analysis, supplemented by interviews with central station operators, software platform engineers, UL compliance auditors, and municipal police dispatch administrators. Secondary validation drew from FCC Part 90 regulatory filings, ETSI encryption standard documentation, SEC 10-K disclosures from listed security technology providers, and hyperscaler data center expansion announcements. Bottom-up subscriber volume estimates triangulated against top-down central station capacity assessments.
The input-output matrix framework modeled deployment architecture, end-user vertical, installation complexity, and service type segmentation across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves incorporating bandwidth infrastructure maturation rates and regulatory compliance deadline clustering. Industry-specific forecast inputs included UL 827 certification queue lengths and cellular carrier network expansion capex disclosures.
Inputs from central station operator interviews and regulatory filing databases were available through the study window; gaps in real-time cloud migration cost data and proprietary subscriber churn rates introduce uncertainty bands around elasticity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Security Services Market
Security and Surveillance
Home Security Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Home Security Solution Market