
 North America Cargo and Vehicle Screening Market | 2026-2036
North America Cargo and Vehicle Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cargo and Vehicle Screening Market Insights
Software-defined threat detection is hardening the revenue profile of North American screening vendors. L3Harris Technologies leverages its defense electronics heritage to sustain long-term service contracts with U.S. federal agencies. Smiths Detection Group Ltd anchors its position through deep integration of computed tomography platforms into customs workflows. Rapiscan Systems competes aggressively on port infrastructure modernization across Canadian maritime gateways.
Cargo and vehicle screening encompasses integrated inspection systems that employ X-ray transmission, gamma-ray imaging, and millimeter-wave sensing to detect contraband, explosives, and radioactive materials in commercial freight and passenger vehicles. Typical fixed-site installations process 200-400 trucks per hour at 3-6 MeV energy levels, with computed tomography systems generating volumetric reconstructions for automated anomaly flagging. X-Ray Scanners dominate installed base value due to decades of regulatory certification and operator training standardization, while Millimeter Wave technology represents the fastest-expanding segment as non-invasive under-vehicle inspection gains traction at high-throughput land borders. Portable Installation configurations are capturing disproportionate interest from event security operators and temporary checkpoint deployments.
U.S. Customs and Border Protection mandates drive product certification requirements under the Department of Homeland Security's SAFETY Act framework, while Transport Canada enforces parallel standards through its Transport of Dangerous Goods regulations. The U.S. FDA maintains oversight of radiation-emitting screening equipment under 21 CFR 1020, creating dual compliance pathways for manufacturers. Stakeholders must weigh the trade-off between AI-enabled autonomous screening capabilities and the regulatory latency of certifying machine-learning threat libraries for operational deployment.
Market Dynamics
AI-driven threat detection algorithms are compressing operator decision cycles at high-throughput border crossings, forcing vendors to restructure service delivery models around real-time algorithm updates rather than static hardware certification cycles.
Growth Catalysts
- Customs-Trade Partnership Against Terrorism:The U.S. Department of Homeland Security program mandates tiered security protocols that accelerate procurement of automated inspection systems at commercial ports of entry.
- Cross-border freight volume concentration:The U.S.-Mexico border corridor processes rising commercial truck traffic that demands throughput rates above 300 vehicles per hour at primary inspection lanes.
- Computed tomography platforms:Volumetric reconstruction capabilities enable automated anomaly flagging that reduces manual secondary inspection rates and labor costs at land borders.
Market Restraints
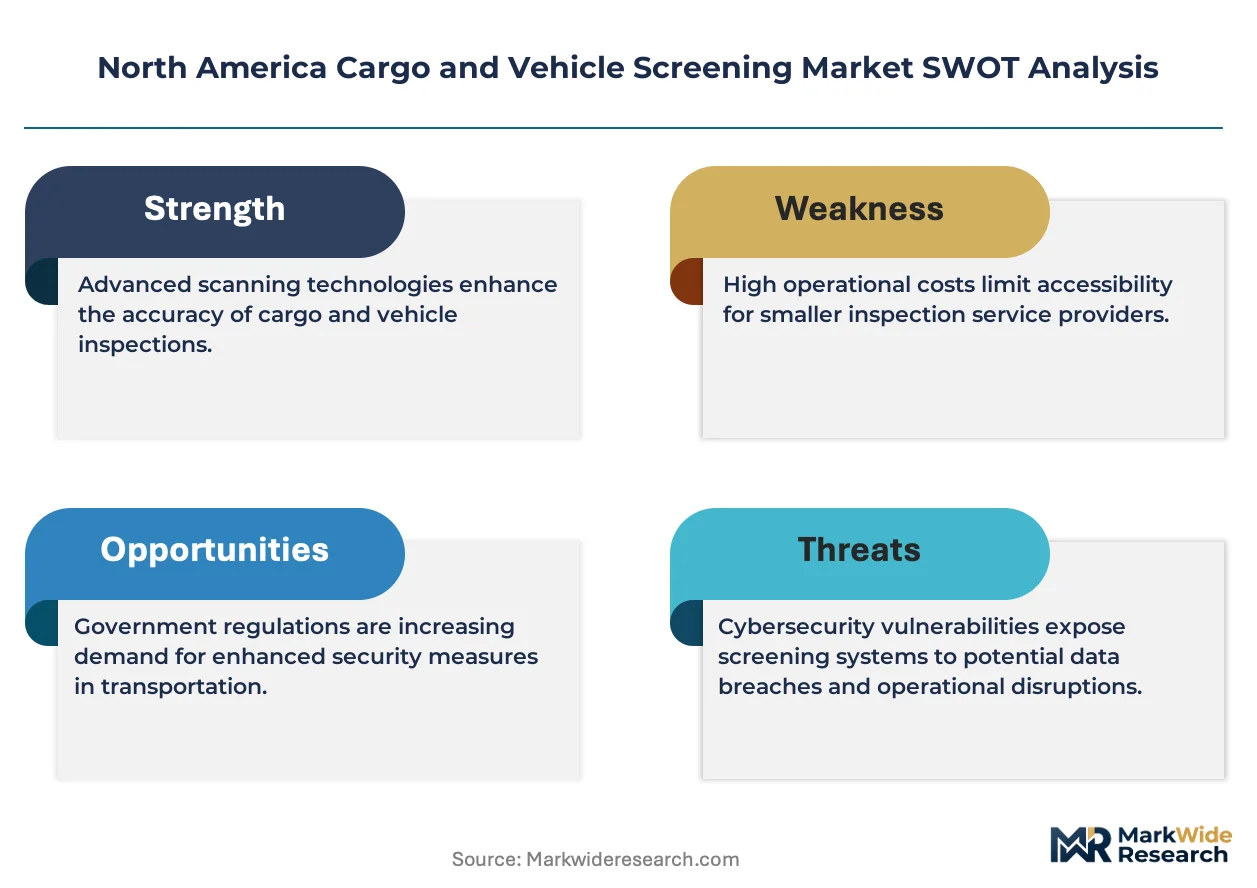
- SAFETY Act certification latency:The U.S. Department of Homeland Security framework requires extensive operational testing that extends product approval timelines to 18-24 months for new screening technologies.
- High-purity detector crystal supply:Cadmium zinc telluride and sodium iodide detector materials concentrate among limited specialty chemical suppliers, creating input cost volatility and allocation risk.
- Gamma-ray system substitution:X-ray transmission systems with 6 MeV linear accelerators achieve comparable material discrimination at lower regulatory compliance burden for non-radioactive threat detection.
Strategic Opportunities
- Canadian maritime gateway modernization:Port infrastructure expansion at Vancouver and Halifax creates demand for integrated vehicle and container screening systems with customs workflow integration.
- 21 CFR 1020 dual pathway:The U.S. FDA radiation-emitting equipment framework enables manufacturers to pursue parallel certification tracks that accelerate deployment timelines.
- Millimeter-wave under-vehicle sensing:Non-invasive inspection technology converges with automated license plate recognition to create unified screening architectures for high-throughput land borders.
Industry Challenges
- Machine-learning threat library validation:AI-enabled autonomous screening requires extensive false-positive rate testing that extends operational certification timelines beyond traditional hardware-only systems.
- Legacy analog system integration:Existing 3 MeV X-ray installations at older port-of-entry facilities require costly retrofitting to interface with digital threat detection networks and centralized monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cargo and Vehicle Screening Market |
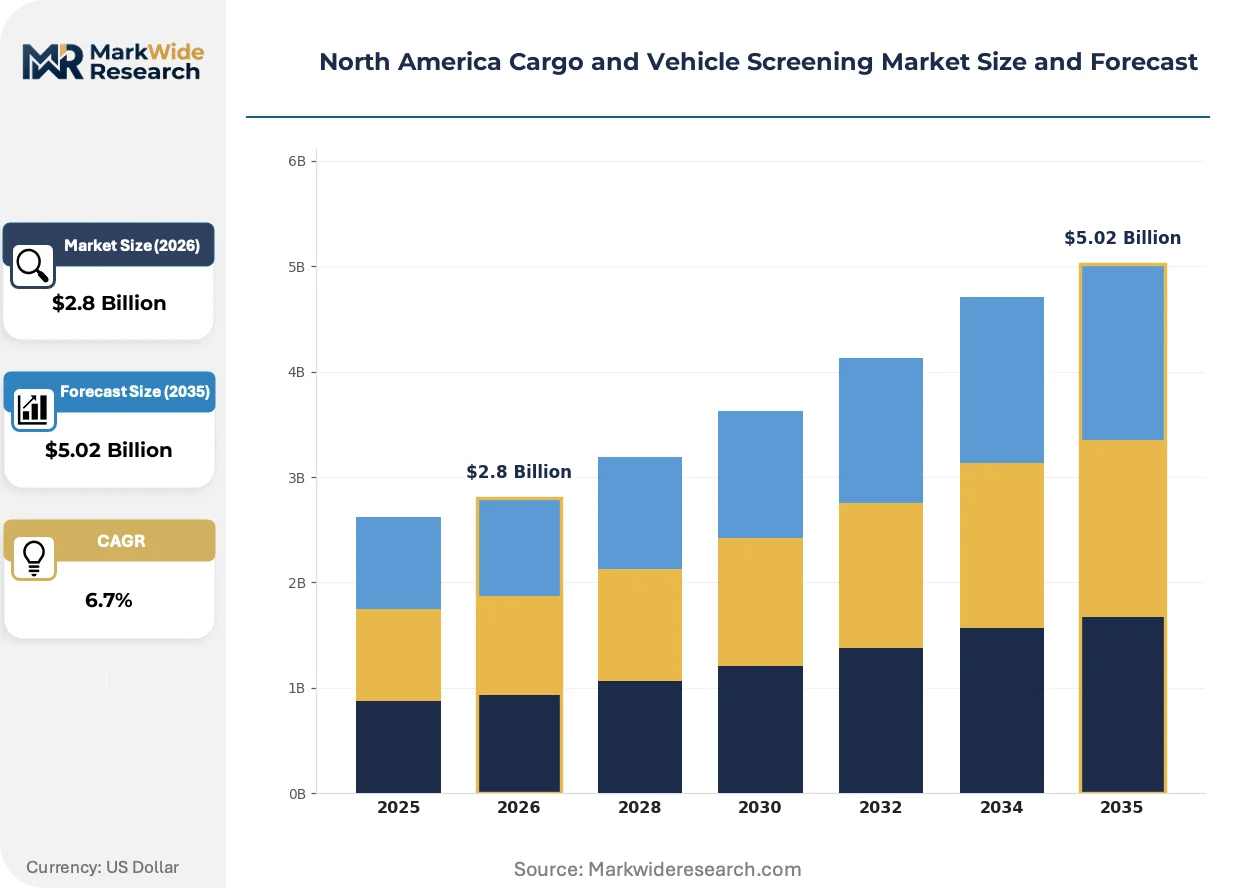
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Scanners, Mobile Screening Units, Explosive Detectors, Radiation Detectors End User: Transport Authorities, Customs Agencies, Military, Event Organizers Technology: Computed Tomography, Millimeter Wave, Laser Scanning, Image Processing Installation: Fixed Site, Portable, Temporary, Permanent |
| Companies Covered | Nuctech Company Limited, L3Harris Technologies, Rapiscan Systems, Vantage Security, LINEV Systems, Smiths Detection Group Ltd, OSI Systems, UVeye Inc, Leidos Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cargo and Vehicle Screening Market Trends and Innovations
Software-defined detection architectures are displacing hardware-centric product strategies across North American screening procurement, compressing vendor margins on equipment sales while expanding recurring revenue from algorithm subscriptions and threat library updates.
Millimeter-wave sensing arrays are expanding into under-vehicle inspection applications at land border crossings. U.S. Customs and Border Protection field offices are piloting these systems at Arizona and Texas corridor checkpoints to achieve sub-30-second inspection cycles. The technology is expanding into service contracts that bundle hardware, software updates, and operator training into multi-year agreements.
The U.S. FDA maintains dual compliance oversight under 21 CFR 1020 for radiation-emitting screening equipment alongside Department of Homeland Security SAFETY Act certification. Manufacturers face overlapping validation requirements that extend product launch timelines. Transport Canada enforces parallel Transport of Dangerous Goods regulations that create additional certification burden for vendors seeking unified North American product platforms.
Service unbundling is reshaping procurement patterns among federal and state border agencies. Traditional capital purchase models for fixed-site installations are giving way to performance-based contracts where vendors retain system ownership and charge per-inspection fees. This shift is most visible at temporary checkpoint deployments and event security operations where portable configurations dominate demand.
North America Cargo and Vehicle Screening Market Segmentation
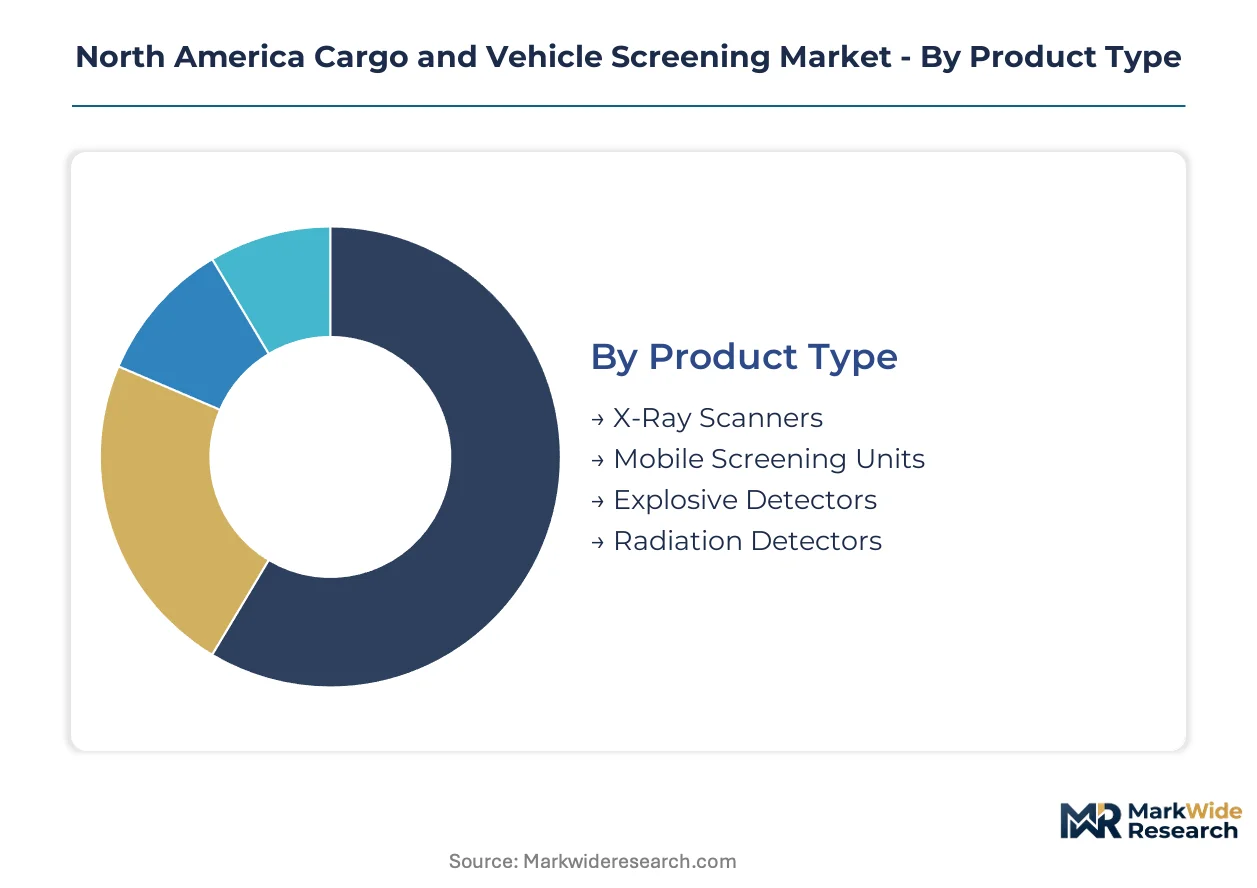
Segmentation in cargo and vehicle screening reveals how procurement priorities diverge between throughput-maximizing infrastructure and threat-specific detection capabilities. Understanding these splits enables vendors to align R&D investment with the operational constraints of border agencies, military logistics commands, and temporary checkpoint operators.
Product Type:
Standardization dominates high-volume land borders while customization prevails in threat-specific applications requiring modular sensor configurations.
- X-Ray Scanners:Fixed-site linear accelerator systems operate at 3-6 MeV energy levels to penetrate dense commercial freight. U.S. Customs and Border Protection deploys these at the U.S.-Mexico border corridor where 200-400 trucks per hour demand certified throughput rates.
- Mobile Screening Units:Self-contained trailer-mounted platforms integrate power generation, climate control, and radiation shielding for rapid redeployment. Canadian maritime gateways at Vancouver and Halifax procure these for surge capacity during container volume spikes.
- Explosive Detectors:Ion mobility spectrometry and chemiluminescence sensors trace vapor and particulate residues at checkpoint secondary inspection lanes.
- Radiation Detectors:Cadmium zinc telluride and sodium iodide scintillation arrays identify gamma and neutron signatures in commercial traffic streams.
Most installed capacity flows through X-Ray Scanners. Expansion is steepest in Mobile Screening Units.
End User:
Volume concentration sits with federal border agencies while margin capture shifts toward military and event security contracts demanding rapid deployment expertise.
- Transport Authorities:State and provincial departments of transportation enforce commercial vehicle safety compliance at weigh stations and inspection facilities. California and Texas DOTs are retrofitting legacy weigh stations with automated screening interfaces.
- Customs Agencies:U.S. Customs and Border Protection and Canada Border Services Agency mandate SAFETY Act and Transport of Dangerous Goods certification respectively. These agencies drive procurement through the Customs-Trade Partnership Against Terrorism program requirements.
- Military:Theater logistics commands require hardened platforms for forward operating base perimeter security and convoy screening.
- Event Organizers:Temporary checkpoint operators at sporting venues and political summits demand rapid-install configurations with minimal site preparation.
Procurement volume concentrates with Customs Agencies. Technology refresh rates run highest among Event Organizers.
Technology:
Maturity gradients separate legacy imaging modalities from emerging sensor fusion architectures requiring algorithmic certification.
- Computed Tomography:Volumetric reconstruction generates three-dimensional density maps enabling automated anomaly flagging without physical cargo disruption. U.S. port-of-entry modernization programs are accelerating deployment at land border primary inspection lanes.
- Millimeter Wave:Non-invasive under-vehicle inspection arrays achieve sub-30-second scan cycles at Arizona and Texas corridor checkpoints. The technology converges with automated license plate recognition for unified screening workflows.
- Laser Scanning:Lidar-based dimensional profiling verifies container manifest declarations against physical cargo configurations.
- Image Processing:Convolutional neural networks and deep learning classifiers automate threat recognition across heterogeneous sensor feeds.
Deployment scale favors Computed Tomography. Capability investment tilts toward Millimeter Wave.
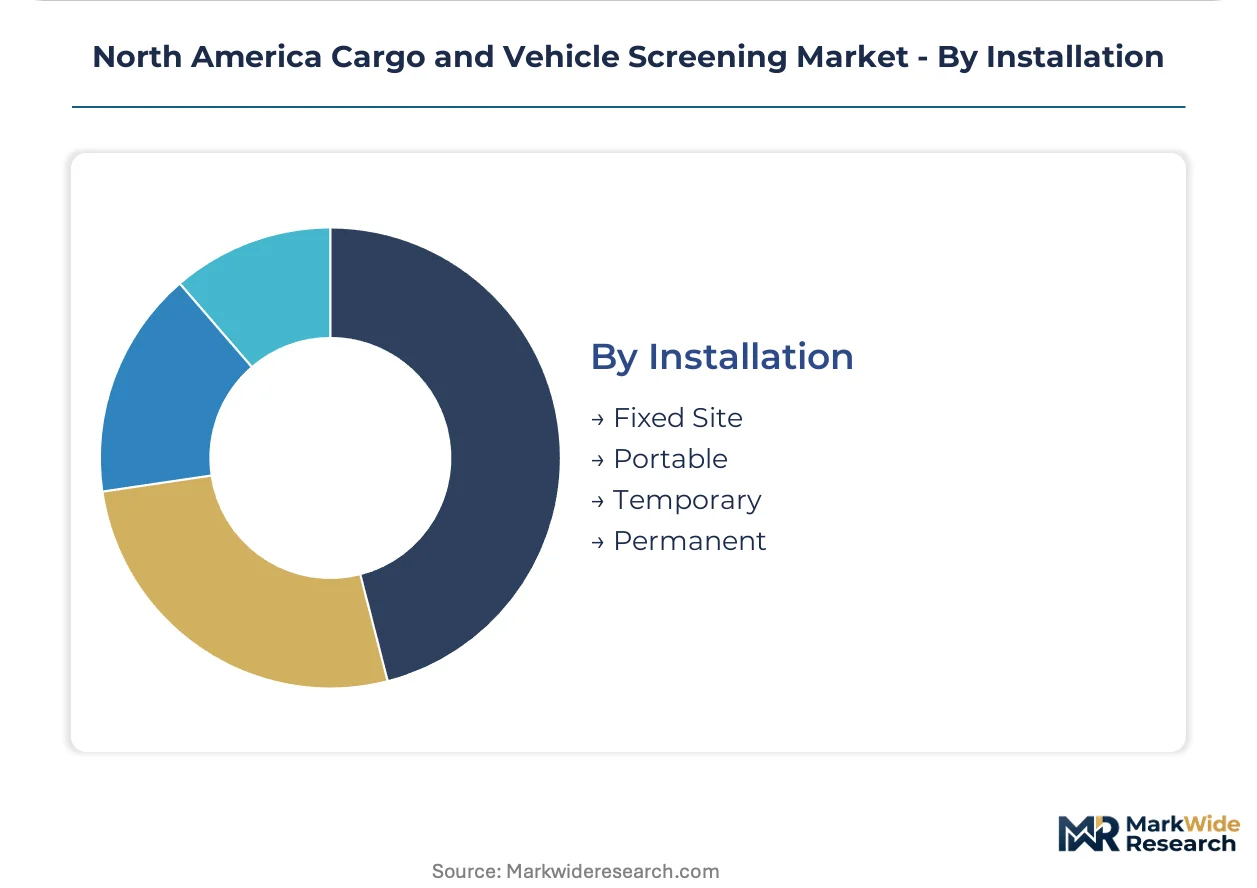
Installation:
Capital intensity and operational flexibility trade off across permanent infrastructure commitments and contingent deployment models.
- Fixed Site:Permanent concrete foundations with integrated radiation shielding and utility hardening support 24/7 operations at major commercial ports of entry. These installations anchor vendor service revenue through multi-year maintenance agreements.
- Portable:Rapidly deployable configurations with modular shielding and self-contained power suit temporary checkpoint requirements. U.S. Customs and Border Protection field offices are expanding portable fleet procurement for surge and contingency operations.
- Temporary:Event-specific deployments with minimal site preparation requirements serve security contractors operating on performance-based contracts.
- Permanent:Fully integrated customs workflow architectures with centralized monitoring and digital threat detection networks.
Asset base tilts toward Fixed Site. Contract innovation concentrates in Portable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in cargo and vehicle screening remain muted given the security-critical nature of procurement, though certification cost differentials between U.S. and Canadian frameworks do influence vendor market entry sequencing. The U.S.-Mexico border corridor concentrates infrastructure investment, while Canadian maritime gateways pursue parallel modernization tracks under distinct national security mandates.
United States
U.S. Customs and Border Protection drives procurement volume through the Customs-Trade Partnership Against Terrorism program and SAFETY Act certification requirements. The Department of Homeland Security mandates tiered security protocols at commercial ports of entry, with Arizona and Texas corridor checkpoints piloting sub-30-second millimeter-wave inspection cycles. California and Texas state transportation departments are retrofitting legacy weigh stations with automated screening interfaces.
Canada
Canada Border Services Agency enforces Transport of Dangerous Goods regulations that create parallel certification burden for unified North American product platforms. Port infrastructure expansion at Vancouver and Halifax generates demand for integrated vehicle and container screening systems with customs workflow integration. Transport Canada maintains oversight of radiation-emitting equipment alongside Health Canada safety standards.
Mexico
Mexican customs administration coordinates with U.S. agencies on bilateral port-of-entry modernization under the USMCA trade framework. Northern border states concentrate commercial truck traffic requiring throughput rates above 300 vehicles per hour at primary inspection lanes. Mexican maritime gateways at Lázaro Cárdenas and Manzanillo are expanding container screening capacity to handle Pacific trade volume growth.
North America Cargo and Vehicle Screening Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-electronics heritage conferring advantage in federal service contracts. The vendor base concentrates around three tiers: integrated platform providers sustaining multi-year maintenance agreements, rapid-deployment specialists capturing portable configuration demand, and component suppliers feeding detector crystal and sensor array requirements. Strategic moves center on algorithm subscription models displacing static hardware sales, and performance-based contracting where vendors retain system ownership.
Within the integrated platform tier, L3Harris Technologies and Smiths Detection Group Ltd occupy positions shaped by long-term federal agency relationships. Rapiscan Systems exemplifies the port-infrastructure modernization specialist archetype. These three entities anchor competitive dynamics through differentiated certification track records and service delivery model evolution toward real-time threat library updates.
| Leading Market Players |
|---|
| Nuctech Company Limited |
| L3Harris Technologies |
| Rapiscan Systems |
| Vantage Security |
| LINEV Systems |
| Smiths Detection Group Ltd |
| OSI Systems |
| UVeye Inc |
| Leidos Inc |
| Others |
Pricing and Supply Chain Analysis
SAFETY Act certification mandates from U.S. Customs and Border Protection compress procurement timelines while forcing supply chains to absorb extended validation costs, shifting pricing power toward vendors with established federal approval track records and locking out speculative entrants.
Pricing Analysis
Direct-to-agency contracting eliminates distributor margins, though systems integrators capture 12-18% markup for customs workflow integration. Three-tier pricing structure across premium, standard, and economy levels separates SAFETY Act-certified platforms from Transport Canada equivalents and uncertified portable configurations. Pricing pressure stems from performance-based contracts where vendors retain ownership and charge per-inspection fees. Customs Agencies show lowest price sensitivity given mandate-driven procurement; Event Organizers demand economy-tier portable units with minimal service bundling.
Supply Chain Analysis
Specialized workforce availability in Massachusetts and California defense electronics clusters constrains detector crystal fabrication capacity. Cadmium zinc telluride and sodium iodide scintillation materials draw from limited specialty chemical suppliers in the United States and Japan. Single-source vulnerability concentrates in high-purity detector crystal feedstock. Distribution runs through systems integrators with existing Customs and Border Protection contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchets, with the U.S. Department of Homeland Security's SAFETY Act framework creating recurring certification revenue streams that extend vendor cash flow visibility beyond hardware replacement cycles.
For Market Incumbents: Anchor service revenue through real-time threat library subscription models that displace static hardware sales. Defend against millimeter-wave substitution by deepening computed tomography integration into primary inspection lanes. Prioritize backward integration into detector crystal supply to mitigate sodium iodide allocation risk. For New Entrants and Emerging Players: Begin with portable configuration contracts at temporary checkpoint deployments where certification latency is shortest. Canadian maritime gateway modernization at Vancouver and Halifax offers white-space penetration before U.S. federal certification completion. Pursue Transport Canada approval as parallel pathway to accelerate revenue recognition. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-native entrants possessing machine-learning threat detection capabilities that compress operator decision cycles. Five-to-ten-year viability favors vendors transitioning from capital sales to recurring service models. Watch millimeter-wave pilot expansion at Arizona and Texas corridor checkpoints as inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SAFETY Act Certification Investment | Accelerates Customs and Border Protection procurement eligibility while creating 18-24 month competitive moat. |
| Algorithm Subscription Model | Transforms one-time hardware margins into recurring threat library update revenue with federal agencies. |
| Canadian Maritime Gateway Expansion | Captures port infrastructure modernization at Vancouver and Halifax under Transport Canada regulations. |
| Detector Crystal Backward Integration | Secures captive supply of cadmium zinc telluride against specialty chemical supplier concentration. |
| Millimeter-Wave Pilot Scaling | Converts Arizona and Texas corridor field trials into standardized sub-30-second inspection protocols. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national border agency jurisdiction. The analysis combines structured interviews with U.S. Customs and Border Protection procurement officers, Canada Border Services Agency technical standards leads, port authority infrastructure planners, and systems integrators with active federal contracting vehicles. Secondary validation draws from Department of Homeland Security SAFETY Act certification records, Transport Canada dangerous goods filings, and U.S. FDA 21 CFR 1020 radiation equipment registrations. Bottom-up installation counts at land border ports of entry triangulate against top-down federal agency budget appropriations.
Granularity-level modeling disaggregates volume and value across product type, end user, technology, and installation configuration dimensions. The analytical framework projects adoption curves for computed tomography and millimeter-wave platforms over the projection horizon. CAGRs derive from segment-specific growth rates weighted by installed base replacement cycles and port-of-entry modernization program timelines. Forecast inputs include cross-border freight volume trajectories along the U.S.-Mexico corridor and Transport Canada infrastructure spending commitments.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to SAFETY Act testing protocols and abrupt shifts in U.S.-Mexico trade policy. Forecasts reflect assumptions about certification timeline stability and detector crystal supply continuity. Material deviation in threat detection technology substitution rates or federal agency procurement acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market