
 Home Security Sensors Market | 2026-2036
Home Security Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Home Security Sensors Market Foresight
The EU Green Deal is repositioning material sourcing requirements for connected home devices, pushing manufacturers toward lower-carbon supply chains. ASSA ABLOY leverages its door hardware heritage to dominate integrated access control sensor bundles. Honeywell International Inc. anchors its position through in-house semiconductor fabrication for motion detection chipsets. Robert Bosch GmbH specializes in glass break acoustic pattern recognition, sustaining premium positioning in European professional installation channels.
Home security sensors are electromechanical or solid-state devices that detect intrusion events through infrared motion detection, magnetic field disruption, acoustic signature analysis, or glass vibration frequency response, typically operating at detection ranges of 12–40 feet with wireless transmission protocols such as Z-Wave or Zigbee at 2.4 GHz. Their primary commercial purpose is to trigger alarm response workflows, initiate video recording sequences, or dispatch monitoring service alerts upon unauthorized entry detection. Motion sensors lead product type revenue due to universal deployment across residential and commercial footprints, while IoT-enabled technology captures the fastest growth as cloud-native architectures displace legacy panel-centric systems. DIY installation expands fastest among technology segments, though professional installation retains the deepest margin pools through recurring monitoring revenue attachment.
FCC certification governs radio frequency emissions for wireless sensors sold in the United States, while CE marking and the EU AI Act establish conformity requirements for algorithm-enabled detection systems across European markets. GDPR data processing rules further constrain how IoT-enabled sensors store and transmit occupancy data, directly shaping product architecture decisions for cloud-connected devices. Stakeholders must monitor evolving interoperability mandates between competing smart home ecosystems to preserve addressable market scope.
Market Dynamics
The EU AI Act is rewriting compliance architecture for algorithm-enabled intrusion detection systems, forcing sensor manufacturers to revalidate acoustic and motion pattern recognition models under new conformity assessment procedures before CE marking authorization.
Growth Catalysts
- GDPR Data Localization Mandates:Occupancy data processing constraints are accelerating edge-computing sensor designs that perform detection analytics locally rather than transmitting raw data to cloud servers.
- DIY Installation Momentum:Wireless Z-Wave and Zigbee protocol standardization is collapsing technical barriers for unskilled residential buyers seeking self-monitored security configurations.
- Germany's Building Energy Efficiency Standards:Integrated sensor-thermostat combinations are qualifying for renovation subsidies that bundle security upgrades with climate retrofit programs.
Market Restraints
- Lithium Battery Supply Concentration:Wireless sensor power modules depend on cathode material refining clusters concentrated in China, exposing manufacturers to export quota volatility and forced labor due diligence requirements under the EU Corporate Sustainability Due Diligence Directive.
- Radio Spectrum Licensing Friction:FCC Part 15 certification timelines for 2.4 GHz devices have extended from 8 to 14 weeks due to testing backlog at Telecommunication Certification Bodies, delaying product launches.
- Subscription Fatigue Threshold:Residential buyers are resisting additional monthly monitoring fees when smartphone push notifications and self-managed video verification satisfy their response requirements.
Strategic Opportunities
- Japan's Aging-in-Place Infrastructure:Fall detection and unusual activity pattern sensors are qualifying for long-term care insurance reimbursement when integrated with municipal emergency response networks.
- Matter Protocol Convergence:Thread radio and IP-based interoperability standards are dissolving ecosystem lock-in between Amazon Alexa, Google Home, and Apple HomeKit platforms.
- EU Green Deal Material Sourcing Incentives:Lower-carbon aluminum housing and recycled plastic certification are unlocking preferential procurement status in Dutch and Danish public housing renovation tenders.
Industry Challenges
- Firmware Security Validation Talent Scarcity:Penetration testing and over-the-air update cryptography implementation require embedded systems engineers with IoT-specific cybersecurity credentials that command 40% salary premiums over general hardware developers.
- Legacy Panel Integration Complexity:Cloud-native sensors must maintain backward compatibility with 1990s-era hardwired control panels through translator modules that add hardware cost and installation labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Security Sensors Market |
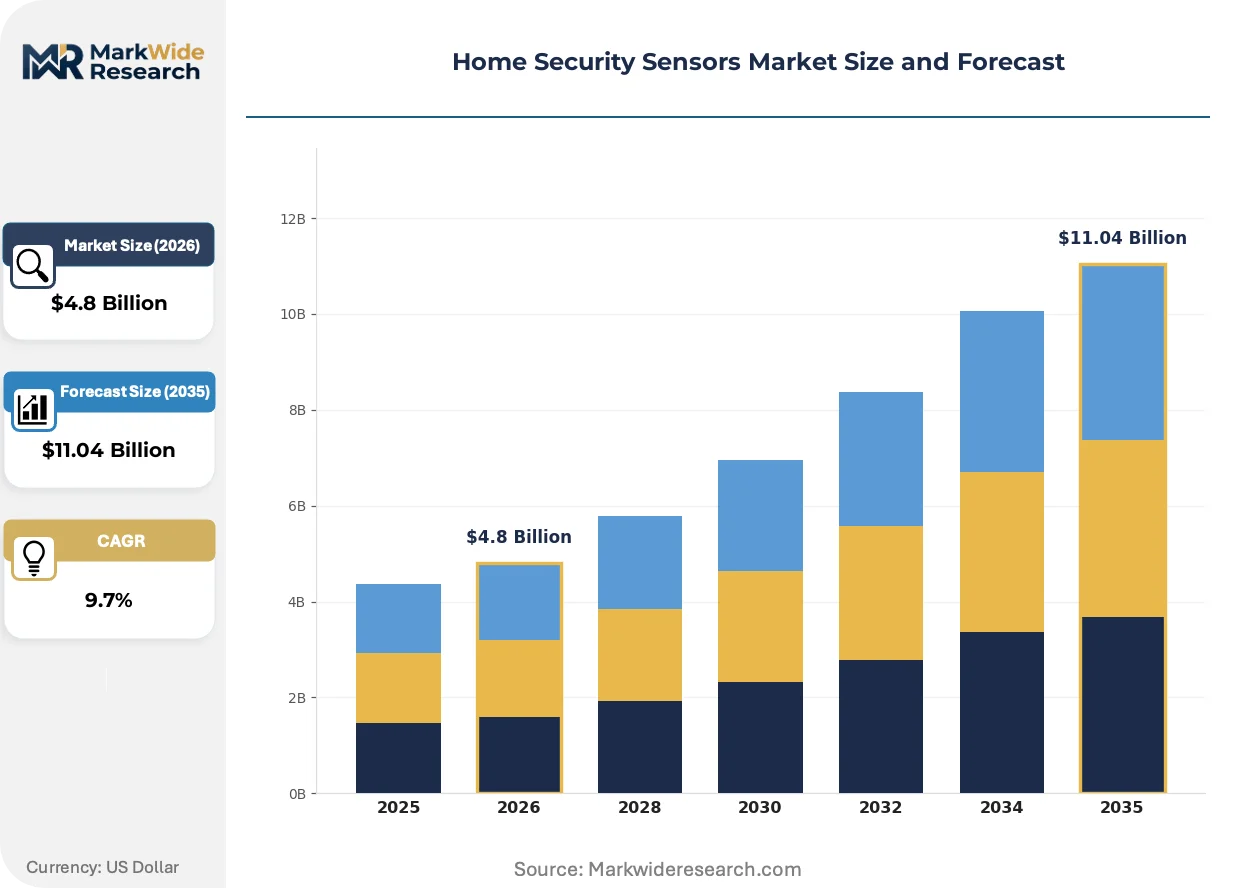
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motion Sensors, Window Sensors, Door Sensors, Glass Break Sensors Technology: Wired, Wireless, Hybrid, IoT-Enabled Installation: DIY, Professional, Remote Assistance, Integrated End User: Residential, Commercial, Government, Educational |
| Companies Covered | ASSA ABLOY, Johnson Controls, ADT, SimpliSafe, Resideo Technologies Inc., Honeywell International Inc., Robert Bosch GmbH, Arlo Technologies, Vivint, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Security Sensors Market Shifts & Advancements
Acoustic signature recognition and millimeter-wave presence detection are converging to eliminate false alarms from pets and environmental vibration, compressing the performance gap between residential and commercial-grade sensing accuracy.
Millimeter-wave radar-on-chip architectures are rewriting the economics of presence detection by enabling through-wall motion sensing without line-of-sight requirements. Multi-family housing developers in Germany and the Netherlands are specifying these sensors for common area monitoring where privacy regulations restrict camera deployment. The technology is compressing the addressable market for traditional PIR sensors in corridor and stairwell applications.
The EU AI Act's risk-based classification system is mandating third-party conformity assessment for biometric identification capabilities embedded in video-verified sensors. Manufacturers serving European professional installation channels are restructuring firmware to disable facial recognition by default, preserving CE marking eligibility while maintaining feature parity for non-EU markets. This regulatory fragmentation is increasing SKU complexity and regional inventory management overhead.
Subscription unbundling is accelerating as residential buyers in the United States and Japan prioritize hardware ownership with optional monitoring flexibility over mandatory multi-year contracts. Retail channels including Home Depot and Bic Camera are expanding shelf space for self-monitored starter kits that integrate with existing smart displays. This channel shift is compressing recurring revenue multiples that previously justified customer acquisition subsidies in professional installation segments.
Home Security Sensors Market Segmentation
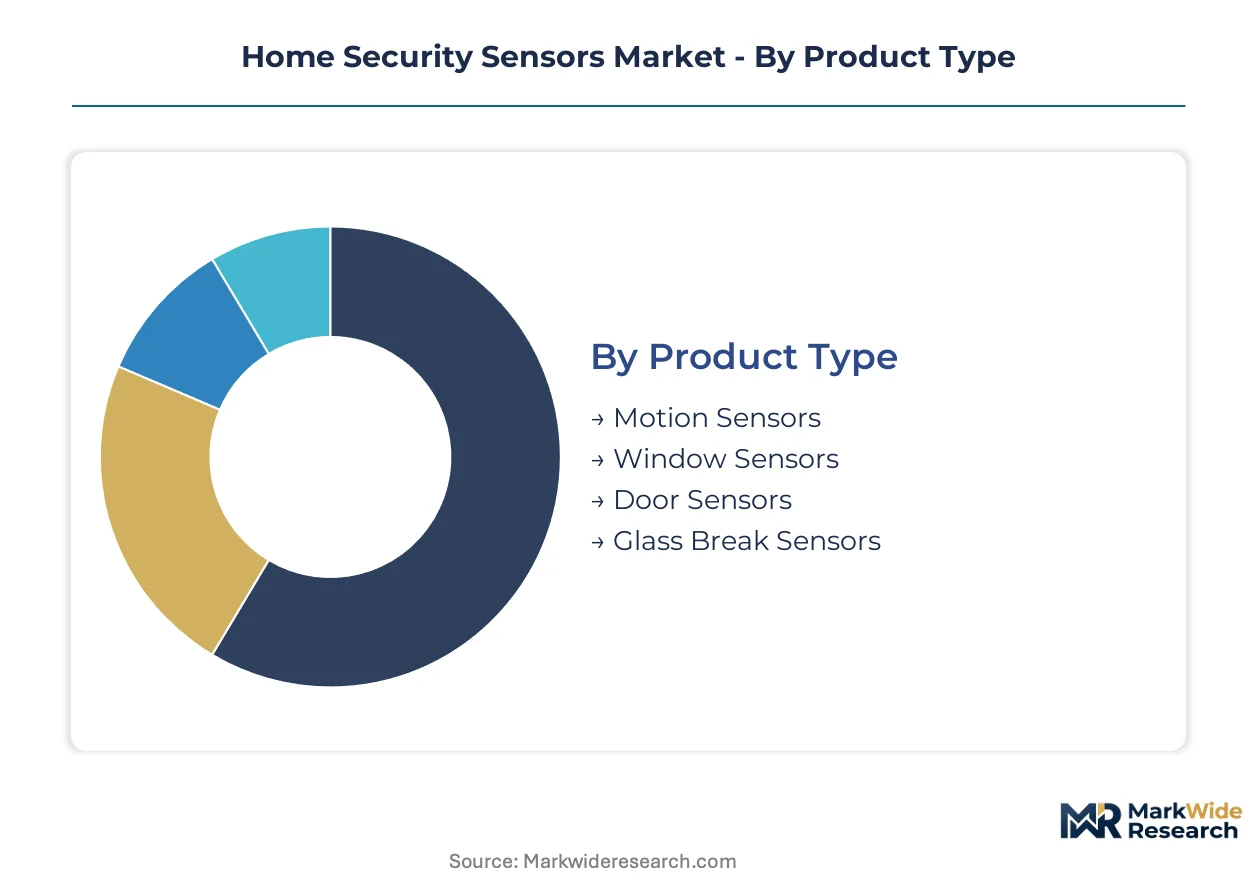
Segmentation in home security sensors reveals divergent capital requirements across hardware architectures, installation modalities, and customer procurement patterns. Each dimension carries distinct margin structures and regulatory exposure that shape go-to-market economics for component suppliers and system integrators.
Product Type:
Capital intensity varies sharply across detection technologies, with multi-element infrared arrays and acoustic pattern recognition chipsets demanding the heaviest upfront R&D investment.
- Motion Sensors:Passive infrared (PIR) and dual-tech microwave configurations dominate residential deployment. Demand concentrates in the United States where professional monitoring services bundle these as standard perimeter protection, though millimeter-wave radar-on-chip alternatives are eroding PIR share in German multi-family housing corridors.
- Glass Break Sensors:Acoustic signature analysis requires dedicated MEMS microphones and onboard FFT processing capability. European professional installation channels absorb the majority of volume, driven by CE marking requirements for algorithm-enabled detection under the EU AI Act.
- Window Sensors:Magnetic reed switches and vibration detection strips offer the lowest bill-of-materials cost in the category. These see highest attach rates in DIY starter kits sold through North American retail channels.
- Door Sensors:Contact switches and hinge-mounted accelerometers serve as entry-point sentinels. Japanese aging-in-place infrastructure programs subsidize these when integrated with municipal emergency response networks.
Motion sensors absorb the bulk of installed capacity; glass break sensors are expanding most quickly.
Technology:
Wireless protocol standardization has collapsed the capital barrier for new entrants, while IoT-native architectures require sustained cloud infrastructure investment.
- Wireless:Z-Wave and Zigbee at 2.4 GHz have displaced proprietary RF in residential applications. FCC Part 15 certification timelines now stretch 14 weeks due to testing backlog, delaying product launches for US-bound hardware.
- IoT-Enabled:Cloud-native sensors with edge analytics capability command premium positioning. GDPR data localization mandates are accelerating designs that perform detection analytics locally rather than transmitting raw occupancy data to servers.
- Wired:Hardwired 12V DC and PoE configurations persist in commercial and government verticals where reliability requirements override installation cost. Legacy panel backward compatibility adds translator module expense.
- Hybrid:Battery-backed wireless sensors with optional hardwired power suit renovation projects where cable routing proves impractical. These capture modest share in German building energy efficiency retrofit programs.
Wireless deployments dominate unit economics; IoT-enabled configurations claim the steepest expansion trajectory.
Installation:
Professional installation segments demand working capital for technician certification and fleet logistics, while DIY channels prioritize packaging and instructional content investment.
- DIY:Self-monitored configurations with smartphone push notifications are resisting subscription fatigue. Retail shelf space at Home Depot and Bic Camera is expanding for starter kits that integrate with existing smart displays.
- Professional:Monitored service attachment generates recurring revenue that justifies customer acquisition subsidies. Germany, the United States, and Japan concentrate demand through certified installer networks.
- Remote Assistance:Video-guided installation support reduces technician dispatch costs. This model gains traction among semi-technical residential buyers seeking guided self-configuration.
- Integrated:Pre-installed sensors in new construction and major renovations bundle with smart home ecosystems. Dutch and Danish public housing tenders now specify lower-carbon housing and recycled plastic certification.
Professional installation retains the deepest margin pools; DIY channels are climbing the fastest.
End User:
Residential procurement runs on consumer electronics margin structures, while government and educational verticals impose extended certification cycles and bonded warranty requirements.
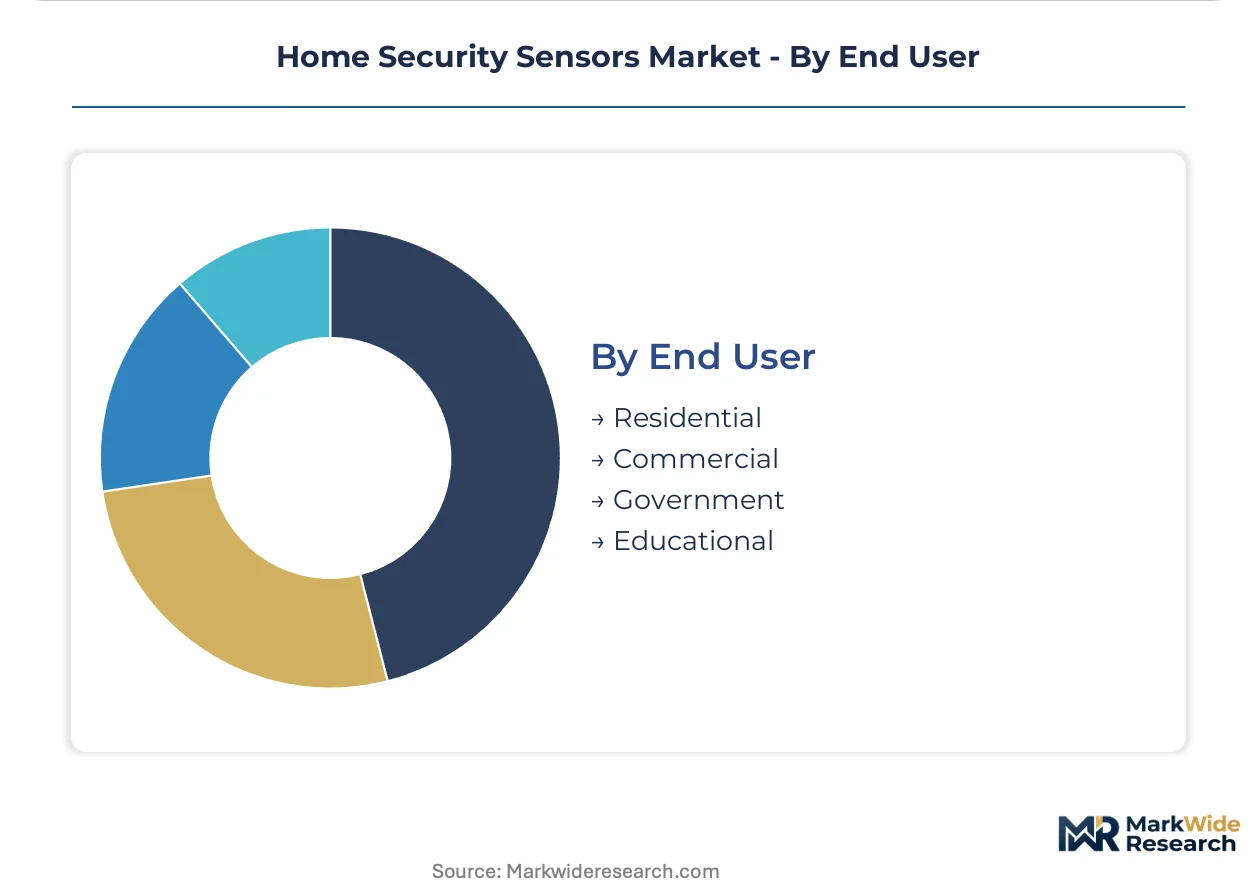
- Residential:Single-family and multi-family deployments prioritize aesthetic discretion and smartphone integration. Subscription unbundling is accelerating as buyers prioritize hardware ownership with optional monitoring flexibility.
- Commercial:Office, retail, and hospitality applications demand centralized management platforms and SLA-backed response times. Acoustic and millimeter-wave convergence is eliminating false alarms from environmental vibration.
- Government:Federal and municipal facilities require FISMA or equivalent cybersecurity compliance. Procurement cycles extend 18-24 months with mandatory penetration testing and firmware validation.
- Educational:K-12 and university campuses balance open access with emergency lockdown capability. These installations favor hybrid wireless-hardwired architectures for resilience during network outages.
Residential deployments absorb the bulk of unit volume; commercial applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European sensor manufacturing through Robert Bosch GmbH's acoustic detection R&D campus, while Shenzhen's electronics corridor supplies wireless module components across Asia-Pacific installer networks.
United States
Professional monitoring services bundle motion sensors with recurring revenue contracts across suburban single-family markets. FCC Part 15 certification timelines now stretch 14 weeks due to testing backlog at Telecommunication Certification Bodies. Dallas-Fort Worth concentrates installer fleet operations for nationwide residential deployment.
Germany
Building energy efficiency renovation subsidies accelerate integrated sensor-thermostat combinations in multi-family housing. EU AI Act conformity assessment procedures force revalidation of acoustic pattern recognition models before CE marking. Munich's professional installation channel absorbs premium glass break sensor volume.
Japan
Long-term care insurance reimburses fall detection sensors when integrated with municipal emergency response networks. METI standards govern interoperability between aging-in-place devices and smart city infrastructure. Osaka's housing cooperatives pilot through-wall millimeter-wave radar for common area monitoring.
Netherlands
Public housing tenders specify lower-carbon aluminum housing and recycled plastic certification for renovation projects. GDPR data localization mandates accelerate edge-computing sensor designs with local analytics. Eindhoven's smart home ecosystem developers test Matter protocol Thread radio implementations.
China
Wireless sensor power module supply concentrates around cathode material refining clusters. MIIT radio transmission standards govern 2.4 GHz device certification for domestic and export markets. Shenzhen's electronics manufacturing corridor ships Zigbee and Z-Wave modules to global DIY retail channels.
Home Security Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across installation modality and certification complexity. The vendor base stratifies between professional monitoring integrators, DIY retail platform suppliers, and component specialists. Three archetypes dominate: door hardware heritage companies leveraging access control bundles, semiconductor fabricators with captive motion detection chipsets, and acoustic pattern recognition specialists serving European professional channels. Competitive moves concentrate on backward integration into radio module fabrication and strategic partnerships around Matter protocol interoperability.
Within the heritage hardware tier, ASSA ABLOY and Robert Bosch GmbH exemplify European-centric positioning through professional installation channel depth. Honeywell International Inc. anchors the semiconductor-integrated archetype through in-house fabrication capabilities. These three entities occupy positions that reflect divergent responses to EU AI Act compliance architecture and GDPR data processing constraints.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Johnson Controls |
| ADT |
| SimpliSafe |
| Resideo Technologies Inc. |
| Honeywell International Inc. |
| Robert Bosch GmbH |
| Arlo Technologies |
| Vivint, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up monitoring service aggregators have consolidated installer networks across suburban United States markets, compressing procurement leverage for sensor OEMs while preserving recurring-revenue pricing power through multi-year contract lock-in. This ownership pattern feeds directly into supply chain behavior: rolled-up platforms demand volume rebates that squeeze component margins, yet their pricing discipline at the consumer level remains intact due to low switching costs and brand fragmentation.
Pricing Analysis
Outcome-based pricing anchored to false-alarm reduction and insurance premium discounts commands the highest tier in professional installation channels, separating CE-marked acoustic sensors with EU AI Act conformity from uncertified DIY alternatives. Price differentiation rests on certification grade and after-sales monitoring bundling, with FCC Part 15 certification adding measurable cost to United States-bound hardware. Cost compression in DIY starter kits is intensifying because Z-Wave module standardization has collapsed technical barriers for new entrants. Residential buyers seeking self-monitored configurations exhibit the sharpest price sensitivity, while commercial facilities with SLA-backed response requirements absorb premium positioning without material pushback.
Supply Chain Analysis
Freight cost volatility from Shenzhen to Rotterdam has reshored some wireless module assembly to Poland and Hungary, though cathode material refining for lithium power cells remains concentrated in China. The supply chain draws from Chinese rare-earth processing, Taiwanese semiconductor foundries, and German acoustic MEMS fabrication, creating multi-node exposure. Single-source vulnerability in 2.4 GHz radio chipset supply presents structural risk given FCC certification delays and MIIT export licensing friction. Distribution runs through professional installer fleets in Germany and the United States, DIY retail channels in Japan and the Netherlands, and direct-to-consumer platforms for Matter-compatible starter kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fabrication capacity for edge-computing architectures with local analytics capability remains bottlenecked by embedded cybersecurity engineering scarcity, propping pricing for GDPR-compliant designs above cloud-dependent alternatives. This supply constraint justifies sustained investment in certification-heavy professional channels despite DIY volume expansion.
For Market Incumbents: Deploy firmware modularization to maintain CE marking eligibility in European markets while preserving feature parity for non-EU jurisdictions facing less stringent algorithm assessment. Consolidate backward integration into radio module fabrication to offset FCC certification timeline risk and capture margin from Zigbee and Z-Wave component supply. Threat from millimeter-wave radar-on-chip substitutes demands accelerated R&D in through-wall presence detection to defend PIR sensor installed base. For New Entrants and Emerging Players: Municipal aging-in-place programs in Japan offer the most penetrable buyer archetype, with long-term care insurance reimbursement creating predictable procurement volume for fall-detection sensor bundles. Target Dutch and Danish public housing renovation tenders specifying lower-carbon aluminum housing certification, where incumbent compliance overhead creates white space for purpose-built sustainable designs. Go-to-market angle should emphasize Matter protocol Thread radio compatibility to bypass ecosystem lock-in friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor acoustic pattern recognition specialists with captive European professional installation channel relationships in Germany, where EU AI Act revalidation costs will strain undercapitalized competitors. Five-to-ten year viability hinges on sustained R&D amortization across multi-regional SKU portfolios. Signal to watch is FCC Telecommunication Certification Body backlog resolution, which would release pent-up hardware launch inventory and compress pricing for wireless-enabled configurations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Restructuring | Disables facial recognition by default in European firmware while maintaining feature parity elsewhere, preserving CE marking eligibility. |
| Edge-Computing Sensor Architecture | Performs detection analytics locally under GDPR data localization mandates, eliminating cloud transmission compliance exposure. |
| Matter Protocol Certification | Enables Thread radio interoperability across Amazon Alexa, Google Home, and Apple HomeKit platforms, dissolving ecosystem lock-in. |
| Millimeter-Wave Radar-on-Chip Integration | Rewrites presence detection economics for German multi-family housing corridors where privacy regulations restrict camera deployment. |
| Lower-Carbon Material Certification | Unlocks preferential procurement status in Dutch and Danish public housing tenders under EU Green Deal sourcing requirements. |
Research Methodology
Document review covered FCC Part 15 certification databases, EU AI Act implementing guidance, and GDPR supervisory authority decisions, complemented by interviews with professional installation network managers, embedded systems engineers, smart home platform integration specialists, and municipal aging-in-place program administrators. Secondary validation drew from customs trade data for wireless module shipments, SEC filings of monitoring service aggregators, and CE marking notification body records. Bottom-up sensor shipment estimates triangulated against top-down smart home ecosystem penetration data.
Historical installation modality splits cross-referenced against panel input from professional monitoring service procurement leads shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include detection technology, wireless protocol, installation type, and end-use vertical with regional regulatory cluster differentiation. CAGRs derived from curve-fitting historical adoption patterns against infrastructure subsidy program trajectories in Germany and Japan, with IoT-enabled architecture transition rates calibrated to cloud-native displacement of legacy panel-centric systems.
Revisions become necessary when FCC certification timeline extensions persist, EU Corporate Sustainability Due Diligence Directive enforcement disrupts lithium battery supply, or Matter protocol interoperability mandates accelerate faster than ecosystem consolidation permits. Forecasts reflect assumptions about regulatory stability and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Home Security Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Global Bot Security Market