
 Global Law Enforcement Software Market | 2026-2036
Global Law Enforcement Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Law Enforcement Software Market Foresight
North American software development capacity is decoupling from traditional on-premise delivery models as vendors rearchitect for cloud-native architectures. Motorola Solutions leverages its installed base of radio and dispatch hardware to extend into integrated software suites. Palantir Technologies anchors its position through specialized data fusion platforms for federal intelligence and investigative workflows. Tyler Technologies competes by dominating the municipal and county-level records management segment with deep jurisdictional customization.
Law enforcement software encompasses integrated digital platforms designed for crime analytics, evidence tracking, incident reporting, and operational command, typically architected with role-based access controls, audit trails, and API interoperability with criminal justice information systems. Cloud-based deployment configurations are capturing the fastest expansion as agencies prioritize remote accessibility and reduced infrastructure overhead, while case management and evidence management solutions concentrate margin pools due to stringent chain-of-custody requirements and long-term data retention mandates. On-premise and hybrid alternatives sustain relevance among federal agencies with classified or air-gapped operational constraints.
FDA cybersecurity guidance for connected devices, EU GDPR and AI Act provisions on automated decision-making, and India's MeitY data localization requirements collectively shape procurement specifications and vendor eligibility across jurisdictions. The FBI Criminal Justice Information Services security policy and ISO 27001 certification frameworks further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving cross-border data transfer restrictions and emerging algorithmic accountability mandates to anticipate compliance-driven replacement cycles.
Market Dynamics
Cloud-native architectures are displacing legacy on-premise installations as municipal police departments prioritize remote accessibility and reduced infrastructure overhead. The EU AI Act's algorithmic accountability mandates and India's MeitY data localization requirements are forcing vendors to requalify for procurement eligibility.
Growth Catalysts
- EU AI Act Compliance Mandates:Automated decision-making restrictions in European law enforcement procurement are accelerating replacement of legacy analytics platforms with auditable alternatives.
- Evidence Chain-of-Custody Digitization:Prosecutorial standards for digital evidence admissibility are driving investment in tamper-proof tracking systems with cryptographic verification.
- India:National police modernization programs under MeitY guidelines are funding cloud migration for state-level criminal databases and inter-jurisdictional data sharing.
Market Restraints
- Federal Air-Gapped Constraints:Classified operational requirements at FBI and NSA facilities perpetuate on-premise hardware demand, fragmenting vendor R&D investment across deployment modes.
- GDPR Cross-Border Transfer Friction:Schrems II rulings complicate cloud hosting arrangements for European agencies using US-based infrastructure providers.
- Specialized Cybersecurity Talent Scarcity:CJIS security policy certification requirements exceed supply of cleared personnel capable of implementing compliant architectures.
Strategic Opportunities
- Interoperable API Standards:Convergence of computer vision and natural language processing enables unified platforms merging body-worn camera analysis with transcribed interview intelligence.
- Germany:Bundesländer procurement consolidation creates opening for integrated suites replacing fragmented municipal point solutions.
- Subscription-Based Evidence Retention:Long-term cloud storage contracts for digital evidence offer recurring revenue models displacing capital-intensive on-premise server procurement.
Industry Challenges
- CJIS Security Policy Certification Timelines:FBI audit cycles extending 18-24 months delay product launches and strain vendor cash conversion.
- Legacy Records Management Integration:Decades-old COBOL-based arrest databases resist API connectivity, requiring expensive middleware development for data migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Law Enforcement Software Market |
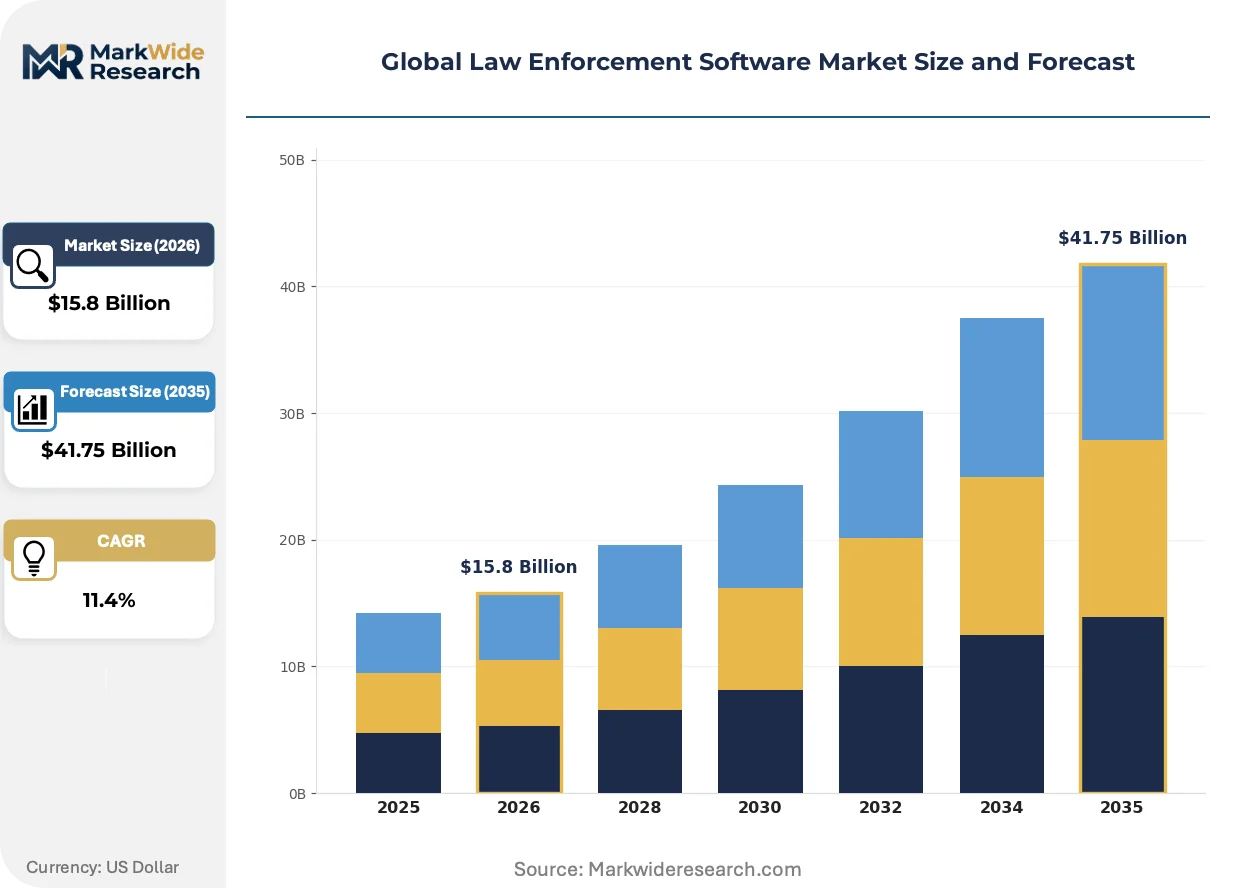
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Type: Crime Analytics, Case Management, Evidence Management, Digital Forensics, Records Management, Incident Reporting Application: Traffic Monitoring, Criminal Investigation, Cybercrime Prevention, Border Security, Crowd Control, Emergency Response End User: Police Departments, Federal Agencies, Border Patrol Units, Security Firms, Public Safety Organizations, Traffic Authorities |
| Companies Covered | Motorola Solutions, Axon Enterprise, NICE, NEC Corporation, Hexagon, IBM, Tyler Technologies, Palantir Technologies, CentralSquare Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Law Enforcement Software Market Shifts & Advancements
Artificial intelligence deployment patterns are bifurcating between real-time operational tools and retrospective investigative analytics. Vendors must navigate divergent latency, accuracy, and auditability requirements across these use cases.
Edge computing for real-time facial recognition and license plate reading is overtaking centralized cloud processing for patrol vehicle deployments. California Highway Patrol and Texas Department of Public Safety are prioritizing sub-100-millisecond response times for officer safety alerts. This architecture is compressing reliance on continuous connectivity and reshaping hardware-software bundling strategies.
The EU AI Act's prohibitions on biometric identification in public spaces are constraining product roadmaps for European sales. Vendors must maintain parallel feature sets—full-capability versions for US federal clients and restricted alternatives for GDPR jurisdictions. Germany's interior ministries are negotiating carve-outs for serious crime investigations, creating regulatory fragmentation within the single market.
Consolidated platform procurement is displacing best-of-breed point solution acquisition at the municipal level. Mid-sized police departments in Illinois and Ohio are favoring integrated suites from single vendors over specialized evidence, dispatch, and analytics tools. This concentration is visible most acutely in counties with populations between 100,000 and 500,000 residents where IT staffing constraints limit multi-vendor integration capacity.
Global Law Enforcement Software Market Segmentation
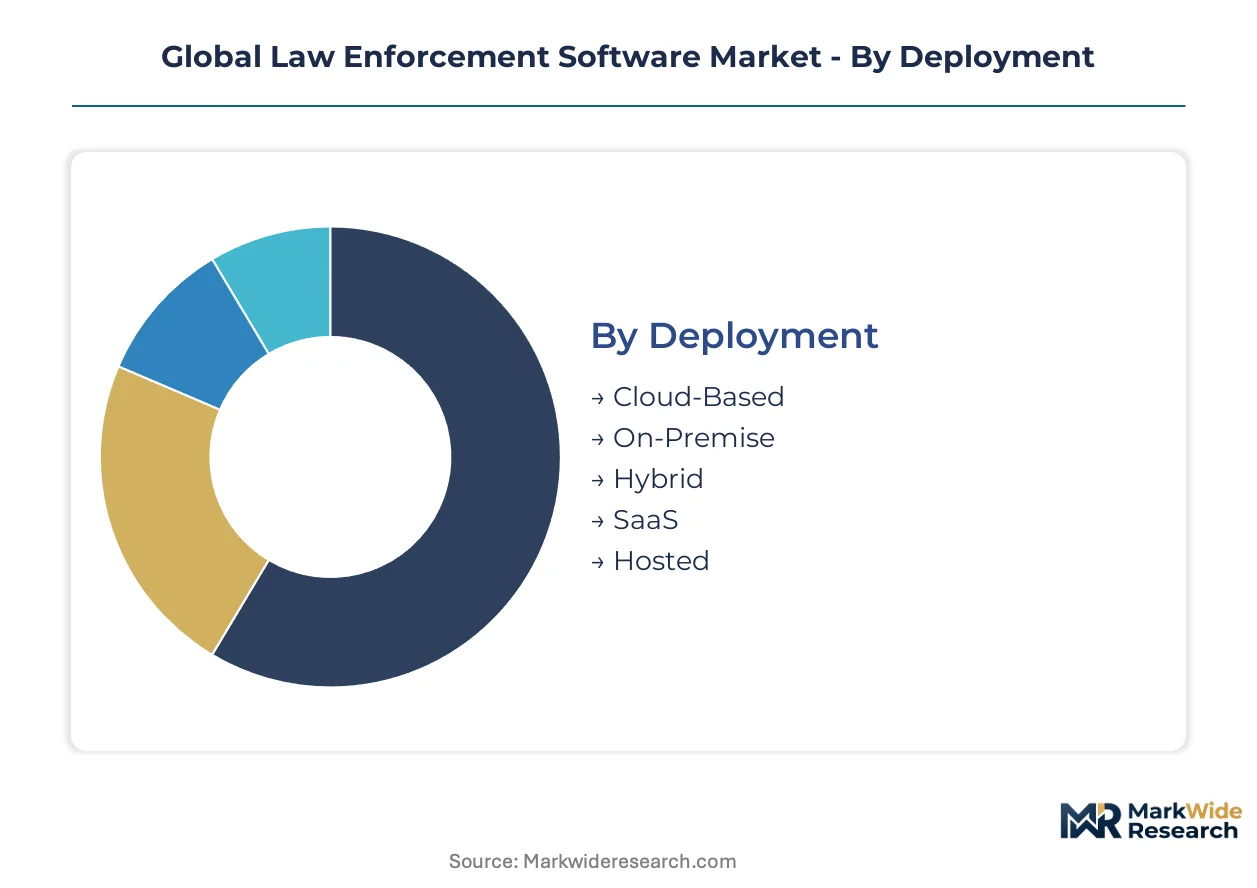
Segmentation in law enforcement software reflects divergent procurement priorities across jurisdictions with varying data sovereignty requirements and IT modernization timelines. Deployment architecture and solution specialization determine vendor qualification pathways and recurring revenue potential.
Deployment:
Supply concentration among hyperscale cloud providers is reshaping how agencies negotiate data residency and CJIS compliance terms.
- Cloud-Based:Multi-tenant architectures with FedRAMP or ISO 27001 certification enable rapid provisioning for municipal departments. Procurement in Germany and India accelerates as MeitY guidelines and EU AI Act auditability requirements favor centralized infrastructure with transparent logging.
- On-Premise:Air-gapped installations serve FBI and NSA facilities with classified operational constraints. Hardware-software bundling persists where continuous connectivity is prohibited, fragmenting vendor R&D across deployment modes.
- Hybrid:Split architectures retain sensitive records locally while pushing analytics workloads to cloud environments. Texas Department of Public Safety and California Highway Patrol pilot these configurations for patrol vehicle edge computing.
- SaaS:Subscription models reduce capital expenditure for counties with populations between 100,000 and 500,000 residents. Tyler Technologies and Motorola Solutions compete aggressively in this tier with integrated municipal suites.
- Hosted:Dedicated single-tenant environments address GDPR cross-border transfer friction for European agencies avoiding US-based hyperscale infrastructure. German Bundesländer procurement consolidation favors these arrangements.
On-Premise absorbs the bulk of installed capacity; Cloud-Based is expanding most quickly.
Solution Type:
Margin pools concentrate where chain-of-custody requirements and long-term retention mandates create switching costs.
- Crime Analytics:Machine learning platforms for pattern recognition and predictive deployment face EU AI Act prohibitions on biometric identification in public spaces. Vendors maintain parallel feature sets—full-capability versions for US federal clients, restricted alternatives for GDPR jurisdictions.
- Case Management:Workflow automation for investigative timelines integrates with prosecutorial systems. Illinois and Ohio mid-sized departments favor unified platforms over specialized point solutions due to IT staffing constraints.
- Evidence Management:Tamper-proof tracking with cryptographic verification addresses prosecutorial standards for digital evidence admissibility. Subscription-based cloud retention contracts displace capital-intensive server procurement.
- Digital Forensics:Specialized tools for device extraction and data recovery serve cybercrime units. Certification timelines for CJIS security policy compliance extend 18-24 months, delaying product launches.
- Records Management:Deep jurisdictional customization dominates municipal and county-level procurement. Decades-old COBOL-based arrest databases resist API connectivity, requiring expensive middleware development.
- Incident Reporting:Mobile-first data entry for field officers demands sub-100-millisecond response times. Edge computing architectures compress reliance on continuous connectivity.
Records Management retains the largest installed base; Evidence Management shows the steepest expansion trajectory.
Application:
Operational use cases diverge sharply between real-time safety alerts and retrospective investigative workflows.
- Traffic Monitoring:License plate recognition and automated violation processing generate high transaction volumes. Edge computing deployment in patrol vehicles overtakes centralized cloud processing for latency-sensitive alerts.
- Criminal Investigation:Data fusion platforms integrate body-worn camera analysis with transcribed interview intelligence. Palantir Technologies anchors federal intelligence workflows through specialized offerings.
- Cybercrime Prevention:Threat intelligence and digital asset tracing require continuous connectivity and cross-jurisdictional data sharing. India's state-level criminal database modernization under MeitY guidelines targets this gap.
- Border Security:Multi-modal biometric screening faces EU AI Act restrictions on automated decision-making. ANVISA and Health Canada interoperability standards shape North American procurement.
- Crowd Control:Real-time video analytics for public event monitoring encounters algorithmic accountability mandates in European jurisdictions. Germany's interior ministries negotiate serious crime investigation carve-outs.
- Emergency Response:Dispatch and command platforms integrate with legacy radio infrastructure. Motorola Solutions leverages installed hardware base to extend into software suites.
Criminal Investigation commands the deepest per-seat pricing; Cybercrime Prevention is climbing the fastest.
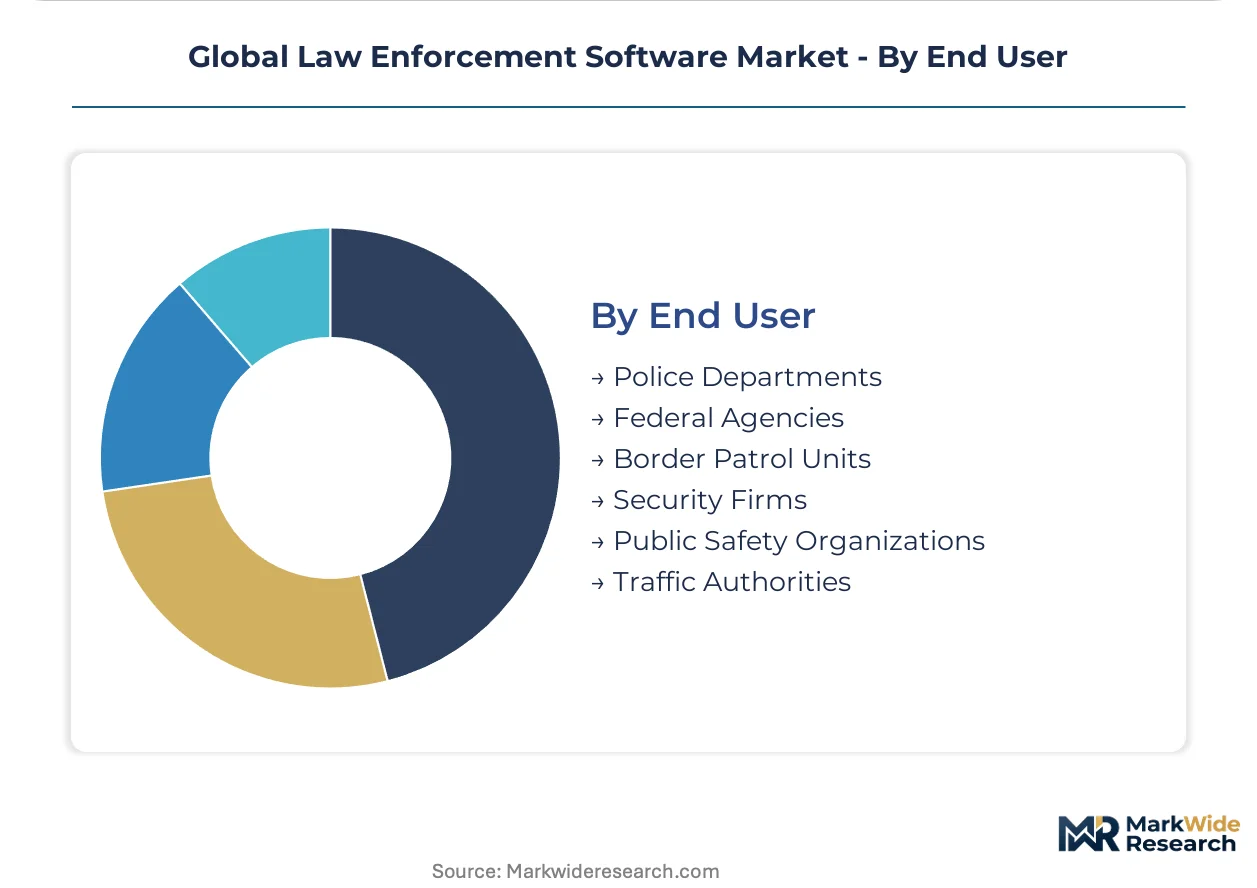
End User:
Procurement authority fragmentation across federal, state, and municipal tiers creates complex sales cycles.
- Police Departments:Municipal agencies in North America and Europe drive cloud migration with limited IT staffing. Consolidated platform procurement displaces best-of-breed point solution acquisition.
- Federal Agencies:FBI and NSA classified facilities perpetuate on-premise demand with air-gapped constraints. CJIS security policy certification requirements exceed supply of cleared implementation personnel.
- Border Patrol Units:Interoperability demands span national boundaries and customs regimes. EU GDPR and India's MeitY data localization requirements complicate cross-border hosting arrangements.
- Security Firms:Private sector adoption lags public procurement due to liability concerns and evidence admissibility standards. ISO 27001 certification frameworks constrain market access.
- Public Safety Organizations:Multi-agency coordination platforms require API interoperability with criminal justice information systems. Schrems II rulings complicate European deployment on US infrastructure.
- Traffic Authorities:State-level departments in Texas and California prioritize sub-100-millisecond response times for officer safety. Edge computing hardware-software bundling strategies reshape competitive dynamics.
Police Departments represent the largest addressable base; Federal Agencies sustain the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American development capacity, while Germany's industrial software heritage and India's IT services clusters shape procurement patterns across three continents.
United States
Municipal police departments in Illinois and Ohio accelerate consolidated platform procurement due to IT staffing constraints. CJIS security policy certification requirements exceed cleared personnel supply, extending vendor audit cycles to 18-24 months. The California Highway Patrol and Texas Department of Public Safety pilot edge computing for sub-100-millisecond officer safety alerts.
Germany
Bundesländer procurement consolidation creates openings for integrated suites replacing fragmented municipal point solutions. EU AI Act algorithmic accountability mandates and biometric identification prohibitions in public spaces force vendors to maintain parallel feature sets. Interior ministries negotiate serious crime investigation carve-outs, generating regulatory fragmentation within the single market.
India
National police modernization programs under MeitY data localization guidelines fund cloud migration for state-level criminal databases. Cross-jurisdictional data sharing requirements target cybercrime prevention gaps. State-level agencies in Maharashtra and Karnataka lead procurement of interoperable platforms with API connectivity to legacy systems.
United Kingdom
GDPR cross-border transfer friction complicates cloud hosting arrangements for agencies using US-based infrastructure providers. Schrems II rulings reshape procurement specifications toward dedicated single-tenant environments. Metropolitan police forces in London prioritize audit trail transparency for automated decision-making systems.
Japan
Metropolitan police in Tokyo and Osaka demand ISO 27001 certification frameworks for vendor qualification. Integration with legacy records management systems requires expensive middleware development for decades-old arrest databases. Prefectural agencies balance cybersecurity talent scarcity against CJIS-equivalent compliance timelines.
Global Law Enforcement Software Market Competitive Landscape
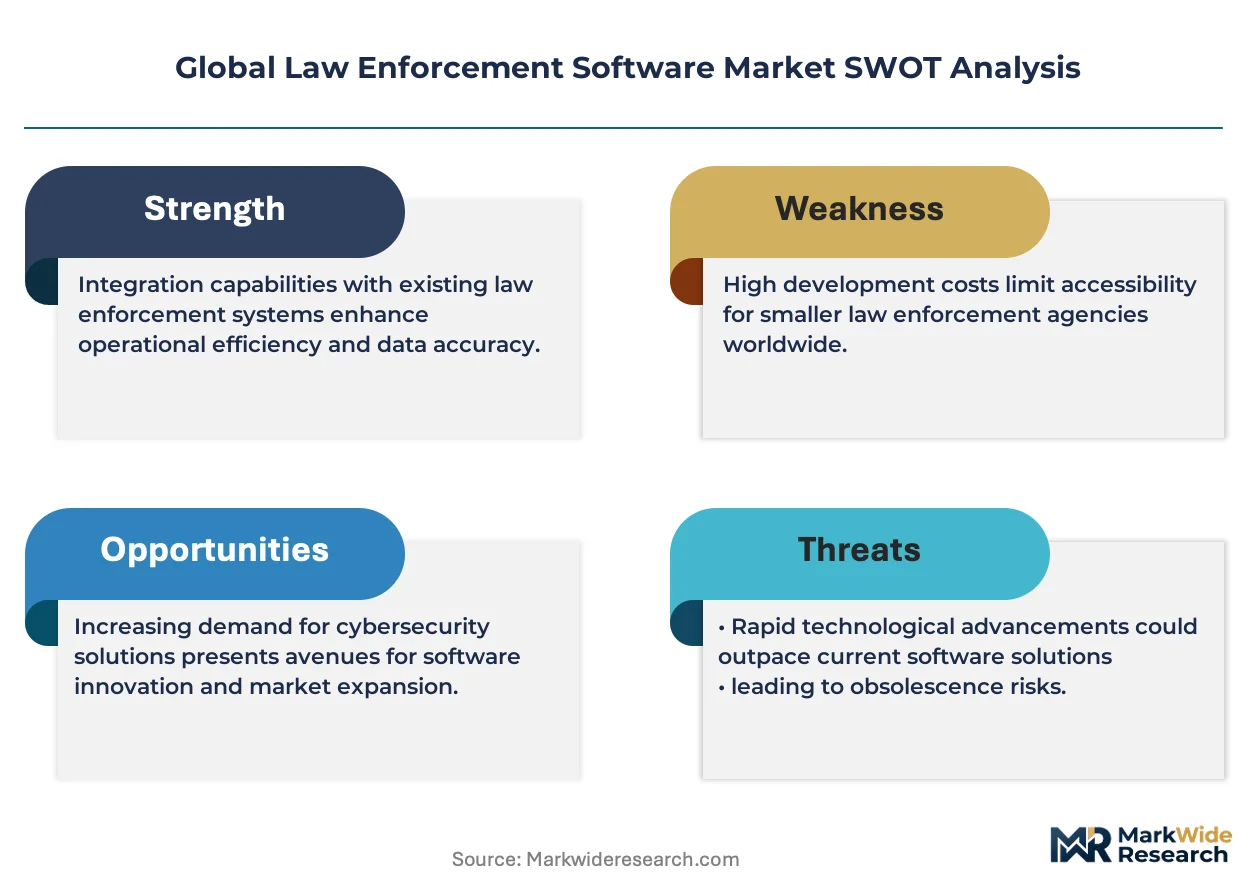
Global majors compete with regional champions across deployment architecture specialization and jurisdictional customization depth. The market exhibits tiered concentration where integrated suite vendors capture municipal consolidation while point solution specialists retain federal niches. Three archetypes dominate: hardware-leveraged platform extenders, data fusion specialists, and jurisdictional customization leaders. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent public safety verticals.
Within the hardware-leveraged tier, Motorola Solutions exemplifies platform extension from radio and dispatch infrastructure into integrated software suites. Palantir Technologies occupies a position as the data fusion specialist anchoring federal intelligence workflows. Tyler Technologies represents the jurisdictional customization archetype dominating municipal and county-level records management with deep adaptation to local procedural requirements.
| Leading Market Players |
|---|
| Motorola Solutions |
| Axon Enterprise |
| NICE |
| NEC Corporation |
| Hexagon |
| IBM |
| Tyler Technologies |
| Palantir Technologies |
| CentralSquare Technologies |
| Others |
Supply & Pricing Matrix
Municipal procurement consolidation across Illinois and Ohio police departments is compressing vendor margins as buyers demand integrated suites over point solutions, forcing suppliers to absorb middleware development costs for legacy COBOL database integration while maintaining competitive SaaS subscription rates.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from economy competitors, with CJIS security policy certification and FedRAMP authorization serving as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance investment depth rather than feature differentiation alone. Pricing pressure stems from state-level agencies in India and Germany negotiating volume discounts for national police modernization programs. County-level departments with populations below 500,000 residents exhibit highest price sensitivity due to constrained IT capital budgets.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor software delivery networks, with hyperscale cloud infrastructure concentrated among AWS, Azure, and Google Cloud facilities. The supply chain draws from specialized cybersecurity talent pools, cryptographic hardware security modules, and API middleware development capacity. Single-source vulnerability in CJIS-cleared implementation personnel creates procurement bottlenecks extending vendor audit cycles. Distribution runs through direct enterprise sales teams for federal agencies and channel partners for municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Law Enforcement Software Market functions as a cost-of-compliance story where EU AI Act algorithmic accountability mandates and CJIS security policy certification requirements erect substantial barrier-to-entry moats favoring incumbent vendors with established audit relationships.
For Market Incumbents: Acquire specialized digital forensics capabilities to fill portfolio gaps in cybercrime investigation tools. Consolidate middleware development expertise for legacy records management integration to defend against cloud-native challengers. Expand CJIS-cleared implementation capacity in Texas and California where edge computing pilots are accelerating procurement timelines.
For New Entrants and Emerging Players: Launch via API-first interoperability platforms targeting mid-sized municipal departments in Ohio and Illinois frustrated by vendor lock-in from integrated suite providers. White-space opportunities concentrate in subscription-based evidence retention services for counties with 100,000-500,000 residents lacking long-term digital storage infrastructure.
For Investors and Strategic Acquirers: The window for entry favors vendors with existing CJIS certification or EU AI Act compliance infrastructure already operational. Long-term viability hinges on regulatory moat durability rather than feature innovation velocity. Monitor German interior ministry negotiations for serious crime biometric identification carve-outs as inflection signal for European market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies body-worn camera analysis with transcribed interview intelligence for federal investigative workflows. |
| Strategic Partnership | Aligns with hyperscale cloud providers to satisfy MeitY data localization requirements in Indian state deployments. |
| Acquisition of Specialist Firm | Targets middleware developers capable of bridging decades-old COBOL arrest databases to modern APIs. |
| Geographic Expansion | Penetrates German Bundesländer procurement consolidation with hosted single-tenant alternatives to US hyperscale infrastructure. |
| Product Launch | Introduces edge computing architectures achieving sub-100-millisecond response times for California and Texas patrol vehicles. |
Research Methodology
Independent corroboration across procurement officers at municipal police departments, CJIS security policy auditors, and cloud infrastructure architects underwrites the qualitative findings. Primary interviews with IT directors at mid-sized departments in Illinois and Ohio, federal technology procurement leads, and European data protection officers combined with secondary validation from FBI Criminal Justice Information Services policy documentation, EU AI Act regulatory texts, and MeitY guideline publications. Bottom-up deployment model segmentation triangulates against top-down jurisdictional spending analysis.
Rate-of-change decomposition separates cloud migration velocity from on-premise replacement cycles across the analysis window. Segmentation dimensions modeled include deployment architecture, solution specialization, operational application, and end-user tier alongside regional regulatory cluster differentiation. CAGRs derive from installed base erosion rates and new procurement pipeline conversion. Forecast inputs incorporate CJIS certification timeline delays and EU AI Act implementation phase-in schedules.
Regulatory enforcement variance, CJIS audit backlog fluctuations, and cross-border data transfer ruling modifications are the dominant revision risks. Forecasts reflect documented assumptions on compliance timeline adherence and procurement authority consolidation trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Burglar Alarm Systems Market
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Crowdsourced Security Market