
 Tele Protection Market | 2026-2036
Tele Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Tele Protection Market Intelligence
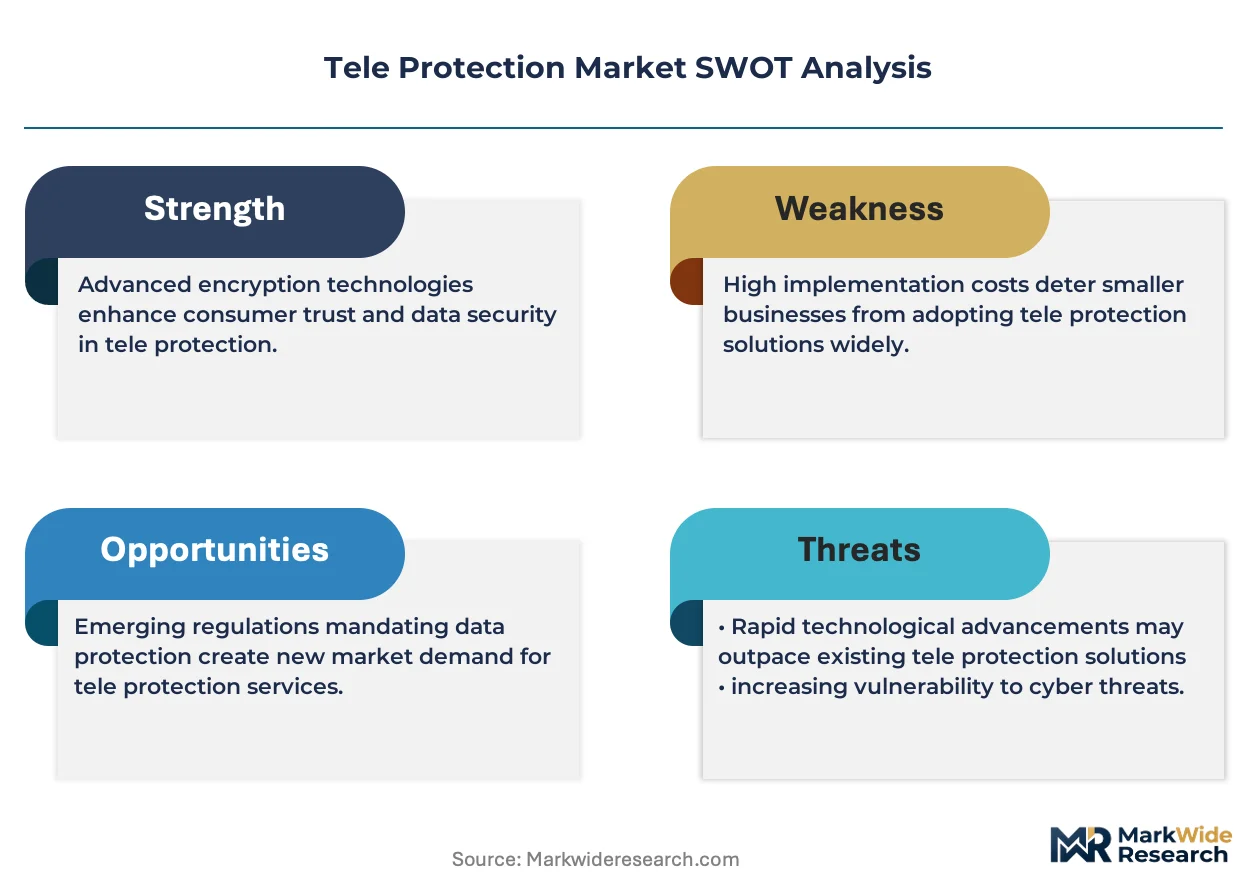
The IEC 61850 standard for power utility automation is bifurcating the competitive landscape between legacy system providers and new entrants. Siemens AG leverages its deep expertise in both energy and automation to offer integrated solutions. Schneider Electric competes by focusing on digital transformation solutions for energy management. Cisco Systems anchors its position by providing secure, IP-based networking infrastructure essential for modern teleprotection.
Tele protection refers to systems that use communication channels to remotely trip circuit breakers and isolate faults on high-voltage electricity networks. These systems require extremely low-latency communication, often below 10 milliseconds, to ensure grid stability and prevent cascading failures. IP Networking technology now dominates new deployments over legacy communication methods. Security solutions represent the fastest-growing solution category, driven by heightened cybersecurity concerns among telecom operators and government agencies.
Regulatory frameworks from bodies like the North American Electric Reliability Corporation (NERC) and guidelines from Europe's ENTSO-E mandate stringent reliability and cybersecurity standards for grid operations. In China, the national 'dual carbon goals' policy is accelerating investments in smart grid technologies that rely on advanced teleprotection. Vendors must now decide whether to specialize in hardware, software, or integrated systems as the market moves towards more disaggregated, software-defined architectures.
Market Dynamics
The teleprotection market's structure is being redefined by the transition from legacy time-division multiplexing (TDM) networks to IP/MPLS packet-switched infrastructure. This technological shift, driven by the need for greater bandwidth and flexibility, introduces new complexities around latency, interoperability, and cybersecurity.
Growth Catalysts
- Grid Modernization Mandates:Regulatory bodies, including NERC in the United States and ENTSO-E in Europe, are enforcing stricter reliability standards that compel utilities to upgrade aging protection and communication systems to prevent wide-area blackouts.
- IEC 61850 Standard Adoption:The widespread implementation of the IEC 61850 standard for substation automation creates a common language for intelligent electronic devices, fueling demand for interoperable teleprotection solutions that can leverage its capabilities.
- Smart Grid Investment:National policies, such as China's 'dual carbon goals', are accelerating public and private investment in smart grid technologies, which depend on high-speed, reliable teleprotection for integrating renewable energy sources and managing bidirectional power flows.
Market Restraints
- High Capital Expenditure:The substantial upfront cost associated with migrating from established, depreciated TDM and SONET/SDH networks to modern IP/MPLS infrastructure presents a significant financial barrier for many electric utilities, particularly smaller cooperatives.
- Latency Assurance Complexity:Achieving and guaranteeing the ultra-low latency required for protection schemes like line current differential is technically more challenging over packet-switched networks compared to deterministic legacy circuits, requiring sophisticated engineering.
- Legacy System Interoperability:Ensuring seamless operation between new IP-based teleprotection equipment and the vast installed base of older electromechanical and solid-state relays creates significant integration hurdles and potential points of failure.
Strategic Opportunities
- Emerging Economy Grids:Countries like India and Brazil are undertaking massive grid expansion and modernization projects, representing significant greenfield opportunities for advanced teleprotection systems without the burden of extensive legacy infrastructure.
- OT Cybersecurity Integration:The convergence of teleprotection with broader operational technology (OT) security platforms creates an opportunity for vendors to offer integrated solutions that provide both fault isolation and comprehensive cyber threat monitoring.
- Managed Service Models:A shift towards offering Teleprotection-as-a-Service (TPaaS) allows utilities to convert capital expenditures into operating expenses while outsourcing network management, security, and compliance to specialized providers.
Industry Challenges
- Vendor Implementation Differences:Variations in how different manufacturers interpret and implement the IEC 61850 standard can lead to interoperability problems, hindering the creation of truly multi-vendor substation environments and increasing integration complexity.
- Specialized Skills Gap:A shortage of engineers and technicians with combined expertise in power system protection, IP networking, and cybersecurity is a critical operational challenge for both utilities and system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tele Protection Market |
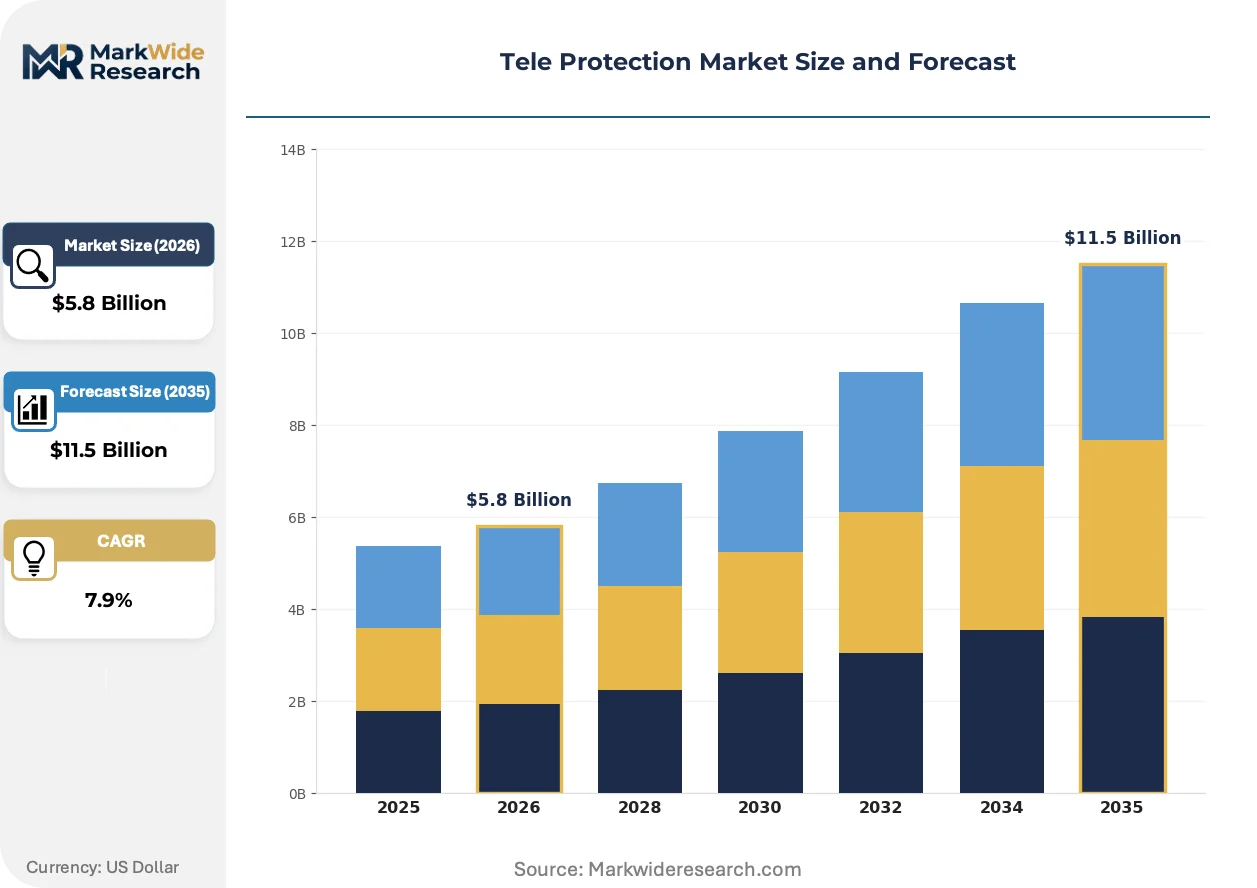
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IP Networking, MPLS, VPN, Satellite Communication Deployment: On-Premises, Cloud-Based, Hybrid, Remote Access End User: Telecom Operators, Enterprises, Government Agencies, Service Providers Solution: Network Management, Security Solutions, Backup Services, Monitoring Tools |
| Companies Covered | Cisco Systems, Schneider Electric, Mitsubishi Electric Corporation, Hitachi Energy, ABB Power Grids, Siemens AG, Abb Ltd, EnerNex, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tele Protection Market Strategic Shifts & Innovations
The market is pivoting from hardware-defined, monolithic systems toward disaggregated, software-centric architectures. This evolution enhances flexibility and enables new service models but simultaneously expands the attack surface, elevating the importance of embedded cybersecurity in all system components.
Software-defined networking (SDN) provides a method to centrally manage and program network behavior, separating the control logic from the underlying hardware. Power utilities are adopting SDN to dynamically prioritize critical protection traffic over less urgent data, ensuring deterministic performance on shared IP networks. This move away from proprietary hardware appliances is fragmenting the value chain, creating space for specialized software vendors to compete with incumbent system providers.
Regulatory frameworks are increasingly focused on the cyber-resilience of critical infrastructure. The North American Electric Reliability Corporation's Critical Infrastructure Protection (NERC CIP) standards, for example, mandate stringent security controls for assets vital to the grid's operation. This forces utilities to invest heavily in securing their communication networks, including those used for teleprotection. The security solutions category is therefore seeing accelerated innovation in intrusion detection and access control for OT environments.
A notable shift in purchasing behavior involves utilities moving from one-time equipment acquisitions to lifecycle management agreements with vendors. This disrupts the traditional sales model, favoring suppliers who can provide ongoing support, software updates, and security patching as part of a long-term partnership. This trend is most pronounced in developed markets where utilities are focused on optimizing total cost of ownership rather than just initial capital outlay.
Tele Protection Market Segmentation
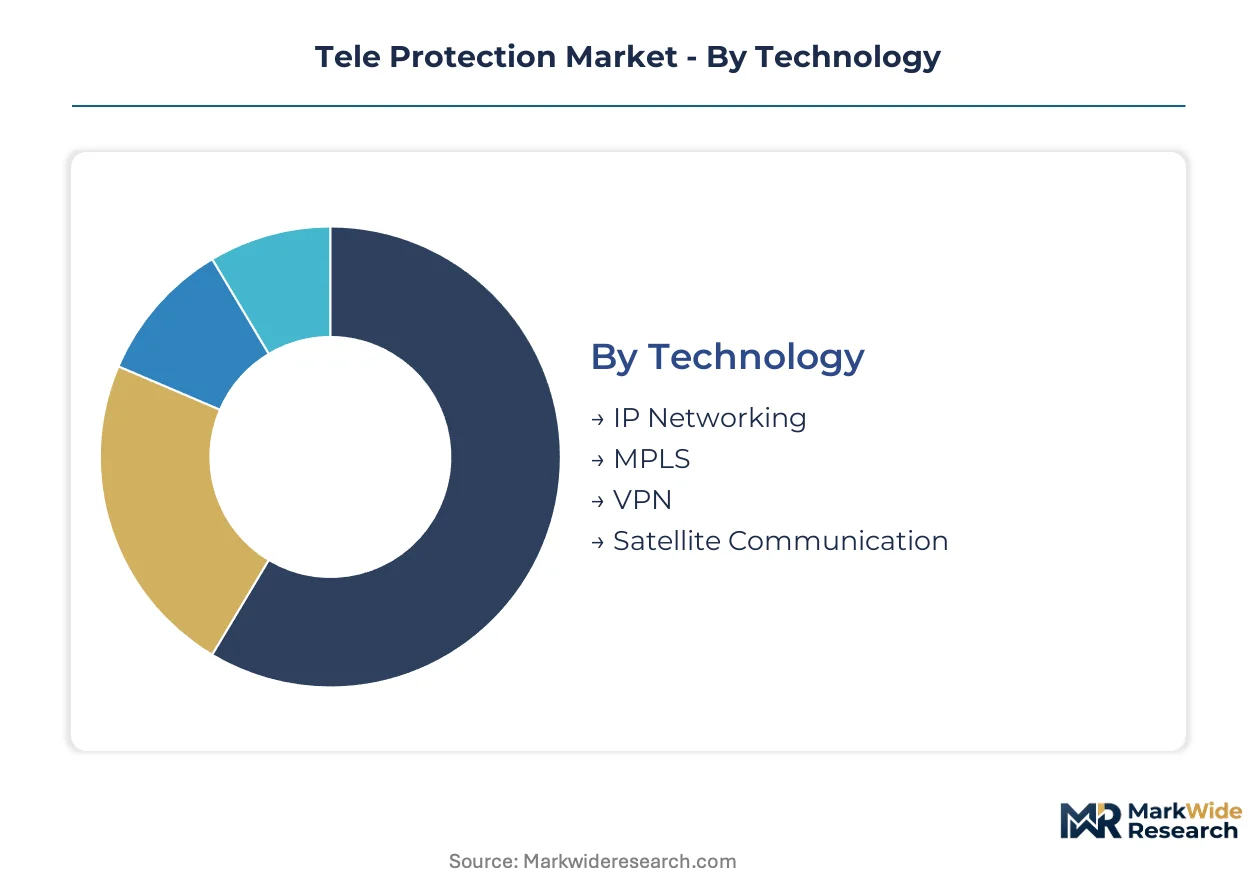
Segmenting the tele protection market reveals how different technological approaches and deployment models address the critical requirements of grid stability and fault isolation. Analyzing these distinct categories helps stakeholders understand the specific value propositions and operational challenges across the energy and communication sectors.
Technology:
The choice of communication technology dictates the underlying channel mix and performance characteristics for tele protection systems, influencing latency and bandwidth capabilities.
- IP Networking:This segment encompasses systems utilizing Internet Protocol for data transmission, providing the foundation for modern packet-switched tele protection with enhanced flexibility and scalability for grid modernization projects. Demand for IP Networking is concentrating in the United States, driven by NERC mandates for robust, secure communication infrastructure.
- MPLS:Multi-Protocol Label Switching provides a high-performance, low-latency data-carrying mechanism over IP networks, offering traffic engineering capabilities crucial for deterministic tele protection services. European utilities are increasingly adopting MPLS to manage critical protection traffic on shared communication backbones, aligning with ENTSO-E reliability guidelines.
- VPN:Virtual Private Networks establish secure, encrypted connections over public or private networks, protecting sensitive tele protection data from unauthorized access.
- Satellite Communication:Satellite links provide communication redundancy and coverage for remote or geographically challenging areas where terrestrial infrastructure is impractical.
IP Networking dominates the installed base. MPLS is where expansion concentrates.
Deployment:
Deployment models reflect the operational control and infrastructure investment strategies adopted by utilities and telecom operators for their tele protection systems.
- On-Premises:These deployments involve physical hardware and software installed and managed directly within the utility's or operator's own facilities, offering maximum control and data sovereignty. Utilities in Germany prioritize on-premises solutions for critical infrastructure, adhering to strict national cybersecurity regulations.
- Cloud-Based:Cloud-based solutions leverage external data centers and services for hosting tele protection applications and data, providing scalability and reduced upfront capital expenditure. Investment in cloud-based tele protection is gaining traction in China, supported by the national 'dual carbon goals' policy accelerating smart grid digital transformation.
- Hybrid:Hybrid deployments combine elements of both on-premises and cloud-based infrastructure, allowing utilities to manage sensitive data locally while leveraging cloud flexibility for non-critical functions.
- Remote Access:Remote access solutions enable monitoring and control of tele protection systems from off-site locations, enhancing operational efficiency and response times.
Traditional on-premises deployments remain prevalent due to security concerns. Cloud-based and hybrid models are gaining traction as utilities seek operational flexibility.
End User:
Different end-user categories exhibit distinct requirements and procurement behaviors for tele protection solutions, influenced by their core business objectives and regulatory environments.
- Telecom Operators:These entities provide the communication infrastructure for tele protection, focusing on network reliability, latency assurance, and compliance with industry standards. Telecom operators in the United States are investing in advanced tele protection solutions to support grid modernization mandates from NERC.
- Government Agencies:Government bodies often own or regulate critical infrastructure, demanding highly secure, resilient tele protection systems to ensure national security and public safety. Chinese government agencies are driving demand for advanced tele protection as part of extensive smart grid projects.
- Enterprises:Large industrial enterprises with their own power generation or distribution infrastructure require tele protection to ensure operational continuity and protect valuable assets.
- Service Providers:These companies offer specialized services, including managed tele protection, network integration, and cybersecurity, to utilities and other end-users.
Telecom operators are foundational to tele protection infrastructure. Government agencies are driving significant investment in advanced systems.
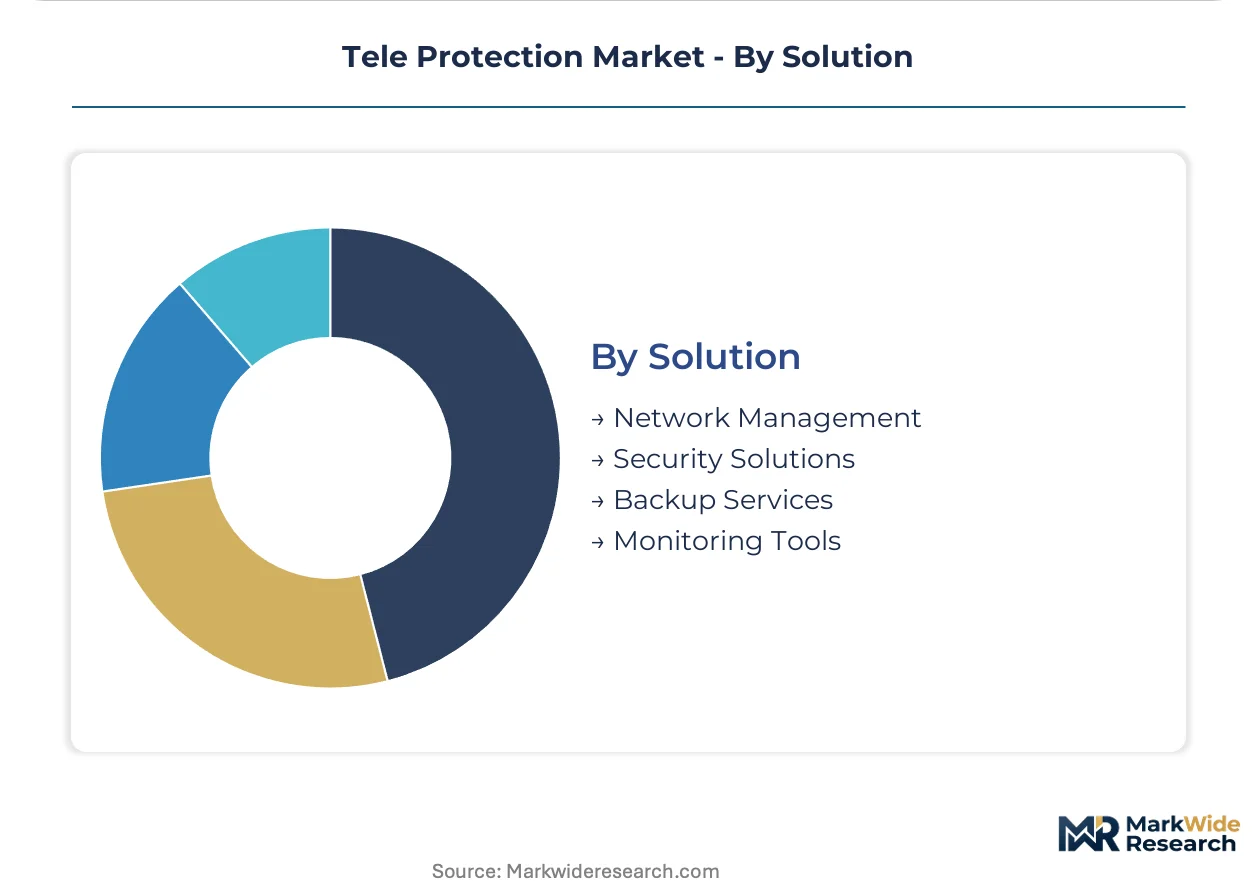
Solution:
The solution segment categorizes the specific functionalities and services offered within the tele protection ecosystem, addressing various operational and security needs.
- Network Management:These solutions encompass tools and platforms for configuring, monitoring, and maintaining the communication networks that support tele protection, ensuring optimal performance and availability. Utilities in Germany are enhancing network management capabilities to meet stringent ENTSO-E reliability standards.
- Security Solutions:This category includes hardware and software designed to protect tele protection systems from cyber threats, ensuring data integrity, confidentiality, and system resilience. Security solutions represent the fastest-growing solution category, driven by heightened cybersecurity concerns among telecom operators and government agencies.
- Backup Services:Backup services provide redundancy for tele protection communication channels and data, ensuring continuous operation even during primary system failures.
- Monitoring Tools:These tools provide real-time visibility into the performance and health of tele protection systems, enabling proactive fault detection and rapid response.
Network Management forms the operational backbone for tele protection. Security Solutions are becoming increasingly critical for grid resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National grid modernization policies and stringent reliability mandates are significantly influencing teleprotection market demand across diverse geographies. Governments are driving investments in smart grid technologies to enhance grid stability and integrate renewable energy sources. This focus on infrastructure upgrades is creating distinct regional growth patterns.
United States
United States utilities are heavily investing in teleprotection systems due to extensive grid modernization initiatives. NERC mandates for robust, secure communication infrastructure drive demand for IP Networking solutions. The Pacific Northwest, with its significant hydropower assets, is a focal point for advanced protection system deployments.
Germany
German energy companies are enhancing network management capabilities to meet stringent ENTSO-E reliability standards. National cybersecurity regulations compel utilities to prioritize secure on-premises teleprotection deployments. The industrial heartland of North Rhine-Westphalia is witnessing significant upgrades in substation automation.
China
China's national 'dual carbon goals' policy is accelerating substantial investments in smart grid technologies. This policy drives demand for advanced teleprotection systems to manage bidirectional power flows. The Yangtze River Delta region, a hub for industrial growth, is seeing rapid deployment of new digital grid infrastructure.
India
India is undertaking massive grid expansion and modernization projects, presenting significant greenfield opportunities for teleprotection. National infrastructure development initiatives support the adoption of advanced communication technologies. The rapidly urbanizing region of Maharashtra is a key area for new smart grid deployments.
Brazil
Brazil's grid modernization efforts focus on enhancing stability and integrating growing renewable energy capacities. Regulatory incentives are encouraging utilities to upgrade their protection and communication systems. Utilities in São Paulo state are particularly active in deploying advanced teleprotection solutions for urban and industrial areas.
Tele Protection Market Key Industry Players
Player mix skews toward established industrial conglomerates with deep energy sector expertise, alongside specialized communication technology firms. The competitive landscape features a blend of legacy system providers adapting to new communication protocols and agile software-centric entrants. Strategic archetypes include integrated solution providers, communication infrastructure specialists, and niche operational technology (OT) cybersecurity vendors. Companies are increasingly pursuing strategic partnerships and portfolio diversification to offer comprehensive, secure teleprotection solutions.
Within the integrated solution provider archetype, Siemens AG exemplifies a strong position by leveraging its extensive expertise in both energy and automation systems, offering comprehensive teleprotection solutions. Schneider Electric competes by focusing on digital transformation solutions specifically for energy management, addressing modern grid requirements with a software-centric approach. Cisco Systems anchors its position as a communication infrastructure specialist, providing the secure, IP-based networking essential for modern teleprotection deployments, particularly crucial for ensuring cyber resilience and low-latency communication across the grid.
| Leading Market Players |
|---|
| Cisco Systems |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Hitachi Energy |
| ABB Power Grids |
| Siemens AG |
| Abb Ltd |
| EnerNex |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
Lifecycle management agreements, increasingly adopted by utilities, lock in long-term service provision and provide predictable revenue streams for vendors. This shift influences both access to specialized teleprotection components and overall price visibility across the grid modernization lifecycle.
Pricing Analysis
IEC 61850 standard compliance creates the primary spread in teleprotection system pricing, reflecting integration complexity and interoperability guarantees. Project-based pricing models dominate initial deployments, while managed service models (TPaaS) offer subscription-tiered options for ongoing support. Cybersecurity features and ultra-low latency performance command a premium, driven by NERC and ENTSO-E mandates. Smaller utility cooperatives often exhibit higher price sensitivity compared to large telecom operators and government agencies, leading to pricing softness in basic solutions.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized networking hardware and communication modules, impact the final price of teleprotection systems. Supply concentration for critical components primarily rests in manufacturing hubs like China and Germany. Geopolitical tensions introduce a structural risk for sourcing essential semiconductors and advanced communication equipment. Distribution typically runs through direct sales channels to large utilities and telecom operators, supplemented by specialized system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The teleprotection market presents a significant service-attach opportunity, with managed service models like Teleprotection-as-a-Service (TPaaS) expanding faster than traditional hardware sales. This recurring revenue stream encompasses vital software updates, security patching, and network management.
For Market Incumbents: Secure long-term lifecycle management agreements with utilities by integrating advanced cybersecurity and NERC CIP compliance into core offerings. Siemens AG and Schneider Electric should deepen expertise in software-defined architectures to counter agile software-centric entrants. Investing in localized support and specialized engineering talent across developed markets helps mitigate the threat of a skills gap.
For New Entrants and Emerging Players: Differentiate on specialized software-defined networking (SDN) solutions and comprehensive OT cybersecurity platforms. Target emerging economies like India and Brazil, which represent greenfield opportunities without extensive legacy infrastructure. A go-to-market strategy focused on Teleprotection-as-a-Service (TPaaS) can penetrate utilities seeking to convert capital expenditures to operating expenses, offering operational flexibility.
For Investors and Strategic Acquirers: Capital is best deployed toward software-centric firms specializing in OT cybersecurity and advanced network management for critical infrastructure. The long-term viability of teleprotection hinges on robust cyber-resilience and interoperability with evolving grid standards. An acquisition target archetype includes niche providers with proven SDN capabilities or deep expertise in IEC 61850 implementation. The widespread adoption of TPaaS by major utilities serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Development | Enhances network flexibility and enables dynamic prioritization of critical teleprotection traffic. |
| OT Cybersecurity Integration | Protects critical grid infrastructure from escalating cyber threats and ensures data integrity. |
| Managed Service Model Launch | Allows utilities to convert capital expenditure to operational expenditure, outsourcing complex network management. |
| IEC 61850 Interoperability Enhancement | Facilitates seamless communication between diverse intelligent electronic devices in substations. |
| Emerging Market Grid Modernization Partnerships | Captures greenfield opportunities in countries undertaking large-scale grid expansion. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this analysis. Primary insights were gathered from utility planning officers, telecom network architects, system integrators, and government agency representatives. Secondary data sources included NERC compliance reports, ENTSO-E guidelines, national smart grid policy documents from China and India, and vendor whitepapers. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Sensitivity analysis was applied to key market drivers and restraints to project the teleprotection market across the analysis window. The analytical framework modeled segmentation across technology, deployment, end-user, solution, and regional grid maturity. Compound Annual Growth Rates were derived from historical adoption trends and projected investment in grid modernization. Key forecast inputs included regulatory compliance timelines and smart grid investment allocations.
Material uncertainties—such as unforeseen geopolitical events impacting critical component supply chains or rapid technological obsolescence—sit outside the modeled envelope. Forecasts reflect assumptions documented based on current market intelligence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market