
 Japan Surveillance Camera Market | 2026-2036
Japan Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Surveillance Camera Market Insights
Buyer concentration among Japan's municipal governments and railway operators is hardening as procurement consolidates under national infrastructure programs. Panasonic i-PRO Sensing Solutions leverages its domestic manufacturing footprint to anchor supply relationships with prefectural police departments. Hikvision Digital Technology competes through cost-engineered IP camera portfolios tailored to mid-tier commercial installations. Sony Corporation differentiates via image sensor R&D that sustains low-light performance leadership in critical infrastructure deployments.
A surveillance camera integrates an image sensor, optical lens, and video processing unit to capture, encode, and transmit visual data for real-time monitoring or forensic analysis; Japanese manufacturers emphasize wide dynamic range and edge-based AI analytics compliant with JIS standards. Dome cameras dominate indoor banking and retail applications where vandal resistance and discreet positioning matter, while PTZ units command premium positioning in transportation hubs requiring active operator control. IP technology is displacing analog and HD-TVI architectures as NTT and regional telcos expand fiber-enabled backhaul across secondary cities.
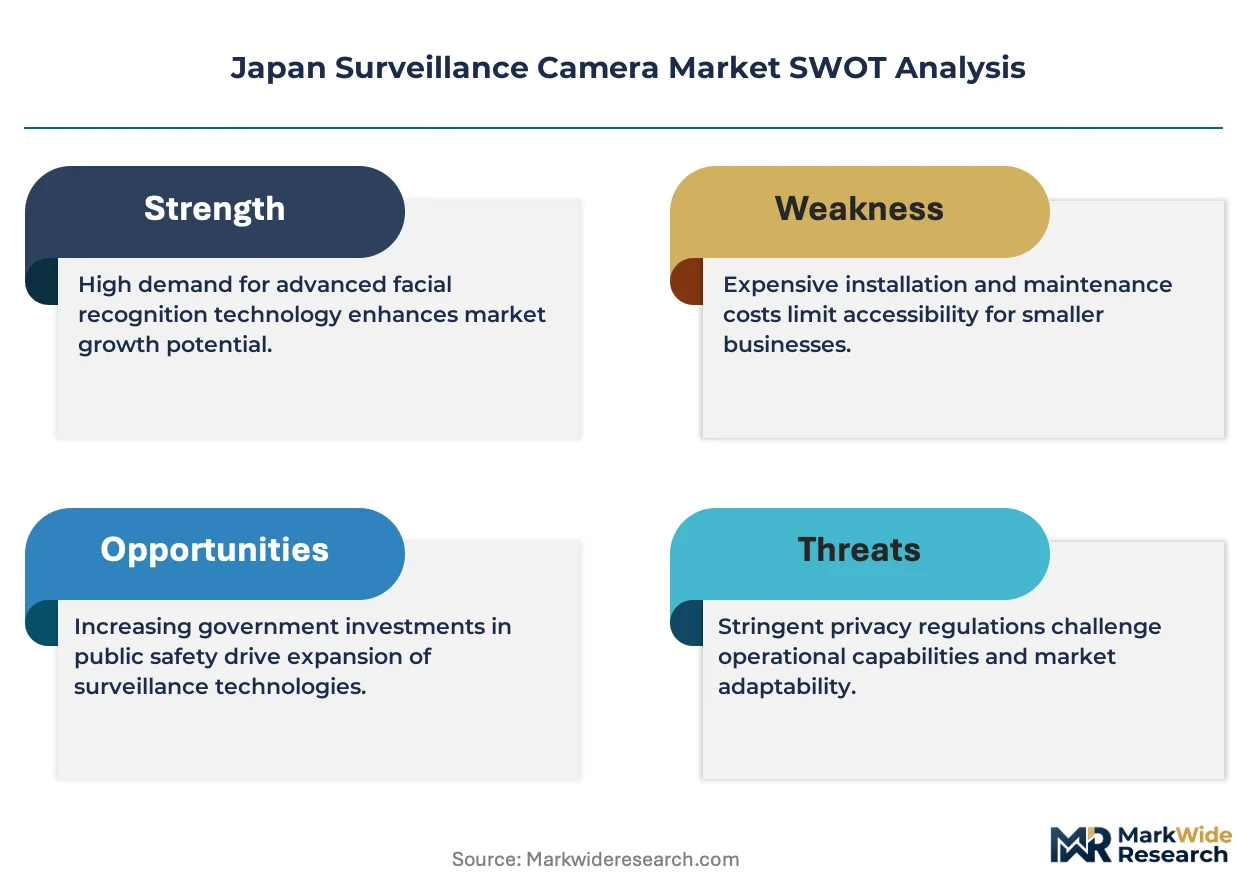
METI's cybersecurity certification framework and the Personal Information Protection Commission's guidelines on facial recognition govern product design and deployment permissions across Japanese jurisdictions. JIS standards for electromagnetic compatibility and environmental durability shape manufacturing requirements for outdoor installations in typhoon-prone coastal zones. Stakeholders must monitor whether METI tightens domestic content thresholds for public-sector tenders, as this would reshape supplier eligibility and component sourcing strategies.
Market Dynamics
Japan's surveillance camera market is being fundamentally restructured by the forced migration from analog to IP architectures, as NTT and regional telecommunications carriers extend fiber-optic backhaul into secondary cities and municipal governments mandate encrypted, domestically certified systems for public safety networks.
Growth Catalysts
- METI Cybersecurity Certification:The Ministry of Economy, Trade and Industry's encryption standards for critical infrastructure are mandating domestic certification for all public-sector camera deployments, creating guaranteed demand for compliant Japanese manufacturers.
- Smart City Infrastructure:Tokyo, Osaka, and Fukuoka are expanding video surveillance networks under national disaster response programs, driving bulk procurement of AI-enabled equipment for real-time monitoring.
- Railway Modernization:Japan Railways Group operators are replacing legacy analog systems with PTZ-capable IP cameras across stations and rolling stock, prioritizing wide dynamic range sensors for tunnel and platform coverage.
Market Restraints
- Image Sensor Supply Concentration:Advanced CMOS sensor production concentrates among a handful of foundries in Taiwan and South Korea, exposing Japanese camera assemblers to geopolitical supply disruption and allocation constraints.
- Domestic Content Cost Premium:JIS-certified components and local manufacturing carry 15-25% cost premiums over imported alternatives, compressing margins for mid-tier commercial installations where price sensitivity dominates.
- Facial Recognition Regulatory Friction:The Personal Information Protection Commission's strict guidelines on biometric data collection are limiting deployment permissions in retail and private commercial settings, constraining addressable market expansion.
Strategic Opportunities
- Hokkaido and Tohoku Underpenetration:Secondary cities and rural prefectures lag Tokyo-Osaka corridor in fiber-enabled surveillance density, presenting first-mover advantage for IP camera vendors with regional distribution partnerships.
- Edge AI Analytics Convergence:On-device machine learning inference combined with 5G low-latency transmission is enabling real-time anomaly detection without cloud dependency, opening premium pricing for critical infrastructure applications.
- Disaster Response Mandate Expansion:The Cabinet Office's evolving standards for earthquake and tsunami early-warning integration are creating regulatory tailwinds for cameras with environmental sensor fusion capabilities.
Industry Challenges
- Embedded Systems Engineering Talent Gap:Japanese manufacturers face acute shortages of firmware developers capable of integrating edge-based AI analytics with JIS-compliant hardware architectures, slowing product development cycles.
- Legacy Analog Integration Complexity:Municipal governments and railway operators maintain extensive installed bases of coaxial-cable infrastructure, forcing costly hybrid deployment strategies during phased IP migrations.
- Multi-Agency Certification Timelines:Simultaneous METI cybersecurity review, JIS electromagnetic compatibility testing, and prefectural police technical validation extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Surveillance Camera Market |
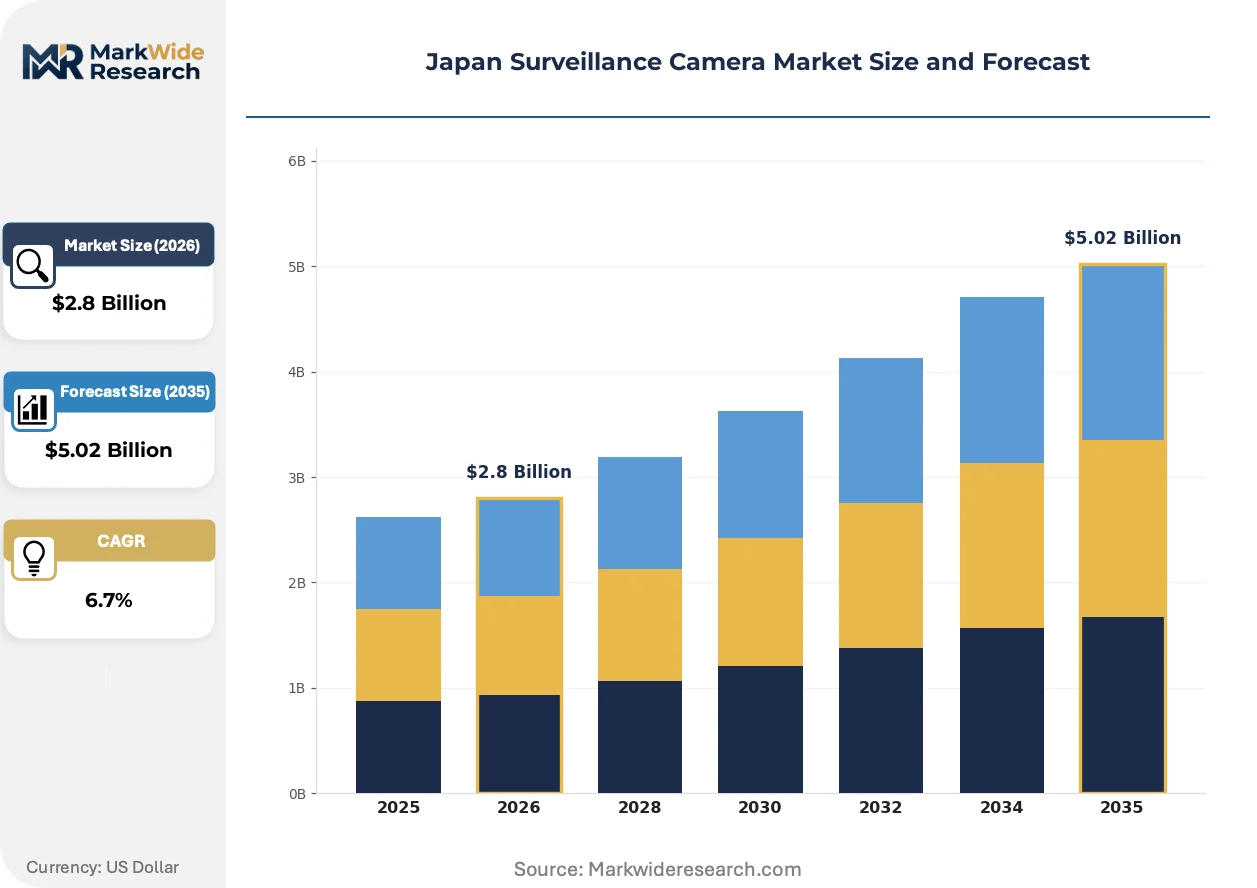
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, Box Technology: Analog, IP, HD-TVI, Wireless Application: Retail, Transportation, Banking, Residential End User: Government, Commercial, Industrial, Educational |
| Companies Covered | Panasonic i-PRO Sensing Solutions, Japan Security System Corporation, Hikvision Digital Technology, Bosch Security Systems, Hanwha Techwin, Dahua Technology, Axis Communications, Honeywell Security, Sony Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Surveillance Camera Market Trends and Innovations
Active technological and regulatory forces are compressing product lifecycles and reshaping competitive positioning across Japan's surveillance camera value chain, with particular intensity in sensor architecture, compliance frameworks, and procurement methodologies.
Wide dynamic range CMOS image sensors with starlight-level low-light sensitivity are overtaking conventional sensor architectures in transportation and critical infrastructure deployments. Tokyo Metro and JR East are specifying these sensors for platform and tunnel monitoring where lighting conditions fluctuate dramatically. This capability is overtaking resolution specifications as the primary technical discriminator in municipal tender evaluations.
METI's cybersecurity certification framework is tightening domestic content and encryption standards for all public-sector surveillance procurements. Manufacturers must now demonstrate in-country firmware development and supply chain traceability to qualify for national infrastructure programs. Railway operators and prefectural police departments are responding by consolidating vendor relationships around domestically certified suppliers with proven JIS compliance histories.
Municipal procurement officers are bundling long-term maintenance and software update subscriptions into initial capital tenders, unbundling the traditional equipment-only purchasing model. System integrators and regional telecommunications carriers are capturing this service revenue stream, displacing pure hardware vendors from ongoing customer relationships. This pattern is most visible in Kanto region smart city projects where Tokyo Metropolitan Government mandates ten-year total-cost-of-ownership evaluation criteria.
Japan Surveillance Camera Market Segmentation
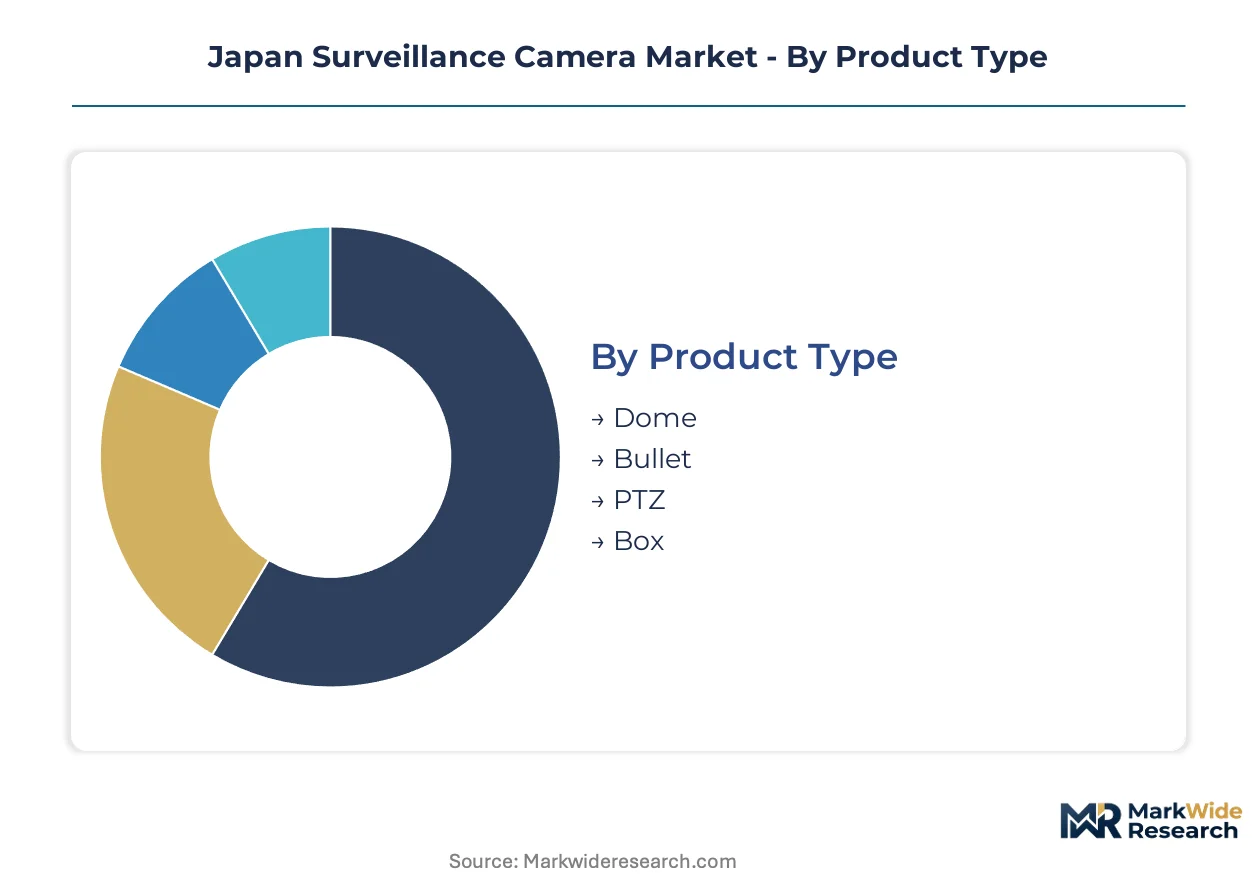
Japan's surveillance camera market fragments across four critical dimensions that determine procurement specifications, certification requirements, and vendor eligibility. Product type and technology architecture decisions cascade through application suitability and end-user compliance obligations, with METI cybersecurity mandates and JIS standards filtering available choices at each decision node.
Product Type:
Dome and bullet units function as standalone perimeter solutions, while PTZ and box cameras embed within integrated command infrastructure requiring active operator interfaces.
- Dome:Enclosed hemispherical housings with vandal-resistant polycarbonate domes protect internal PTZ mechanisms and fixed lenses from physical tampering. Demand clusters in Tokyo Metro banking branches and Osaka retail complexes where discreet ceiling mounting and 360-degree coverage eliminate blind spots; METI's public safety encryption mandates favor domestically certified dome suppliers for municipal tender participation.
- PTZ:Pan-tilt-zoom mechanisms enable real-time operator control over horizontal rotation, vertical tilt, and optical zoom ranges exceeding 30x magnification. JR East and West Japan Railway Company specify these for platform monitoring across Shinkansen terminals where active tracking of passenger flow anomalies supports disaster response protocols; fiber-enabled backhaul expansion into secondary cities is extending addressable deployment beyond the Tokyo-Osaka corridor.
- Bullet:Cylindrical weatherproof housings with integrated infrared illuminators deliver fixed-view perimeter surveillance for outdoor installations.
- Box:Modular camera bodies accepting interchangeable C/CS-mount lenses provide specialized optical configurations for machine vision and scientific applications.
Volume placements concentrate in dome configurations; the faster expansion belongs to PTZ units driven by railway modernization timelines.
Technology:
Cost tier separation runs deepest here, with analog and HD-TVI occupying budget-constrained retrofit scenarios while IP and wireless command premium positioning in new infrastructure.
- IP:Network-enabled cameras transmitting H.265-encoded video over Ethernet infrastructure with Power-over-Ethernet power delivery and edge-based analytics processing. NTT's fiber expansion into Fukuoka and Sapporo secondary markets is accelerating displacement of legacy architectures; municipal governments now mandate encrypted IP protocols for all public safety network participation.
- Wireless:Wi-Fi 6 and 5G-enabled cameras eliminating structured cabling requirements for temporary deployments and heritage building installations. Tokyo Metropolitan Government's smart city pilot programs specify wireless units for disaster-response mobile command centers where infrastructure damage prevents fixed network reliance; battery and solar power integration extends operational autonomy in grid-compromised scenarios.
- Analog:Coaxial-cable-based CVBS signal transmission persists in rural prefectures with limited fiber penetration.
- HD-TVI:High-definition transport video interface bridges analog infrastructure with 1080p resolution over existing coaxial plant.
Deployment volumes still favor IP architectures; wireless configurations are climbing the fastest as 5G low-latency backhaul reaches commercial viability.
Application:
Customer maturity separates segments, with transportation and banking representing compliance-heavy early adopters while retail and residential lag in certification sophistication.
- Transportation:Railway stations, airports, and bus terminals requiring wide dynamic range sensors for tunnel-to-platform lighting transitions and real-time crowd density analytics. JR Group operators consolidate procurement under ten-year total-cost-of-ownership frameworks that bundle hardware, software maintenance, and cybersecurity update subscriptions; this pattern is displacing pure equipment vendors from ongoing revenue streams.
- Banking:Financial institutions subject to Financial Services Agency guidelines on physical security and customer privacy protection. Major Tokyo and Osaka banks specify JIS-certified dome cameras with facial masking capabilities to comply with Personal Information Protection Commission restrictions on biometric data retention; vault and ATM monitoring applications prioritize edge-based encryption to minimize cloud transmission risks.
- Retail:Department stores and convenience chains deploying loss prevention and customer flow analysis systems.
- Residential:Single-family and multi-unit dwelling installations driven by insurance premium reductions and neighborhood watch programs.
Transportation maintains the largest installed base; retail applications are gaining share fastest as facial recognition restrictions ease for non-biometric analytics.
End User:
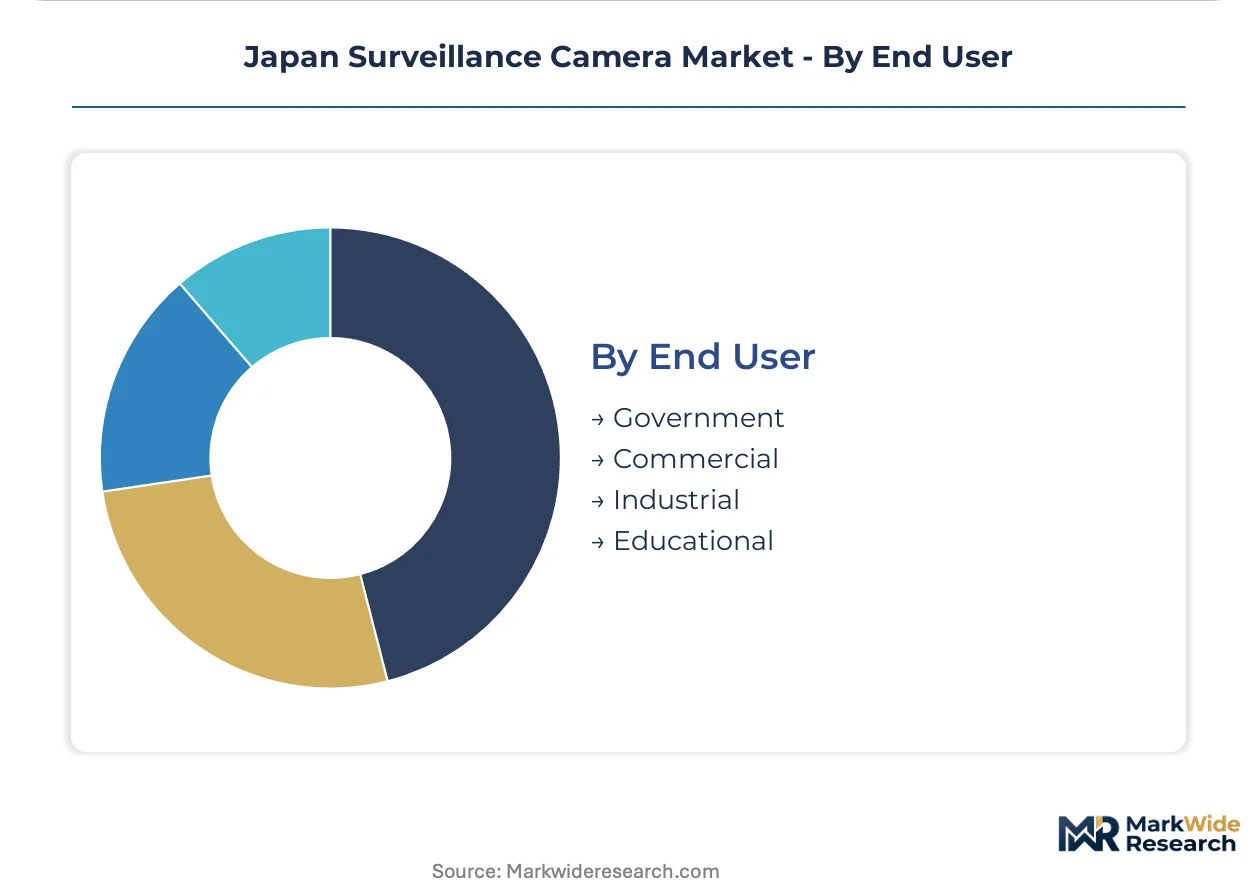
Procurement scale and certification intensity vary sharply, with government and commercial segments dominating volume while industrial and educational represent emerging specification battlegrounds.
- Government:Prefectural police departments, municipal disaster response agencies, and national infrastructure operators subject to Act on the Protection of Specially Designated Secrets compliance. The Cabinet Office's earthquake early-warning integration standards are mandating environmental sensor fusion capabilities; METI's domestic content thresholds favor Japanese manufacturers with in-country firmware development.
- Commercial:Office buildings, hotels, and logistics facilities balancing security coverage against operational budget constraints. Mid-tier commercial buyers in Nagoya and Hiroshima commercial districts exhibit acute price sensitivity, compressing margins for vendors unable to achieve scale economies; regional system integrators capture recurring maintenance revenue through managed service contracts.
- Industrial:Manufacturing plants and critical infrastructure facilities requiring explosion-proof and corrosion-resistant housings.
- Educational:Universities and K-12 institutions deploying campus-wide surveillance for student safety and facility protection.
Government procurement commands the highest unit values; commercial volume dominates aggregate placements with industrial segments showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates heavily in Japan's major metropolitan corridors, with procurement patterns diverging sharply between fiber-enabled urban centers and infrastructure-lagging rural prefectures. Municipal governments and railway operators anchor volume, while regulatory fragmentation across prefectural jurisdictions shapes vendor eligibility.
Kanto/Tokyo
Tokyo Metropolitan Government's smart city infrastructure drives bulk procurement of AI-enabled surveillance equipment for disaster response networks. METI's cybersecurity certification mandates filter vendor participation, favoring domestic manufacturers with in-country firmware development. JR East's station modernization across the Greater Tokyo Area specifies wide dynamic range PTZ cameras for platform monitoring.
Kansai/Osaka
Osaka Prefecture's municipal safety programs expand video surveillance density across commercial districts and transit hubs. The Personal Information Protection Commission's facial recognition guidelines constrain retail deployment permissions, pushing demand toward banking and transportation applications. Kansai International Airport's security upgrades exemplify premium-tier procurement bundling decade-long maintenance subscriptions.
Chubu/Nagoya
Nagoya's industrial corridor generates specialized demand for explosion-proof camera housings in manufacturing facilities. Mid-tier commercial buyers exhibit acute price sensitivity, compressing margins for vendors lacking scale economies. Regional system integrators capture recurring revenue through managed service contracts with logistics and warehousing operators.
Kyushu/Fukuoka
Fukuoka City's disaster response infrastructure investments accelerate IP camera deployment under national program funding. NTT's fiber expansion into secondary Kyushu markets enables encrypted backhaul for municipal safety networks. Local prefectural police departments consolidate vendor relationships around JIS-certified suppliers with proven compliance histories.
Hokkaido and Tohoku
Rural prefectures lag the Tokyo-Osaka corridor in surveillance density, presenting first-mover opportunities for IP vendors with regional distribution partnerships. Legacy analog infrastructure persists in areas with limited fiber penetration, forcing costly hybrid deployment strategies. The Cabinet Office's earthquake early-warning integration standards are mandating environmental sensor fusion capabilities in new installations.
Japan Surveillance Camera Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-AI analytics and wireless deployment specializations. The vendor base stratifies across three tiers: domestic manufacturers with METI certification heritage, cost-engineered international suppliers targeting mid-tier commercial segments, and sensor technology specialists leveraging R&D differentiation. Market structure reflects procurement consolidation under national infrastructure programs, with railway operators and prefectural police departments narrowing vendor panels. Dominant competitive moves include backward integration into firmware development to satisfy domestic content thresholds, and strategic partnerships with regional telecommunications carriers to capture recurring service revenue.
Among Japan-based entities, Panasonic i-PRO Sensing Solutions and Japan Security System Corporation exemplify the domestically certified tier, anchoring supply relationships with public-sector buyers through JIS compliance and in-country manufacturing footprints. Sony Corporation occupies a distinct technology-specialist position, representing sensor R&D leadership that sustains premium positioning in critical infrastructure deployments. Hikvision Digital Technology and Dahua Technology exemplify cost-engineered international suppliers, competing through IP camera portfolios tailored to price-sensitive commercial installations where certification requirements permit non-domestic sourcing.
| Leading Market Players |
|---|
| Panasonic i-PRO Sensing Solutions |
| Japan Security System Corporation |
| Hikvision Digital Technology |
| Bosch Security Systems |
| Hanwha Techwin |
| Dahua Technology |
| Axis Communications |
| Honeywell Security |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-decade JIS certification heritage anchor premium pricing power through captive firmware development and in-country manufacturing footprints, while cost-engineered international suppliers compress margins in mid-tier commercial segments where municipal procurement consolidates under METI mandates.
Pricing Analysis
Volume placements concentrate in economy-tier IP dome configurations for commercial installations, while premium-tier PTZ units with wide dynamic range sensors and edge-AI analytics command sustained margins in railway modernization programs. Price differentiation hinges on METI cybersecurity certification tier and after-sales service bundling, with ten-year total-cost-of-ownership frameworks displacing transactional equipment-only purchasing. Cost compression in mid-tier commercial segments is intensifying because regional system integrators capture recurring maintenance revenue through managed service contracts. Municipal governments and railway operators exhibit lowest price sensitivity due to regulatory compliance mandates, while mid-tier commercial buyers in Nagoya and Hiroshima commercial districts show acute price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with advanced CMOS image sensor production concentrated among foundries in Taiwan and South Korea, exposing Japanese camera assemblers to geopolitical allocation constraints. Component sourcing draws from China for optical lens assemblies, Japan for precision mechanical housings, and Taiwan for semiconductor fabrication. Raw material dependencies include rare-earth elements for sensor magnetics, polycarbonate resins for vandal-resistant dome housings, and copper for PoE Ethernet infrastructure. Tariff exposure on Chinese optical components presents structural risk as METI tightens domestic content thresholds. Distribution runs through NTT and regional telecommunications carriers extending fiber-enabled backhaul into secondary cities, with system integrators capturing downstream service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering talent scarcity constrains firmware development capacity, propping pricing for JIS-compliant edge-AI analytics as railway operators and prefectural police departments consolidate vendor panels around domestically certified suppliers.
For Market Incumbents: Anticipate margin compression from cost-engineered international suppliers by deepening backward integration into sensor calibration and firmware development to satisfy METI domestic content thresholds. Defend position by locking ten-year maintenance subscriptions with JR Group operators and Tokyo Metropolitan Government before procurement consolidation hardens vendor panels further.
For New Entrants and Emerging Players: The price-point gap between premium PTZ units and economy dome configurations opens white-space opportunity in Hokkaido and Tohoku rural prefectures where fiber expansion lags and legacy analog infrastructure persists. Target regional distribution partnerships with NTT regional carriers to capture IP camera deployment in secondary cities before domestic incumbents establish compliance histories with prefectural police departments.
For Investors and Strategic Acquirers: METI tightening domestic firmware development requirements is the leading indicator that acquisition premiums for JIS-certified specialists with in-country engineering teams will sustain across the medium-term horizon. Target mid-cap manufacturers with proven prefectural police validation histories and captive edge-AI analytics capabilities as consolidation candidates. Watch for Cabinet Office earthquake early-warning integration standards mandating environmental sensor fusion as the signal for next-generation capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Firmware Development | Satisfies METI domestic content thresholds for public-sector tender eligibility. |
| Regional Distribution Partnership with NTT Carriers | Captures IP camera deployment in Fukuoka and Sapporo fiber expansion zones. |
| Long-term Maintenance Subscription Bundling | Displaces pure hardware vendors from Tokyo smart city ten-year TCO frameworks. |
| Edge-AI Analytics Platform Launch | Enables real-time anomaly detection for JR East platform monitoring specifications. |
| JIS Certification Investment for Dome Cameras | Unlocks Osaka banking branch procurement under Financial Services Agency guidelines. |
Research Methodology
Independent corroboration across prefectural police procurement officers, JR Group infrastructure planners, METI certification auditors, and regional system integrators underwrites the qualitative findings. Primary interviews with security technology directors at major Tokyo banks, platform engineers at NTT regional carriers, and municipal disaster response coordinators combined with secondary validation from JIS electromagnetic compatibility filings, METI cybersecurity certification registries, and NTT fiber deployment disclosures. Bottom-up camera shipment estimates triangulate against top-down infrastructure budget allocations across the analysis window.
Rate-of-change decomposition separates volume expansion from value migration across technology architecture, product type, application maturity, and end-user procurement sophistication. The analytical framework models IP versus analog displacement curves, dome versus PTZ mix shifts, transportation versus retail application growth, and government versus commercial buyer concentration throughout the forecast period. CAGRs derive from infrastructure investment timelines, railway modernization schedules, and METI regulatory enforcement intensity rather than extrapolation.
Underlying measurement precision varies by segment; government procurement data carries tighter precision than mid-tier commercial estimates where informal channel sales predominate. Forecasts reflect documented assumptions about METI certification timeline enforcement, NTT fiber expansion pace, and JR Group station modernization commitments. Geopolitical sensor supply disruption, facial recognition guideline tightening by the Personal Information Protection Commission, or municipal budget austerity could materially revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
North America Crawler Camera System Market