
 Night Vision Scopes Market | 2026-2036
Night Vision Scopes Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Scopes Market Analysis
Law enforcement agencies is collapsing as the fastest-growing buyer archetype for night vision scopes, overtaking traditional military-only procurement patterns. L3Harris Technologies leverages deep vertical integration in image intensifier tube manufacturing to control supply security. Teledyne FLIR anchors its position through thermal core miniaturization for clip-on systems. Elbit Systems specializes in helmet-mounted configurations for tactical operations.
Night vision scopes are electro-optical devices that amplify ambient light or detect infrared radiation to render visible images in near-total darkness, typically employing gallium arsenide photocathodes or uncooled vanadium oxide microbolometers to achieve detection thresholds below one millilux. Their primary purpose spans military target engagement, law enforcement surveillance, and civilian wildlife observation where unaided human vision fails. Thermal imaging leads technology adoption in tactical applications where passive detection trumps image clarity, while digital night vision grows fastest in recreational hunting due to cost accessibility and recording integration. Clip-on scopes capture expanding share among military end users seeking retrofit compatibility with existing daytime optics.
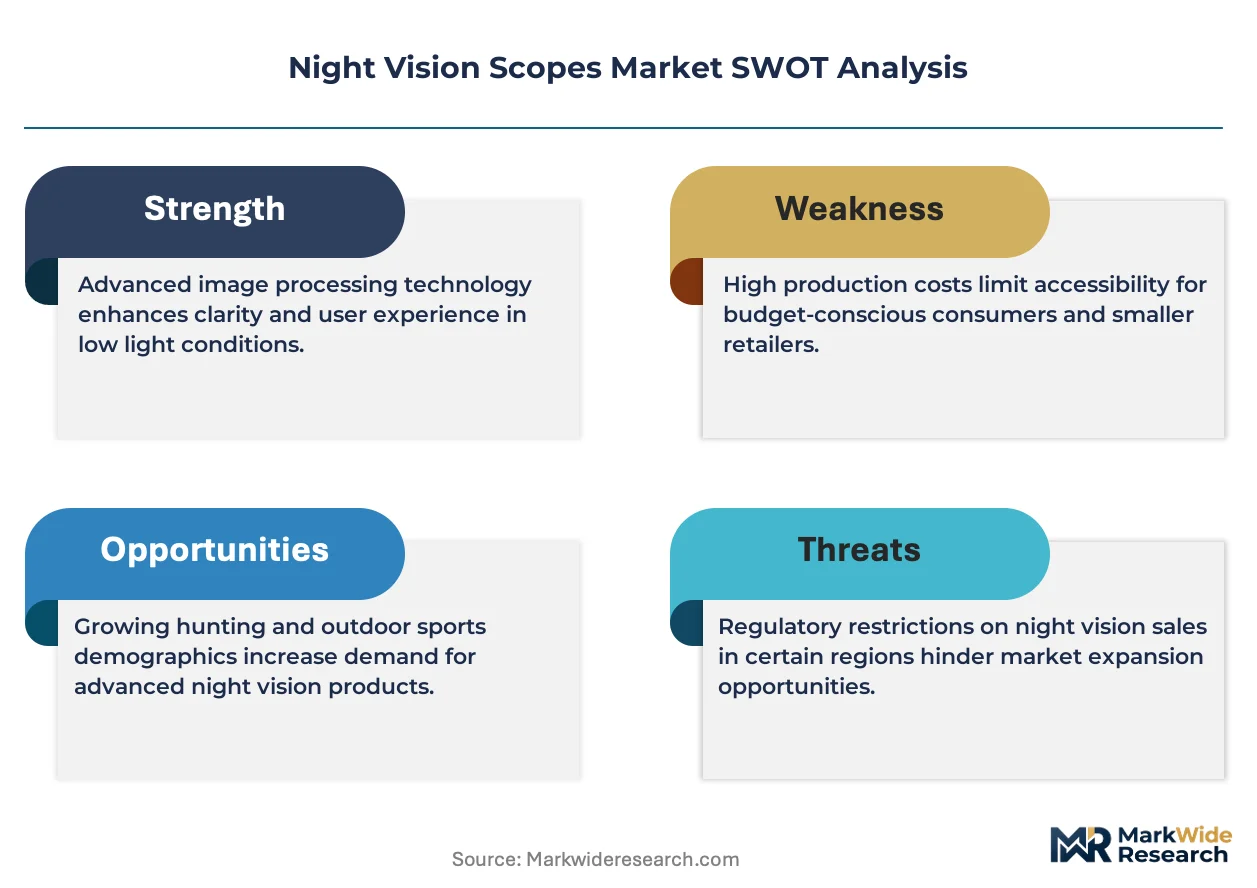
The US State Department's International Traffic in Arms Regulations restricts night vision exports through licensing thresholds on image intensifier performance, while the EU Dual-Use Regulation governs intra-bloc transfers of thermal cores above specified resolution thresholds. These frameworks fragment supplier market access and compel regional manufacturing footprints. Stakeholders must monitor evolving de minimis thresholds that could reclassify commercial-grade thermal sensors as controlled items.
Market Dynamics
Defense procurement departments across NATO member states are expanding orders for clip-on and thermal systems while tightened export control frameworks under the International Traffic in Arms Regulations constrain cross-border technology transfers.
Growth Catalysts
- Law enforcement modernization:Police departments in the United States are replacing legacy surveillance equipment with helmet-mounted thermal configurations for tactical operations. Domestic security budgets are redirecting funds toward passive detection capabilities.
- ITAR licensing thresholds:The US State Department's export control framework is creating captive demand within allied nations, compelling regional manufacturing footprints and localized supply security investments.
- Uncooled vanadium oxide microbolometers:Advances in thermal core fabrication are reducing unit costs and expanding addressable demand in civilian wildlife observation segments.
Market Restraints
- Gallium arsenide supply concentration:Photocathode substrate production clusters in limited jurisdictions, exposing image intensifier tube manufacturers to input volatility and geopolitical disruption.
- Resolution thresholds in EU Dual-Use Regulation:Thermal cores above specified performance criteria face licensing friction, fragmenting supplier market access across European member states.
- Digital night vision substitution:Cost-accessible CMOS-based alternatives are compressing demand for traditional image intensification in recreational hunting applications.
Strategic Opportunities
- India's paramilitary expansion:Border security forces are procuring clip-on scopes for retrofit compatibility with existing infantry rifles, creating untapped demand outside NATO procurement patterns.
- Recording integration convergence:Digital night vision systems with embedded video capture are opening new use cases in wildlife research and documentary production.
- Japan's METI technology incentives:Domestic manufacturers are qualifying for subsidies targeting dual-use electro-optical component localization.
Industry Challenges
- Image intensifier tube fabrication expertise:Skilled technicians for photocathode processing and vacuum sealing operations are scarce, constraining production scaling.
- ITAR compliance certification timelines:Licensing reviews for export-qualified variants extend development cycles and delay revenue recognition.
- Helmet-mounted system integration:Weight and power constraints complicate compatibility with existing soldier modernization kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Scopes Market |
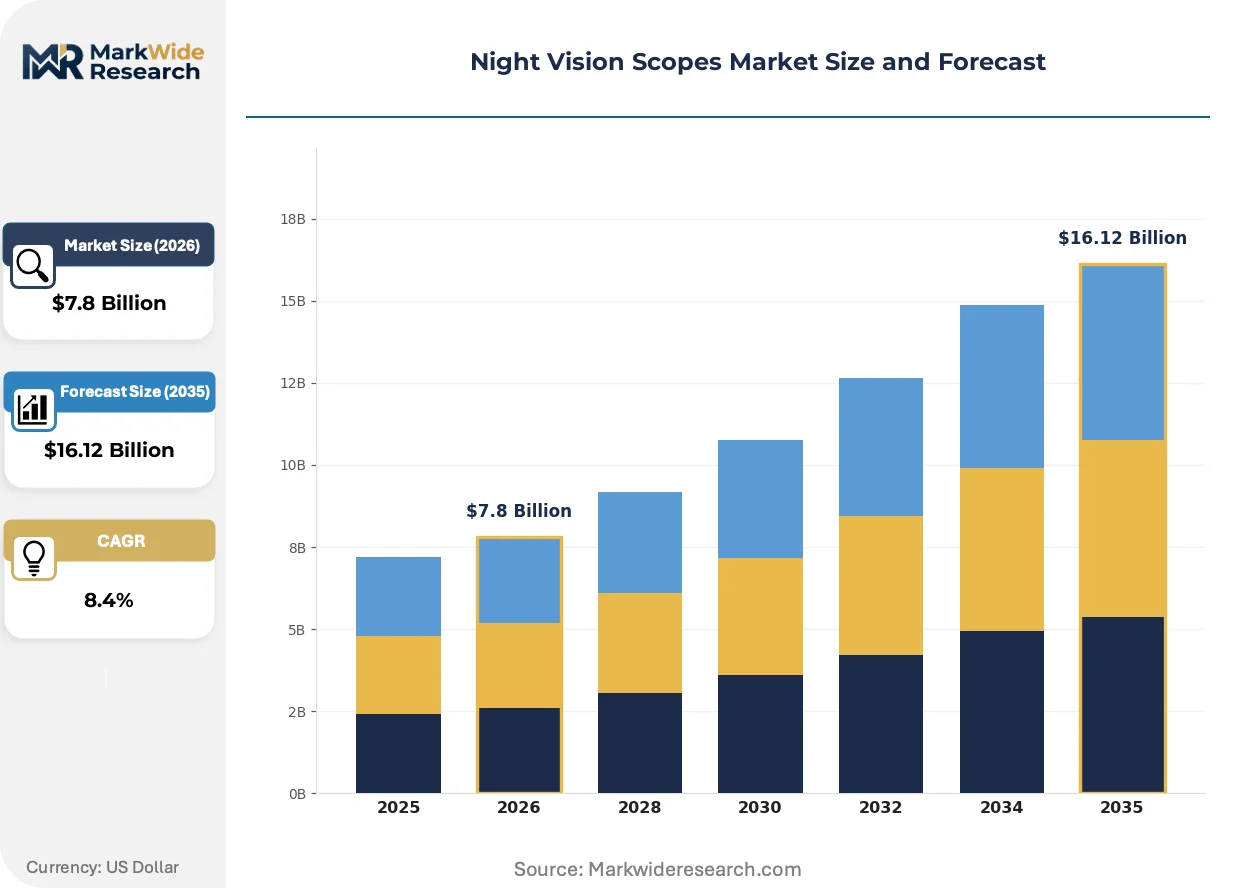
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clip-on Scopes, Monoculars, Binoculars, Goggles Technology: Image Intensification, Digital Night Vision, Thermal Imaging, Smart Night Vision End User: Military, Wildlife Observation, Law Enforcement, Hunting Application: Surveillance, Search and Rescue, Tactical Operations, Recreational Use |
| Companies Covered | L3Harris Technologies, Teledyne FLIR, BAE Systems, Raytheon Technologies, Thales Group, ATN Corp., Bushnell, Elbit Systems, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Scopes Market Emerging Trajectories
Thermal core miniaturization is compressing form factors while regulatory thresholds are reclassifying commercial-grade sensors, and procurement patterns are fragmenting across defense, law enforcement, and civilian verticals.
Uncooled vanadium oxide microbolometers are miniaturizing detection thresholds below one millilux in package sizes compatible with clip-on rifle configurations. Military end users are retrofitting existing daytime optics rather than replacing complete weapon systems. This form factor compression is miniaturizing the addressable market for standalone thermal weapon sights.
The EU Dual-Use Regulation governs intra-bloc transfers of thermal cores above specified resolution thresholds, compelling manufacturers to maintain parallel product lines. Industrial consequence includes regional manufacturing footprints and supply chain duplication. Civilian-grade variants below threshold limits are capturing expanding share in European hunting segments.
Buyer concentration is fragmenting as law enforcement agencies displace military-only procurement patterns with direct contracting authority. Traditional defense integrators are losing channel control to specialized tactical equipment distributors. This pattern is most visible in the United States where municipal police departments maintain independent acquisition budgets.
Night Vision Scopes Market Segmentation
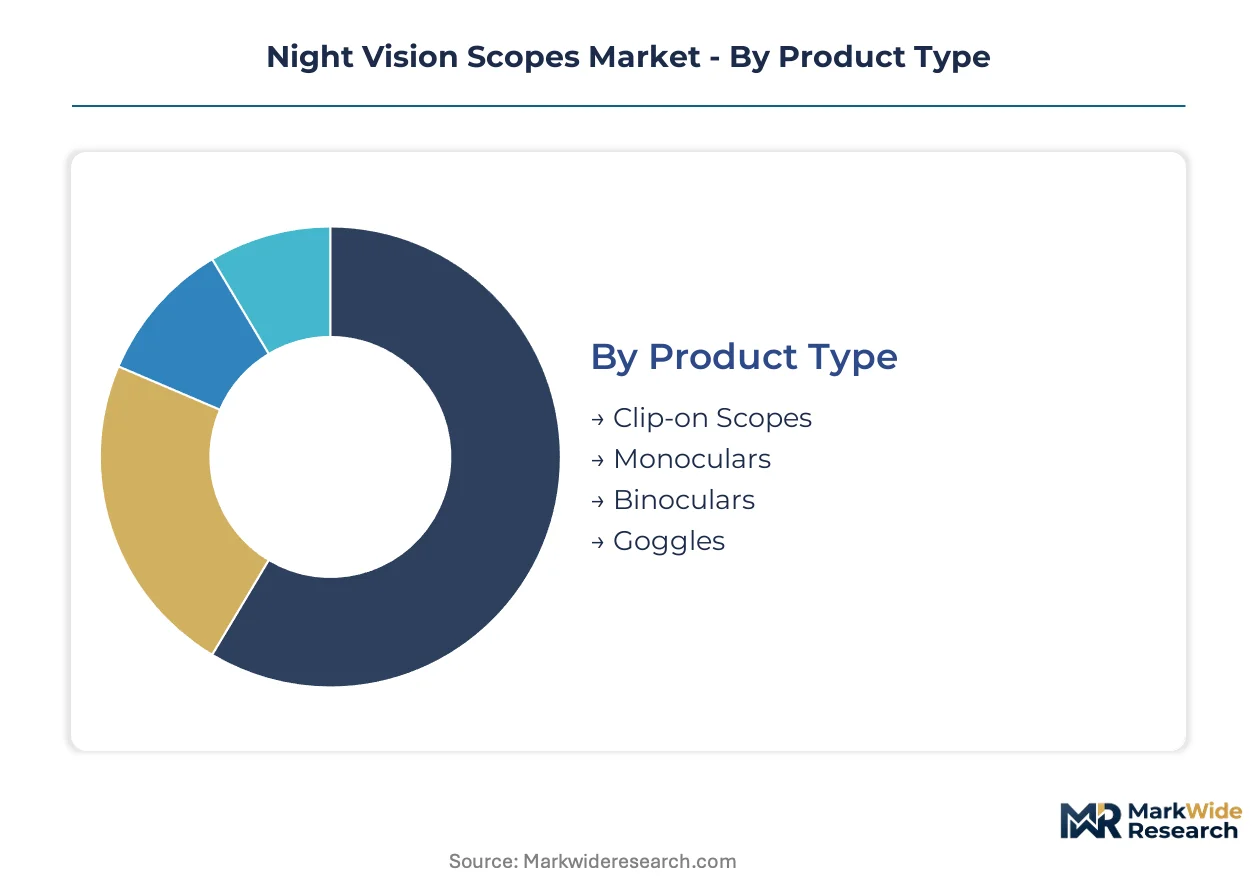
Channel access and procurement authority vary sharply across night vision scope segments. Defense integrators control military thermal systems while tactical distributors serve law enforcement clip-on demand. Recreational buyers purchase through outdoor retailers and direct-to-consumer platforms with minimal regulatory friction.
Product Type:
Defense procurement flows through prime contractors for helmet-mounted systems, while law enforcement and civilian segments distribute through specialized tactical dealers and outdoor retail channels.
- Clip-on Scopes:These retrofit devices mount forward of existing daytime optics, preserving zero and magnification settings. Military modernization programs in the United States and Germany are standardizing these for infantry rifle platforms to avoid complete weapon system replacement costs.
- Monoculars:Single-tube handheld devices dominate wildlife observation applications where weight minimization determines purchase decisions. European hunting segments in France and Germany concentrate demand for sub-500 gram configurations with extended battery life.
- Binoculars:Dual-tube stereoscopic systems serve border surveillance and maritime patrol applications requiring depth perception.
- Goggles:Helmet-mounted binocular configurations enable hands-free tactical movement during close-quarters operations.
Clip-on scopes dominate installed base in military channels. Goggles represent where expansion concentrates for law enforcement tactical units.
Technology:
Cost tiers separate procurement channels, with thermal systems commanding premium pricing through defense integrators while digital variants penetrate civilian markets through retail distribution.
- Image Intensification:Vacuum tube-based systems employing gallium arsenide photocathodes achieve detection below one millilux. ITAR licensing constraints in the United States restrict export-qualified variants to allied military procurement, creating captive domestic manufacturing.
- Digital Night Vision:CMOS sensor arrays with embedded recording capability serve recreational hunting and wildlife research segments. Cost accessibility in the United States and Canada is compressing demand for traditional image intensification in civilian applications.
- Thermal Imaging:Uncooled vanadium oxide microbolometers detect infrared radiation independent of ambient light. EU Dual-Use Regulation thresholds fragment European supplier access based on resolution specifications.
- Smart Night Vision:Sensor-fusion platforms combining intensification and thermal channels with ballistic computation software.
Thermal imaging dominates installed base in tactical military applications. Digital night vision is climbing the fastest in recreational distribution channels.
End User:
Volume concentration varies by customer type, with military orders delivering batch scale while law enforcement and civilian segments fragment across numerous small-quantity purchasers.
- Military:National defense procurement departments across NATO member states order helmet-mounted and clip-on configurations through multi-year framework agreements. United States Army modernization programs sustain the largest single-customer demand concentration globally.
- Law Enforcement:Municipal police departments and federal tactical units in the United States procure thermal monoculars and goggles through independent acquisition budgets. This segment is gaining share fastest as domestic security budgets redirect toward passive detection capabilities.
- Wildlife Observation:Academic researchers and documentary producers in Kenya and Botswana demand recording-integrated digital systems for nocturnal behavior studies.
- Hunting:Recreational shooters in Scandinavia and the United States purchase cost-accessible digital and entry-level thermal systems through outdoor retail networks.
Military end users dominate installed base. Law enforcement is where expansion concentrates as procurement authority fragments toward municipal agencies.
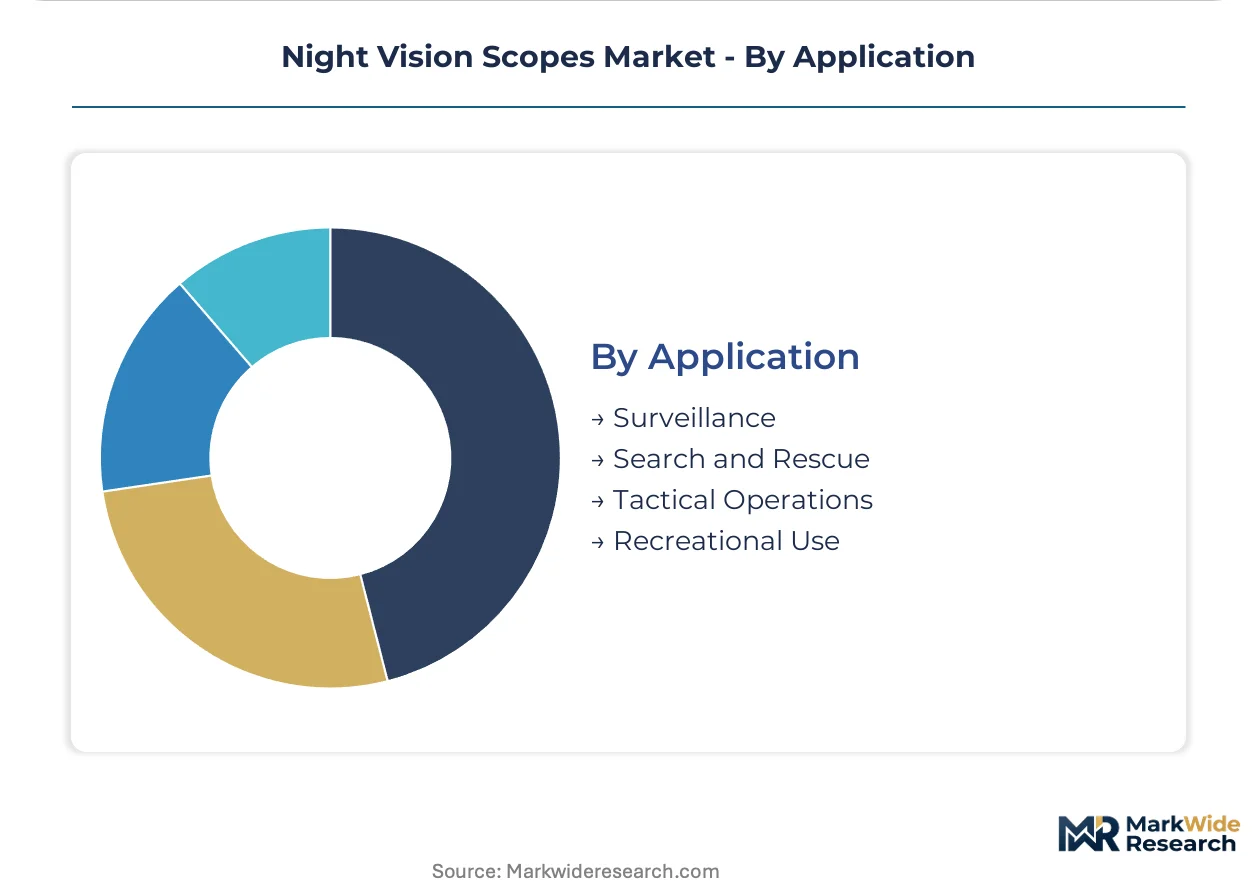
Application:
Maturity gradients separate established surveillance deployments from emerging recreational use cases, with margin profiles tightening as applications shift toward consumer price sensitivity.
- Surveillance:Continuous monitoring applications employ fixed-position thermal cameras and mobile scope systems for perimeter security. Border forces in India and Saudi Arabia are procuring clip-on scopes for retrofit compatibility with existing infantry equipment.
- Tactical Operations:Dynamic entry and close-quarters combat require helmet-mounted goggles with wide field-of-view and rapid target acquisition. Weight and power constraints complicate integration with existing soldier modernization kits across NATO forces.
- Search and Rescue:Thermal detection of human heat signatures in wilderness and disaster environments.
- Recreational Use:Night hunting and wildlife observation with recording-integrated digital systems.
Surveillance dominates installed base. Recreational use is gaining share fastest as digital cost accessibility expands addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export image intensifier tubes to NATO allies under ITAR licensing frameworks, while German thermal core producers supply intra-EU defense integrators navigating dual-use thresholds. This trade-flow structure concentrates high-performance component fabrication in jurisdictions with established regulatory carve-outs.
United States
Army modernization programs sustain procurement of helmet-mounted goggles and clip-on thermal configurations through multi-year framework agreements. The State Department's ITAR licensing creates captive domestic manufacturing for export-qualified variants. Rochester, New York hosts concentrated image intensifier tube fabrication facilities serving allied military demand.
Germany
Bundeswehr procurement departments order retrofit clip-on scopes for standard infantry rifles to avoid complete weapon system replacement. The EU Dual-Use Regulation governs intra-bloc transfers of thermal cores above specified resolution thresholds. Bavaria hosts precision electro-optical component clusters supplying defense integrators across NATO member states.
India
Border Security Force and Central Reserve Police units procure clip-on scopes for existing rifle platforms deployed along Himalayan frontiers. The Defence Procurement Procedure mandates minimum local content thresholds for electro-optical imports. Hyderabad and Bengaluru host emerging domestic assembly operations qualifying for PLI scheme incentives.
Japan
Japan Ground Self-Defense Force modernization drives demand for lightweight helmet-mounted systems compatible with existing soldier kits. METI technology incentives subsidize dual-use electro-optical component localization programs. Nagoya and Osaka metropolitan areas concentrate precision optics manufacturing with civilian-military crossover capability.
Israel
Israel Defense Forces procurement sustains demand for thermal weapon sights and fused sensor platforms for urban tactical operations. The Israeli Ministry of Defense maintains strict export licensing for thermal core technologies with resolution performance above specified thresholds. Northern industrial zones around Haifa host electro-optical R&D clusters serving domestic and selective export markets.
Night Vision Scopes Market Vendor Landscape
Player mix skews toward defense-integrated conglomerates with captive electro-optical divisions and specialized tactical equipment manufacturers serving fragmented law enforcement channels. Market structure concentrates high-performance image intensification among three vertically integrated suppliers controlling photocathode substrate supply. Strategic archetypes include: prime contractors with multi-domain defense portfolios; pure-play night vision specialists with helmet-mounted system expertise; and tactical distributors capturing municipal law enforcement procurement authority. Dominant competitive moves encompass backward integration into gallium arsenide substrate production and geographic licensing partnerships to circumvent ITAR export constraints.
Among US-based defense conglomerates, L3Harris Technologies exemplifies the vertically integrated archetype through in-house image intensifier tube manufacturing. Teledyne FLIR anchors the thermal imaging specialist tier with uncooled vanadium oxide microbolometer capabilities. Elbit Systems represents the helmet-mounted configuration specialist serving tactical operations demand. These three entities occupy distinct competitive positions without direct product overlap in core technology segments.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Teledyne FLIR |
| BAE Systems |
| Raytheon Technologies |
| Thales Group |
| ATN Corp. |
| Bushnell |
| Elbit Systems |
| Leonardo DRS |
| Others |
Supply Flow & Price Mechanics
ITAR licensing thresholds in the United States simultaneously gate supply qualification for export-capable image intensifier tubes and stratify pricing across allied military, domestic law enforcement, and commercial buyer tiers. This regulatory architecture forces manufacturers to maintain parallel production lines with divergent cost structures and margin profiles.
Pricing Analysis
Technology-generation pricing gaps separate vacuum tube-based image intensification at premium tiers from CMOS digital systems in economy positioning. Three-tier pricing structure across ITAR-restricted military, law enforcement, and civilian hunting segments reflects certification burden and performance thresholds. Cost compression in digital night vision stems from uncooled vanadium oxide microbolometer commoditization. Law enforcement agencies exhibit highest price sensitivity as municipal budgets face fixed-cost legacy obligations.
Supply Chain Analysis
Extended lead times for gallium arsenide photocathode substrates constrain inventory planning across tube manufacturers. Supply concentrates in the United States for image intensifier fabrication, Germany for precision thermal core assembly, and Japan for optical component finishing. Raw material dependencies span gallium arsenide wafers, vanadium oxide thin films, and specialized vacuum-grade glass. Single-source vulnerability in photocathode substrate production exposes manufacturers to geopolitical disruption. Distribution runs through defense integrators for military channels and tactical distributors for law enforcement procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The night vision scopes market represents a high-growth disruption as uncooled thermal core miniaturization collapses cost barriers and fragments buyer concentration beyond traditional military procurement patterns.
For Market Incumbents: Secure backward integration into gallium arsenide substrate production to insulate against photocathode supply volatility. Lock law enforcement distribution channels before municipal procurement authority fully fragments. Digital night vision substitution in civilian hunting segments threatens traditional image intensification volume. For New Entrants and Emerging Players: Differentiate on recording-integrated digital platforms targeting wildlife research and documentary production white spaces. India's paramilitary expansion offers the most penetrable geography outside NATO procurement patterns. Direct-to-researcher go-to-market models bypass entrenched defense integrator control. For Investors and Strategic Acquirers: EU Dual-Use Regulation threshold revisions reshape the acquisition landscape by reclassifying commercial-grade thermal sensors as controlled items. Five-to-ten year viability favors targets with established regional manufacturing footprints and ITAR-compliant production lines. Monitor de minimis threshold adjustments as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photocathode Substrates | Captive gallium arsenide supply secures production continuity against geopolitical input disruption. |
| Regional Manufacturing Footprint Expansion | Localized EU assembly circumvents Dual-Use Regulation licensing friction for thermal core transfers. |
| Law Enforcement Distribution Channel Control | Municipal procurement authority fragmentation creates first-mover advantage in tactical equipment distribution. |
| Recording-Integrated Digital Platform Launch | Embedded video capture opens wildlife research and documentary production use cases beyond traditional tactical demand. |
| Helmet-Mounted System Weight Reduction Program | Power and mass optimization enables compatibility with existing NATO soldier modernization kits. |
Methodological Framework
A standing panel of defense procurement officers, tactical equipment distributors, electro-optical R&D directors, and law enforcement acquisition specialists provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from ITAR licensing databases, EU Dual-Use Regulation filings, customs trade records, and defense budget appropriations documents. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across technology and end-user segments.
Consistency checks validated projection outputs against historical procurement patterns in United States Army modernization programs and Bundeswehr retrofit initiatives. The analytical framework modeled demand across product type, technology generation, end-user archetype, and application use case throughout the forecast period. CAGR derivation incorporated defense budget trajectory assumptions, thermal core cost curves, and regulatory threshold evolution. Industry-specific inputs included image intensifier tube fabrication capacity constraints and photocathode substrate supply availability.
The analysis sits within stated boundaries; outcomes outside sustained defense spending levels or stable regulatory thresholds would require recalibration. Forecasts reflect documented assumptions regarding ITAR licensing timelines, EU Dual-Use resolution thresholds, and uncooled microbolometer cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Global Alarm Monitoring Market