
 Destructible Security Labels Market | 2026-2036
Destructible Security Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Destructible Security Labels Market Analysis
ISO 17712 certification for high-security seals is redrawing competitive boundaries in destructible security labels. Brady Corporation leverages its vertical integration into materials science to sustain specification-grade product lines for defense logistics. Avery Dennison anchors global supply through controlled distribution of proprietary destructible facestocks. tesa SE specializes in adhesive formulations that fracture under mechanical stress, differentiating its portfolio from conventional tamper-evident alternatives.
Destructible security labels are pressure-sensitive constructions engineered to fragment, delaminate, or reveal hidden void messaging upon removal attempts, typically employing brittle substrates below 50-micron thickness with aggressive permanent adhesives exceeding 20 N/25mm peel strength. Their primary commercial purpose is to provide irreversible evidence of unauthorized access to packaged goods, electronic enclosures, or secure documents. Tamper evident labels occupy the largest volume share across pharmaceutical cold chain and electronics OEM applications, while digital printing technology represents the fastest-growing segment as brand owners adopt variable-data serialization for unit-level track-and-trace compliance. Polyester material grades command premium positioning due to dimensional stability in temperature-extreme logistics environments.
FDA drug supply chain regulations under the Drug Supply Chain Security Act mandate serialized tamper verification at the package level, directly expanding specification requirements for destructible label converters. EMA's Annex 11 guidelines on computerized systems and EU Falsified Medicines Directive enforcement create parallel compliance obligations for exporters serving European pharmaceutical distribution. REACH chemical restrictions on adhesive constituents further constrain formulation choices for suppliers targeting EU member states. Stakeholders must monitor evolving serialization mandates in emerging pharmaceutical manufacturing jurisdictions and assess adhesive chemistry portfolios against expanding substance restriction lists.
Market Dynamics
Digital printing technology is fragmenting production economics across destructible security labels, compressing minimum order quantities from tens of thousands to single-unit serialization while redistributing converter margins toward variable-data software licensing.
Growth Catalysts
- Drug Supply Chain Security Act:FDA mandates for serialized tamper verification at package level expand specification requirements for pharmaceutical converters serving US distribution networks.
- Polyester substrate engineering:Dimensional stability in temperature-extreme logistics environments commands premium positioning across cold chain pharmaceutical applications.
- German automotive component exports:Cross-border shipment verification requirements concentrate EU-compliant security labeling demand among Baden-Württemberg and Bavaria manufacturing clusters.
Market Restraints
- Adhesive chemistry constraints:REACH chemical restrictions on adhesive constituents limit formulation choices for suppliers targeting EU member states.
- Substrate supply concentration:Brittleness-engineered polyester films below 50-micron thickness rely on concentrated specialty film extrusion capacity in Japan and South Korea.
- Mechanical stress threshold limitations:Conventional tamper-evident alternatives fracture unpredictably in high-humidity logistics corridors, creating authentication ambiguity.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO serialization mandates for export-oriented formulation units create first-mover advantage for converters establishing local specification-grade production.
- RFID-destructible hybrid convergence:Integration of passive RFID inlays with fracture-prone substrates enables unit-level track-and-trace without secondary label application.
- Brazilian generic drug distribution:ANVISA track-and-trace implementation timelines open white space for tamper-evident label converters ahead of full serialization enforcement.
Industry Challenges
- ISO 17712 certification timelines:High-security seal specification testing extends product qualification cycles by 8-14 months for defense logistics suppliers.
- Variable-data workflow integration:Pharmaceutical contract packagers face legacy line equipment retrofit costs to accommodate serialized destructible label application at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Destructible Security Labels Market |
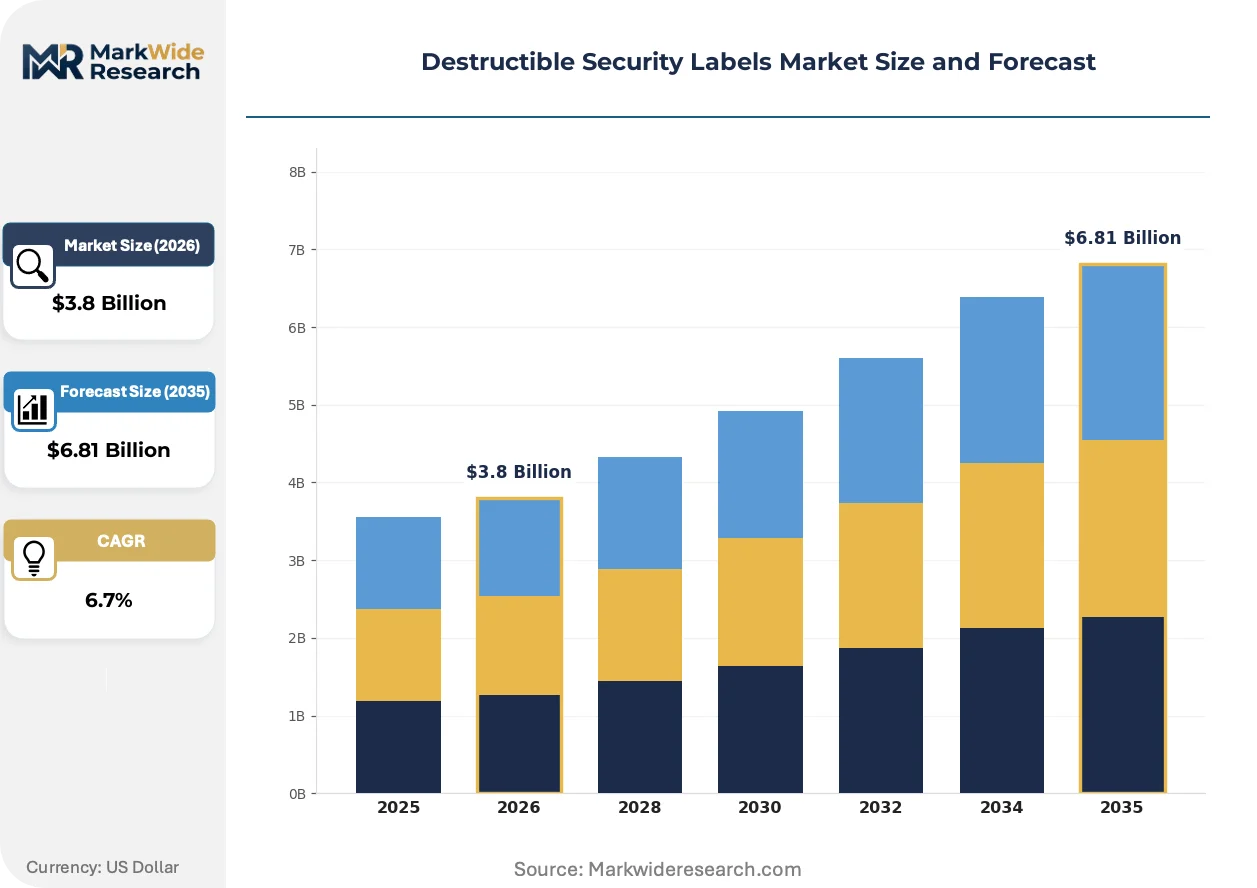
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tamper Evident Labels, Void Labels, Breakable Labels, Security Seals Application: Pharmaceuticals, Electronics, Document Security, Retail Material: Polyester, Paper, Vinyl, Polypropylene Technology: Digital Printing, Flexographic Printing, Lithographic Printing, Screen Printing |
| Companies Covered | 3M, Avery Dennison, Brady Corporation, Shosky Security, CCL Industries, UPM Raflatac, tesa SE, SECURITAG, B-Sealed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Destructible Security Labels Market Emerging Trajectories
Three intersecting developments are restructuring how destructible security labels are specified, produced, and deployed across pharmaceutical and electronics supply chains.
Digital inkjet serialization with inline die-cutting is displacing flexographic and screen-printing analog methods for short-run pharmaceutical label production. Brand owners in North American and European markets are adopting these systems to meet DSCSA and FMD unit-level traceability mandates without inventorying pre-printed label stocks. This displacement compresses converter working capital requirements while elevating software and data management capabilities above mechanical printing expertise.
EMA's Annex 11 guidelines on computerized systems are mandating electronic record integrity for tamper-evidence verification data across EU pharmaceutical distribution. The regulation requires audit trails linking physical label destruction to digital authentication records, forcing label converters to partner with track-and-trace platform providers. Cold chain biologics shipments from Germany, Ireland, and Belgium face the most stringent documentation requirements.
Direct sourcing from label converters is consolidating procurement authority among top-20 pharmaceutical manufacturers, disintermediating traditional distribution channels. These buyers are establishing approved vendor lists with dedicated capacity allocations and quality agreements spanning multiple production sites. The pattern is most pronounced among Boston-Cambridge biotech clusters and Basel-Novartis supply chain ecosystems.
Destructible Security Labels Market Segmentation
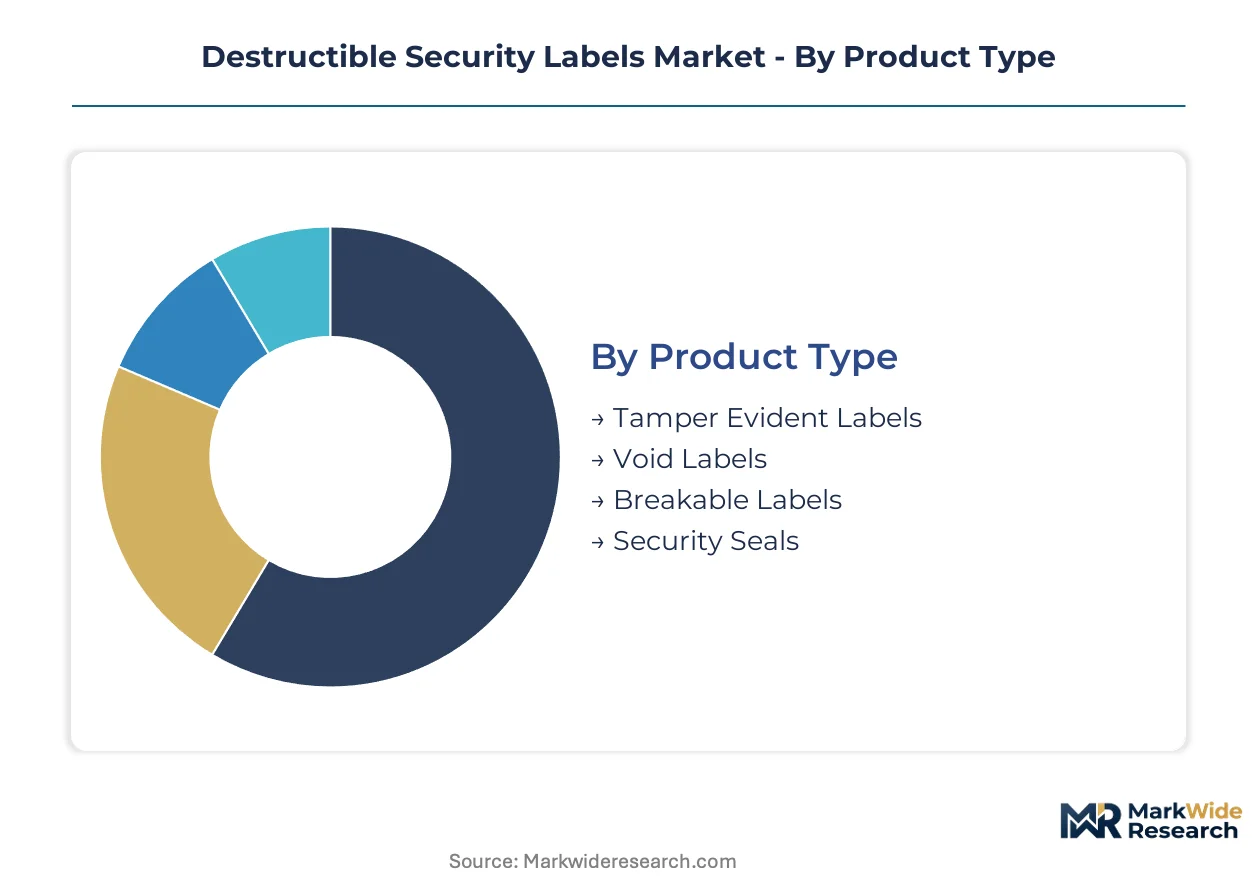
Destructible security labels fragment into distinct specification tiers based on authentication rigor, substrate engineering, and serialization compatibility. Pharmaceutical and defense procurement teams source against divergent compliance frameworks, creating non-interchangeable demand pools that reward specialized converter capabilities.
Product Type:
FDA DSCSA mandates and ISO 17712 defense specifications create divergent performance thresholds across product categories, with pharmaceutical buyers prioritizing void messaging clarity and military logistics requiring mechanical seal integrity.
- Tamper Evident Labels:Pressure-sensitive constructions employing brittle substrates below 50-micron thickness with permanent adhesives exceeding 20 N/25mm peel strength. Pharmaceutical cold chain applications in Germany and Massachusetts concentrate demand as brand owners comply with unit-level serialization mandates.
- Void Labels:Multi-layer laminates engineered to reveal hidden messaging upon delamination attempts, typically using patterned release coatings between facestock and adhesive. Electronics OEMs in South Korea and Taiwan specify these for warranty-void authentication on consumer device enclosures.
- Breakable Labels:Ultra-thin polyester or cellulose acetate constructions that fracture under mechanical stress, suited for high-temperature automotive component tracking in Baden-Württemberg manufacturing clusters.
- Security Seals:Rigid or semi-rigid mechanical closures with integrated destructible elements for container and tote authentication.
Tamper evident labels handle the majority of throughput; void labels are climbing the fastest on share as electronics manufacturers integrate authentication into warranty management systems.
Application:
End-use concentration follows regulatory enforcement intensity, with pharmaceutical serialization deadlines and automotive export verification requirements concentrating procurement authority among specification-grade converters.
- Pharmaceuticals:Unit-level track-and-trace compliance under FDA DSCSA and EU Falsified Medicines Directive mandates serialized tamper verification at the package level. Cold chain biologics shipments from Ireland and Belgium impose the most stringent documentation requirements.
- Electronics:Warranty authentication and anti-counterfeiting for smartphones, laptops, and semiconductor components. Original equipment manufacturers in Shenzhen and Seoul specify destructible labels to secure aftermarket revenue streams.
- Document Security:Passport, certificate, and secure credential protection against forgery and alteration.
- Retail:High-value merchandise protection and return-fraud prevention in luxury goods distribution.
Pharmaceuticals commands premium pricing tiers; electronics is gaining share fastest as Asian manufacturing clusters scale authentication programs.
Material:
Substrate selection trades dimensional stability against cost position, with temperature-extreme logistics environments forcing specification upgrades that compress converter margins on standard-grade contracts.
- Polyester:Biaxially oriented polyethylene terephthalate films engineered for brittleness below 50-micron thickness. Cold chain pharmaceutical applications command premium positioning due to dimensional stability across temperature extremes from -80°C to +150°C.
- Paper:Calendered or cast-coated stocks with destructible fiber structures for document security and low-cost retail applications. Indian pharmaceutical exporters specify paper-based alternatives for domestic distribution where serialization requirements remain less stringent.
- Vinyl:Flexible polyvinyl chloride formulations for conformable surfaces and curved electronics enclosures.
- Polypropylene:Oriented polypropylene films balancing cost and performance for mid-tier pharmaceutical and retail applications.
Polyester dominates revenue concentration; polypropylene is expanding most quickly as Brazilian and Indian generic drug manufacturers seek specification-grade alternatives at lower unit economics.
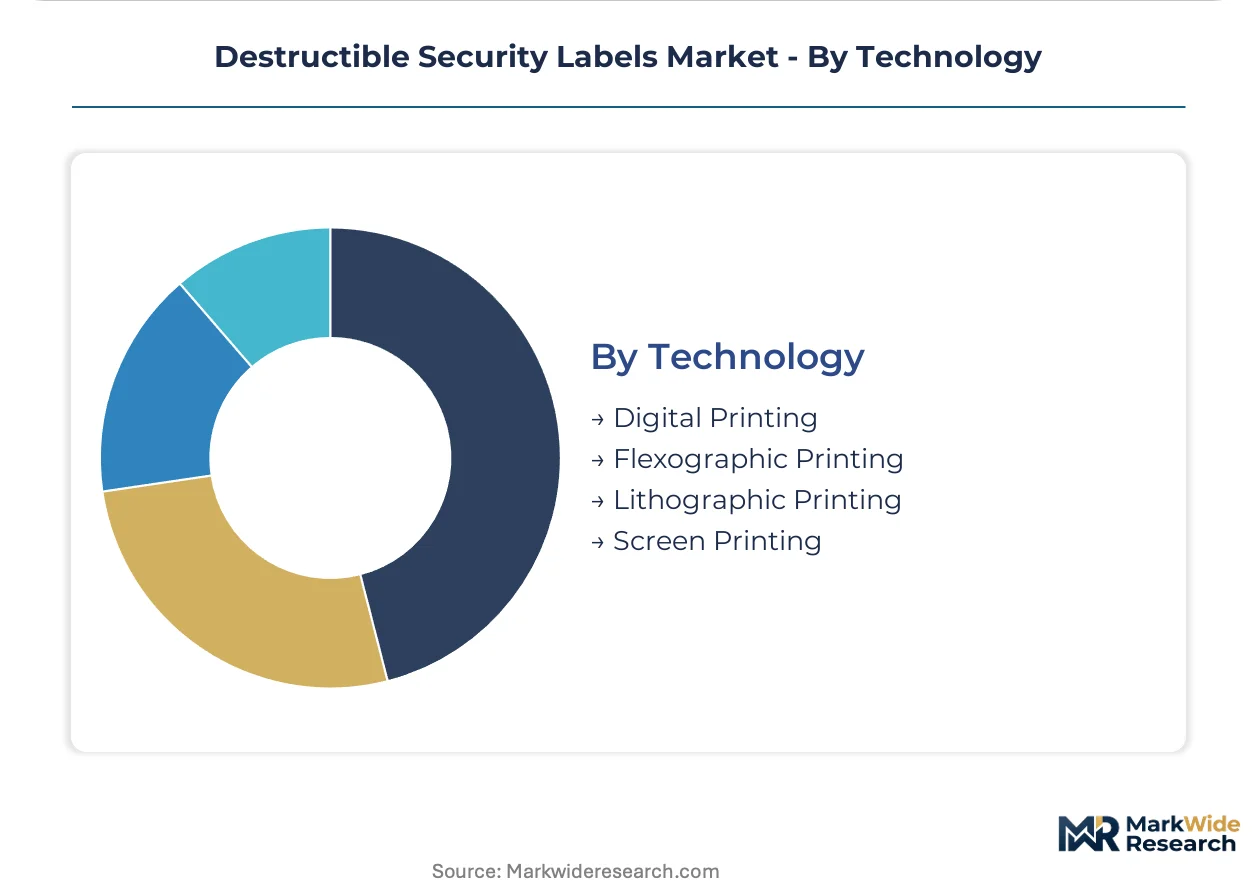
Technology:
Production method selection determines minimum order quantities, serialization capability, and converter capital intensity, with digital adoption redistributing competitive advantage toward software and data management competencies.
- Digital Printing:Inkjet and toner-based systems enabling single-unit serialization with variable-data integration. North American and European brand owners adopt these systems to meet DSCSA and FMD mandates without inventorying pre-printed label stocks.
- Flexographic Printing:Rotary relief printing with photopolymer plates for medium-to-long runs of standardized security designs. German automotive component suppliers rely on flexographic output for cross-border shipment verification labels requiring consistent color matching.
- Lithographic Printing:Offset methods for high-volume document security applications with intricate anti-counterfeiting features.
- Screen Printing:Stencil-based deposition for heavy ink coverage and tactile security elements on durable substrates.
Flexographic printing maintains the largest installed base; digital printing is the fastest mover on share as pharmaceutical contract packagers retrofit legacy lines for serialized application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA mandates under the Drug Supply Chain Security Act and parallel EU serialization requirements are redrawing procurement geography across destructible security labels. Pharmaceutical exporters in Germany, the United States, India, China, and Brazil face the most stringent compliance deadlines, concentrating specification-grade demand among converters with multi-jurisdictional certification capabilities.
United States
Pharmaceutical cold chain expansion and biologics distribution from Massachusetts and California drive specification-grade demand. FDA DSCSA enforcement mandates serialized tamper verification at the package level by November 2024. Boston-Cambridge biotech clusters are consolidating procurement authority through approved vendor lists with dedicated capacity allocations.
Germany
Automotive component exports and pharmaceutical cold chain shipments generate dual demand streams for EU-compliant security labeling. EMA Annex 11 guidelines mandate electronic record integrity for tamper-evidence verification data across pharmaceutical distribution. Baden-Württemberg manufacturing clusters specify destructible labels for cross-border shipment verification of precision components.
India
Export-oriented pharmaceutical formulation units seek specification-grade production as CDSCO serialization mandates phase in for international shipments. The country's national pharmaceutical regulator is aligning track-and-trace requirements with WHO prequalification standards. Gujarat and Maharashtra manufacturing corridors are retrofitting packaging lines for unit-level label application.
China
Electronics OEM authentication programs and domestic pharmaceutical serialization create bifurcated demand. NMPA implementation of drug traceability codes expands specification requirements for converters serving both local and export markets. Shenzhen and Shanghai manufacturing clusters specify void labels for warranty authentication on consumer devices.
Brazil
Generic drug distribution and agricultural chemical tracking open white space ahead of full ANVISA serialization enforcement. The national health surveillance agency's implementation timelines create first-mover opportunities for tamper-evident label converters. São Paulo pharmaceutical manufacturing zones are piloting serialized destructible label application at commercial speeds.
Destructible Security Labels Market Vendor Landscape
Player mix skews toward diversified materials science conglomerates with captive adhesive and substrate capabilities. The vendor base concentrates among three tiers: premium specification-grade specialists with ISO 17712 certification, mid-scale regional converters serving pharmaceutical contract packagers, and commodity-grade suppliers competing on minimum order quantity compression. Strategic differentiation centers on backward integration into specialty film extrusion and variable-data software licensing partnerships.
Among diversified materials conglomerates, 3M, Avery Dennison, and Brady Corporation exemplify the premium-tier archetype through in-house production of proprietary destructible facestocks. These entities occupy positions that reward specification-grade certification and multi-jurisdictional regulatory compliance. Mid-scale specialists including tesa SE and CCL Industries represent regional fabrication capabilities with focused adhesive formulation expertise. The competitive dynamic favors converters that bridge mechanical label production with digital serialization infrastructure.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| Brady Corporation |
| Shosky Security |
| CCL Industries |
| UPM Raflatac |
| tesa SE |
| SECURITAG |
| B-Sealed |
| Others |
Supply Flow & Price Mechanics
ISO 17712 certification for high-security seals gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where defense-grade converters command substantial premiums over commodity suppliers lacking mechanical seal testing capabilities.
Pricing Analysis
Certification level creates the primary spread between ISO 17712-qualified defense suppliers and standard pharmaceutical converters. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance rigor, with FDA DSCSA-grade serialization commanding mid-tier positioning and commodity void labels for retail applications anchoring the low end. Cost compression in the standard tier is intensifying because digital printing technology lowers converter capital barriers. Contract packagers serving generic drug manufacturers exhibit highest price sensitivity, while defense logistics procurement teams prioritize mechanical integrity over unit cost.
Supply Chain Analysis
Inventory lead times for brittleness-engineered polyester films below 50-micron thickness extend production cycles as specialty extrusion capacity concentrates in Japan and South Korea. Raw material sourcing draws from biaxially oriented polyethylene terephthalate resin suppliers, proprietary adhesive formulation houses, and precision release coating specialists. Single-source vulnerability pervades the substrate tier where two Asian producers control specification-grade film supply. Distribution runs through approved vendor lists maintained by top-20 pharmaceutical manufacturers, disintermediating traditional label distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Destructible security labels represent a high-growth disruption as FDA DSCSA enforcement deadlines force pharmaceutical contract packagers to retrofit legacy lines for serialized application at commercial speeds.
For Market Incumbents: Consolidate specification-grade certification portfolios to defend against mid-scale regional converters encroaching on pharmaceutical serialization contracts. Brady Corporation's backward integration into materials science exemplifies the capability moat required to sustain premium positioning. Prioritize capacity allocation agreements with Boston-Cambridge biotech clusters where procurement authority concentrates.
For New Entrants and Emerging Players: Variable-data workflow integration services present an under-served layer where incumbent converters lack software competencies. Brazilian generic drug distribution offers the most penetrable geography ahead of full ANVISA serialization enforcement. Partner with track-and-trace platform providers to bypass mechanical printing expertise requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital printing-enabled converter operations as inkjet serialization displaces flexographic plate investment. Five-to-ten year viability favors mid-scale specialists with adhesive formulation depth over commodity-grade competitors. Monitor CDSCO implementation timelines in India as the signal for emerging market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17712 Certification Investment | Defense logistics qualification extends product cycles but locks in multi-year supply agreements. |
| Digital Printing Infrastructure Deployment | Variable-data serialization capability opens pharmaceutical contract packaging opportunities. |
| Backward Integration into Specialty Films | Captive substrate supply insulates against Japanese and Korean extrusion concentration. |
| Track-and-Trace Platform Partnership | EMA Annex 11 compliance requires audit trail integration for EU pharmaceutical distribution. |
| Regional Capacity Expansion in India | CDSCO serialization mandates for export units create first-mover positioning. |
Methodological Framework
The analysis maps tamper-evident labels, void labels, breakable labels, and security seals, each validated through converter operations managers, pharmaceutical packaging engineers, defense procurement officers, and adhesive formulation chemists. Primary fieldwork combined with secondary validation against FDA DSCSA guidance documents, EMA Annex 11 guidelines, ISO 17712 testing protocols, and REACH chemical restriction lists. Bottom-up demand modeling across end-use applications triangulates with top-down market sizing from trade flow analysis.
Consistency checks validated volume and value outputs against customs data for security label imports, pharmaceutical packaging equipment installation records, and defense logistics spending disclosures. Segmentation dimensions modeled include product type, application, material grade, printing technology, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating serialization mandate phase-in schedules. Industry-specific forecast inputs encompass cold chain pharmaceutical shipment growth and electronics OEM warranty authentication program expansion.
Underlying assumptions cover regulatory enforcement timelines, substrate supply stability, and digital printing adoption curves, with deviation risk concentrated in REACH chemical restriction expansion and emerging market serialization delay. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Private Security Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Integrated Security Solutions Market