
 Speed Limit Radar Signs Market | 2026-2036
Speed Limit Radar Signs Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Limit Radar Signs Market Insights
The gap between premium solar-powered radar signs and commodity AC-powered units is expanding as battery efficiency and photovoltaic costs diverge. Carmanah Technologies leverages integrated solar design to anchor its position in off-grid municipal deployments. Traffic Logix competes through modular hardware platforms that accommodate retrofitted Doppler or microwave sensors. RadarSign differentiates via cloud-connected feedback systems that sustain recurring service revenue from transportation agencies.
Speed limit radar signs are roadside display devices that use Doppler or microwave radar to detect approaching vehicle velocity and flash the measured speed alongside a posted limit, typically operating within detection ranges of 300 to 1,500 feet depending on sensor class. Solar-powered radar signs now command the fastest-growing product tier as lithium-ion storage chemistry and high-efficiency photovoltaic panels eliminate trenching costs for remote installations. LED radar signs retain structural dominance in urban street and highway applications where grid reliability supports continuous operation and brightness requirements exceed passive display capability. Doppler radar technology occupies the mature core of the sensor stack, while microwave radar variants are gaining share in construction site and industrial park settings where multi-lane coverage and interference rejection matter.
The Federal Highway Administration's MUTCD guidelines shape product certification requirements for U.S. deployments, while the EU Green Deal and national building codes in Germany and France accelerate solar-powered procurement through embedded carbon accounting. ISO 9001 quality management and IEC 62262 impact protection standards govern manufacturing consistency and enclosure durability for outdoor electronics. Stakeholders must monitor evolving state procurement rules around domestic content thresholds and cybersecurity mandates for connected traffic infrastructure.
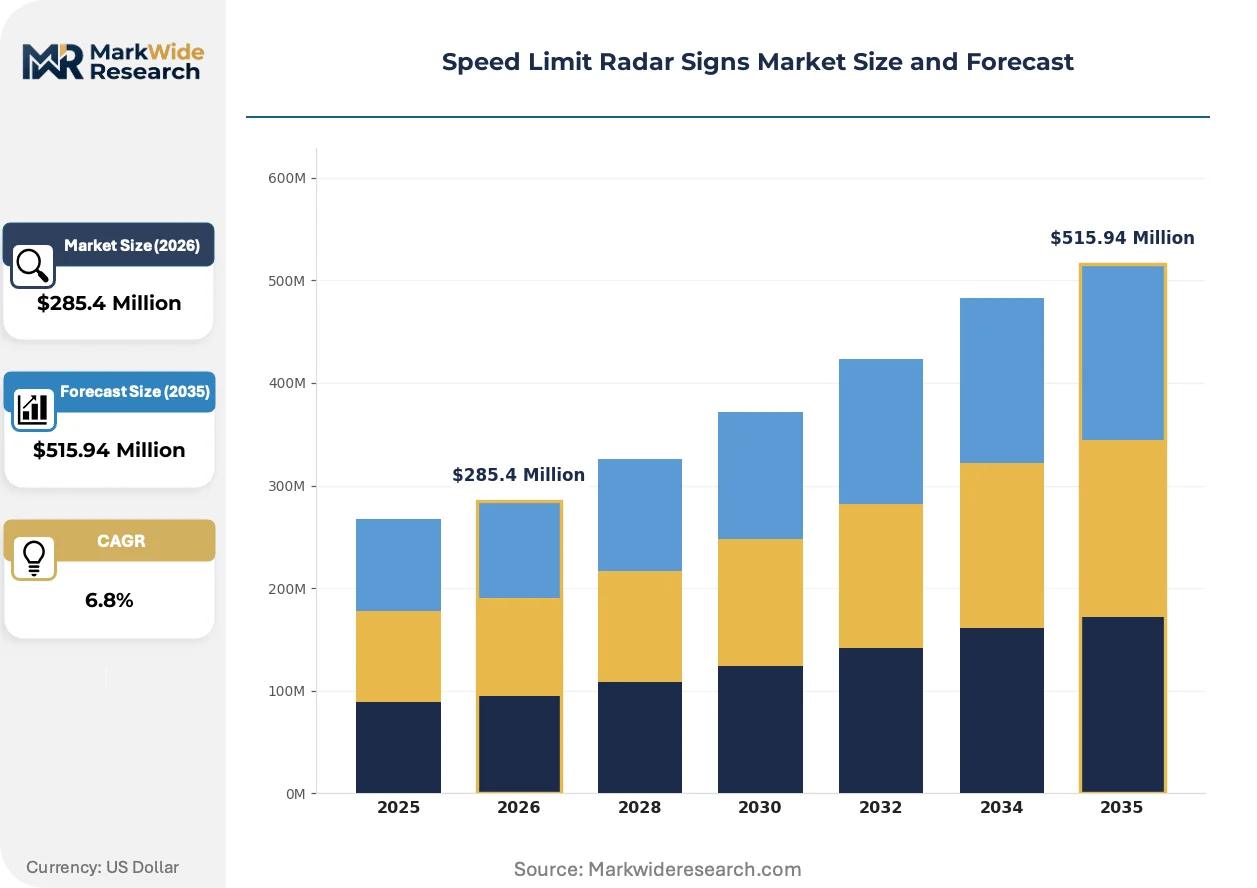
Market Dynamics
Federal highway safety grants and state-level automated enforcement laws are compressing procurement cycles for digital radar sign installations across municipal transportation departments.
Growth Catalysts
- Vision Zero mandates:North American cities deploy solar-powered units in school zones to eliminate traffic fatalities. Municipal budgets now prioritize pedestrian safety infrastructure.
- FHWA MUTCD guidelines:Certification requirements standardize product specifications for U.S. deployments. Transportation agencies accelerate replacement of legacy static signage.
- Lithium-ion storage chemistry:Battery efficiency gains eliminate trenching costs for remote installations. Rural counties adopt off-grid radar signs where grid extension proves uneconomical.
Market Restraints
- Photovoltaic cost volatility:Solar panel input prices fluctuate with polysilicon supply from concentrated Asian manufacturing bases. Municipal procurement officers face budget uncertainty.
- AC grid dependency:Urban highway applications require continuous grid power for brightness specifications. Solar variants cannot meet luminosity thresholds in high-traffic corridors.
- Domestic content thresholds:Evolving state procurement rules restrict foreign-manufactured components. Supply chains require reconfiguration to qualify for federal grant funding.
Strategic Opportunities
- EU Green Deal carbon accounting:German and French national building codes accelerate solar-powered procurement through embedded emissions scoring. European municipal tenders favor low-carbon infrastructure.
- Cloud-connected feedback systems:Transportation agencies seek recurring service revenue from speed data analytics. Software subscriptions supplement hardware margins.
- Construction site multi-lane coverage:Microwave radar variants address industrial park and temporary work zone applications. Interference rejection capabilities open non-municipal demand verticals.
Industry Challenges
- Cybersecurity mandates for connected infrastructure:Transportation agencies require hardened communication protocols for cloud-enabled signs. Vendors must certify data encryption standards.
- ISO 9001 and IEC 62262 compliance timelines:Quality management and impact protection certifications delay product launches. Testing cycles extend six to twelve months for enclosure durability validation.
- Legacy Doppler sensor integration:Retrofitting existing installations with microwave variants requires hardware platform compatibility. Modular design expertise separates competitive tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Limit Radar Signs Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Radar Signs, LED Radar Signs, Solar-Powered Radar Signs, Variable Speed Radar Signs, Fixed Speed Radar Signs Technology: Doppler Radar, Microwave Radar, Ultrasonic Radar, Infrared Radar, Laser Radar Application: School Zones, Construction Sites, Urban Streets, Highways, Industrial Parks End User: Municipal Authorities, Transportation Agencies, Private Property Managers, Road Safety Contractors |
| Companies Covered | Carmanah Technologies, Traffic Logix, RadarSign, Trafficalm, A&A Safety, Traffic Safety Corporation, Wanco Inc., Jinke Traffic Signal, Elan City, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Limit Radar Signs Market Trends and Innovations
Speed limit radar signs are converging around three vectors: photovoltaic-battery integration compressing installation economics, regulatory carbon accounting reshaping procurement scoring, and service-based revenue models displacing pure hardware transactions.
Edge computing architectures are unifying sensor processing with local data storage in next-generation radar signs. State transportation departments in California and Texas pilot units that aggregate speed patterns without continuous cellular uplink. This unifying architecture reduces recurring connectivity costs while preserving enforcement-grade data integrity for traffic engineering analysis.
EU Green Deal embedded carbon accounting is restructuring municipal tender evaluation criteria across France, Germany, and the Netherlands. Transportation procurement officers now weight lifecycle emissions alongside upfront capital expenditure. Solar-powered radar signs with documented supply chain carbon footprints capture preference in European competitive bidding.
Outcome-based speed reduction contracts are displacing traditional equipment purchase models in North American school districts. Vendors guarantee percentage reductions in posted-limit violations rather than selling hardware units. Texas and Florida counties lead this behavioral contracting approach, paying for documented safety outcomes rather than installed asset counts.
Speed Limit Radar Signs Market Segmentation
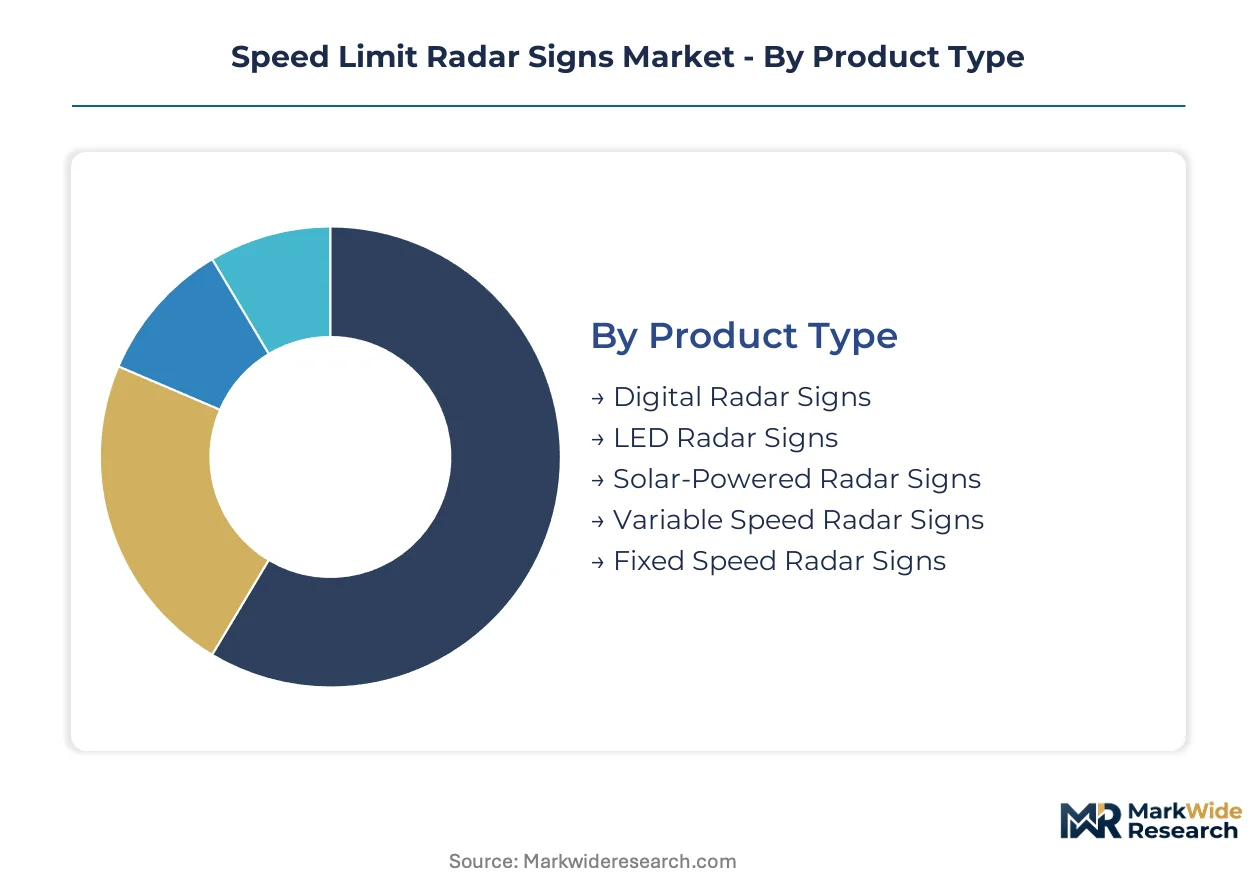
Speed limit radar signs fragment across four intersecting dimensions that determine procurement specifications, installation economics, and operational lifecycle. Product type and technology choices dictate power infrastructure requirements, while application context and end-user governance structures shape purchasing authority and compliance obligations.
Product Type:
Customization intensity spans fixed mechanical displays at the standardized end to cloud-connected variable systems requiring site-specific programming.
- Solar-Powered Radar Signs:Integrated photovoltaic panels and lithium-ion battery arrays eliminate trenching requirements for off-grid installations. Municipal authorities in rural U.S. counties prioritize these units where grid extension costs exceed hardware premiums, driven by FHWA highway safety grant eligibility for standalone safety infrastructure.
- LED Radar Signs:High-luminance diode arrays deliver visibility thresholds exceeding passive display capability for urban highway corridors. Transportation agencies specify these where continuous grid power supports brightness requirements that solar variants cannot sustain through diurnal cycles.
- Digital Radar Signs:Full-matrix LED displays enable programmable messaging beyond speed feedback.
- Variable Speed Radar Signs:Dynamic limit adjustment responds to real-time traffic conditions or weather events.
- Fixed Speed Radar Signs:Static posted limits with embedded detection sensors serve permanent installations.
Leading the category by volume: LED Radar Signs. Growing fastest: Solar-Powered Radar Signs.
Technology:
Sensor sophistication correlates with unit cost and interference rejection capability across deployment environments.
- Doppler Radar:Mature frequency-shift detection occupies the cost-optimized core of municipal procurement. School zone installations across Texas and Florida standardize on this technology for proven velocity accuracy within 300-to-1,500-foot ranges.
- Microwave Radar:Multi-lane coverage and superior interference rejection command premium positioning in construction site and industrial park applications. Road safety contractors specify these variants where overlapping detection zones and metallic clutter challenge simpler sensors.
- Ultrasonic Radar:Short-range proximity detection serves low-speed residential applications.
- Infrared Radar:Thermal signature detection complements visible-light systems in adverse weather.
- Laser Radar:LIDAR-based velocity measurement targets precision enforcement applications.
Category leadership by installed base: Doppler Radar. Steepest expansion trajectory: Microwave Radar.
Application:
Regulatory enforcement intensity varies from voluntary compliance zones to statutory speed limit jurisdictions.
- School Zones:Vision Zero mandates and pedestrian fatality reduction targets concentrate procurement volume here. Municipal authorities deploy solar-powered units with guaranteed outcome contracts replacing traditional equipment purchases.
- Construction Sites:Temporary work zone regulations mandate active speed feedback for worker protection. Road safety contractors lease microwave-equipped trailers under short-term rental models rather than capital acquisition.
- Urban Streets:Grid-connected LED installations dominate downtown corridors with continuous power availability.
- Highways:High-luminance requirements and vandalism resistance specifications favor hardened enclosures.
- Industrial Parks:Private roadway governance allows flexible procurement outside municipal bidding rules.
Dominant volume segment: School Zones. Fastest policy-driven expansion: Construction Sites.
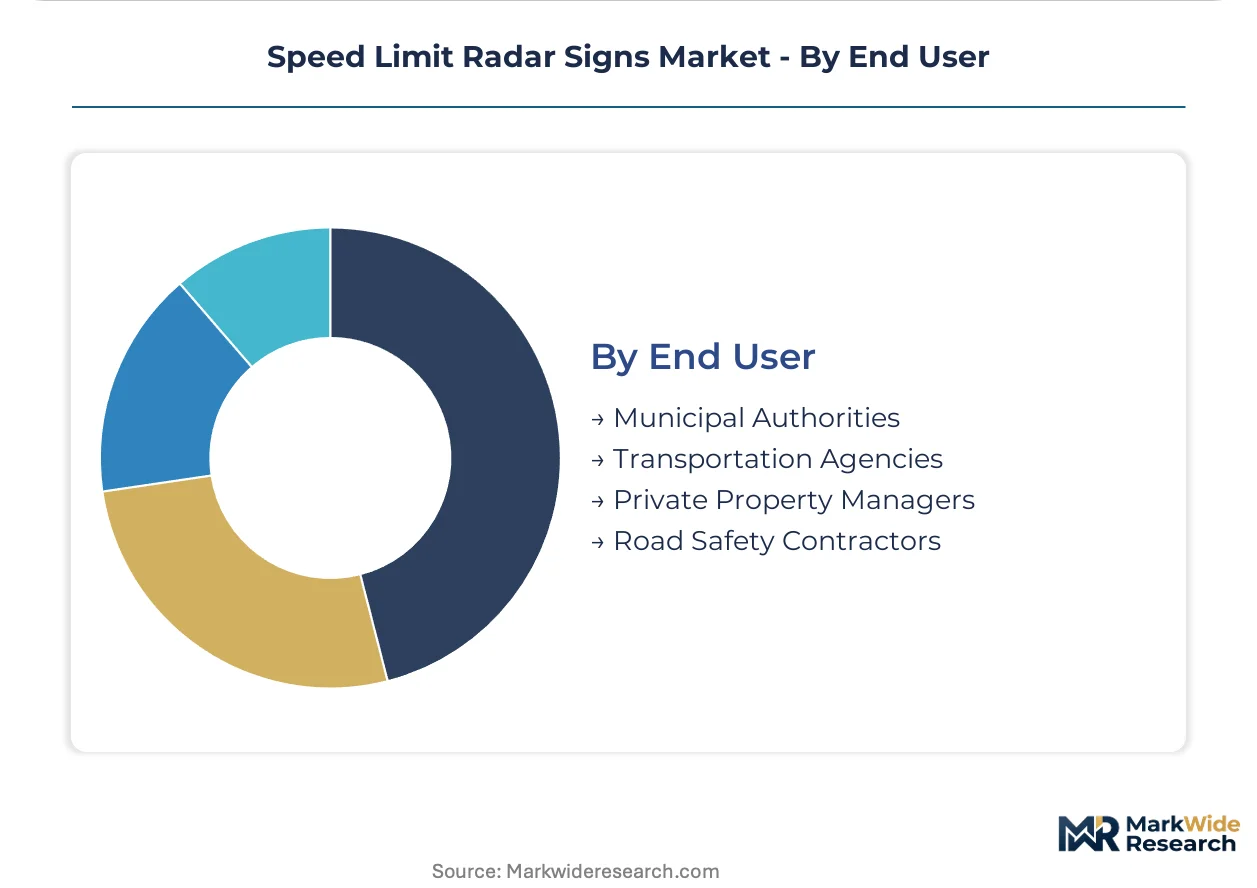
End User:
Purchasing authority fragmentation separates tax-funded public procurement from private capital deployment.
- Municipal Authorities:City and county transportation departments operate under FHWA MUTCD certification requirements and federal grant compliance. Budget cycles align with fiscal year appropriations and Vision Zero safety mandate deadlines.
- Transportation Agencies:State DOTs manage highway corridor installations with standardized specifications across multiple jurisdictions. California and Texas DOTs pilot edge-computing architectures for aggregated speed pattern analysis.
- Private Property Managers:Corporate campus and retail parking governance operates outside public procurement rules.
- Road Safety Contractors:Rental and service-based revenue models displace hardware ownership in temporary applications.
Largest procurement volume: Municipal Authorities. Fastest contract model innovation: Transportation Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American procurement velocity as Texas counties pilot edge-computing radar sign architectures. Federal highway safety grants and state automated enforcement statutes compress municipal purchasing cycles across four priority markets.
United States
FHWA MUTCD certification requirements and Vision Zero pedestrian safety mandates drive municipal procurement. California DOT and Texas DOT deploy solar-powered units with guaranteed outcome contracts replacing traditional equipment purchases. Dallas-Fort Worth metroplex leads school zone deployment volume.
Canada
Transport Canada collision reduction targets and provincial highway safety programs accelerate digital signage replacement. Ontario and British Columbia transportation ministries prioritize off-grid installations in remote corridor segments. Greater Toronto Area concentrates manufacturing integration for North American supply chains.
Germany
EU Green Deal embedded carbon accounting reshapes municipal tender evaluation through lifecycle emissions scoring. KBA technical standards and federal building codes favor photovoltaic-battery systems in competitive bidding. Bavaria and Baden-Württemberg industrial clusters supply enclosure and sensor components.
France
National building code carbon thresholds and ANSM infrastructure safety protocols accelerate solar-powered procurement. French municipal authorities weight documented supply chain footprints alongside capital expenditure. Île-de-France region dominates transportation agency pilot programs for cloud-connected feedback systems.
United Kingdom
Department for Transport active travel mandates and local authority road safety budgets concentrate procurement in school zone applications. England's combined authorities deploy outcome-based speed reduction contracts with vendor performance guarantees. Greater Manchester leads behavioral contracting adoption among metropolitan regions.
Speed Limit Radar Signs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across power infrastructure and connectivity dimensions. The vendor base stratifies between integrated solar designers, modular hardware platforms, and cloud-connected service providers. Three archetypes dominate: off-grid specialists optimizing photovoltaic-battery economics, modular fabricators accommodating sensor retrofits, and software-anchored vendors capturing recurring data analytics revenue. Geographic expansion and technology licensing represent the dominant competitive vectors as procurement rules harden around domestic content and cybersecurity compliance.
Within the integrated solar tier, Carmanah Technologies occupies a position exemplifying off-grid municipal deployment specialization. Traffic Logix and RadarSign sit within the North American vendor cluster, with the former representing modular hardware platform approaches and the latter anchoring cloud-connected recurring revenue models. These three companies collectively illustrate the strategic divergence between hardware-centric and service-based market positioning.
| Leading Market Players |
|---|
| Carmanah Technologies |
| Traffic Logix |
| RadarSign |
| Trafficalm |
| A&A Safety |
| Traffic Safety Corporation |
| Wanco Inc. |
| Jinke Traffic Signal |
| Elan City |
| Others |
Pricing and Supply Chain Analysis
Captive solar-battery integration anchors supply positioning for premium-tier vendors while compressing procurement economics for municipal buyers. This vertical control over photovoltaic and lithium-ion inputs simultaneously insulates margin structures from polysilicon volatility and enables outcome-based pricing models that tie vendor compensation to documented speed reduction metrics.
Pricing Analysis
Outcome-based speed reduction contracts anchor municipal procurement evaluation, displacing transactional hardware purchases with performance-guaranteed engagements. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected service bundles from modular hardware platforms and fixed-mechanical commodity units. Price differentiation hinges on FHWA MUTCD certification tier and after-sales analytics subscription depth. Cost compression in the solar-powered tier is intensifying because polysilicon input volatility forces vendors to absorb margin risk or pass through to grant-dependent municipal budgets. Rural county transportation departments exhibit highest price sensitivity due to constrained fiscal capacity, while state DOTs with federal highway safety grant access demonstrate lowest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Polysilicon supply rests on concentrated Asian manufacturing bases, with photovoltaic panel production clustering in China, Vietnam, and Malaysia. Lithium-ion battery cells draw from South Korean and Japanese specialty chemical producers, while LED diode arrays source from Taiwanese semiconductor foundries. Single-source vulnerability in photovoltaic wafer supply creates exposure to trade policy shifts and logistics chokepoints at major port complexes. Distribution runs through municipal procurement officers operating under federal grant compliance timelines, with road safety contractors accessing hardware via rental-service intermediaries for temporary construction site deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with integrated solar design capabilities and certified cloud infrastructure, as cybersecurity mandates and domestic content thresholds force weaker assemblers without captive supply or software competence toward exit.
For Market Incumbents: Anchor defensive positioning through backward integration into lithium-ion battery pack assembly and photovoltaic enclosure manufacturing, eliminating exposure to polysilicon price volatility that threatens margin stability in the solar-powered product tier. Deepen vertical control over edge-computing firmware development to satisfy FHWA cybersecurity mandates for connected infrastructure before certification deadlines compress competitive windows. For New Entrants and Emerging Players: Private property managers at corporate campuses and industrial parks represent an underserved buyer archetype operating outside municipal bidding rules and federal grant compliance complexity. Target construction site temporary work zone applications with microwave radar trailer leasing models, where rental-service revenue displaces capital acquisition and incumbent hardware vendors lack service infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial automation conglomerates seeking traffic infrastructure software capabilities and recurring service revenue streams. Long-term viability favors vendors with demonstrated FHWA MUTCD certification, captive solar-battery integration, and transportation agency outcome-contract track records. The signal to watch is state-level domestic content threshold legislation that disqualifies foreign-component-dependent assemblers from federal grant eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | RadarSign and Traffic Logix compete via software subscription revenue that supplements hardware margins. |
| Solar-Battery Backward Integration | Carmanah Technologies anchors off-grid positioning through captive photovoltaic and lithium-ion supply control. |
| Cybersecurity Certification Investment | Transportation agencies require hardened communication protocols that delay product launches for non-compliant vendors. |
| Outcome-Based Contracting | Texas and Florida counties pay for documented speed reduction percentages rather than installed asset counts. |
| Geographic Expansion to EU Green Deal Markets | German and French municipal tenders weight lifecycle emissions scoring that favors solar-powered procurement. |
Research Methodology
Multi-period observation of FHWA grant disbursement patterns, state automated enforcement statute adoption timelines, and municipal procurement cycle compression anchored the trend analysis, supplemented by interviews with transportation agency planning officers, municipal public works directors, road safety contractor operations managers, and radar sign vendor sales executives. Secondary validation drew from Federal Highway Administration MUTCD documentation, state DOT capital improvement program filings, EU Green Deal procurement guideline releases, and customs trade data on photovoltaic panel imports. Bottom-up unit deployment estimates triangulated against top-down addressable market sizing across school zone, construction site, and highway corridor applications.
Input-output matrices modeled unit shipments and average selling prices across product type, sensor technology, application context, and end-user governance structure dimensions throughout the forecast period. CAGRs were derived from segment-specific growth trajectory analysis incorporating lithium-ion battery cost decline curves, solar panel efficiency improvement rates, and regulatory mandate adoption schedules. Industry-specific forecast inputs included Vision Zero policy implementation timelines and federal highway safety grant appropriation trajectories.
Revisions become necessary when photovoltaic input price volatility exceeds modeled ranges, domestic content threshold legislation accelerates beyond baseline assumptions, or cybersecurity mandate enforcement timelines compress vendor certification windows. A small set of named triggers—polysilicon supply disruption, state procurement rule changes, and FHWA connected infrastructure protocol updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Private Security Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Air Cargo Security and Screening Systems Market