
 Port Security Systems Market | 2026-2036
Port Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Port Security Systems Market Analytics
The capability gap between integrated platform providers and point-solution vendors is reorganizing competitive dynamics across port security procurement. Saab AB leverages its naval defense heritage to anchor long-cycle government contracts for vessel protection systems. Siemens AG competes through its building-technology division, extending industrial automation expertise into facility safety and access control networks for European harbor authorities.
Port security systems encompass integrated hardware-software architectures designed to detect, deter, and respond to threats across maritime infrastructure, typically incorporating radar sweep rates of 30-60 RPM, thermal imaging resolutions of 640x512 pixels, and AI-enabled video analytics for automated anomaly detection in high-throughput cargo environments. Surveillance cameras and perimeter security solutions dominate current procurement budgets, while intrusion detection systems represent the fastest-expanding technology segment as ports retrofit legacy fences with fiber-optic and ground-sensor arrays. Container security applications command the deepest margin pools due to customs-integration requirements and insurance-premium linkages, whereas remote monitoring deployments are gaining traction among logistics providers seeking to centralize oversight across dispersed terminal networks.
The International Maritime Organization's ISPS Code, the U.S. Coast Guard's Maritime Transportation Security Act regulations, and the EU's Critical Entities Resilience Directive collectively mandate layered security architectures, forcing terminal operators to upgrade from single-point solutions to integrated command-and-control platforms. Port authorities in the United States, the Netherlands, and Singapore face overlapping compliance deadlines that compress procurement cycles and favor vendors with certified end-to-end portfolios. Stakeholders must weigh the trade-off between proprietary system lock-in and interoperability standards as port operators consolidate vendor relationships over multi-year modernization programs.
Market Dynamics
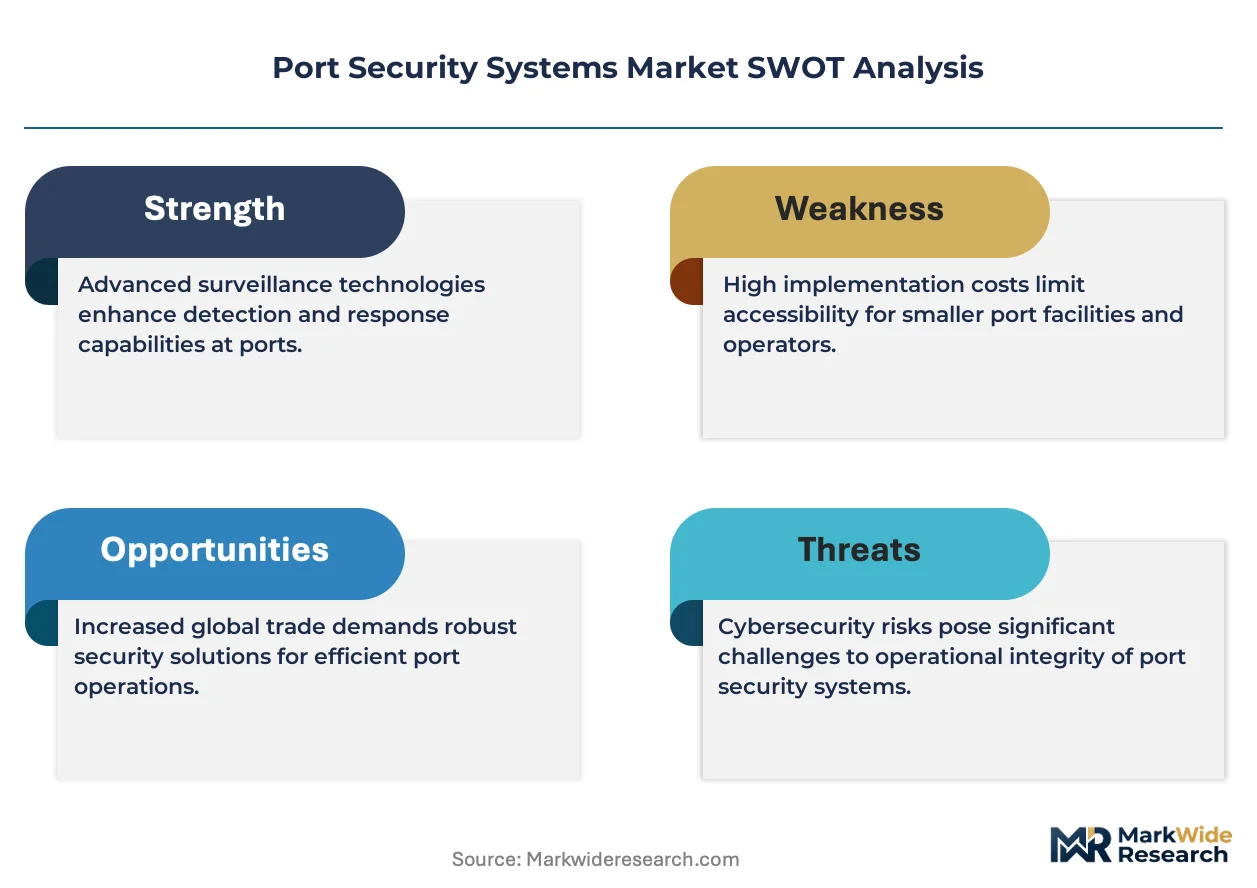
The ISPS Code's layered-security mandate is compressing procurement cycles as terminal operators abandon single-point solutions for integrated command platforms. Compliance deadlines in the United States, the Netherlands, and Singapore are forcing simultaneous infrastructure overhauls across major transshipment hubs.
Growth Catalysts
- Container security mandates:Customs-integration requirements and insurance-premium linkages in Singapore and Rotterdam are deepening margin pools for integrated system providers.
- Fiber-optic perimeter retrofitting:Ports across the United States are replacing legacy fences with ground-sensor arrays, accelerating intrusion detection system deployments.
- EU Critical Entities Resilience Directive:Terminal operators in European harbor authorities must upgrade facility safety and access control networks by overlapping compliance deadlines.
Market Restraints
- Proprietary system lock-in:Vendor consolidation over multi-year modernization programs creates switching friction and interoperability barriers for port authorities.
- High-resolution thermal imaging costs:640x512 pixel sensor arrays and AI-enabled video analytics require substantial capital allocation from logistics providers.
- Certified portfolio scarcity:Few vendors possess end-to-end certified portfolios spanning radar sweep systems, thermal imaging, and automated anomaly detection.
Strategic Opportunities
- Dispersed terminal centralization:Remote monitoring deployments allow logistics providers to consolidate oversight across fragmented networks in the United States.
- AI-radar convergence:Machine learning integration with 30-60 RPM radar systems enables predictive threat assessment in high-throughput cargo environments.
- Netherlands harbor automation:Siemens AG's building-technology division extension creates template for industrial automation expertise transfer into maritime facility safety.
Industry Challenges
- Multi-vendor integration complexity:Terminal operators struggle to unify point-solution legacy infrastructure with new integrated command-and-control platforms.
- Maritime-cybersecurity skill scarcity:Shortage of technicians proficient in both naval defense heritage systems and modern AI analytics compresses deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Security Systems Market |
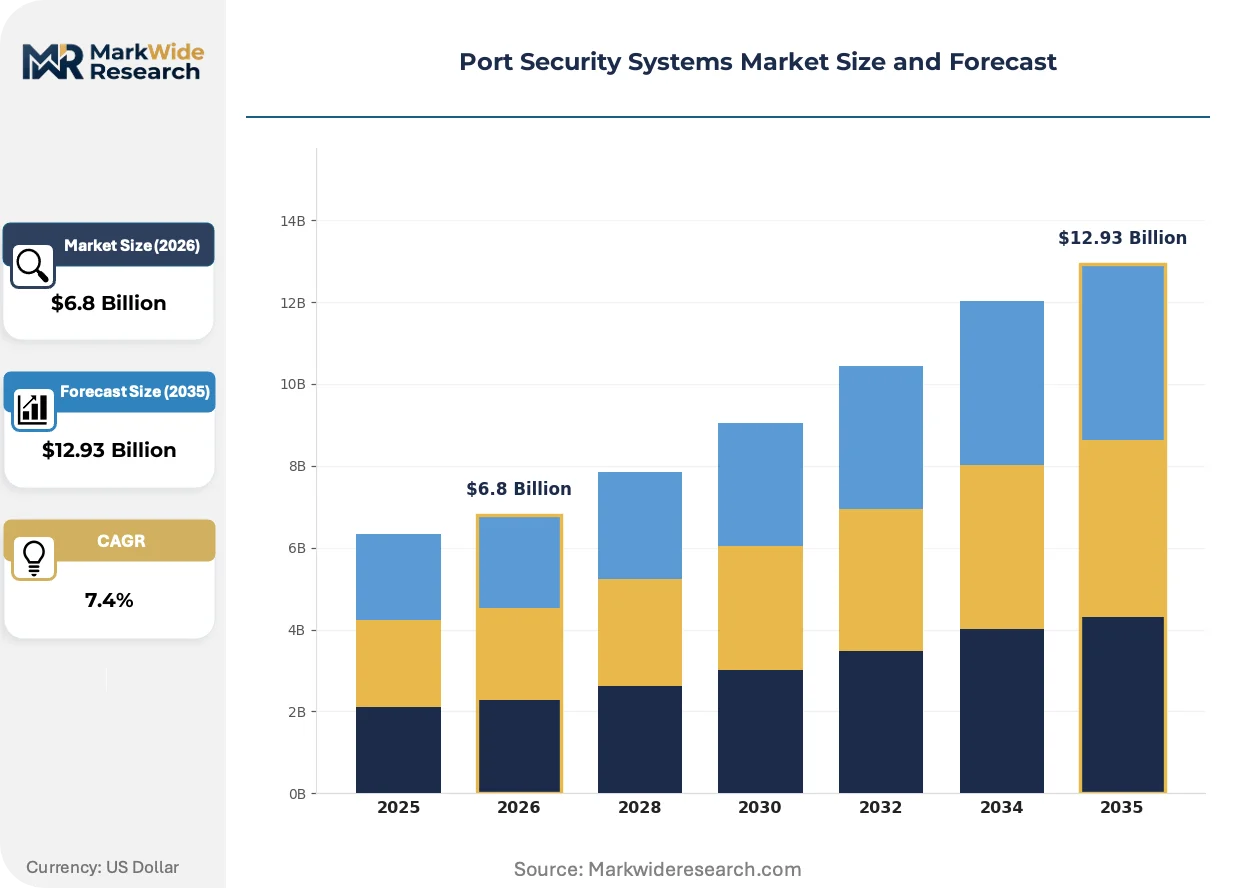
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Access Control, Surveillance Cameras, Intrusion Detection, Perimeter Security Application: Container Security, Cargo Monitoring, Vessel Protection, Facility Safety Deployment: On-premises, Cloud-based, Hybrid, Remote Monitoring End User: Ports and Harbors, Logistics Providers, Government Agencies, Shipping Companies |
| Companies Covered | Saab AB, Siemens AG, RTX Corporation, THALES, Leidos Inc, Honeywell International Inc, BAE Systems plc, Johnson Controls, Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Security Systems Market Evolving Landscape
Hardware-software convergence is collapsing traditional procurement categories as integrated platforms subsume discrete point solutions. Vendors now compete on system-architecture coherence rather than individual component performance.
AI-enabled video analytics is decomposing the boundary between surveillance and response systems. Terminal operators in Rotterdam and the Port of Los Angeles are deploying these platforms for automated anomaly detection in container yards. The technology is decomposing legacy silos between perimeter detection and centralized command centers, forcing vendors to restructure service offerings around unified data architectures.
The EU's Critical Entities Resilience Directive mandates layered security architectures with explicit interoperability standards. Terminal operators must demonstrate cross-system communication capabilities to receive operating certifications. European harbor authorities are responding by consolidating vendor relationships around providers with certified end-to-end portfolios rather than assembling multi-vendor stacks.
Service unbundling is fragmenting traditional procurement as logistics providers separate hardware acquisition from analytics subscriptions. Remote monitoring specialists are capturing recurring revenue streams previously held by integrated platform vendors. This pattern concentrates in Singapore and the Netherlands where dispersed terminal networks favor centralized oversight models over on-site security staffing.
Port Security Systems Market Segmentation
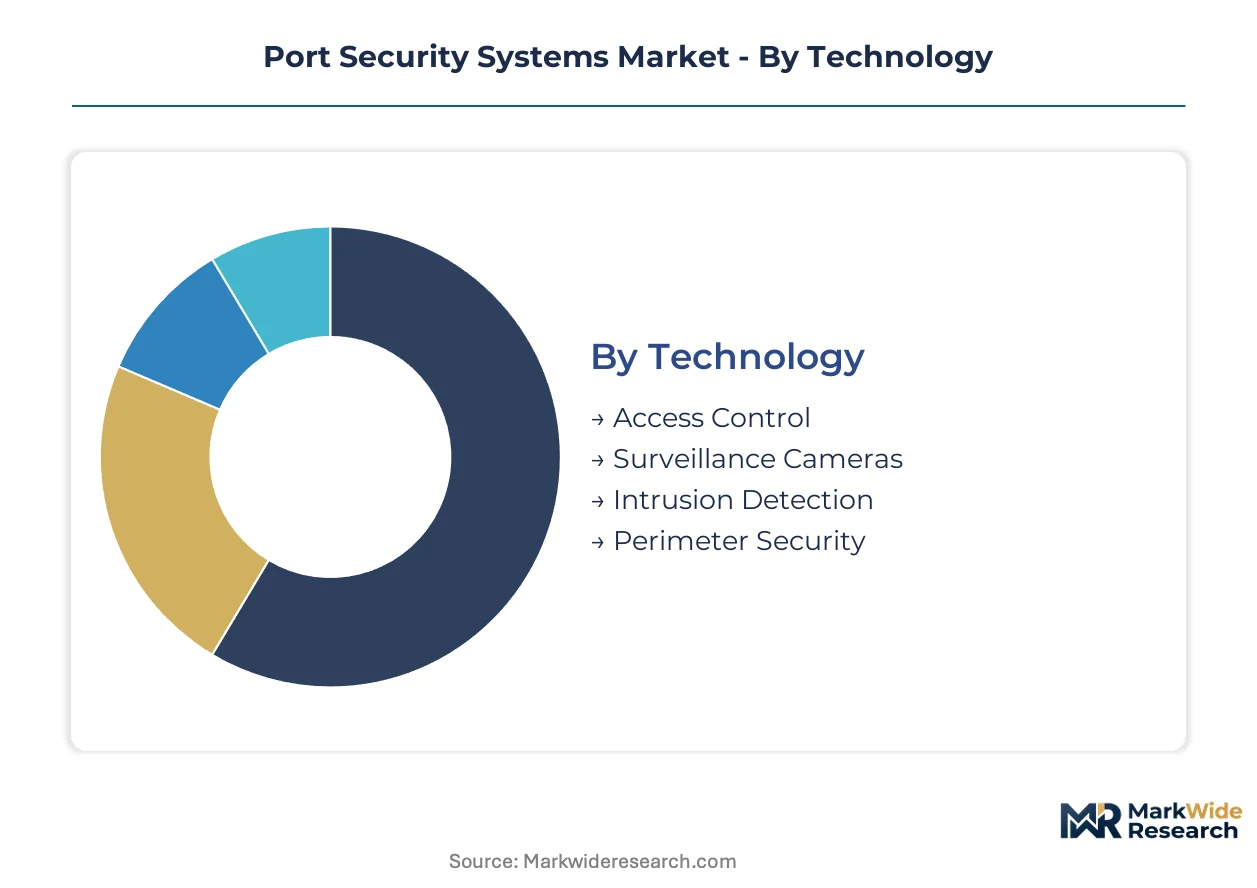
Port security procurement fragments across four distinct taxonomies that determine vendor selection criteria and contract structures. Technology choices dictate integration complexity, while application focus shapes compliance requirements and margin profiles. Deployment models and end-user categories further stratify purchasing power and lifecycle expectations across maritime infrastructure investments.
Technology:
Surveillance cameras face the most intense substitution pressure as AI-enabled video analytics collapses traditional hardware categories into unified platforms.
- Surveillance Cameras:Fixed and pan-tilt-zoom units with 640x512 pixel thermal imaging resolution form the visual backbone of terminal monitoring. Demand concentrates in Rotterdam and the Port of Los Angeles as these facilities modernize perimeter coverage to meet overlapping ISPS Code compliance deadlines.
- Intrusion Detection:Fiber-optic and ground-sensor arrays retrofit legacy fence infrastructure with automated breach notification capabilities. Singapore's transshipment hubs are accelerating deployments here as insurance-premium linkages deepen return-on-investment calculations for terminal operators.
- Access Control:Biometric and credential-based entry management systems regulate personnel movement through restricted zones. European harbor authorities prioritize these upgrades under the EU Critical Entities Resilience Directive's facility safety mandates.
- Perimeter Security:Integrated radar sweep systems operating at 30-60 RPM coordinate with physical barriers to create layered defense architectures. United States ports dominate procurement volumes as Maritime Transportation Security Act enforcement tightens.
Surveillance cameras retain volume leadership; intrusion detection holds the steepest expansion curve.
Application:
Cost tier stratification separates container security's premium integration requirements from facility safety's standardized compliance purchases.
- Container Security:Customs-integrated tracking and inspection systems command the deepest margin pools due to multi-agency coordination requirements. Rotterdam and Singapore lead procurement as these hubs process the highest container throughput volumes subject to international verification protocols.
- Facility Safety:Fire suppression, emergency response, and hazardous material containment systems protect terminal infrastructure and personnel. European harbor authorities consolidate spending here to satisfy the EU Critical Entities Resilience Directive's explicit interoperability standards.
- Cargo Monitoring:Real-time tracking and condition sensing for bulk and breakbulk commodities in transit. United States logistics providers are expanding deployments to centralize oversight across dispersed terminal networks.
- Vessel Protection:Shipboard and alongside security systems defending against boarding, piracy, and sabotage threats. Government agencies in the Netherlands and Singapore anchor demand through long-cycle naval defense heritage contracts.
Container security captures the premium pricing tier; facility safety generates the broadest addressable base.
Deployment:
Customer type divergence splits the market between capital-intensive on-premises installations and recurring-revenue remote monitoring services.
- Remote Monitoring:Centralized oversight platforms enabling logistics providers to manage security operations across fragmented terminal networks without on-site staffing. Singapore and the Netherlands favor this model for dispersed harbor facilities.
- On-premises:Locally hosted command-and-control infrastructure requiring dedicated hardware and personnel at each terminal site. Major transshipment hubs in the United States prefer this architecture for direct regulatory audit access.
- Cloud-based:Vendor-hosted analytics and storage reducing capital allocation for mid-tier ports with limited IT infrastructure. Adoption concentrates among European harbor authorities seeking rapid scalability.
- Hybrid:Architectures combining local processing for latency-critical functions with cloud analytics for historical trend analysis. Rotterdam's modernization programs are establishing templates for this balanced approach.
On-premises deployments retain volume leadership; remote monitoring climbs the fastest as service unbundling fragments traditional procurement.
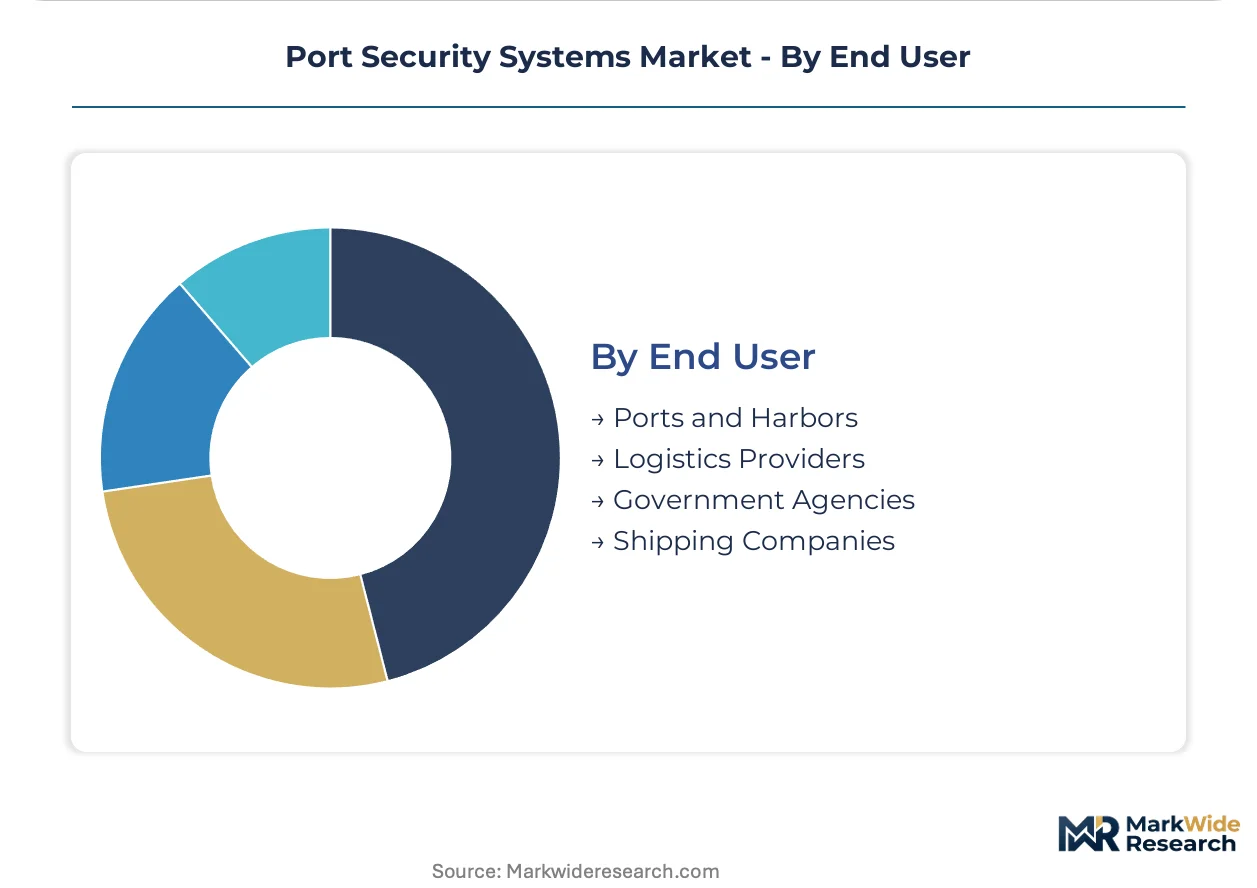
End User:
Supply concentration among government agencies and major port authorities creates procurement bottlenecks that favor vendors with certified end-to-end portfolios.
- Ports and Harbors:Terminal operators responsible for integrated security across cargo handling, storage, and transfer zones. Singapore, Rotterdam, and the Port of Los Angeles drive specification standards through simultaneous infrastructure overhauls.
- Government Agencies:Coast guards, customs authorities, and naval defense organizations mandating compliance and funding security upgrades. The U.S. Coast Guard's Maritime Transportation Security Act regulations and the EU's Critical Entities Resilience Directive shape procurement requirements.
- Logistics Providers:Third-party operators seeking centralized security management across multiple terminal contracts. These stakeholders are separating hardware acquisition from analytics subscriptions to capture recurring revenue streams.
- Shipping Companies:Vessel operators implementing shipboard protection and port interface security protocols. Compliance with the International Maritime Organization's ISPS Code drives baseline spending levels.
Ports and harbors retain volume leadership; logistics providers are gaining share fastest through remote monitoring centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Netherlands and Singapore demonstrate the lowest price elasticity, absorbing premium integrated systems, while United States port authorities face tighter capital constraints and favor phased retrofitting over wholesale replacement.
United States
The U.S. Coast Guard's Maritime Transportation Security Act enforcement drives perimeter radar and thermal imaging upgrades at the Port of Los Angeles and Long Beach. Terminal operators here prioritize on-premises command infrastructure for direct regulatory audit access, compressing procurement cycles as compliance deadlines approach.
Netherlands
Rotterdam's transshipment hub anchors European demand for container security systems with customs-integration requirements. The EU Critical Entities Resilience Directive mandates layered facility safety architectures, forcing harbor authorities to consolidate vendor relationships around certified end-to-end portfolios rather than multi-vendor stacks.
Singapore
Insurance-premium linkages and customs-integration mandates deepen margin pools for integrated providers at the city-state's transshipment terminals. Remote monitoring deployments gain traction among logistics providers managing dispersed harbor facilities across Southeast Asian networks.
Germany
Industrial automation expertise from building-technology divisions transfers into maritime facility safety under EU interoperability standards. Hamburg and Bremerhaven port authorities modernize access control networks and perimeter defense infrastructure to satisfy overlapping certification requirements.
China
Domestic transshipment expansion at Shanghai and Shenzhen ports drives vessel protection and cargo monitoring procurement. The country's national maritime regulator tightens security code compliance for international shipping interface zones, accelerating fiber-optic perimeter retrofitting programs.
Port Security Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated platform providers command premium positioning against point-solution specialists. The vendor base separates into naval defense heritage contractors, industrial automation conglomerates, and remote monitoring service specialists. Consolidation pressure favors certified portfolio holders as port authorities reduce vendor counts over multi-year modernization cycles. Dominant competitive moves include strategic partnerships for interoperability certification and geographic expansion through harbor authority framework agreements.
Within the naval defense heritage tier, Saab AB and BAE Systems plc represent long-cycle government contracting archetypes, while Siemens AG anchors the industrial automation-to-maritime transfer model. THALES occupies a position spanning both defense and civilian harbor security procurement channels.
| Leading Market Players |
|---|
| Saab AB |
| Siemens AG |
| RTX Corporation |
| THALES |
| Leidos Inc |
| Honeywell International Inc |
| BAE Systems plc |
| Johnson Controls |
| Teledyne FLIR LLC |
| Others |
Value Network & Pricing Analysis
Long-term framework agreements with certified portfolio vendors lock in both supply access and price visibility for port authorities navigating overlapping ISPS Code compliance deadlines in the United States, the Netherlands, and Singapore. These multi-year contracts bundle hardware acquisition with service subscriptions, compressing procurement cycles while embedding escalation clauses tied to thermal imaging sensor costs and AI analytics licensing fees.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for integrated platform providers, with recurring revenue streams capturing 40-60% of total contract value over deployment lifecycles. Three-tier pricing structure across premium certified systems, standard compliance-grade packages, and economy retrofit solutions stratifies the market by certification tier and integration complexity. Cost compression in thermal imaging hardware stems from 640x512 pixel sensor commoditization and competitive pressure from Chinese component suppliers. Logistics providers demonstrate the highest price sensitivity due to dispersed terminal centralization mandates, while government agencies in Singapore and the Netherlands absorb premium pricing for customs-integrated container security systems.
Supply Chain Analysis
China and Taiwan anchor thermal imaging sensor fabrication and radar component manufacturing for port security systems, with South Korea supplying specialized fiber-optic perimeter detection arrays. Supply chains draw from gallium arsenide substrates, germanium lenses, and AI processing chipsets, creating dependencies on semiconductor foundry capacity allocation. Single-source vulnerability concentrates in high-resolution thermal sensor modules where qualified suppliers remain limited. Distribution runs through harbor authority framework agreements and government procurement channels rather than open commercial markets, with Siemens AG and Saab AB leveraging direct contracting relationships to bypass traditional distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor base creates acquisition opportunities as port authorities consolidate around certified end-to-end portfolios, with service unbundling opening niches for remote monitoring specialists to capture recurring revenue streams previously held by integrated platform providers.
For Market Incumbents: Secure interoperability certification under the EU Critical Entities Resilience Directive and U.S. Coast Guard Maritime Transportation Security Act regulations to defend against emerging remote monitoring specialists. Vertical integration into AI-enabled video analytics software reduces dependency on third-party algorithm licensing. Capacity expansion in Singapore and Rotterdam harbor authority framework agreements anchors long-cycle government contracting positions against naval defense heritage competitors.
For New Entrants and Emerging Players: EU Critical Entities Resilience Directive fast-track certification creates entry pathways for industrial automation specialists transferring building-technology expertise into maritime facility safety. Remote monitoring deployments for logistics providers managing dispersed terminal networks represent the most penetrable white space, with Singapore and the Netherlands offering concentrated demand clusters. Cloud-based analytics subscriptions bypass capital-intensive on-premises infrastructure requirements, enabling rapid scaling without competing for harbor authority framework agreement slots.
For Investors and Strategic Acquirers: Capital is best deployed toward remote monitoring service specialists with proven recurring revenue models and established logistics provider relationships over the coming decade. Acquisition targets should demonstrate certified interoperability portfolios spanning radar, thermal imaging, and access control systems. The signal to watch is consolidation velocity among European harbor authorities as EU compliance deadlines compress vendor selection windows and favor incumbent scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | EU Critical Entities Resilience Directive mandates cross-system communication capabilities for operating certifications. |
| Remote Monitoring Service Launch | Singapore logistics providers seek centralized oversight across dispersed Southeast Asian terminal networks. |
| AI-Radar Convergence Development | Machine learning integration with 30-60 RPM systems enables predictive threat assessment in high-throughput cargo environments. |
| Harbor Authority Framework Agreement | Rotterdam and Port of Los Angeles simultaneous infrastructure overhauls compress procurement cycles toward certified vendors. |
| Backward Integration into Thermal Sensors | 640x512 pixel sensor cost compression and supply vulnerability create captive supply incentives for major platform providers. |
Research Methodology
A spread of perspectives from port security directors, harbor authority procurement officers, customs integration specialists, and naval defense program managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with terminal operators in Singapore, Rotterdam, and the Port of Los Angeles alongside secondary validation through U.S. Coast Guard Maritime Transportation Security Act filings, EU Critical Entities Resilience Directive implementation guidance, International Maritime Organization ISPS Code amendments, and customs authority procurement databases. Bottom-up equipment deployment tracking and top-down infrastructure investment flow analysis were triangulated to anchor volume and value estimates.
Segmentation dimensions modeled include technology type, application focus, deployment architecture, and end-user category across the analysis window. Technology splits captured surveillance camera, intrusion detection, access control, and perimeter security procurement patterns. Application segmentation separated container security, facility safety, cargo monitoring, and vessel protection investments. Deployment models tracked remote monitoring, on-premises, cloud-based, and hybrid adoption curves. CAGRs were derived from infrastructure modernization pipeline analysis and regulatory deadline clustering without year-specific anchoring. Forecast inputs incorporated radar sweep rate upgrade cycles, thermal imaging resolution transition timelines, and AI analytics penetration rates in high-throughput cargo environments.
Decision-makers should treat outputs as directional under assumptions of sustained ISPS Code enforcement intensity and continued insurance-premium linkage expansion for container security; material deviation in regulatory stringency or maritime trade volume would warrant model refresh. Recalibration cycles align with material shifts in EU directive implementation schedules, U.S. Coast Guard enforcement priorities, and transshipment hub infrastructure award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Network Access Control Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
China Access Control Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Building Access Control Security Market
Access Control Systems
Programmable Safety Systems Market