
 Pure Epoxy Powder Coatings Market | 2026-2036
Pure Epoxy Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Pure Epoxy Powder Coatings Market Intelligence
Modular coating service packages are restructuring how fabrication shops and equipment manufacturers procure finishing solutions. Akzo Nobel N.V. leverages its European formulation network to sustain premium-grade epoxy supply for industrial machinery clients. PPG Industries, Inc. anchors North American distribution through captive resin sourcing and regional blending facilities. Jotun A/S specializes in marine-grade anti-corrosion epoxies, occupying a defensible niche in salt-exposure applications.
Pure epoxy powder coatings comprise thermosetting resins based on diglycidyl ether of bisphenol-A (DGEBA) cured with amine or anhydride hardeners, applied at film builds of 50-150 microns through electrostatic spray or fluidized bed processes to deliver chemical resistance and dielectric protection on metal substrates. Anti-corrosion formulations command the deepest margin pools due to certification requirements in marine and offshore equipment, while texture finishes compete primarily on aesthetics for metal furniture and consumer-facing appliances. Electrostatic spray technology dominates volume throughput, though tribo charging gains ground in complex-geometry electrical enclosures where Faraday cage effects complicate conventional corona application.
EPA oversight in the United States restricts hazardous air pollutant emissions from coating operations, compelling OEMs to validate powder systems against Method 24 solvent-content thresholds. ECHA administers REACH registration for epoxy resin precursors imported into Europe, while China's MEE enforces dual carbon goals that favor powder coatings over liquid alternatives in state-backed industrial parks. Buyers must monitor evolving substance restrictions on bisphenol derivatives and assess whether their supplier base maintains multi-region regulatory dossiers.
Market Dynamics
REACH and RoHS compliance in Europe is forcing formulators to reformulate entire product portfolios, compressing development cycles while elevating technical barriers to market entry for unprepared suppliers.
Growth Catalysts
- Infrastructure electrification:Electrical enclosure manufacturers across China, India, and Germany are installing dedicated powder coating lines to serve grid modernization and EV charging infrastructure buildouts.
- Dual carbon goals:China's MEE enforcement favors powder coatings over liquid alternatives in state-backed industrial parks, redirecting capex toward low-VOC epoxy systems.
- Tribo charging advancement:Complex-geometry electrical enclosure fabricators are adopting tribo spray technology to overcome Faraday cage effects that plague conventional corona application.
Market Restraints
- Bisphenol derivative restrictions:ECHA substance evaluations and evolving EPA Method 24 thresholds are narrowing the approved precursor chemistry set for DGEBA-based formulations.
- Captive resin concentration:North American supply depends heavily on PPG Industries' regional blending facilities, creating single-source vulnerability for industrial machinery clients.
- Cure energy intensity:Epoxy powder systems require 180-200°C substrate temperatures for full crosslinking, excluding heat-sensitive substrates and limiting substrate versatility versus UV-curable alternatives.
Strategic Opportunities
- Marine certification depth:Salt-exposure applications in offshore wind and shipbuilding reward Jotun A/S-style specialization with defensible margin pools unavailable to generalist suppliers.
- Modular service packaging:Fabrication shops are unbundling coating operations from in-house capex, creating demand for toll-coating and coating-as-a-service models.
- Texture finish premiumization:Metal furniture and consumer appliance OEMs are specifying aesthetic-grade epoxies with differentiated haptic properties, opening margin expansion outside commodity anti-corrosion grades.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance amine and anhydride hardener systems with REACH-compliant precursors concentrates among aging technical staff at established European networks.
- Multi-region dossier maintenance:Suppliers must simultaneously track ECHA registrations, EPA hazardous air pollutant validations, and China's GB standard evolutions, fragmenting compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pure Epoxy Powder Coatings Market |
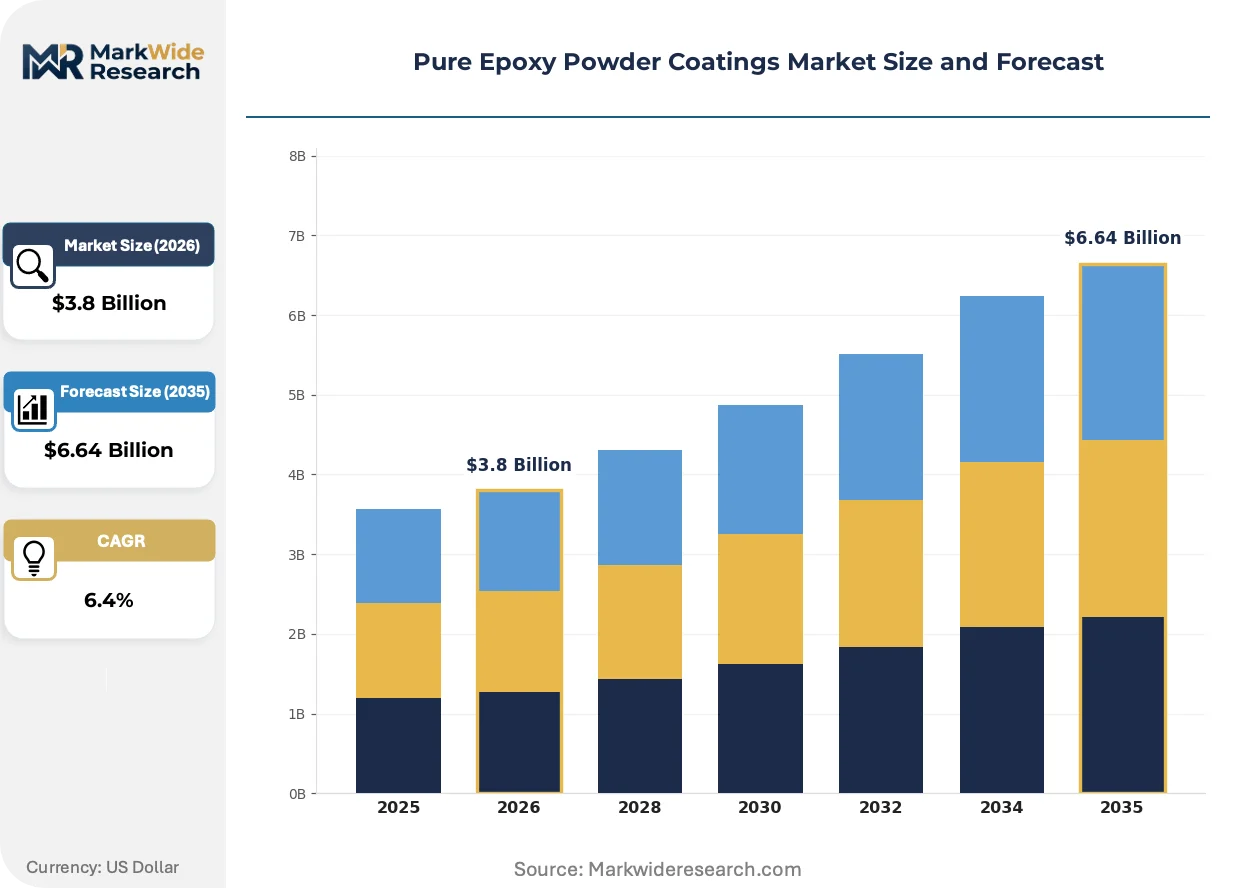
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Epoxy, Modified Epoxy, High-Gloss, Texture, Anti-Corrosion, Heat-Resistant Application: Industrial Machinery, Electrical Enclosures, Metal Furniture, Marine Equipment, Appliances, HVAC Systems Technology: Electrostatic Spray, Fluidized Bed, Twin-Stage, Tribo Charging, Powder Slurry, Corona Treatment End User: Equipment Manufacturers, Fabrication Shops, Maintenance Providers, OEMs, Metal Processors, Contractors |
| Companies Covered | Axalta Coating Systems, Nippon Paint Holdings Co., Ltd., Akzo Nobel N.V., Evonik Industries AG, BASF SE, PPG Industries, Inc., Jotun A/S, Solvay S.A., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pure Epoxy Powder Coatings Market Strategic Shifts & Innovations
Electrostatic spray equipment and curing infrastructure is modularizing into containerized, redeployable units that decouple coating capacity from fixed factory footprints.
Tribo charging systems are modularizing around plug-and-play gun configurations that electrical enclosure manufacturers can reconfigure without line shutdowns. Tier-one automotive suppliers in Germany are piloting these systems for prototype runs. The technology is modularizing quality control by embedding real-time voltage monitoring at each gun station.
REACH authorization requirements for epoxy resin precursors are compressing the approved substance list ahead of 2027 sunset dates. Formulators in the Netherlands and Belgium are accelerating substitution programs for bisphenol-A derivatives. Marine-grade suppliers face the steepest reformulation burden due to salt-spray certification dependencies on legacy chemistries.
Buyer consolidation among electrical OEMs is compressing supplier qualification cycles and demanding consolidated coating service contracts spanning multiple fabrication sites. Tier-one enclosure manufacturers in China are unbundling coating from component sourcing, treating finishing as a separable procurement category. This pattern is most visible in state-backed industrial parks where MEE enforcement has already eliminated liquid coating alternatives.
Pure Epoxy Powder Coatings Market Segmentation
Capital allocation patterns across the Pure Epoxy Powder Coatings Market diverge sharply by segment. Equipment manufacturers and coating service providers must match substrate requirements, regulatory constraints, and throughput economics to specific formulation and application technologies.
Product Type:
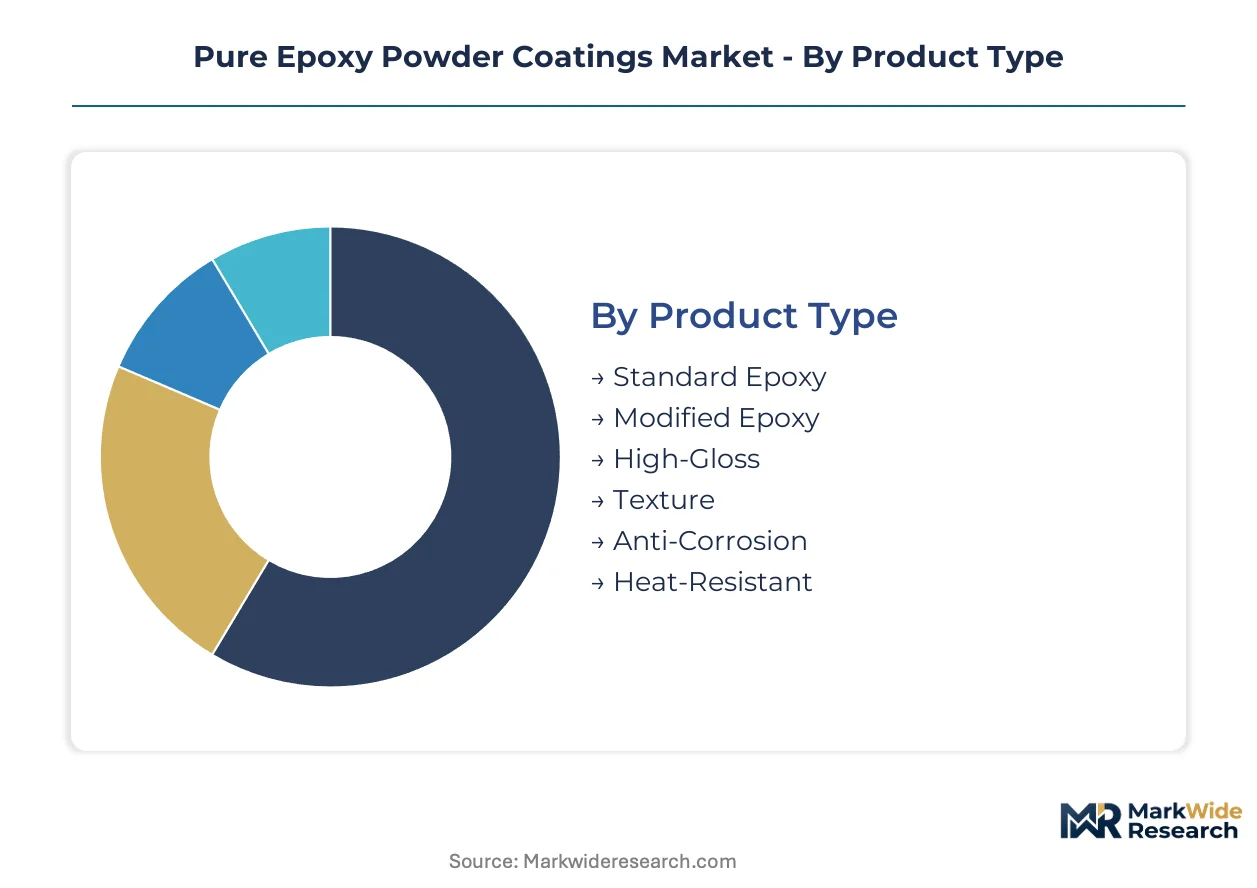
Capital-intensity varies most dramatically in this category, with certification-heavy formulations demanding specialized curing infrastructure and testing protocols that smaller formulators cannot replicate.
- Anti-Corrosion:Marine-grade formulations incorporate zinc-rich primers and high-build epoxy matrices certified to salt-spray standards. Offshore wind installations in the North Sea and shipyards in South Korea and Japan concentrate procurement for this segment. Certification maintenance consumes 15-20% of annual R&D budgets at specialized suppliers.
- Texture:Surface aesthetics drive specification for metal furniture and consumer-facing appliances, with haptic differentiation commanding 12-18% price premiums over smooth-finish equivalents. German kitchen appliance OEMs and Italian furniture manufacturers anchor European demand.
- Standard Epoxy:General-purpose DGEBA formulations serve cost-sensitive industrial applications with baseline chemical resistance requirements.
- Modified Epoxy:Hybrid resin systems blend epoxy with polyester or acrylic modifiers to improve weatherability for outdoor electrical enclosures.
- High-Gloss:Optical-grade clearcoats protect decorative metal substrates in retail fixtures and premium appliance segments.
- Heat-Resistant:Anhydride-cured systems tolerate continuous operating temperatures above 150°C for engine components and exhaust systems.
Most installed capacity flows through Standard Epoxy. Expansion is steepest in Anti-Corrosion.
Application:
Customer procurement sophistication separates this category, with electrical enclosure manufacturers demanding integrated coating-as-a-service contracts while metal furniture buyers negotiate spot pricing.
- Electrical Enclosures:Grid modernization and EV charging infrastructure buildouts in China, India, and Germany are accelerating dedicated powder coating line installations. Tribo charging technology adoption runs highest here due to complex Faraday cage geometries in switchgear housings.
- Marine Equipment:Salt-exposure applications in offshore wind and shipbuilding reward specialized certification depth with margin pools unavailable to generalist suppliers. Jotun A/S occupies a defensible position in this segment.
- Industrial Machinery:Heavy equipment manufacturers specify anti-corrosion epoxies for underbody and hydraulic component protection.
- Metal Furniture:Aesthetic-grade texture finishes dominate outdoor and office furniture applications.
- Appliances:Washing machines, refrigerators, and cooking equipment use high-gloss and texture formulations for consumer-facing surfaces.
- HVAC Systems:Heat exchangers and ducting require corrosion-resistant coatings for outdoor installation durability.
Electrical Enclosures absorbs the largest share of new coating line investment. Marine Equipment shows the steepest margin expansion trajectory.
Technology:
Application method selection hinges on substrate geometry complexity, film build requirements, and line throughput economics rather than capital cost alone.
- Electrostatic Spray:Corona charging dominates volume throughput across high-production environments. PPG Industries anchors North American supply through captive resin sourcing optimized for this technology.
- Tribo Charging:Friction-based charging systems overcome Faraday cage effects in complex electrical enclosure geometries. German tier-one automotive suppliers are piloting plug-and-play gun configurations for prototype flexibility.
- Fluidized Bed:Dip coating of preheated parts delivers thick film builds for pipe fittings and rebar applications.
- Twin-Stage:Sequential primer-topcoat application improves edge coverage on sharp metal profiles.
- Powder Slurry:Aqueous dispersion systems enable thin-film application on heat-sensitive substrates below standard cure temperatures.
- Corona Treatment:Surface activation pretreatment improves adhesion on problematic metal alloys and recycled substrates.
Electrostatic Spray commands the largest installed base. Tribo Charging is gaining share fastest in electrical enclosure fabrication.
End User:
Procurement model fragmentation creates distinct service requirements, from toll-coating arrangements for fabrication shops to integrated supply contracts for multinational OEMs.
- Equipment Manufacturers:In-house coating operations at electrical enclosure and appliance OEMs are unbundling finishing from component sourcing. Chinese tier-one enclosure manufacturers now treat coating as a separable procurement category in state-backed industrial parks.
- Fabrication Shops:Modular coating service packages are restructuring how small and mid-size metal processors procure finishing solutions, shifting capex to operating expense models.
- Maintenance Providers:Aftermarket recoating of industrial machinery and infrastructure drives spot demand for matched color and performance specifications.
- OEMs:Original equipment manufacturers with multi-site production networks negotiate consolidated coating service contracts spanning multiple fabrication locations.
- Metal Processors:Toll-coating specialists serve customers lacking in-house application infrastructure or regulatory compliance capabilities.
- Contractors:Field application services address on-site recoating of installed equipment and structural steel.
Equipment Manufacturers deploy the most captive coating capacity. Fabrication Shops are converting to outsourced service models most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powder coating technology first achieved industrial scale in Germany during the 1960s, establishing the Rhine-Ruhr corridor as the foundational center for thermoset formulation chemistry before dispersing to Asia-Pacific manufacturing hubs.
Germany
Electrical enclosure manufacturers in Bavaria and Baden-Württemberg are installing dedicated tribo charging lines to serve EV charging infrastructure buildouts. ECHA REACH enforcement is accelerating reformulation programs for bisphenol-A derivatives ahead of 2027 sunset dates. The Stuttgart industrial cluster concentrates marine-grade certification expertise for offshore wind applications.
China
State-backed industrial parks in Jiangsu and Guangdong provinces are redirecting capex toward low-VOC epoxy systems under MEE dual carbon enforcement. Grid modernization and charging infrastructure projects are absorbing the bulk of new powder coating line investment. The Yangtze River Delta hosts the densest concentration of electrical enclosure fabrication capacity.
United States
EPA Method 24 compliance is compelling OEMs to validate powder systems against hazardous air pollutant thresholds for industrial machinery finishing. Captive resin sourcing through regional blending facilities anchors supply security for heavy equipment manufacturers. The Ohio-Michigan industrial corridor maintains legacy infrastructure for automotive and appliance coating applications.
India
Electrical infrastructure expansion in Maharashtra and Gujarat is driving demand for corrosion-resistant enclosure coatings. BIS standards evolution is gradually tightening VOC limits for industrial finishing operations. The Pune-Nashik manufacturing belt is emerging as a secondary hub for powder coating service providers.
South Korea
Shipyards in Busan-Ulsan and offshore wind fabrication in the southeast region are sustaining procurement for salt-spray certified marine formulations. Domestic formulators are navigating REACH-equivalent precursor registration requirements for export markets. The Gyeongnam industrial complex specializes in high-build epoxy matrices for heavy marine equipment.
Pure Epoxy Powder Coatings Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and regulatory dossier maintenance. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive resin networks, specialized coating formulators with marine or electrical niche depth, and regional toll-coating service providers. Consolidation pressure concentrates among mid-scale European formulators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into epoxy resin production and geographic expansion through toll-coating partnership networks.
Among European formulation specialists, Akzo Nobel N.V. and Jotun A/S exemplify divergent archetype strategies. Akzo Nobel N.V. occupies a position emphasizing broad industrial coverage through distributed blending networks. Jotun A/S represents the certification-depth archetype, anchoring defensible margin pools in salt-exposure applications. PPG Industries, Inc. sits within the captive-supply tier, with its company name indicating North American industrial heritage and corporate structure.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Nippon Paint Holdings Co., Ltd. |
| Akzo Nobel N.V. |
| Evonik Industries AG |
| BASF SE |
| PPG Industries, Inc. |
| Jotun A/S |
| Solvay S.A. |
| The Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
Epoxy resin precursor costs cascade through formulation tiers with DGEBA feedstock volatility compressing margins at standard-grade suppliers while marine-certified formulators in Germany and South Korea command defensible premiums. REACH-compliant bisphenol-A alternatives carry 15-20% raw material uplifts that tier-one buyers absorb through consolidated coating service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates marine-grade certified formulations from commodity industrial epoxies and toll-coating spot rates. Certification depth and REACH dossier maintenance drive price differentiation, with salt-spray validated systems commanding 25-35% premiums over baseline anti-corrosion grades. Cost compression in standard epoxy tiers intensifies because Chinese state-backed industrial parks favor low-VOC systems through MEE enforcement. Fabrication shops exhibit highest price sensitivity, while electrical enclosure OEMs prioritize regulatory compliance over unit economics.
Supply Chain Analysis
Formulation chemist scarcity in the Netherlands and Belgium concentrates specialized knowledge at aging European technical networks, constraining new capacity deployment. Raw material sourcing draws from Saudi petrochemical complexes for DGEBA precursors, German specialty chemical producers for anhydride hardeners, and Chinese state-owned enterprises for zinc-rich primer feedstocks. Single-source vulnerability runs through PPG Industries' regional North American blending facilities. Distribution runs through captive resin networks for multinational OEMs and toll-coating partnerships for mid-size fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between China's MEE-enforced low-VOC mandates and India's gradually tightening BIS standards, with cost differentials favoring early capacity positioning in Maharashtra and Gujarat ahead of regulatory convergence.
For Market Incumbents: Hedge against REACH 2027 sunset dates by accelerating bisphenol-A derivative substitution programs in Netherlands and Belgium formulation centers. Deepen backward integration into epoxy resin production to offset captive supply vulnerabilities. Prioritize tribo charging technology certification for electrical enclosure applications where Faraday cage complexity creates switching costs. For New Entrants and Emerging Players: Capture modular coating service contracts from Chinese tier-one enclosure manufacturers unbundling finishing operations in Jiangsu and Guangdong state-backed industrial parks. Target India's Pune-Nashik manufacturing belt where electrical infrastructure expansion outpaces local formulation capacity. Lead with toll-coating partnerships that convert fabrication shop capex to operating expense models. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale European formulators face REACH compliance cost escalation without marine certification depth to justify premium pricing. Five-to-ten year viability favors specialists with multi-region regulatory dossiers and salt-spray validated product lines. Watch ECHA substance evaluation timelines as inflection indicators for precursor chemistry substitution waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive DGEBA supply secures margin control against petrochemical feedstock volatility. |
| Tribo Charging Technology Certification | Plug-and-play gun configurations unlock electrical enclosure contracts with complex geometries. |
| Marine-Grade Salt-Spray Certification Investment | Offshore wind procurement in North Sea and Busan-Ulsan rewards specialized formulation depth. |
| Toll-Coating Partnership Network Expansion | Modular service packaging converts fabrication shop capex to recurring revenue streams. |
| REACH-Compliant Precursor Substitution Program | Bisphenol-A alternative registration ahead of 2027 sunset dates preserves European market access. |
Research Approach
Bottom-up electrical enclosure and marine equipment modeling reconciled against top-down resin precursor supply tracking forms the analytical core. Primary interviews with plant managers at powder coating line installations, procurement leads at electrical OEMs, distribution channel partners in coating service networks, and technical R&D directors at European formulation centers combined with secondary validation from ECHA registration databases, customs trade data for DGEBA imports, SEC 10-K filings of listed coating suppliers, and MEE enforcement disclosures in Chinese state-backed industrial parks. Triangulation between demand-side capacity installation tracking and supply-side raw material flow analysis ensures cross-verified outputs.
Historical trendline analysis of powder coating line investments across China, India, and Germany established baseline growth trajectories extended across the projection horizon. Segmentation modeling incorporated product grade tier, end-use application, charging technology type, and regional regulatory cluster dimensions. CAGRs derived from capacity utilization rates and line throughput economics at captive and toll-coating facilities. Industry-specific forecast inputs included MEE dual carbon enforcement timelines and ECHA substance evaluation schedules.
Regulatory acceleration, raw material substitution cost spikes, and electrical infrastructure investment delays are the dominant revision risks. Forecasts reflect documented assumptions on REACH compliance cost pass-through rates and tribo charging adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Antifouling Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Waterborne Wood Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Acrylic Coating Market
Coatings
Corrosion Protection Coating Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Global Sputter Coater Market
Coatings
In-Mold Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Anti-Adhesion Coatings Market