
 UV-Curable Adhesives Market | 2026-2036
UV-Curable Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
UV-Curable Adhesives Market Intelligence
The UV-curable adhesives tier is consolidating around two distinct value bands. Henkel AG & Co. KGaA leverages its European manufacturing footprint to dominate specification-grade electronics applications. H.B. Fuller Company anchors its position through captive resin synthesis for flexible packaging laminating. 3M Company differentiates via patented oligomer platforms serving medical device bonding.
UV-curable adhesives are single-component systems polymerized by ultraviolet light in the 200–400 nm range, typically comprising photoinitiators, oligomers, and reactive diluents that cure in seconds without solvents. Acrylic formulations command the largest volume share due to their optical clarity and tunable modulus for display bonding. The electronics end-user segment represents the fastest-expanding demand pool, driven by camera module assembly and PCB protection applications where low-Viscosity technology enables precise micro dispensing.
EPA regulations on volatile organic compound emissions constrain solvent-based alternatives, directly expanding UV-curable penetration in US manufacturing. REACH authorization requirements for photoinitiator substances force European suppliers to reformulate around safer chemistry platforms. FDA device master file expectations for medical-grade adhesives raise compliance barriers that favor established registrants over new entrants. Stakeholders must monitor mercury lamp phase-out timelines and LED curing equipment compatibility as these technology transitions reshape formulation requirements and capital deployment decisions.
Market Dynamics
Mercury lamp phase-out mandates are forcing immediate reformulation of photoinitiator systems, compressing equipment replacement cycles and redrawing supplier qualification criteria across electronics and medical device supply chains.
Growth Catalysts
- REACH Authorization Pressure:ECHA's tightening controls on hazardous photoinitiators accelerate mercury-free formulation adoption among European adhesive suppliers.
- Camera Module Miniaturization:Electronics manufacturers demand low-viscosity UV systems for micro-dispensing in smartphone and automotive sensor assembly.
- LED Curing Equipment Penetration:Solid-state UV sources reduce energy consumption and enable inline process integration for high-speed manufacturing lines.
Market Restraints
- Oligomer Supply Concentration:Specialty acrylate resin production clusters in Germany and Japan, exposing formulators to single-source risk and extended lead times.
- Substrate Compatibility Limitations:UV-curable chemistry fails to bond low-surface-energy plastics without costly plasma or corona pre-treatment.
- Photoinitiator Cost Volatility:Benzoin derivative and phosphine oxide prices swing with benzene feedstock and rare earth catalyst availability.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and mobile device assembly create specification-grade adhesive demand in Tamil Nadu and Karnataka clusters.
- Flexible Hybrid Electronics:Convergence of printed electronics and UV-curable stretchable conductors opens wearable health monitor and automotive interior applications.
- Revised FDA Device Master File Pathways:Streamlined submission procedures for medical-grade UV adhesives reduce time-to-market for surgical device bonding applications.
Industry Challenges
- Formulation Chemist Scarcity:Photochemistry expertise required for photoinitiator-synergy optimization commands premium compensation and extended recruitment cycles.
- Dual-Cure System Integration:Hybrid UV-moisture or UV-thermal platforms complicate process validation and quality assurance protocols for automotive Tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV-Curable Adhesives Market |
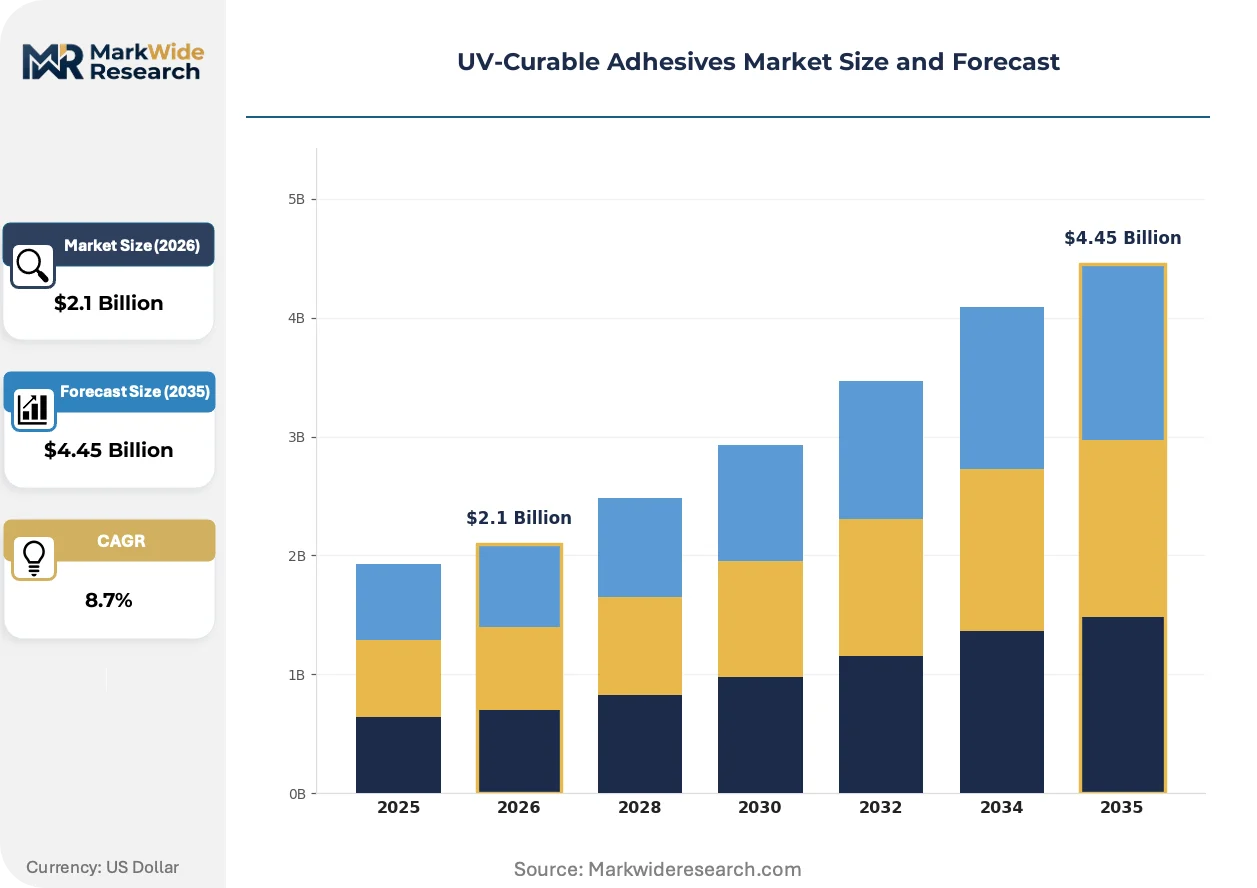
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
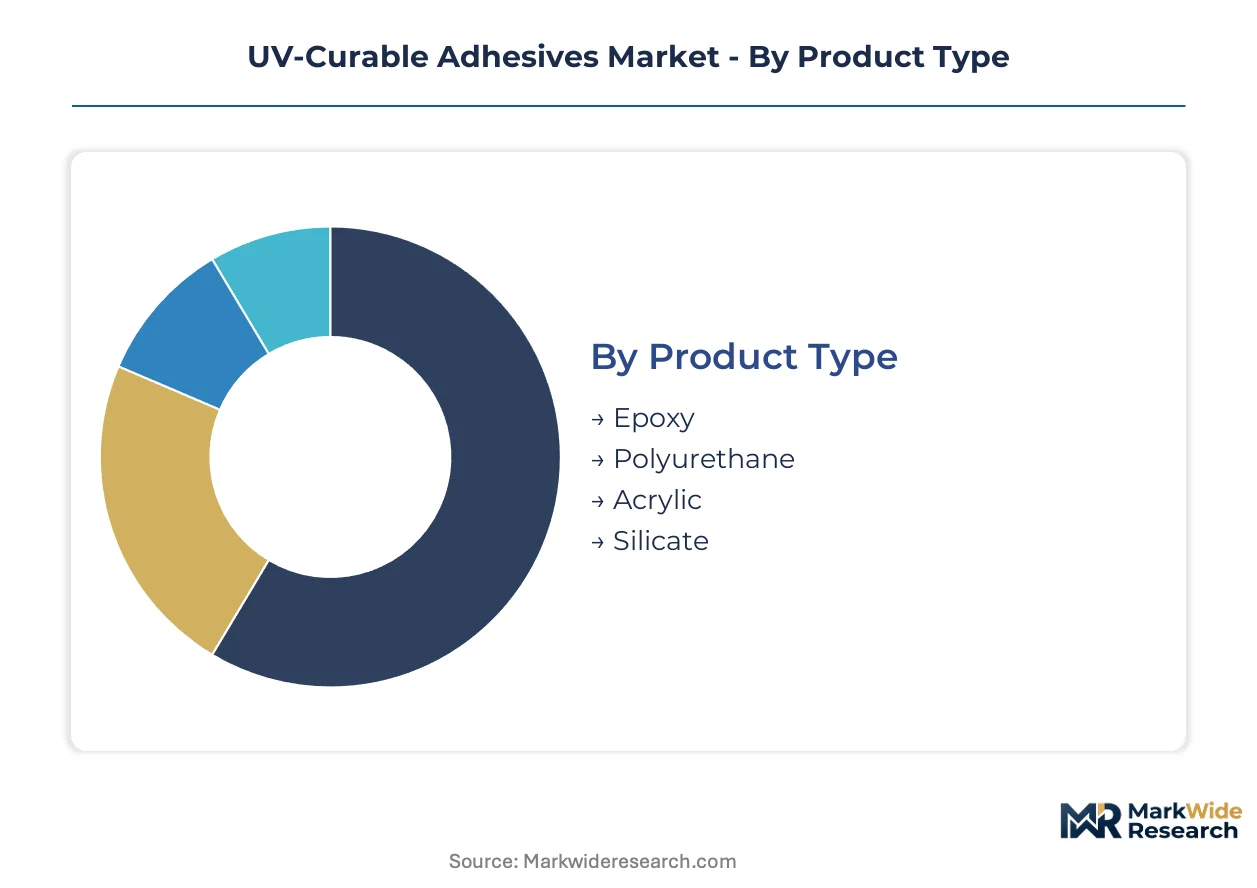
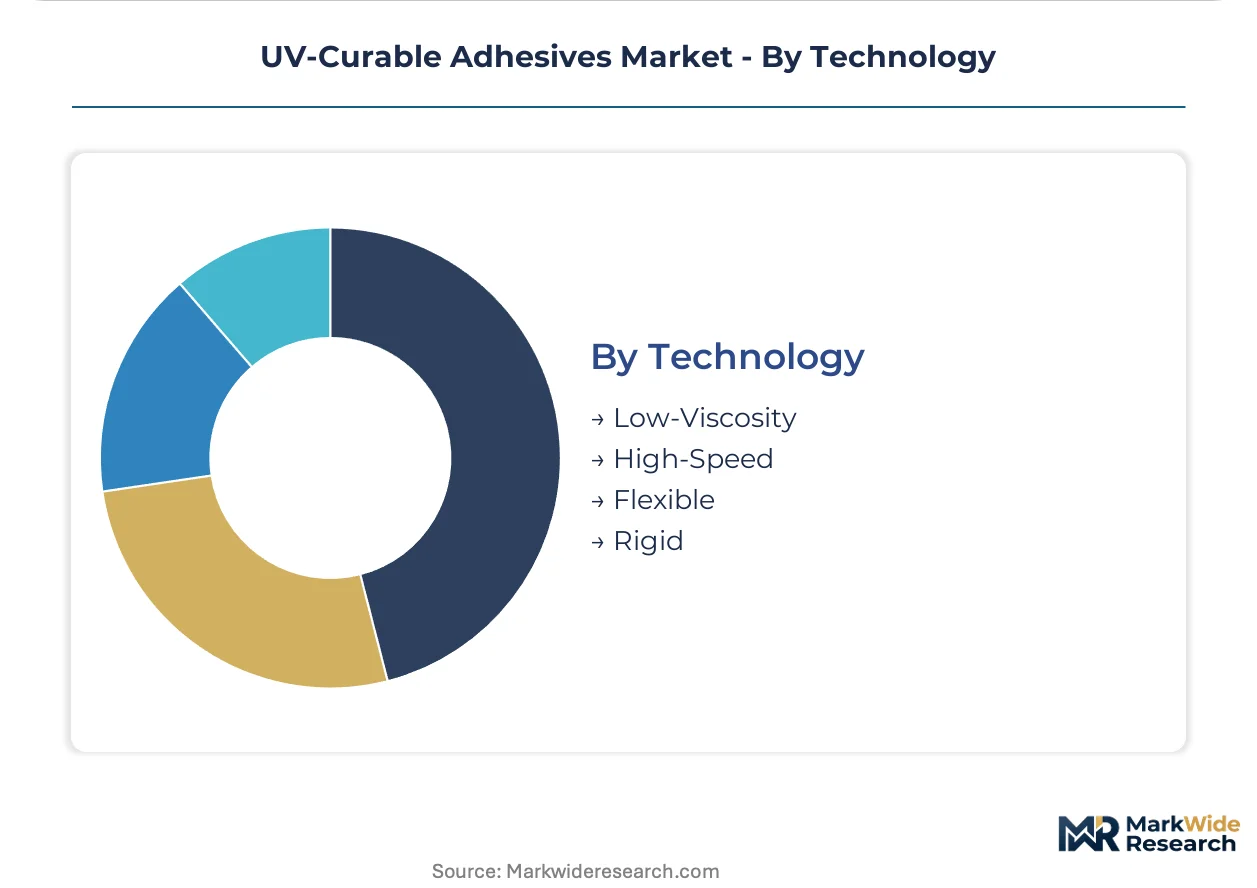
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicate End User: Electronics, Automotive, Medical, Packaging Application: Bonding, Coating, Sealing, Laminating Technology: Low-Viscosity, High-Speed, Flexible, Rigid |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dymax Corporation, Arkema, Sika AG, Permabond LLC, Master Bond Inc., Panacol-Elosol GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV-Curable Adhesives Market Strategic Shifts & Innovations
Formulation chemistry and curing hardware are converging to eliminate process variability, with suppliers embedding predictive control systems and real-time viscosity monitoring into integrated adhesive-dispensing platforms.
Cationic epoxy-UV hybrid systems are modularizing process flexibility for manufacturers running mixed substrate portfolios. Automotive lighting and display module assemblers adopt these platforms to switch between polycarbonate, PMMA, and glass bonding without line changeover. The technology is modularizing capital deployment decisions by reducing dedicated-line requirements and enabling contract manufacturers to serve multiple end-use verticals from shared assets.
EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) for surface coating operations tighten volatile organic compound limits in US manufacturing facilities. Solvent-based adhesive users face compliance-driven capital expenditure for emission control equipment, directly expanding UV-curable penetration in metal finishing and wood coating applications. Midwest automotive suppliers and Southeast furniture manufacturers accelerate qualification timelines for 100% solids UV alternatives.
Specification-grade procurement is consolidating around adhesive-dispenser system partnerships rather than discrete material purchasing. Medical device OEMs in Minnesota and Massachusetts negotiate multi-year supply agreements bundling formulated resin, precision dispensing equipment, and validation support services. European electronics contract manufacturers in Bavaria and Baden-Württemberg mirror this pattern, favoring integrated platform providers over commodity chemical distributors for high-reliability applications.
UV-Curable Adhesives Market Segmentation
UV-curable adhesive procurement decisions pivot on formulation chemistry, curing hardware compatibility, and end-use certification requirements. Each segmentation dimension carries distinct supply chain implications for inventory management, technical service support, and regulatory documentation.
Product Type:
Specialty resin production concentrates in Germany's industrial corridor and Japan's chemical manufacturing zones, exposing formulators to feedstock availability risks and extended qualification timelines.
- Acrylic:Dominates volume through optical clarity and tunable modulus characteristics. Camera module assembly in Bavaria and smartphone manufacturing in Tamil Nadu drive specification-grade procurement for display bonding applications.
- Epoxy:Cationic epoxy-UV hybrid systems deliver superior adhesion to low-surface-energy substrates. Automotive lighting manufacturers in Michigan and Baden-Württemberg adopt these platforms for polycarbonate and PMMA bonding without line changeover.
- Polyurethane:Offers flexibility and impact resistance for dynamic load-bearing joints.
- Silicate:Provides thermal stability for high-temperature electronics encapsulation.
Today's leader: Acrylic. Tomorrow's challenger: Epoxy.
End User:
Customer procurement patterns diverge sharply between specification-grade OEMs and commodity contract manufacturers, with certification documentation requirements determining supplier selection criteria.
- Electronics:Miniaturized component assembly demands low-viscosity systems for micro-dispensing. PCB protection and camera module bonding in Karnataka and Massachusetts clusters accelerate mercury-free photoinitiator adoption.
- Medical:FDA device master file expectations and EMA quality system requirements raise compliance barriers. Surgical device manufacturers in Minnesota and Switzerland favor integrated adhesive-dispenser platform partnerships over discrete material purchasing.
- Automotive:Tier-1 suppliers in Michigan and Bavaria validate dual-cure systems for interior module assembly.
- Packaging:Flexible laminating applications in Southeast Asia and the US Midwest shift from solvent-based alternatives under EPA NESHAP compliance pressure.
Electronics commands current volume leadership. Medical represents the steepest expansion trajectory as device master file pathways streamline.
Application:
Process equipment integration requirements vary substantially across application modes, with inline curing systems favoring high-speed coating and sealing over batch-mode bonding operations.
- Bonding:Structural assembly of dissimilar materials requires precise viscosity control and substrate-specific surface preparation protocols.
- Coating:Conformal protection of sensitive electronics dominates demand in semiconductor packaging facilities.
- Sealing:Hermetic enclosure applications in medical device and automotive sensor manufacturing demand zero-defect cure verification systems.
- Laminating:Flexible packaging converters in the US Midwest and Southeast Asia accelerate UV-curable penetration as EPA emission standards tighten on solvent-based alternatives.
Coating holds established position in electronics protection. Laminating gains share fastest under regulatory pressure on volatile organic compound emissions.
Technology:
Curing hardware transitions from mercury arc lamps to LED solid-state sources are redrawing formulation compatibility requirements and capital deployment decisions across all technology tiers.
- Low-Viscosity:Enables precise micro-dispensing for camera module assembly and fine-pitch PCB applications. Smartphone manufacturers in Tamil Nadu and automotive sensor suppliers in Baden-Württemberg specify these systems for high-speed production lines.
- Flexible:Stretchable conductor applications in wearable health monitors and automotive interior electronics open hybrid printed electronics opportunities.
- High-Speed:Optimized for inline processing with rapid cure kinetics under high-intensity LED arrays.
- Rigid:Delivers maximum structural integrity for load-bearing assemblies and permanent fixation applications.
Low-Viscosity dominates current procurement. Flexible platforms emerge as the critical enabler for next-generation hybrid electronics manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photochemistry talent concentrates in Germany's industrial corridor and Japan's chemical manufacturing zones, anchoring formulation innovation for specification-grade applications. Regional demand patterns diverge sharply between electronics manufacturing clusters in Asia and medical device production centers in North America and Europe.
Germany
Automotive lighting and display module assemblers in Baden-Württemberg and Bavaria drive cationic epoxy-UV hybrid adoption for polycarbonate and PMMA bonding. ECHA REACH authorization requirements force mercury-free photoinitiator reformulation across adhesive suppliers serving the industrial corridor. Stuttgart and Munich clusters validate dual-cure systems for Tier-1 automotive interior assembly.
United States
EPA NESHAP emission standards for surface coating operations accelerate UV-curable penetration in Midwest automotive and Southeast furniture manufacturing. FDA device master file expectations in Minnesota and Massachusetts raise compliance barriers favoring integrated adhesive-dispenser platform partnerships. Minnesota's surgical device corridor and Massachusetts medical technology cluster concentrate specification-grade procurement.
China
Camera module assembly and smartphone manufacturing in the Yangtze River Delta and Pearl River Delta generate massive low-viscosity system demand for micro-dispensing applications. MIIT industrial standards and GB certification requirements shape photoinitiator selection criteria for electronics contract manufacturers. Shenzhen and Shanghai clusters drive LED curing equipment integration for high-speed production lines.
India
PLI scheme incentives for semiconductor and mobile device assembly create specification-grade adhesive demand in Tamil Nadu and Karnataka electronics manufacturing clusters. BIS certification requirements and CDSCO medical device regulations establish quality thresholds for imported formulations. Chennai and Bengaluru contract manufacturers accelerate mercury-free photoinitiator qualification timelines.
Japan
Specialty acrylate resin production and oligomer synthesis expertise concentrate in Chubu and Kansai chemical manufacturing zones. METI energy efficiency standards and JIS quality specifications influence LED curing equipment adoption patterns. Nagoya and Osaka-based formulators supply high-reliability electronics and automotive applications across Asia-Pacific.
UV-Curable Adhesives Market Key Industry Players
Top-tier vendors anchor specification-grade electronics and medical applications, while mid-scale formulators serve flexible packaging and industrial bonding segments. The vendor base stratifies across integrated resin producers, captive compounders, and regional distributors. Three archetypes dominate: European industrial conglomerates with captive resin synthesis, American diversified materials companies with patented oligomer platforms, and Asian contract manufacturers with cost-optimized formulations. Competitive moves concentrate on strategic partnerships bundling adhesive and dispensing equipment, plus geographic expansion into India electronics manufacturing clusters.
Within the European industrial tier, Henkel AG & Co. KGaA and Sika AG exemplify integrated resin-to-formulation control. Among American diversified players, 3M Company and H.B. Fuller Company occupy positions spanning multiple end-use verticals through distinct technology platforms. Dymax Corporation represents the specialist archetype focused on precision curing systems and application-specific formulations. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their visible structural characteristics.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Dymax Corporation |
| Arkema |
| Sika AG |
| Permabond LLC |
| Master Bond Inc. |
| Panacol-Elosol GmbH |
| Others |
Cost & Logistics Intelligence
Benzene feedstock indices and rare earth catalyst pricing cascade through UV-curable adhesive supply chains, compressing margins at commodity tiers while specification-grade producers in Germany and Japan maintain pricing power through captive oligomer synthesis.
Pricing Analysis
Adhesive-dispenser platform partnerships versus discrete material purchasing splits the market into bundled and unbundled service tiers. Premium-mid-economy pricing differentiation tracks certification grade and volume scale, with FDA device master file holders commanding substantial premiums over commodity formulators. Cost compression in standard-grade electronics applications intensifies as Chinese contract manufacturers scale LED-compatible formulations. Contract manufacturers in Tamil Nadu and Karnataka exhibit highest price sensitivity, while Minnesota surgical device OEMs prioritize validation support over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit anchor hub-and-spoke patterns for time-sensitive specification-grade deliveries. Specialty acrylate resin production concentrates in Germany, Japan, and China, exposing formulators to single-source vulnerability when qualification timelines extend. Photoinitiator synthesis draws from benzene derivatives and phosphine oxide chemistry tethered to petrochemical and rare earth supply chains. Distribution runs through authorized distributor networks for medical-grade materials, while electronics applications tolerate broader channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-curable adhesive markets offer margin-expansion pathways through mercury-free photoinitiator premiumization and LED curing equipment bundling, as compliance-driven specification upgrades displace commodity solvent-based alternatives.
For Market Incumbents: Acquire captive photoinitiator synthesis capabilities to secure supply continuity as ECHA REACH authorization pressure accelerates reformulation cycles. Expand technical service teams in Tamil Nadu and Karnataka to capture PLI scheme-driven specification-grade demand. Defend against Asian cost-optimized entrants by embedding predictive control systems into integrated adhesive-dispensing platforms. For New Entrants and Emerging Players: Launch via flexible hybrid electronics partnerships targeting wearable health monitor and automotive interior applications where stretchable conductor demand outpaces incumbent capacity. Target India's electronics manufacturing clusters with mercury-free formulations pre-qualified for BIS certification. Penetrate through contract manufacturer relationships bundling formulation, equipment, and validation support. For Investors and Strategic Acquirers: Asymmetric upside sits with European mid-cap formulators possessing REACH-compliant photoinitiator platforms and established FDA device master files. Long-term viability hinges on LED curing equipment compatibility and dual-cure system integration capabilities. Watch mercury lamp phase-out enforcement timelines as the inflection signal for accelerated equipment replacement cycles and reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Synthesis | ECHA REACH authorization requirements favor suppliers with captive mercury-free chemistry control. |
| LED Curing Equipment Partnership | Solid-state UV source adoption in Shenzhen and Shanghai clusters reshapes formulation compatibility requirements. |
| Dual-Cure System Development | Automotive Tier-1 suppliers in Michigan and Bavaria validate hybrid UV-moisture platforms for interior module assembly. |
| India Electronics Cluster Expansion | PLI scheme incentives in Tamil Nadu and Karnataka create specification-grade adhesive demand for semiconductor packaging. |
| Medical Device Master File Investment | FDA expectations in Minnesota and Massachusetts raise compliance barriers favoring established registrants. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulators, LED curing equipment manufacturers, electronics contract manufacturing procurement leads, and medical device quality assurance directors with secondary validation through ECHA substance registration databases, EPA NESHAP regulatory filings, SEC 10-K disclosures from listed chemical companies, and customs trade flow records. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Historical reference periods anchored volume and value trajectories across the projection horizon, with analytical frameworks modeling formulation chemistry tiers, curing hardware compatibility classes, end-use certification requirements, and regional manufacturing cluster adoption patterns. CAGRs were derived from segment-level growth rate synthesis incorporating photoinitiator regulatory transition timelines, LED equipment penetration curves, and electronics miniaturization content-per-device trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated mercury lamp phase-out enforcement or supply disruption in German and Japanese oligomer production. Forecasts reflect documented assumptions regarding regulatory implementation schedules and equipment replacement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Global Concrete Bonding Agents Market