
 Global PET Film Coated Steel Coil Market | 2026-2036
Global PET Film Coated Steel Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Global PET Film Coated Steel Coil Market Intelligence
The EU Green Deal's industrial decarbonization targets is pivoting European appliance OEMs toward low-carbon coated steel substrates. POSCO leverages captive PET film production to control resin-to-coil cost structures across Korean appliance supply chains. JFE Steel Corporation anchors Japanese domestic demand through precision lamination lines serving refrigerator and HVAC panel fabricators. ArcelorMittal competes on European construction facade specifications with coil-coated architectural finishes that meet extended weathering warranties.
PET film coated steel coil consists of cold-rolled or galvanized steel substrate laminated with biaxially oriented polyethylene terephthalate film, typically 12-50 micrometers thick, providing corrosion resistance, surface printability, and dielectric insulation for formed metal components. Extrusion coating dominates high-volume appliance and packaging applications due to throughput speed and bond strength, while UV coating commands premium positioning in furniture and decorative building panels where scratch resistance and gloss retention justify unit cost premiums. Double side coated configurations lead volume in refrigeration liner applications, whereas printed coated variants capture margin pools from branded consumer appliance exteriors requiring multi-color graphic durability.
EMA's updated MDR framework influences medical device packaging specifications for coated steel sterilization trays, while China's GB standards and SAMR quality certification govern domestic appliance material safety and film adhesion testing protocols. Japan's METI energy efficiency labeling rules indirectly shape coated steel demand by mandating improved thermal insulation in refrigerator cabinets, which favors high-performance laminated panels over conventional painted steel. Stakeholders must monitor divergence between EU REACH chemical restrictions and China's dual carbon implementation timelines, as misaligned regulatory calendars could strand coating technology investments or create asymmetric market access conditions for solvent-dependent versus waterborne and UV-curing process lines.
Market Dynamics
REACH compliance deadlines in Europe are forcing solvent-based coating lines into accelerated obsolescence, while East Asian manufacturing clusters absorb displaced volume through extrusion and UV-curing capacity expansions.
Growth Catalysts
- Appliance panel specification upgrades:Refrigerator and washing machine OEMs in China are expanding procurement of laminated steel substrates to meet durability and surface finish requirements for premium product tiers.
- EU Green Deal industrial decarbonization:European appliance manufacturers face binding carbon intensity targets that favor low-carbon coated steel substrates over conventional painted alternatives.
- Extrusion coating throughput advantages:High-speed lamination lines serving Korean and Japanese supply chains deliver bond strength and corrosion resistance at unit economics that solvent processes cannot match.
Market Restraints
- Resin cost volatility:PET film pricing tracks purified terephthalic acid and ethylene glycol feedstock fluctuations, compressing converter margins during upstream petrochemical cycles.
- Korean supply concentration:POSCO's captive resin-to-coil integration controls a disproportionate share of Asian appliance-grade substrate supply, creating dependency risk for non-integrated buyers.
- Waterborne coating performance gaps:Current aqueous formulations fail to match solvent-based systems on adhesion to galvanized substrates in high-humidity forming operations.
Strategic Opportunities
- Indian appliance manufacturing expansion:BIS certification requirements and domestic production incentives under the PLI scheme create import substitution demand for locally laminated steel coils.
- Medical sterilization tray specifications:EMA's updated MDR framework drives coated steel demand for reusable surgical instrument packaging requiring corrosion resistance and autoclave durability.
- UV-curing furniture panel premiumization:Decorative building and furniture segments in Germany and Italy reward scratch-resistant gloss finishes with 15-20% unit price premiums over conventional coatings.
Industry Challenges
- Dual carbon timeline misalignment:China's SAMR certification and MEE enforcement calendars diverge from EU REACH phase-out schedules, stranding coating technology investments intended for cross-regional deployment.
- Precision lamination technician scarcity:Operating biaxial orientation and tension-controlled coating lines requires specialized skill sets concentrated in Japan's Chubu region and Korea's Pohang cluster.
- Film adhesion protocol fragmentation:GB standards in China, JIS specifications in Japan, and EN norms in Europe employ incompatible peel-strength testing methods, multiplying certification burdens for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PET Film Coated Steel Coil Market |
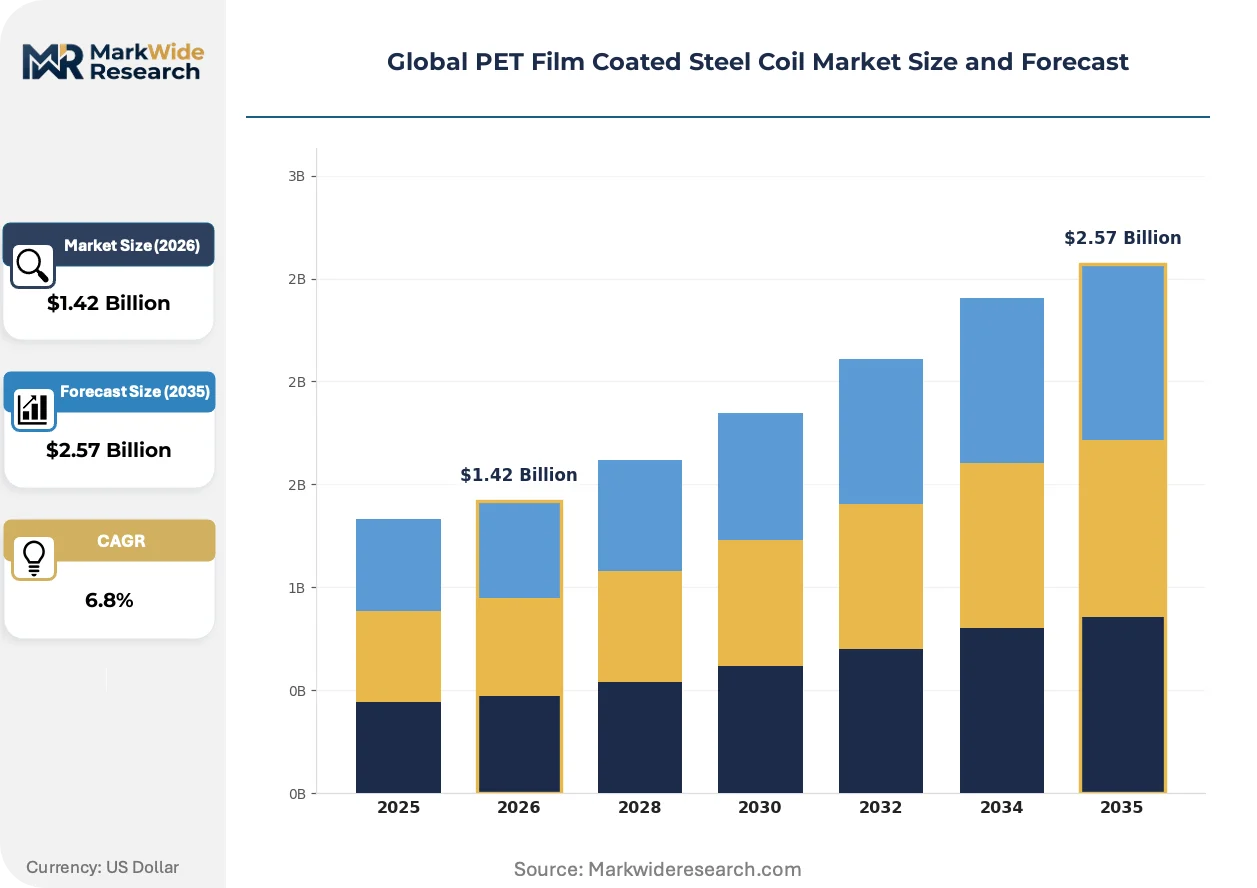
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
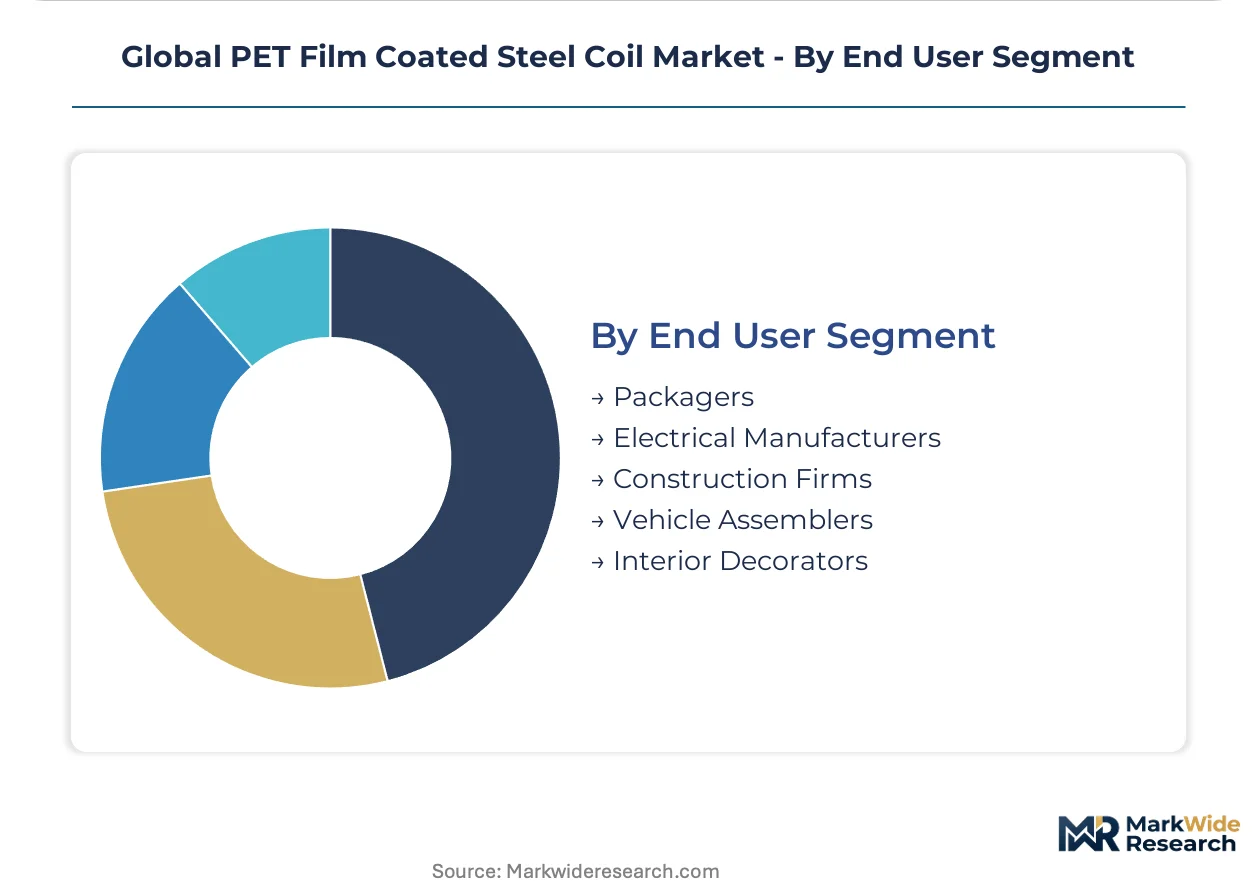
| Segmentation | Product Type: Single Side Coated, Double Side Coated, Printed Coated, Matt Finish, Glossy Finish Coating Technology: Extrusion Coating, Solvent Coating, Lamination, Hot Melt Coating, UV Coating Application: Packaging Industry, Electrical Appliances, Building Facades, Automotive Components, Furniture Manufacturing End User Segment: Packagers, Electrical Manufacturers, Construction Firms, Vehicle Assemblers, Interior Decorators |
| Companies Covered | POSCO, JFE Steel Corporation, ArcelorMittal, YIEH Corp., Uttam Galva Steels Limited, Nippon Steel Corporation, Thyssenkrupp AG, Jiangyin Everest Import and Export Co., Ltd., Acerinox S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PET Film Coated Steel Coil Market Strategic Shifts & Innovations
Coating process economics are bifurcating as environmental compliance costs restructure competitive advantage toward integrated resin-to-coil producers and away from toll-coating converters.
UV-curable acrylate formulations are consolidating position in decorative panel segments where scratch resistance and gloss retention command price premiums. Italian furniture OEMs and German facade fabricators specify these finishes for high-traffic commercial interiors. The technology is consolidating supply relationships around coating lines capable of electron-beam or LED-UV curing, excluding conventional thermal oven operators from premium specification pools.
REACH Annex XVII restrictions on volatile organic compound emissions are compressing solvent-based coating capacity across European converter networks. German and Dutch toll coaters face accelerated capital replacement cycles as ECHA enforcement tightens. Appliance OEMs in Poland and Hungary are qualifying extrusion-laminated alternatives ahead of 2025-2026 compliance deadlines, shifting procurement toward integrated steel-polymer suppliers.
Japanese refrigerator manufacturers now specify double-side coated configurations as standard for cabinet liners and doors, compressing single-side and painted-steel alternatives from mid-tier product lines. METI energy efficiency labeling rules mandate improved thermal insulation performance that laminated panels deliver through superior surface emissivity control. Procurement managers at Tokyo and Osaka headquarters are consolidating supplier bases around domestic lamination specialists with JIS-certified testing capabilities.
Global PET Film Coated Steel Coil Market Segmentation
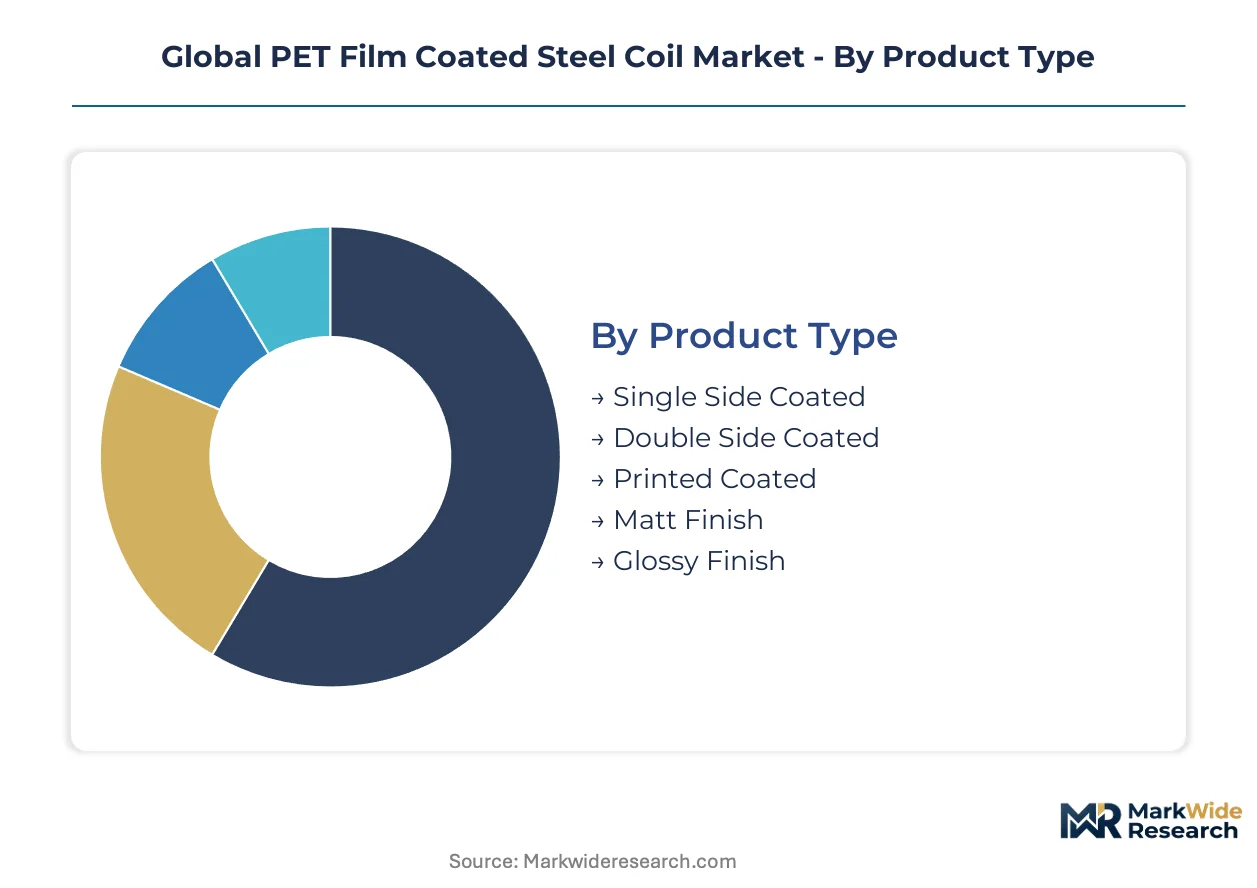
Segmentation in the PET film coated steel coil market reveals how substrate specifications, coating technologies, and end-use durability requirements create distinct procurement clusters. Appliance OEMs prioritize corrosion resistance and thermal emissivity, while construction specifiers demand weathering warranties and surface aesthetics. Understanding these segment boundaries enables suppliers to align lamination line investments with qualified demand pools.
Product Type:
Buyers differentiate by panel configuration needs, with appliance manufacturers requiring full encapsulation and furniture producers seeking surface-specific finishes.
- Double Side Coated:Full encapsulation of cold-rolled or galvanized substrate with biaxially oriented PET film on both surfaces delivers maximum corrosion protection and dielectric insulation. Japanese refrigerator manufacturers in Osaka and Nagoya specify this configuration as standard for cabinet liners to meet METI energy efficiency labeling requirements for thermal performance.
- Printed Coated:Multi-color graphic laminates enable branded appliance exteriors with durable surface printability resisting abrasion and chemical cleaning agents. Chinese OEMs in Jiangsu Province procure these variants for premium washing machine and refrigerator tiers targeting domestic consumer upgrade cycles.
- Single Side Coated:Economical partial encapsulation for applications where one surface requires protection while the other remains concealed or secondary.
- Matt Finish:Low-gloss surface treatment preferred in commercial interiors and medical environments where glare reduction matters.
- Glossy Finish:High-reflectance aesthetic specification common in consumer appliance segments and decorative architectural panels.
Double side coated leads volumes today; printed coated is gaining share fastest.
Coating Technology:
Process selection hinges on throughput economics, bond strength requirements, and regulatory compliance costs across manufacturing geographies.
- Extrusion Coating:Molten polymer direct application onto steel substrate achieves high-speed lamination with superior adhesion for appliance-grade specifications. Korean integrated producers serving domestic refrigerator supply chains leverage captive resin production to control unit economics that toll coaters cannot match.
- UV Coating:Electron-beam or LED-activated acrylate curing delivers scratch-resistant gloss finishes commanding price premiums in furniture and decorative building segments. Italian and German fabricators specify these systems for high-traffic commercial interiors where durability justifies unit cost differentials.
- Solvent Coating:Conventional thermal-cure systems facing accelerated obsolescence under EU REACH Annex XVII VOC emission restrictions.
- Lamination:Pre-formed film bonding process serving specialty applications requiring precise thickness control.
- Hot Melt Coating:Thermoplastic adhesive systems for intermediate performance tiers balancing cost and bond strength.
Extrusion coating dominates appliance volume; UV coating expands most quickly in premium decorative segments.
Application:
End-use performance specifications range from autoclave durability in medical packaging to extended weathering warranties in architectural facades.
- Electrical Appliances:Refrigerator panels, washing machine exteriors, and HVAC casings demand corrosion resistance, formability, and surface emissivity control. Chinese appliance manufacturers are expanding procurement of laminated substrates to meet durability requirements for premium product tiers.
- Building Facades:Architectural exterior specifications require coil-coated finishes meeting extended weathering warranties and color retention standards. ArcelorMittal competes in this segment with European construction specifications.
- Packaging Industry:Sterilization trays and medical device packaging under EMA MDR framework requirements.
- Automotive Components:Interior trim and functional panels requiring precise thickness tolerance and forming characteristics.
- Furniture Manufacturing:Decorative panels where scratch resistance and aesthetic finish command specification premiums.
Electrical appliances anchor current demand; building facades show steepest expansion trajectory as EU Green Deal decarbonization targets pivot OEMs toward low-carbon coated substrates.
End User Segment:
Procurement sophistication varies from integrated steel-polymer supply chains to fragmented toll-coating networks.
- Electrical Manufacturers:Appliance OEMs with direct relationships to integrated coil coaters specifying JIS-certified or GB-standard adhesion protocols. These buyers consolidate supplier bases around domestic lamination specialists capable of precision tension control.
- Construction Firms:Project-based procurement of architectural finishes with extended warranty requirements and color matching specifications.
- Packagers:Medical device and sterilization tray producers navigating EMA MDR compliance for reusable surgical instrument packaging.
- Vehicle Assemblers:Automotive Tier 1 suppliers with exacting thickness tolerance and forming operation requirements.
- Interior Decorators:Furniture and commercial interior specifiers prioritizing surface aesthetics and scratch resistance over unit cost.
Electrical manufacturers represent the largest procurement volume; packagers are climbing the fastest as medical device sterilization tray specifications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision lamination technicians cluster in Japan's Chubu region and Korea's Pohang steel complex, anchoring Asia-Pacific supply chains for appliance-grade coated substrates. Their concentration shapes where extrusion coating capacity expands and which regulatory calendars determine technology investment cycles.
China
Appliance OEMs in Jiangsu Province expand procurement of laminated steel for refrigerator panels and washing machine exteriors. SAMR quality certification and GB standards govern film adhesion testing protocols for domestic material safety compliance. Manufacturing gravity concentrates in Suzhou and Wuxi, where integrated steel-polymer supply chains serve Tier 1 appliance suppliers.
Japan
Refrigerator manufacturers specify double-side coated configurations to meet METI energy efficiency labeling requirements for thermal insulation performance. JIS specifications employ peel-strength testing methods that diverge from European EN norms, multiplying certification burdens. The Chubu region around Nagoya anchors domestic lamination capacity serving Osaka and Tokyo headquarters procurement.
South Korea
POSCO leverages captive PET film production to control resin-to-coil cost structures across domestic appliance supply chains. Korean integrated producers achieve throughput economics that toll coaters cannot match through high-speed extrusion lamination. Manufacturing concentrates in Pohang and Gwangyang, where backward integration into purified terephthalic acid feedstocks secures margin control.
Germany
EU REACH Annex XVII restrictions on volatile organic compound emissions compress solvent-based coating capacity across converter networks. ECHA enforcement tightens ahead of 2025-2026 compliance deadlines, shifting procurement toward extrusion-laminated alternatives. Appliance OEMs in Poland and Hungary qualify these substrates, with German toll coaters facing accelerated capital replacement cycles.
India
BIS certification requirements and domestic production incentives under the PLI scheme create import substitution demand for locally laminated steel coils. Appliance manufacturing expansion in Maharashtra and Gujarat drives substrate qualification programs. Converter networks in Pune and Ahmedabad build extrusion capacity to serve refrigerator and washing machine OEMs targeting domestic consumer upgrade cycles.
Global PET Film Coated Steel Coil Market Key Industry Players
Capital-heavy integrated steel producers compete with asset-light toll-coating converters for specification access to appliance OEMs. The market structure bifurcates around captive resin-to-coil operations versus dependent substrate buyers exposed to PET film pricing volatility. Three archetypes dominate: integrated steel-polymer producers controlling upstream feedstocks, precision lamination specialists with certified testing capabilities, and regional toll coaters serving construction facade specifications. Competitive moves center on capacity expansion in extrusion coating and strategic partnerships to secure resin supply.
Within the integrated producer tier, POSCO exemplifies backward integration into captive PET film manufacturing. JFE Steel Corporation occupies a position among Japanese precision lamination specialists serving domestic appliance supply chains. ArcelorMittal sits within the European construction-facing archetype, competing on architectural facade specifications with coil-coated finishes.
| Leading Market Players |
|---|
| POSCO |
| JFE Steel Corporation |
| ArcelorMittal |
| YIEH Corp. |
| Uttam Galva Steels Limited |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| Jiangyin Everest Import and Export Co., Ltd. |
| Acerinox S.A |
| Others |
Cost & Logistics Intelligence
EU REACH Annex XVII VOC emission mandates gate qualified supply access and premium-tier pricing power, as converters lacking extrusion or UV-curing capabilities forfeit specification access to appliance OEMs in Germany and Poland while integrated resin-to-coil producers capture margin premiums through certified low-emission substrates.
Pricing Analysis
Bundled resin-supply contracts versus unbundled toll-coating services split pricing structures across the market. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and volume scale commitments, with UV-cured decorative finishes commanding 15-20% unit premiums over extrusion-laminated appliance grades. Cost compression in solvent-dependent converter tiers is intensifying because REACH compliance deadlines accelerate capital replacement cycles. Appliance OEMs in China show highest price sensitivity, while Italian furniture fabricators prioritize scratch-resistant gloss retention over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Korean purified terephthalic acid feedstock and Japanese precision lamination technician pools. Manufacturing gravity centers on South Korea, Japan, and China, with downstream distribution running through integrated steel-polymer supply chains serving domestic appliance Tier 1 suppliers. Raw material dependencies encompass PET resin, cold-rolled steel substrate, and UV-curable acrylate formulations. Tariff exposure on steel imports into India strains converter margins. Toll-coating networks in Europe face structural displacement as ECHA enforcement tightens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU REACH compliance costs in Germany and the Netherlands exceed China's SAMR certification burdens by a factor that rewards extrusion capacity relocation to East Asian manufacturing clusters.
For Market Incumbents: Acquire captive PET film production assets to defend against resin cost volatility and POSCO's integrated cost structures. Expand extrusion lamination capacity in Jiangsu Province to serve Chinese appliance OEM procurement expansion. Invest in JIS-certified testing capabilities to maintain specification access to Japanese refrigerator manufacturers consolidating supplier bases. For New Entrants and Emerging Players: Direct-to-appliance-OEM digital procurement platforms offer white-space entry around qualified substrate sourcing. Target Indian Maharashtra and Gujarat manufacturing expansion under PLI scheme incentives. Qualify BIS-certified extrusion capacity ahead of domestic appliance production ramp. Pursue medical sterilization tray specifications under EMA MDR framework as fastest-climbing demand segment. For Investors and Strategic Acquirers: Roll-up economics work for regional toll-coating converters because ECHA enforcement compresses solvent-based capacity valuations and creates distressed acquisition targets. Long-term viability over the next decade hinges on technology transition completion to UV-curing and extrusion systems. Monitor divergence between EU REACH and China's dual carbon implementation timelines as inflection indicator for stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | POSCO's captive feedstock control demonstrates margin protection against purified terephthalic acid volatility. |
| UV-Curing Line Conversion | Italian furniture OEM specifications reward scratch-resistant gloss finishes with durable supply relationships. |
| JIS Certification Investment | Tokyo and Osaka procurement managers consolidate supplier bases around certified domestic lamination specialists. |
| India PLI-Aligned Capacity Buildout | Maharashtra and Gujarat appliance manufacturing expansion creates import substitution demand for locally qualified substrates. |
| Medical Device Packaging Qualification | EMA MDR framework drives coated steel demand for autoclave-durable sterilization tray specifications. |
Research Approach
Coverage spans East Asia, Europe, and South Asia, with primary inputs from each region combining interviews with appliance procurement managers, steel mill technical directors, coating line operators, and regulatory compliance officers alongside secondary validation through customs trade data, SEC filings from integrated producers, JIS and GB standard documentation, and ECHA regulatory enforcement records. Bottom-up demand modeling from end-use procurement patterns triangulates against top-down supply capacity assessments.
Granularity-level modeling disaggregates volume and value outputs by product configuration, coating technology type, end-use application, and regional regulatory cluster across the analysis window. CAGRs derive from segment-specific growth trajectories weighted by procurement concentration in Japanese refrigerator manufacturing, Chinese appliance export demand, and EU Green Deal construction specification shifts. Feedstock cost cycles, REACH compliance calendar enforcement, and METI energy efficiency labeling revisions inform projection sensitivity.
The model assumes a particular technology adoption path; alternative pathways for solvent-to-UV coating transition would alter the outlook. Forecasts reflect assumptions around SAMR certification alignment with EU REACH timelines, resin cost volatility persistence, and technician training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Cladding Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Gelcoat Market
Coatings
Powder Coating Booth Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Antifouling Coatings Market
Coatings
France Protective Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Global Coil Coatings Market