
 Corrosion Protection Coating Market | 2026-2036
Corrosion Protection Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Protection Coating Market Intelligence
Market Context
Specialty chemical producers in Germany and Japan is realigning capacity toward high-solids and solvent-free systems to serve stringent environmental standards. PPG Industries, Inc. leverages its marine coatings heritage to dominate offshore platform maintenance cycles across the North Sea and Gulf of Mexico. Akzo Nobel N.V. sustains leadership in protective coatings for wind energy towers through intensive R&D on direct-to-metal epoxy primers. Hempel A/S anchors its position in the tanker and container ship segments with fouling-release technologies that extend dry-dock intervals.
Technical Definition and Structural Segments
Corrosion protection coatings comprise barrier-forming polymer matrices—typically epoxies, polyurethanes, or zinc-rich formulations—engineered with pigment loadings between 60-85% volume solids to inhibit electrochemical degradation of steel and aluminum substrates in atmospheric, immersion, or underground environments. These systems serve primarily to extend asset life in capital-intensive infrastructure where unplanned downtime exceeds recoating costs by orders of magnitude. Epoxy formulations occupy the largest value share due to their adhesion strength and chemical resistance in oil and gas processing equipment, while water-based technology is displacing solvent-borne alternatives in civil infrastructure applications where VOC emissions face tightening municipal limits. Pipeline application represents a concentrated margin pool driven by fusion-bonded epoxy and three-layer polyethylene specifications for buried transmission lines.
Regulatory Frame and Outlook
REACH in Europe, EPA NESHAP in the United States, and China's MEE emission standards collectively restrict solvent content and hazardous air pollutants in protective coating formulations, forcing manufacturers to reformulate or forfeit market access. The EU Green Deal and associated CSRD reporting obligations further compel asset owners to document coating lifecycle impacts and prioritize lower-carbon maintenance strategies. Stakeholders must monitor divergence between regional chemical hazard classifications, as misalignment between ECHA SVHC listings and EPA risk evaluations threatens to fragment product portfolios and complicate multinational specification compliance.
Market Dynamics
REACH restrictions on hexavalent chromium and volatile organic compounds are compelling wholesale reformulation toward water-based and zinc-rich alternatives, compressing solvent-borne margins while rewarding early movers in compliant chemistries.
Growth Catalysts
- Offshore wind buildout:Turbine foundation installations across the North Sea and Gulf of Mexico consume specialized marine-grade epoxies in volumes that scale with gigawatt commissioning targets.
- China's petrochemical infrastructure wave:State-backed refinery and LNG terminal expansions concentrate coating demand in coastal provinces with aggressive capacity addition schedules.
- ECHA SVHC listing momentum:Accelerated substance-of-very-high-concern designations force asset owners into preemptive recoating cycles before banned chemistries face withdrawal.
Market Restraints
- Zinc price volatility:Fluctuations in zinc ingot costs on the London Metal Exchange directly squeeze margins for sacrificial anode coatings.
- Epoxy resin supply concentration:Bisphenol-A and epichlorohydrin production clusters in Northeast Asia create single-source dependency risks for Western formulators.
- Cure-time limitations:Ambient-temperature curing constraints extend application windows and compress contractor utilization rates in seasonal climates.
Strategic Opportunities
- Floating offshore wind:Mooring chain and dynamic cable protection systems in pre-commercial arrays open specialized coating specifications without incumbent lock-in.
- EU Green Deal procurement mandates:Public infrastructure tenders with embedded lifecycle carbon scoring favor low-VOC and bio-based formulations.
- Drone-assisted inspection:Automated film-thickness measurement and defect mapping enable predictive maintenance contracts that bundle coating services.
Industry Challenges
- Applicator certification bottlenecks:SSPC and NACE qualification backlogs constrain contractor capacity during seasonal demand spikes.
- Legacy coating incompatibility:Direct-to-metal epoxy systems require complete removal of existing alkyd or chlorinated rubber layers, doubling surface preparation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Protection Coating Market |
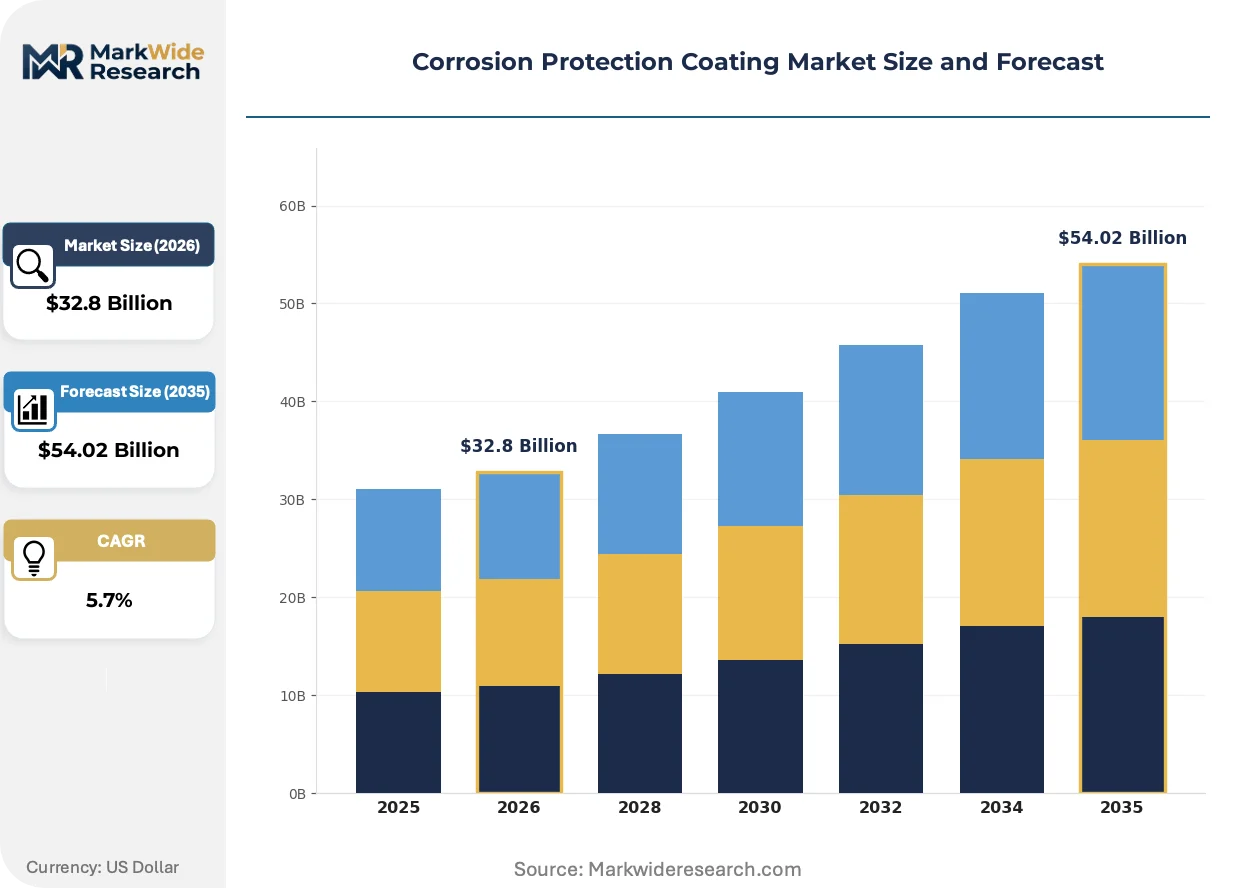
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Zinc, Acrylic End User: Marine, Automotive, Oil & Gas, Construction Application: Civil Infrastructure, Equipment Manufacturing, Coating Services, Pipeline Technology: Solvent-Based, Water-Based, Powder Coating, High-Performance |
| Companies Covered | Jotun Group, Axalta Coating Systems, Akzo Nobel N.V., RPM International Inc., BASF SE, PPG Industries, Inc., Hempel A/S, Kansai Paint Co., Ltd., Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Protection Coating Market Strategic Shifts & Innovations
Formulation science and application methodology are converging to address the tension between performance specifications and tightening chemical hazard limits. The transition favors systems that reduce steps, emissions, and asset downtime simultaneously.
Graphene-enhanced barrier coatings are integrating into high-performance marine specifications. Shipyards in South Korea and Japan are piloting these formulations on ballast tank interiors to extend coating lifecycles beyond standard epoxy limits. The technology is integrating direct-to-metal adhesion properties that eliminate intermediate primer coats, compressing application schedules and reducing volatile organic compound release during construction.
EPA NESHAP Subpart HHHHHH enforcement is tightening permissible hazardous air pollutant thresholds for protective coating operations. Refinery maintenance contractors in Texas and Louisiana face stepped-up inspection protocols that favor high-solids and solvent-free alternatives. The rulemaking is accelerating specification revisions among downstream oil and gas operators seeking to avoid penalty exposure and scheduled maintenance delays.
Asset owners are unbundling coating procurement from integrated construction contracts. Large infrastructure developers in Germany and the Netherlands now separately tender surface preparation and coating application, enabling direct relationships with specialized applicators. This pattern is most pronounced in bridge rehabilitation programs where public-private partnership structures separate maintenance obligations from initial construction warranties.
Corrosion Protection Coating Market Segmentation
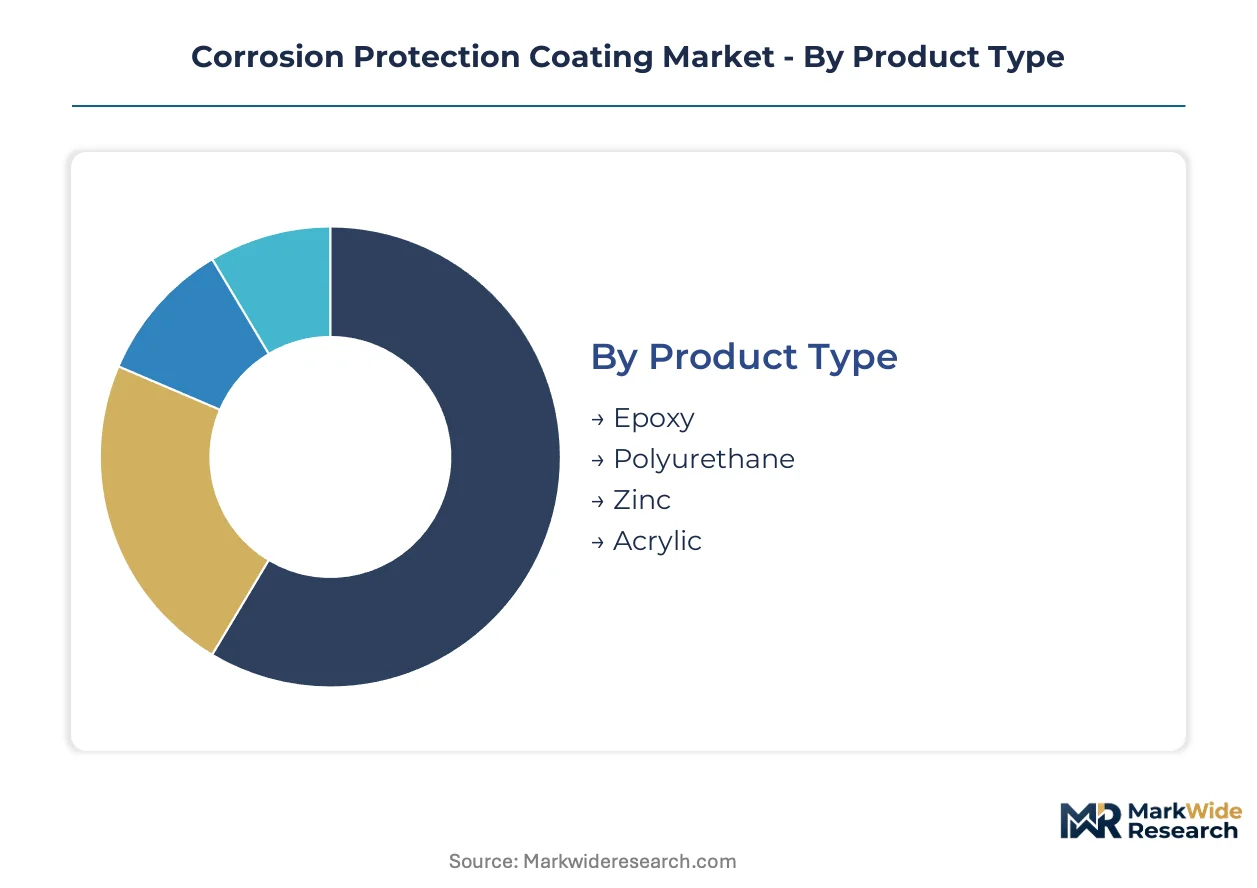
Corrosion protection coatings serve heterogeneous asset classes with divergent performance specifications and regulatory exposure. Segmentation reveals where formulation complexity concentrates and which end-uses command premium pricing tiers.
Product Type:
Capital intensity varies sharply across chemistries, with zinc-rich systems requiring metal feedstock hedging and epoxy demanding specialized resin synthesis infrastructure.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and amine hardeners deliver superior adhesion to blast-cleaned steel and chemical resistance in immersion service. Demand clusters in oil and gas processing equipment across the US Gulf Coast and China's refining corridors, driven by maintenance cycles on aging fractionation columns and storage tanks. REACH SVHC scrutiny on bisphenol-A derivatives is accelerating reformulation timelines.
- Polyurethane:Aliphatic and aromatic isocyanate-cured topcoats provide UV stability and gloss retention for atmospheric exposure. Wind turbine nacelles and tower exteriors in Germany and Denmark specify these systems for 25-year design lives, with direct-to-metal variants compressing application schedules.
- Zinc:Inorganic and organic zinc-rich primers function as sacrificial anodes, with loadings exceeding 85% metallic zinc by weight in dry film. London Metal Exchange price swings directly pressure coating margins.
- Acrylic:Thermoplastic emulsions and solvent-borne resins serve decorative-protective dual roles in architectural metalwork and OEM components. Water-based acrylics are displacing solvent grades in municipal infrastructure tenders.
Most installed capacity flows through epoxy formulations. Expansion is steepest in polyurethane direct-to-metal systems.
End User:
Customer concentration determines contract structure, with marine and oil and gas operators bundling multi-year maintenance agreements.
- Marine:Ballast tanks, cargo holds, and topside structures on tankers and container ships require IMO PSPC-compliant coatings with extended dry-dock intervals. South Korean shipyards are piloting graphene-enhanced epoxies to exceed standard lifecycle limits.
- Oil & Gas:Offshore platforms, refineries, and pipelines specify high-temperature-resistant phenolic and novolac epoxies for process equipment. EPA NESHAP enforcement in Texas and Louisiana is forcing specification shifts toward high-solids alternatives.
- Automotive:Underbody chassis coatings and battery tray protection for electric vehicles demand thin-film corrosion resistance with stone-chip durability. OEM qualification cycles span 18-24 months.
- Construction:Bridge steel, stadium structures, and pre-engineered metal buildings utilize zinc-epoxy-urethane systems with aesthetic finish requirements. German and Dutch public tenders now embed lifecycle carbon scoring.
Procurement volumes concentrate in marine and oil and gas maintenance cycles. Construction applications are gaining share fastest under Green Deal procurement mandates.
Application:
Application setting dictates surface preparation standards and contractor certification requirements.
- Pipeline:Fusion-bonded epoxy and three-layer polyethylene systems for buried transmission lines represent a concentrated margin pool with specification lock-in to FBE applicators.
- Civil Infrastructure:Bridge rehabilitation and water treatment facilities face municipal VOC limits favoring water-based and high-solids technologies. SSPC certification bottlenecks constrain contractor capacity.
- Equipment Manufacturing:OEM coating lines for industrial machinery and wind towers require consistent film thickness and rapid cure for throughput.
- Coating Services:Third-party applicators unbundled from construction contracts now tender directly to asset owners in German and Dutch infrastructure markets.
Pipeline specifications retain the most rigid certification barriers. Civil infrastructure is expanding most quickly under accelerated bridge replacement programs.
Technology:
Technology choice determines regulatory compliance trajectory and capital equipment requirements.
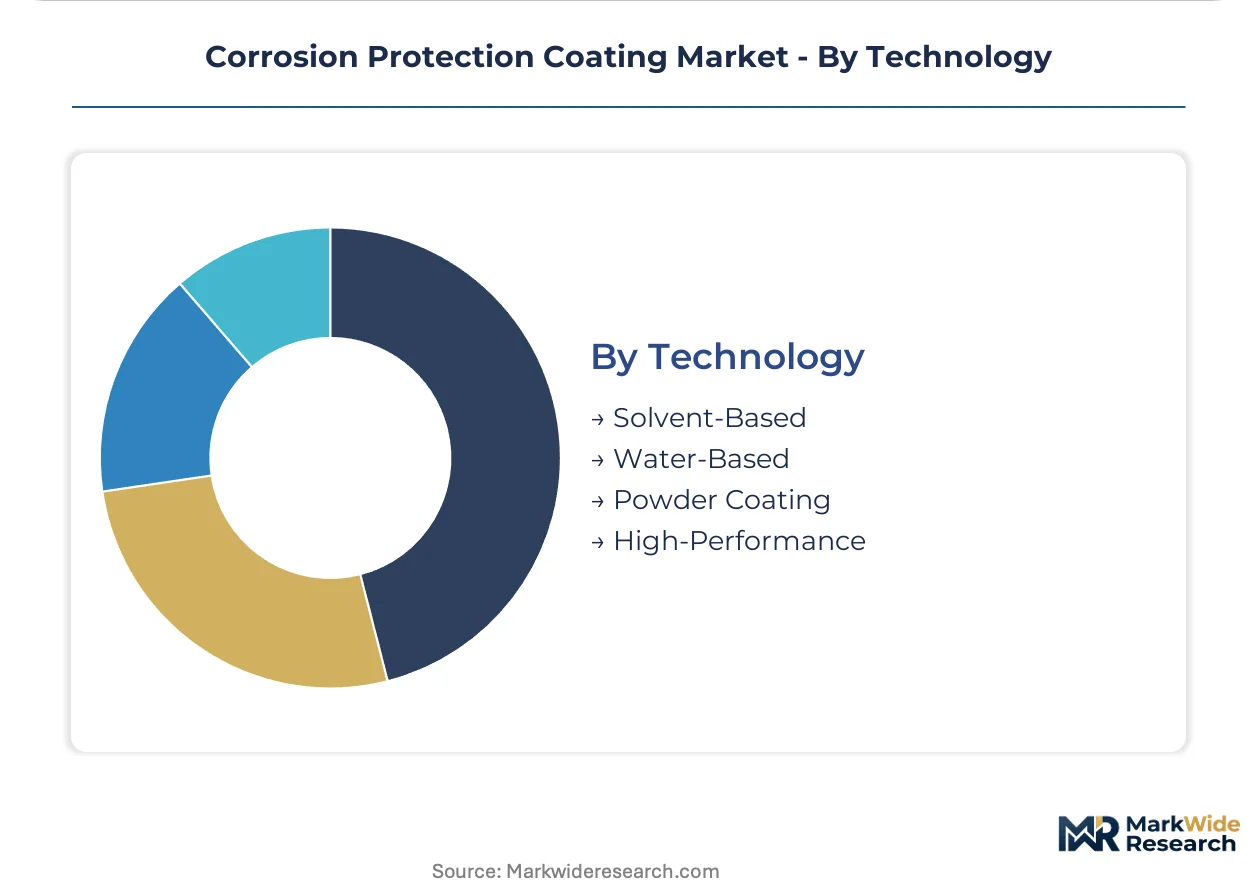
- Solvent-Based:Traditional alkyds, epoxies, and urethanes deliver familiar handling properties but face tightening VOC limits under EPA NESHAP and China's MEE standards.
- Water-Based:Acrylic and epoxy emulsions with reduced HAP emissions are capturing civil infrastructure share where municipal limits apply. Film build and cure-time limitations persist in humid climates.
- Powder Coating:Thermoset epoxy and polyester powders eliminate liquid carrier emissions entirely, serving OEM components and rebar with electrostatic application efficiency.
- High-Performance:Solvent-free and 100% solids systems command premium positioning for confined-space tank linings and offshore splash zones where emission control is impractical.
Installed base remains weighted toward solvent-borne systems. Water-based formulations are climbing the fastest under REACH and EPA enforcement convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as formulators migrate capacity toward jurisdictions with phased environmental deadlines. Cost-of-compliance gaps between REACH enforcement in Europe and China's MEE implementation timeline are accelerating facility relocation decisions.
United States
Offshore wind construction in the Gulf of Mexico and Atlantic seaboard is driving marine-grade epoxy consumption for turbine foundations. EPA NESHAP Subpart HHHHHH enforcement is tightening hazardous air pollutant thresholds for refinery maintenance contractors in Texas and Louisiana. Houston-Galveston Bay anchors the largest concentration of protective coating applicators serving petrochemical infrastructure.
Germany
Bridge rehabilitation programs and wind tower manufacturing sustain demand for polyurethane direct-to-metal systems. EU Green Deal procurement mandates now embed lifecycle carbon scoring in public infrastructure tenders. The Ruhr industrial corridor concentrates specialty chemical producers realigning toward high-solids and solvent-free formulations.
China
State-backed petrochemical infrastructure expansion in coastal provinces is concentrating coating demand for refinery and LNG terminal construction. MEE emission standards are tightening solvent content limits with phased implementation timelines. Yangtze River Delta shipyards are piloting graphene-enhanced barrier coatings for extended lifecycle performance.
South Korea
Tanker and container ship newbuild programs at Ulsan and Geoje shipyards consume IMO PSPC-compliant coating systems. KOSHA occupational safety regulations are accelerating specification shifts toward low-VOC alternatives during construction cycles. Busan-Ulsan industrial cluster represents the densest concentration of marine coating application capacity in Northeast Asia.
Netherlands
North Sea offshore platform maintenance and port infrastructure rehabilitation sustain protective coating demand across multiple chemistries. CSRD reporting obligations compel asset owners to document coating lifecycle impacts in maintenance strategies. Rotterdam-Antwerp port complex anchors European distribution for zinc-rich and epoxy resin feedstocks.
Corrosion Protection Coating Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue graphene-enhanced and bio-based formulations to bypass incumbent lock-in. The market structures around three concentration nodes: diversified chemical conglomerates with captive resin synthesis, specialized coating formulators with marine heritage, and regional applicator networks with SSPC certification assets. Competitive positioning depends on regulatory compliance speed and specification relationships with asset owners. Consolidation pressure is intensifying through strategic partnerships between formulators and inspection technology providers.
Among diversified chemical conglomerates, BASF SE and RPM International Inc. exemplify scale-driven archetypes with backward integration into epoxy resin and additive production. Specialized marine formulators occupy a distinct tier, with Hempel A/S and Jotun Group representing heritage-rich positions in shipyard and offshore platform specifications. PPG Industries, Inc. anchors a hybrid position spanning industrial OEM and maintenance coating services. These three archetypes—integrated chemical producers, marine specialists, and diversified industrials—collectively shape specification standards and procurement channel structures.
| Leading Market Players |
|---|
| Jotun Group |
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| RPM International Inc. |
| BASF SE |
| PPG Industries, Inc. |
| Hempel A/S |
| Kansai Paint Co., Ltd. |
| Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
EU Green Deal procurement mandates with embedded lifecycle carbon scoring gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant formulators while rewarding early movers in low-VOC and bio-based systems with specification lock-in on public infrastructure tenders.
Pricing Analysis
Distributor margins on zinc-rich primers and marine-grade epoxies compress under London Metal Exchange zinc price volatility and REACH-compliant reformulation costs. Three-tier pricing structure across premium certified, standard industrial, and economy solvent-borne levels separates SSPC-certified applicator networks from uncertified contractors. Price erosion runs through solvent-borne tiers as EPA NESHAP enforcement intensifies in Texas and Louisiana. Construction end-users exhibit highest price sensitivity due to municipal budget constraints, while offshore wind developers prioritize performance over unit cost.
Supply Chain Analysis
Bisphenol-A and epichlorohydrin feedstock supply rests on production clusters in China, South Korea, and Taiwan, creating single-source dependency risks for Western epoxy formulators. Zinc ingot sourcing draws from Australian and Peruvian mining operations through London Metal Exchange contracts. Tariff exposure on Chinese resin imports threatens margin stability for North American and European blenders. Distribution runs through Rotterdam-Antwerp and Houston-Galveston Bay hub-and-spoke networks serving regional applicator bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Offshore wind foundation specifications favoring 25-year design lives and direct-to-metal systems drive demand-shift toward premium marine-grade epoxies and polyurethane topcoats.
For Market Incumbents: Anchor specification relationships with North Sea and Gulf of Mexico offshore wind developers through captive R&D on graphene-enhanced barrier systems. Deepen backward integration into epoxy resin synthesis to offset Northeast Asian feedstock concentration. Defend against emerging bio-based formulators by accelerating SSPC certification pipelines for preferred applicator networks. For New Entrants and Emerging Players: Floating offshore wind mooring chain protection offers white-space entry without incumbent specification lock-in. Target drone-assisted inspection bundling with predictive maintenance contracts for German and Dutch bridge rehabilitation programs. Pursue direct tender relationships with unbundled coating procurement in public-private partnership structures. For Investors and Strategic Acquirers: Valuations sit cheapest among regional applicator networks with SSPC certification assets and established relationships with municipal infrastructure authorities. Five-to-ten year viability hinges on regulatory compliance speed rather than scale alone. Monitor ECHA SVHC listing momentum as inflection indicator for preemptive recoating cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Synthesis | Captive bisphenol-A supply insulates margins from Northeast Asian price shocks and tariff exposure. |
| Graphene-Enhanced Formulation Launch | South Korean shipyard pilots validate extended lifecycle claims for premium marine specifications. |
| SSPC Certification Network Expansion | Qualified applicator scarcity in seasonal climates creates channel control leverage during demand spikes. |
| Drone-Assisted Inspection Partnership | Predictive maintenance bundling captures recurring revenue streams from German infrastructure asset owners. |
| EU Green Deal Procurement Alignment | Lifecycle carbon scoring compliance unlocks premium-tier access to Dutch and German public tenders. |
Research Approach
Multiple input streams — technical specification reviews with coating formulators, procurement pattern analysis with infrastructure asset owners, and regulatory tracking across ECHA and EPA dockets — were reconciled against customs trade data and SEC filings from specialty chemical producers. Primary interviews captured perspectives from plant managers at Ulsan and Geoje shipyards, procurement leads at North Sea offshore wind developers, distribution channel partners in Rotterdam-Antwerp, and technical R&D directors at marine coating specialists. Secondary validation drew from IMO PSPC compliance databases, REACH SVHC listings, and Lloyd's Register classification society records. Bottom-up volume estimates triangulated against top-down spending analysis across oil and gas, marine, and construction end-use segments.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct projection frameworks across the analysis window. Segmentation modeling captured chemistry type, end-use industry, application setting, and technology format dimensions. CAGRs were derived from fitted growth curves incorporating named demand drivers including offshore wind gigawatt commissioning targets and petrochemical infrastructure expansion schedules in China's coastal provinces. Zinc price volatility assumptions and REACH implementation timelines fed sensitivity scenarios.
Underlying measurement precision varies by segment; pipeline and marine applications carry tighter precision than dispersed civil infrastructure projects due to concentrated specification documentation. Forecasts incorporate assumptions regarding regulatory enforcement intensity and raw material cost trajectories. ECHA SVHC designation acceleration, zinc ingot supply disruptions, and applicator certification bottlenecks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Floor Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Global Hydrophobic Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Coating Auxiliaries Market
Coatings
Acrylic Coating Market
Coatings
Technical Coil Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Coating Binders Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market