
 Acrylic Coating Market | 2026-2036
Acrylic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Coating Market Analysis
Automotive refinishing demand is shifting toward higher-performance acrylic formulations as electric vehicle manufacturing scales across Asia and North America. PPG Industries Inc. leverages its global color-matching infrastructure to dominate OEM supply chains. The Sherwin-Williams Co. sustains retail and professional contractor channels through dense distribution networks. Axalta Coating Systems LLC specializes in mobility-focused coating technologies, anchoring its position in vehicle refinishing and commercial transport.
Acrylic coating denotes a thermoplastic or thermosetting film-forming system based on polymethyl methacrylate or polyacrylate resins, typically applied at dry-film thicknesses of 25–100 microns to provide UV resistance, gloss retention, and substrate protection. Its primary purpose spans decorative architectural finishes, corrosion barriers on metal structures, and weatherable topcoats for transportation equipment. Water-based emulsion systems lead volume in architectural applications where VOC compliance pressures are most acute, while solvent-based formulations retain margin concentration in automotive and aerospace segments requiring superior chemical resistance. Urethane-modified acrylics represent the fastest-growing formulation category as end users seek hybrid performance bridging hardness and flexibility.
EPA VOC regulations and REACH restrictions on hazardous substance content are forcing reformulation investments across the supply chain, elevating compliance costs for smaller producers. FDA indirect food-contact standards and OSHA workplace exposure limits further constrain permissible chemistries in industrial coating operations. Stakeholders must monitor evolving state-level adoption of California Air Resources Board protocols, as these rules frequently prefigure broader North American regulatory alignment on emission thresholds and product registration requirements.
Market Dynamics
Water-based acrylic emulsion systems are consolidating share across architectural applications as EPA VOC rules and REACH substance restrictions force solvent-based formulation obsolescence, compressing margins for legacy producers unable to fund reformulation.
Growth Catalysts
- Electric vehicle manufacturing scale-up:Automotive OEMs in China and India are specifying high-performance acrylic topcoats for battery enclosure protection and lightweight body panels, pulling advanced resin demand from refinishing into primary manufacturing.
- REACH substance restrictions:ECHA's evolving candidate list of SVHCs is accelerating substitution of isocyanate-containing systems with urethane-modified acrylic hybrids across European industrial maintenance coatings.
- Industrial construction clustering:Manufacturing zone development in Gujarat, Maharashtra, and Guangdong is concentrating demand for corrosion-resistant acrylic barriers on steel infrastructure and processing equipment.
Market Restraints
- Petrochemical feedstock volatility:Methyl methacrylate and acrylic acid prices track propylene naphtha spreads, compressing formulation margins when olefin supply tightens.
- Specialty additive supply concentration:Photoinitiators and hindered amine light stabilizers for UV-curable acrylics source predominantly from Chinese and German chemical producers, creating single-geography exposure.
- Performance ceiling in chemical resistance:Unmodified acrylic films exhibit inferior solvent and fuel resistance versus epoxy-amine and polyurethane systems, limiting penetration in heavy-duty tank lining and chemical processing equipment.
Strategic Opportunities
- Indian architectural coatings penetration:Urban housing stock per capita remains below Southeast Asian benchmarks, positioning decorative emulsion demand for sustained expansion as BIS quality standards elevate product substitution rates.
- UV-LED curing convergence:Mercury lamp phase-out under Minamata Convention obligations is opening specification windows for LED-optimized photoinitiator packages in industrial wood and plastic coating lines.
- Direct-to-contractor digital channels:Professional painter networks in North America are migrating toward platform-based material procurement, bypassing traditional distributor markups on standard architectural grades.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid polymer architecture bridging waterborne delivery with solvent-grade performance concentrates among retiring technical specialists at established resin producers.
- Multi-jurisdiction registration burden:Separate EPA TSCA premanufacture notifications, REACH dossier updates, and state-level California Air Resources Board approvals extend new product commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Coating Market |
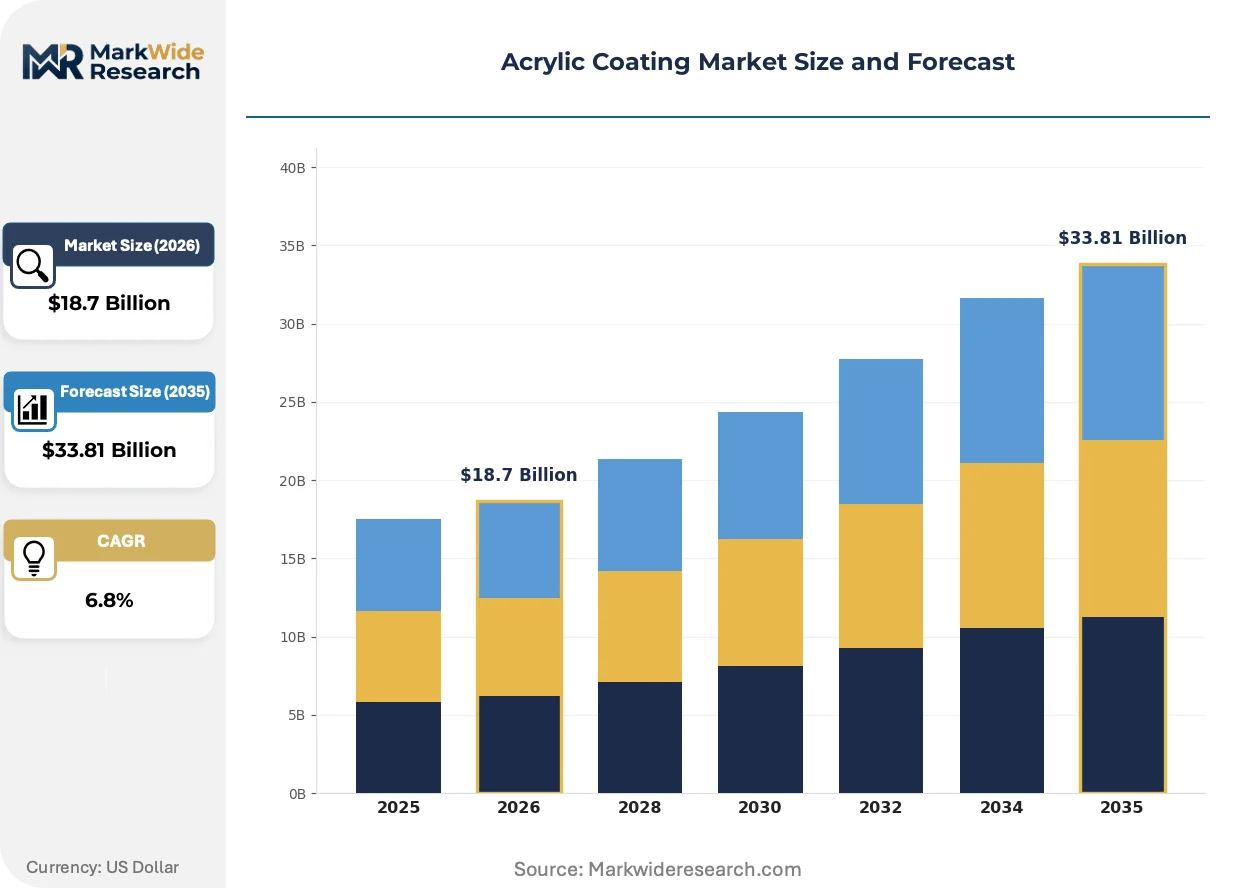
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solvent-based, Water-based, Specialty Application: Automotive, Architectural, Industrial, Aerospace End User: Manufacturers, Contractors, Distributors, Consumers Formulation: Polymer-blend, Urethane-modified, Alkyd, Hybrid |
| Companies Covered | PPG Industries Inc., The Sherwin-Williams Co., Axalta Coating Systems LLC, Akzo Nobel N.V., BASF SE, Dow, Asian Paints, Jotun, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Coating Market Emerging Trajectories
Acrylic coating innovation is pivoting toward hybrid performance architectures that reconcile regulatory compliance with durability specifications previously reserved for solvent-borne systems, compressing traditional technology category boundaries.
Self-crosslinking acrylic emulsion technology is consolidating position in premium architectural finishes by enabling ambient-cure hardness previously requiring thermosetting chemistries. Residential repaint contractors in coastal US markets are specifying these systems for exterior trim and siding applications where gloss retention and chalk resistance justify material cost premiums. The technology is consolidating mid-tier waterborne suppliers into specialty-focused niches as scale advantages concentrate among integrated resin-coating producers.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon propellants in aerosol coatings, forcing reformulation of DIY touch-up and maintenance products toward compressed gas or pump-spray delivery. Industrial maintenance coating manufacturers serving European offshore wind and bridge infrastructure are absorbing compliance costs through premium pricing on reduced-VOC repair systems. Marine and protective segments in Germany, Netherlands, and Denmark are most affected, with specification engineers now requiring third-party environmental product declarations alongside performance data.
Specification authority is migrating from general contractors to certified coating inspectors armed with digital thickness verification and adhesion testing protocols. Large-scale infrastructure owners in Texas, California, and Florida are unbundling material supply from application contracts, forcing coating producers to qualify directly with asset managers rather than subcontractor networks. This disintermediation is most pronounced in transportation department bridge rehabilitation programs where warranty terms now extend to 10-15 year performance guarantees.
Acrylic Coating Market Segmentation
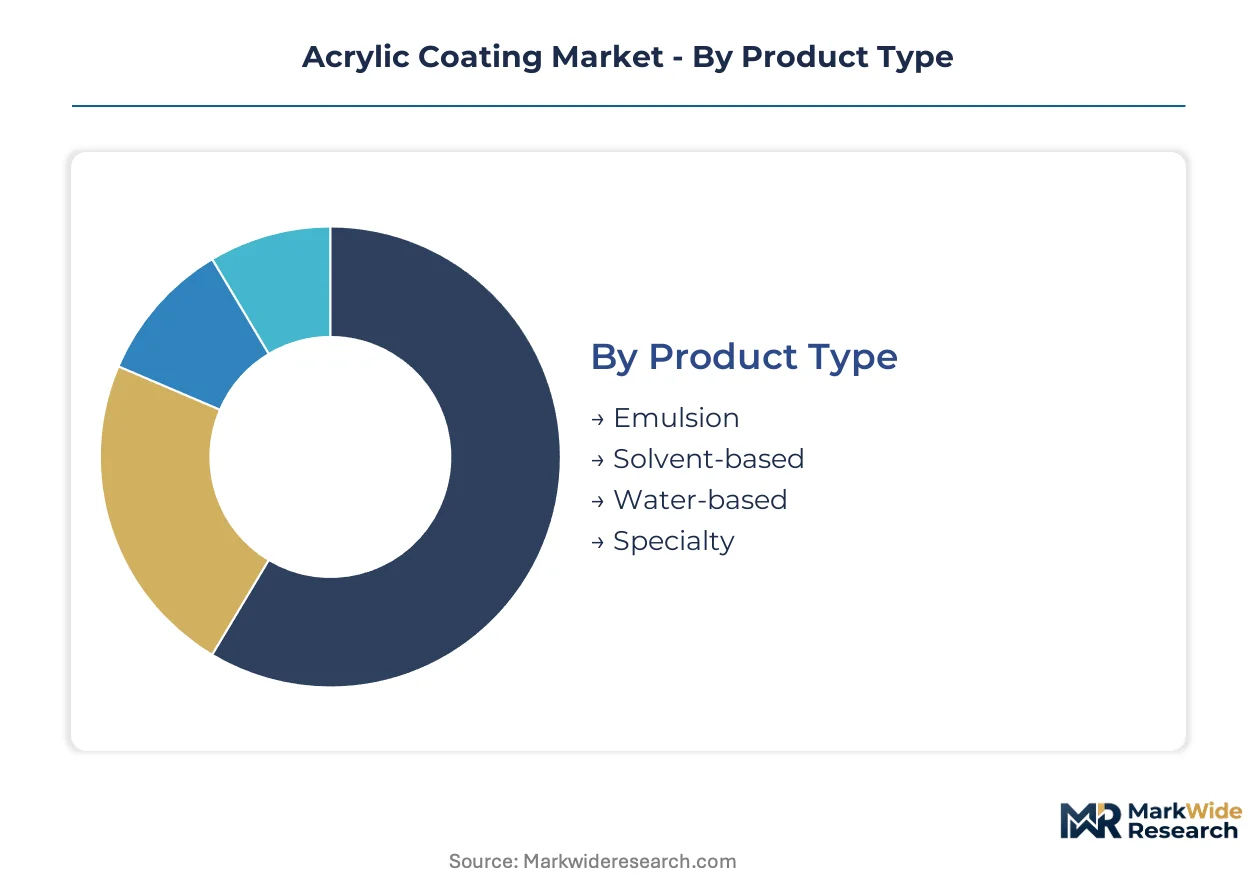
Acrylic coating segmentation reveals how formulation chemistry, application environment, and procurement channel interact to determine margin structure. Product type and application splits expose where waterborne compliance investments concentrate versus where solvent-grade performance still commands premium pricing.
Product Type:
Water-based emulsion systems dominate architectural volume while solvent-based formulations retain automotive and aerospace margin concentration.
- Emulsion:Acrylic polymer particles dispersed in aqueous medium with surfactant stabilization, typically 40-60% solids content. Demand concentrates in residential repaint and new construction across coastal US states where EPA VOC limits are most stringent, though freeze-thaw stability constraints limit northern climate specification.
- Solvent-based:Thermoplastic acrylic resins dissolved in hydrocarbon or oxygenated solvents, delivering superior chemical resistance and gloss. Automotive refinishing shops in Germany, Italy, and Japan specify these systems for clearcoat repair where waterborne alternatives fail on appearance match.
- Water-based:Lower-VOC alternatives to conventional solvent systems using coalescing aids for film formation at ambient temperatures. BIS certification requirements in India are accelerating substitution of solvent decorative paints in Mumbai and Delhi metropolitan construction.
- Specialty:UV-curable, powder, or high-solids formulations for niche industrial applications. Offshore wind tower manufacturers in Denmark specify UV-acrylic repair systems for rapid cure in low-temperature marine environments.
Today's leader: Emulsion. Tomorrow's challenger: Specialty.
Application:
Automotive and industrial applications pull high-performance formulation investment while architectural volume sustains resin producer scale economics.
- Automotive:OEM basecoats, clearcoats, and refinishing systems requiring chip resistance, UV durability, and color stability. Electric vehicle battery enclosure coatings in China specify ceramic-filled acrylic primers for thermal management and dielectric isolation.
- Architectural:Interior and exterior decorative finishes on residential, commercial, and institutional structures. Urban housing stock expansion in India positions decorative emulsion demand for sustained volume growth as BIS quality standards elevate.
- Industrial:Protective coatings for steel infrastructure, processing equipment, and manufacturing facilities. Bridge rehabilitation programs in Texas and California now require 10-15 year warranty terms, forcing direct qualification with asset managers.
- Aerospace:Exterior topcoats and specialty primers for commercial and military aircraft. REACH SVHC restrictions on chromate-containing systems are accelerating urethane-modified acrylic adoption across European MRO facilities.
Architectural commands volume scale. Aerospace captures value per liter.
End User:
Procurement authority is fragmenting across the value chain as infrastructure owners disintermediate traditional distributor networks.
- Manufacturers:OEMs and fabricators applying coatings in controlled factory environments. Automotive assembly plants in China and India are integrating paint shops with resin supply through backward integration into captive emulsion production.
- Contractors:Professional applicators executing field installation on construction and maintenance projects. North American painter networks are migrating toward platform-based material procurement, bypassing traditional distributor markups on standard architectural grades.
- Distributors:Wholesalers and retailers intermediating between producers and smaller contractors or DIY consumers. Margin compression from direct digital channels is forcing specialty focus on technical support and color-matching services.
- Consumers:DIY purchasers of touch-up, maintenance, and small-project coatings. EU F-Gas Regulation phase-down is restricting hydrofluorocarbon propellants in aerosol products, forcing compressed gas or pump-spray reformulation.
Manufacturers set technical specifications. Contractors determine brand selection.
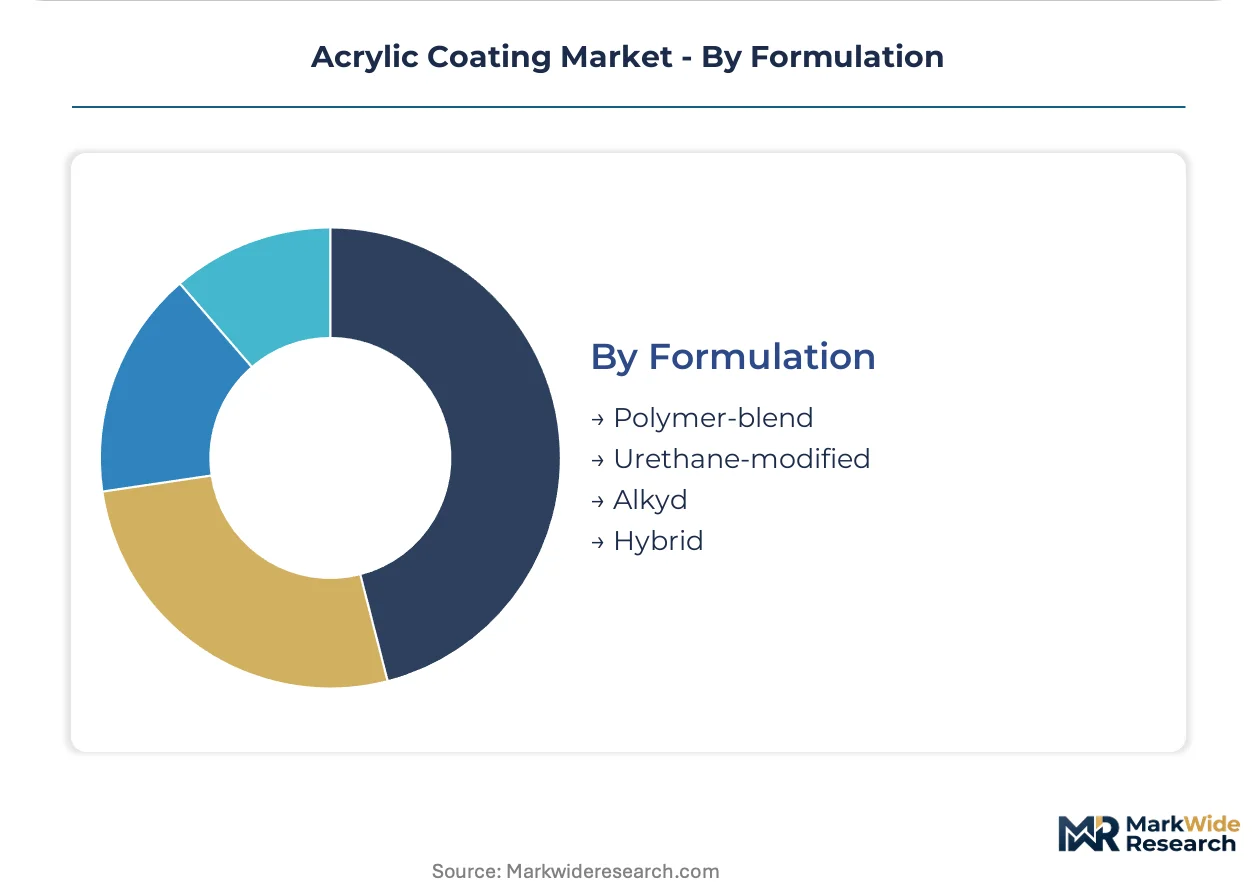
Formulation:
Hybrid architectures are displacing single-resin systems as end users seek regulatory compliance without sacrificing performance.
- Polymer-blend:Physical mixtures of acrylic with vinyl acetate, styrene, or other cost-modifying resins. Volume construction in India and Southeast Asia relies on these formulations for cost-competitive decorative coverage.
- Urethane-modified:Acrylic-urethane hybrid chemistry bridging waterborne delivery with solvent-grade hardness and flexibility. ECHA's evolving SVHC candidate list is accelerating substitution of isocyanate-containing systems across European industrial maintenance coatings.
- Alkyd:Oil-modified polyester resins with acrylic co-reaction for enhanced durability. Decorative trim and siding applications in coastal US markets specify self-crosslinking alkyd-acrylic hybrids for gloss retention and chalk resistance.
- Hybrid:Multi-chemistry systems combining acrylic with epoxy, silicone, or fluoropolymer components. LED-optimized photoinitiator packages are opening specification windows in industrial wood and plastic coating lines as mercury lamp phase-out proceeds under Minamata Convention obligations.
Urethane-modified is gaining specification fastest. Polymer-blend defends volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower compliance-cost burdens, though formulation standards are converging as regulators harmonize VOC thresholds across major economies.
United States
Automotive refinishing demand concentrates in Michigan and Ohio assembly corridors, while coastal states enforce EPA VOC limits that accelerate waterborne formulation adoption. California Air Resources Board protocols prefigure broader North American alignment on emission thresholds. Houston and Gulf Coast chemical clusters supply acrylic acid and methyl methacrylate feedstocks to domestic coating producers.
China
Electric vehicle manufacturing scale-up in Guangdong and Zhejiang provinces pulls advanced resin demand from refinishing into primary automotive production. MIIT dual carbon goals and GB standards on industrial emissions tighten formulation requirements for domestic producers. Yangtze River Delta coating plants are integrating captive emulsion production to secure resin supply.
Germany
REACH SVHC restrictions on isocyanate-containing systems accelerate urethane-modified acrylic substitution across industrial maintenance coatings. ECHA dossier updates and F-Gas Regulation phase-down schedules elevate compliance costs for aerosol and repair product lines. Bavarian and North Rhine-Westphalia chemical producers dominate European photoinitiator and light stabilizer supply.
India
Urban housing stock expansion in Maharashtra and Gujarat positions decorative emulsion demand for sustained volume growth. BIS quality standards elevate product substitution rates in Mumbai and Delhi metropolitan construction markets. Tamil Nadu and Karnataka industrial zones concentrate demand for corrosion-resistant acrylic barriers on steel infrastructure.
Japan
Automotive clearcoat repair specifications in Osaka and Nagoya manufacturing clusters sustain solvent-grade formulation demand despite waterborne advances. METI industrial standards and JIS certification requirements constrain permissible chemistries in coating operations. Kanto region refinishing shops specify high-performance acrylic topcoats where appearance match requirements exceed waterborne capabilities.
Acrylic Coating Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated resin-coating producers fund waterborne formulation lines to capture architectural volume. The vendor base separates into three tiers: multinational chemical conglomerates with captive resin supply, regional coating specialists with dense distribution networks, and niche technology providers focused on UV-curable and hybrid systems. Strategic archetypes include backward-integrated feedstock controllers, specification-driven premium formulators, and scale-focused emulsion commodity producers. M&A activity concentrates on photoinitiator and additive technology assets, while geographic expansion targets Indian and Southeast Asian manufacturing clusters.
Among North American coating producers, PPG Industries Inc. and The Sherwin-Williams Co. occupy positions that exemplify divergent channel strategies—global color-matching infrastructure versus retail and professional contractor density. Axalta Coating Systems LLC represents the mobility-focused specialization archetype, anchoring its competitive position in vehicle refinishing and commercial transport segments where performance specifications resist commodity substitution.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| The Sherwin-Williams Co. |
| Axalta Coating Systems LLC |
| Akzo Nobel N.V. |
| BASF SE |
| Dow |
| Asian Paints |
| Jotun |
| Arkema |
| Others |
Supply Flow & Price Mechanics
OEM automotive procurement teams in China and India command volume-based pricing leverage that compresses margins for standard emulsion grades while specialty formulations retain premium positioning. This buyer concentration forces suppliers to absorb methyl methacrylate feedstock volatility or risk contract loss to integrated resin producers with captive supply.
Pricing Analysis
Distributor markups on architectural emulsions are compressing as North American painter networks migrate toward platform-based procurement, bypassing traditional channel layers. Three-tier pricing structure across premium, standard, and economy levels separates self-crosslinking architectural finishes from commodity construction grades and import-dependent budget tiers. Pricing pressure stems from REACH compliance investments in European markets, where reformulation costs concentrate among non-integrated producers. DIY consumers exhibit highest price sensitivity, while aerospace MRO facilities prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States anchor hub-and-spoke patterns for acrylic acid and methyl methacrylate feedstocks. Photoinitiator and hindered amine light stabilizer supply draws from Bavarian chemical clusters and Chinese specialty producers, creating single-geography exposure for UV-curable formulation lines. Tariff exposure on propylene derivatives intensifies when olefin supply tightens in Gulf Coast petrochemical corridors. Distribution runs through qualified applicator networks in automotive refinishing, while architectural grades shift toward direct contractor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation cost differentials between REACH-regulated Europe and BIS-standard India create geographic-arbitrage opportunities for multi-plant producers with transferable technology platforms.
For Market Incumbents: Extend waterborne formulation expertise into urethane-modified hybrids to defend against specialty chemical entrants with solvent-grade performance claims. Backward integration into captive emulsion production secures resin supply as propylene derivative markets tighten. Capacity addition in Gujarat and Tamil Nadu industrial zones captures Indian architectural demand growth while meeting localized BIS certification requirements. For New Entrants and Emerging Players: The mid-tier price gap between PPG-Sherwin-Williams premium positioning and unbranded commodity imports offers specification entry through certified contractor networks in Texas and Florida bridge rehabilitation programs. Target industrial maintenance coatings for European offshore wind infrastructure, where ECHA SVHC restrictions disqualify established isocyanate-containing suppliers. Digital platform partnerships with North American painter networks bypass distributor markups on standard architectural grades. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive resin supply are the most active acquirers in this space, consolidating photoinitiator and light stabilizer technology assets. Long-term viability hinges on hybrid formulation capabilities bridging regulatory compliance with solvent-grade performance specifications. Watch LED-optimized photoinitiator package adoption rates in industrial wood coating lines as mercury lamp phase-out accelerates under Minamata Convention obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | Secures methyl methacrylate supply against propylene naphtha spread volatility in Gulf Coast corridors. |
| REACH-Compliant Formulation Line Investment | Enables European industrial maintenance specification as ECHA SVHC restrictions tighten. |
| LED-Optimized Photoinitiator Development | Captures industrial wood coating demand as Minamata Convention mercury lamp phase-out proceeds. |
| Direct-to-Contractor Digital Platform Launch | Bypasses distributor markups on standard architectural grades in North American painter networks. |
| Indian Manufacturing Cluster Expansion | Positions for BIS-certified decorative emulsion demand growth in Maharashtra and Gujarat urban construction. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with resin plant managers, coating procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up and top-down triangulation reconciles formulation-grade demand with regional regulatory cluster analysis.
Rate-of-change decomposition separates volume drivers from value migration across the analysis window, modeling segmentation dimensions including formulation chemistry, application environment, end-use vertical, and regional production hub. CAGRs derive from regression analysis against feedstock price indices and regulatory compliance cost trajectories, with electric vehicle manufacturing scale-up and REACH substance restriction timelines as key forecast inputs.
Caveats apply where petrochemical feedstock volatility, photoinitiator supply disruptions, or accelerated state-level EPA VOC adoption could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Metal Finishing Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Transparent Conductive Coatings Market
Coatings
US Industrial Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Coating Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Germany Industrial Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Automotive Refinish Coatings Market