
 In-Mold Coatings Market | 2026-2036
In-Mold Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
In-Mold Coatings Market Outlook
Multi-source procurement among tier-one automotive suppliers is expanding as OEMs diversify coating partnerships to reduce supply risk. PPG Industries leverages its North American manufacturing footprint to sustain just-in-time delivery contracts with Detroit-area automakers. Akzo Nobel N.V. anchors European demand through its Rotterdam-based R&D campus focused on low-VOC polyurethane systems. BASF SE differentiates via captive resin production, extending backward integration into aliphatic isocyanate feedstocks for premium automotive grades.
In-mold coatings are thermoset or thermoplastic formulations applied directly to mold surfaces before polymer injection, curing simultaneously with the substrate to form bonded, decorative, or protective surface layers; typical systems achieve 20-40 micrometer dry film thickness with pencil hardness ratings of 2H-4H. Polyurethane formulations dominate value pools due to superior scratch resistance and soft-touch aesthetics in automotive interiors. Spray coating technology leads installation share but powder coating is gaining traction where zero-VOC compliance is mandatory. Epoxy systems occupy industrial equipment segments where chemical resistance outweighs flexibility requirements.
EPA regulations in the United States limit hazardous air pollutant emissions from coating operations, while REACH and the EU Green Deal impose substance restrictions and carbon footprint disclosure on European suppliers. Japan's METI enforces JIS standards for automotive interior air quality, directly influencing coating formulation chemistry. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing product platforms across multinational OEM supply contracts.
Market Dynamics
Automotive OEMs are consolidating supplier relationships around coating systems that simultaneously satisfy scratch-resistance specifications and EU Green Deal carbon footprint disclosure rules, compressing qualification timelines from 18 months to under 12 months.
Growth Catalysts
- REACH substance restrictions:European coating formulators are accelerating low-VOC polyurethane development to preempt 2025 emission limit tightening, pulling demand toward compliant in-mold systems.
- Automotive interior soft-touch specifications:Scratch-resistant 2H-4H pencil hardness ratings are becoming mandatory for dashboard and door panel applications across German and Japanese OEM supply chains.
- Aliphatic isocyanate feedstock availability:Captive resin production in Germany and the United States is stabilizing supply for premium automotive grades.
Market Restraints
- Aliphatic isocyanate cost volatility:Feedstock price swings of 15-25 percent annually compress coating margins for non-integrated formulators.
- Spray coating equipment concentration:Installation expertise clusters in Detroit, Stuttgart, and Nagoya, creating 6-8 month lead times for new production lines.
- Epoxy flexibility limitations:Rigid thermoset chemistry disqualifies in-mold systems from seating and armrest applications where 180-degree bend testing is required.
Strategic Opportunities
- India automotive manufacturing expansion:Maruti Suzuki and Hyundai Motor India are localizing plastic component production, creating first-mover advantage for coating suppliers establishing technical service centers.
- Powder coating zero-VOC compliance:Mandatory VOC disclosure under EU Green Deal corporate sustainability reporting is accelerating powder system trials at French and Italian Tier-1 suppliers.
- Digital twin mold simulation:Convergence of computational fluid dynamics with coating thickness prediction software is reducing prototype iterations from 12 to 4 cycles.
Industry Challenges
- Polyurethane formulation chemistry expertise:Shortage of resin synthesis engineers with 10+ years of aliphatic isocyanate handling experience is extending R&D team buildout timelines.
- Dual-cure process validation:Simultaneous substrate injection and coating cure requires mold temperature control within 2 degrees Celsius, demanding capital-intensive precision equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Mold Coatings Market |
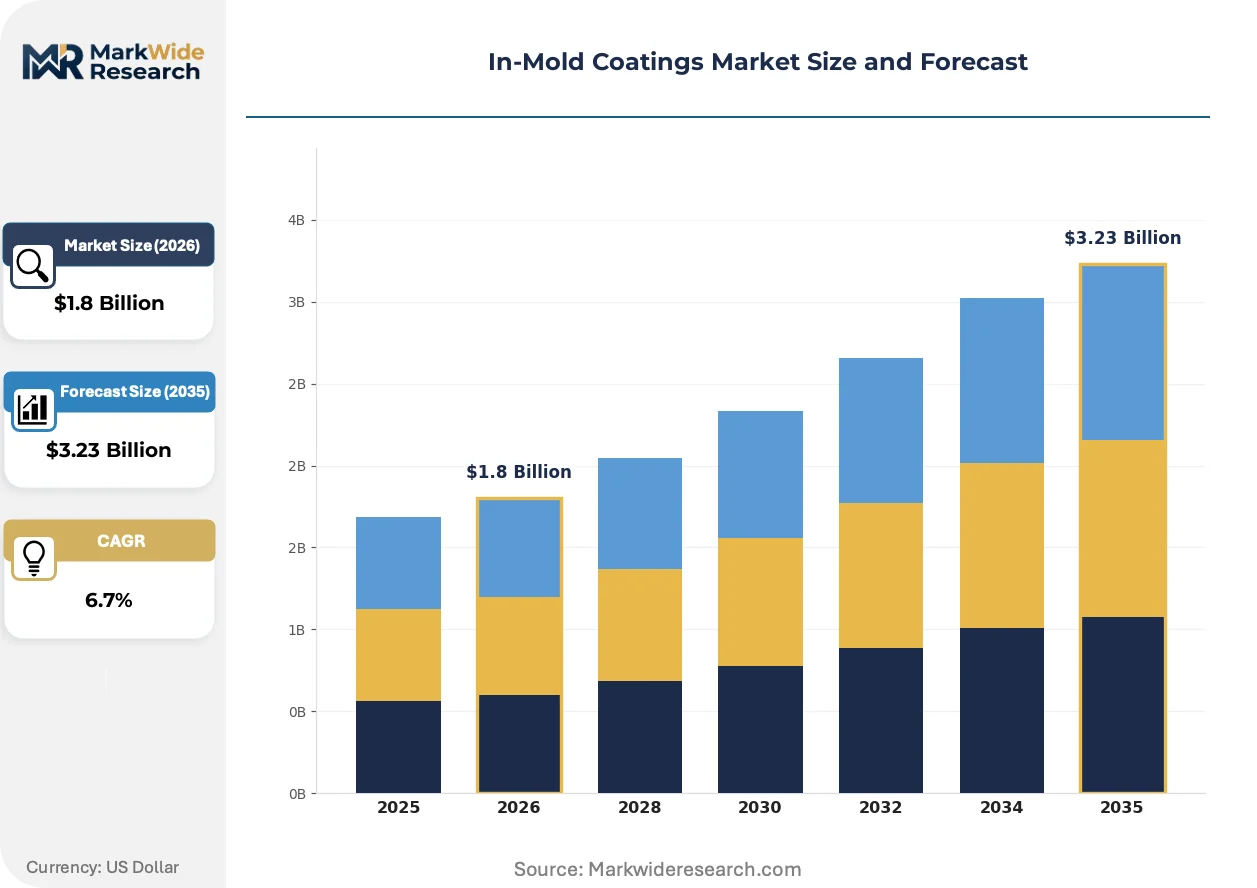
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Polyester Application: Automotive, Consumer Goods, Industrial Equipment, Electronics End User: Manufacturers, Retailers, Distributors, OEMs Technology: Spray Coating, Liquid Coating, Powder Coating, Roll Coating |
| Companies Covered | Nippon Paint Automotive Coatings, Arkema, Akzo Nobel N.V., Kansai Nerolac, The Sherwin-Williams Company, PPG Industries, Uchihamakasei Corp., Mold-Tek Packaging, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Mold Coatings Market Strategic Shifts
Coating-mold integration is advancing through three parallel vectors: digital simulation tools compressing development cycles, regulatory disclosure requirements rewiring procurement criteria, and automotive interior specifications elevating performance thresholds.
Self-healing polyurethane formulations containing microencapsulated repair agents are electrifying scratch-recovery capabilities in luxury vehicle segments. German OEMs are piloting these systems on center console trim pieces ahead of 2026 model year launches. The technology is compressing warranty claim exposure for surface damage while enabling thinner 15-20 micrometer film builds.
EPA hazardous air pollutant emission limits are forcing coating operations above threshold throughput to install thermal oxidizers or switch to powder systems. Michigan and Ohio-based automotive suppliers are consolidating spray booths to capture economies of scale on abatement equipment. The regulatory pressure is segmenting the supplier base between capital-rich integrators and smaller job shops exiting the market.
Automotive procurement teams are unbundling coating supply from molding contracts, creating direct material specification authority that bypasses Tier-1 intermediaries. This pattern is most visible in Japanese keiretsu supply chains where Toyota and Honda are issuing coating performance standards directly to PPG and BASF. The disintermediation is compressing commercial negotiation cycles while elevating technical service requirements.
In-Mold Coatings Market Segmentation
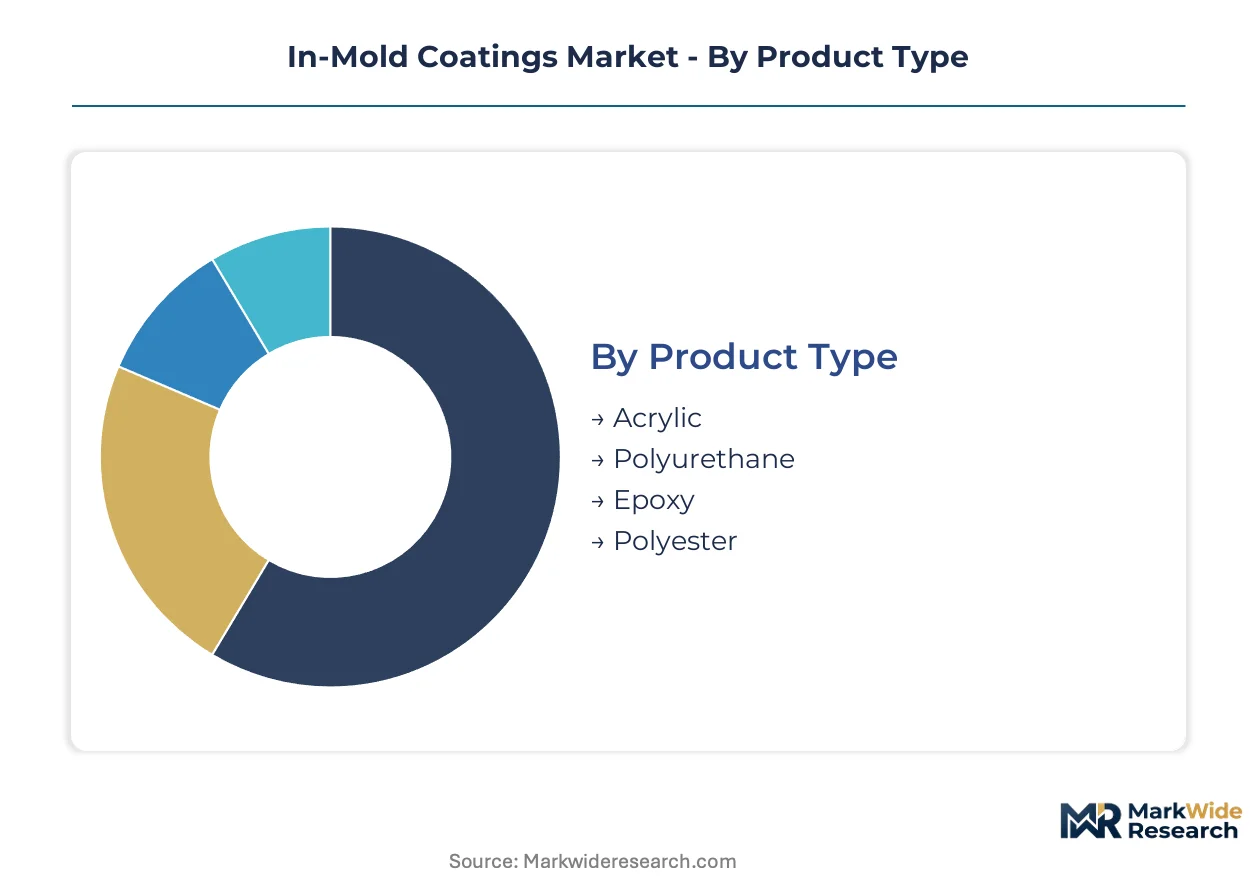
Segmentation in the in-mold coatings market reveals how formulation chemistry, application method, and end-use specifications create distinct compliance and performance requirements. Each dimension carries different certification burdens from EPA, REACH, and automotive OEM qualification protocols.
Product Type:
REACH substance restrictions and EPA hazardous air pollutant rules impose varying formulation disclosure requirements across these chemistries, with aliphatic isocyanate handling triggering the strictest workplace safety protocols.
- Polyurethane:Aliphatic isocyanate-based systems deliver 2H-4H pencil hardness with soft-touch aesthetics. Demand concentrates in German and Japanese automotive interiors where scratch-resistance specifications are mandatory for dashboard and door panel applications.
- Acrylic:Thermoplastic formulations offer faster cure cycles and lower capital equipment requirements. Consumer goods manufacturers in the United States favor these systems for cost-sensitive packaging applications where UV stability outweighs abrasion resistance.
- Epoxy:Rigid thermoset chemistry dominates industrial equipment segments where chemical resistance supersedes flexibility requirements.
- Polyester:Saturated formulations serve powder coating conversions seeking zero-VOC compliance under EU Green Deal disclosure rules.
Leading the category by volume: Polyurethane. Growing fastest: Polyester.
Application:
End-use sectors diverge sharply in performance thresholds, with automotive OEMs demanding 18-month qualification cycles while industrial equipment tolerates 6-month validation timelines.
- Automotive:Interior and exterior plastic components require simultaneous substrate bonding, decorative finish, and 20-40 micrometer dry film thickness control. German OEMs are consolidating supplier relationships around systems satisfying both scratch-resistance specifications and EU Green Deal carbon footprint disclosure rules.
- Consumer Goods:Packaging and appliance housings prioritize cost efficiency over durability. Japanese electronics brands specify these coatings for handheld device enclosures where thin-film builds reduce material consumption.
- Industrial Equipment:Chemical processing machinery and agricultural implements demand epoxy-based protection against solvent exposure and weathering.
- Electronics:Precision components require static-dissipative formulations with controlled surface resistivity for circuit board housings and connector assemblies.
Automotive commands the largest value share. Electronics is expanding most quickly on miniaturization trends.
End User:
Procurement authority patterns determine whether coating specifications flow through Tier-1 intermediaries or issue directly from OEM material engineering teams.
- OEMs:Automotive original equipment manufacturers are unbundling coating supply from molding contracts, creating direct specification authority that bypasses traditional intermediaries. Toyota and Honda keiretsu structures exemplify this disintermediation pattern.
- Manufacturers:Tier-1 plastic component producers operate captive coating lines or outsource to qualified job shops depending on throughput scale and capital availability.
- Distributors:Regional chemical distributors serve fragmented industrial equipment and consumer goods segments where order quantities fall below direct mill minimums.
- Retailers:Private-label product brands specify coating performance indirectly through contract manufacturer agreements.
OEMs drive the steepest margin premiums. Manufacturers represent the broadest addressable base.
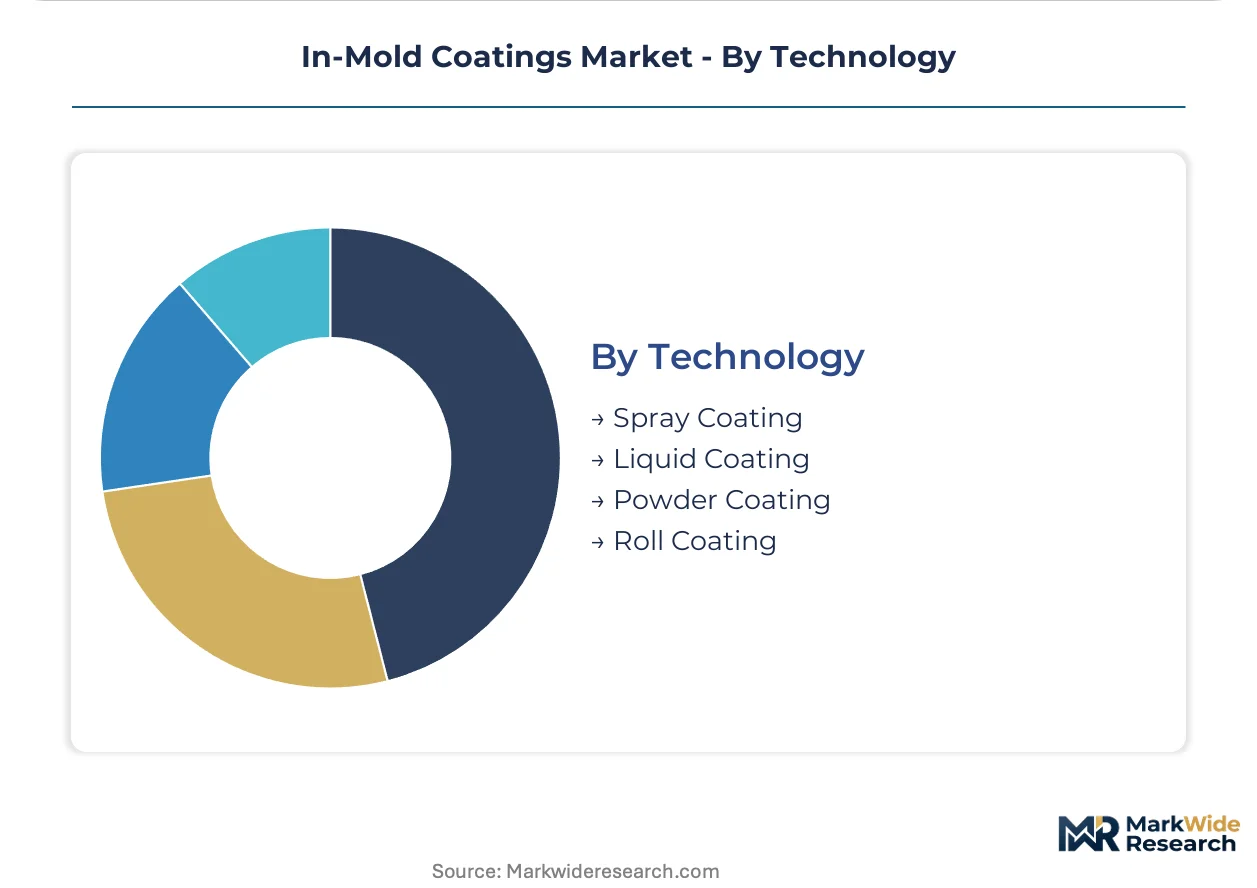
Technology:
Installation expertise availability and VOC compliance mandates create divergent capital intensity profiles across application methods.
- Spray Coating:Dominant installation technology achieving precise film thickness control through robotic application. Equipment expertise clusters in Detroit, Stuttgart, and Nagoya, creating 6-8 month lead times for new production line commissioning.
- Powder Coating:Zero-VOC systems are gaining traction where EU Green Deal corporate sustainability reporting mandates disclosure. French and Italian Tier-1 suppliers are accelerating trials ahead of mandatory compliance deadlines.
- Liquid Coating:Conventional solvent-borne and water-borne formulations serve legacy automotive exterior applications and industrial equipment refurbishment.
- Roll Coating:Continuous web processes suit flat panel consumer goods and electronics substrates where uniform thin films are required across large surface areas.
Spray coating retains the largest installed base. Powder coating is climbing the fastest on regulatory pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing clusters in Germany, Japan, and the United States concentrate in-mold coating consumption, with regulatory divergence across EPA, REACH, and METI jurisdictions reshaping supplier qualification protocols.
United States
Detroit-area automakers drive polyurethane system demand for interior soft-touch applications. EPA hazardous air pollutant emission limits force coating operations above threshold throughput to install thermal oxidizers or convert to powder systems. Michigan and Ohio-based Tier-1 suppliers consolidate spray booths to capture economies of scale on abatement equipment.
Germany
Automotive OEMs in Stuttgart and Munich mandate scratch-resistant 2H-4H pencil hardness ratings for dashboard and door panel specifications. REACH substance restrictions and EU Green Deal carbon footprint disclosure rules compress supplier qualification timelines from 18 months to under 12 months. BASF SE anchors European demand through captive aliphatic isocyanate production at its Ludwigshafen complex.
Japan
Toyota and Honda keiretsu structures disintermediate Tier-1 suppliers by issuing coating performance standards directly to formulators. METI enforces JIS standards for automotive interior air quality, directly influencing polyurethane formulation chemistry. Nagoya-based equipment expertise clusters create 6-8 month lead times for new spray coating production lines.
India
Maruti Suzuki and Hyundai Motor India localize plastic component production, creating first-mover advantage for coating suppliers establishing technical service centers. The country's national automotive regulator aligns with BIS standards for material safety in vehicle interiors. Tamil Nadu and Gujarat automotive corridors attract coating formulators seeking proximity to expanding OEM assembly plants.
China
Domestic automotive brands accelerate in-mold coating adoption for electric vehicle interior differentiation. MIIT oversees GB standards compliance for automotive material emissions and workplace chemical handling. Yangtze River Delta manufacturing hubs concentrate mold-making expertise that supports coating-mold integration trials.
In-Mold Coatings Market Competitive Environment
Strategic partnerships dominate the current landscape as formulators align with automotive OEMs to compress 18-month qualification cycles. The supplier base organizes into three tiers: integrated resin producers with captive feedstock control, regional specialists with mold-maker alliances, and commodity distributors serving fragmented industrial segments. Two competitive vectors define positioning: backward integration into aliphatic isocyanate supply chains, and geographic expansion through technical service center establishment in emerging automotive manufacturing corridors.
Among European-headquartered multinationals, Akzo Nobel N.V. and BASF SE exemplify the integrated archetype through Rotterdam-based R&D concentration and Ludwigshafen feedstock control respectively. Arkema occupies a position within specialty chemical portfolios where acrylic and polyester formulation expertise serves powder coating conversions. Japanese specialists including Nippon Paint Automotive Coatings and Uchihamakasei Corp. sit within keiretsu-anchored supply relationships that bypass traditional Tier-1 procurement channels. North American players PPG Industries and The Sherwin-Williams Company represent scale-driven coating portfolios with automotive refinish heritage extending into OEM specification authority.
| Leading Market Players |
|---|
| Nippon Paint Automotive Coatings |
| Arkema |
| Akzo Nobel N.V. |
| Kansai Nerolac |
| The Sherwin-Williams Company |
| PPG Industries |
| Uchihamakasei Corp. |
| Mold-Tek Packaging |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Aliphatic isocyanate grade bifurcation separates premium automotive polyurethane systems from commodity industrial coatings, with this performance ladder determining both margin capture and supply chain depth. REACH-compliant low-VOC formulations command substantial premiums through captive resin production in Germany and the United States, while standard grades compete on throughput scale in fragmented job-shop networks.
Pricing Analysis
Volume concentration in spray coating installations compresses margins for non-integrated formulators, while powder coating systems capture premium positioning through EU Green Deal zero-VOC compliance. Price differentiation separates automotive OEM-specified grades from industrial refurbishment tiers, with aliphatic isocyanate feedstock volatility driving cost compression across non-captive producers. Tier-1 automotive procurement teams exhibit lowest price sensitivity where scratch-resistance specifications and carbon footprint disclosure rules overlap.
Supply Chain Analysis
Return flows of expired automotive coatings and mold refurbishment cycles create secondary material channels that compete with virgin resin supply. Raw material sourcing draws from German aliphatic isocyanate complexes, Japanese polyol production, and Chinese solvent intermediates. Single-source vulnerability concentrates in specialty isocyanate handling expertise clustered around Stuttgart and Nagoya. Distribution runs through direct mill relationships with automotive OEMs and regional chemical distributors serving industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-mold coatings sector sits at a powder-coating transition inflection, with zero-VOC systems displacing legacy solvent-borne spray installations under regulatory mandate. This technology replacement cycle compresses qualification timelines while elevating capital requirements for compliant production infrastructure.
For Market Incumbents: Extend captive resin production backward into aliphatic isocyanate feedstocks to defend margin position against feedstock volatility. Consolidate technical service center footprints in Tamil Nadu and Gujarat to anchor India automotive expansion. Accelerate powder coating R&D investment ahead of EU Green Deal mandatory disclosure deadlines to preempt competitor qualification. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for low-VOC polyurethane specialists to establish first-mover positioning with French and Italian Tier-1 suppliers. Target electronics segment penetration where miniaturization trends demand precision thin-film control below automotive qualification barriers. Pursue mold-maker alliance strategy to bypass traditional spray coating equipment lead time constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated chemical conglomerates seeking automotive specification authority. Five-to-ten year viability favors formulators with backward integration into isocyanate supply and powder coating technology portfolios. Monitor EPA enforcement intensity around thermal oxidizer mandates as inflection signal for spray-to-powder conversion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic Isocyanate | Captive feedstock production stabilizes margin exposure for German automotive-grade suppliers. |
| Powder Coating Capacity Expansion | Zero-VOC installation addresses EU Green Deal disclosure requirements for Italian Tier-1 networks. |
| Technical Service Center Establishment | Proximity to Maruti Suzuki and Hyundai Motor India assembly plants accelerates qualification cycles. |
| Digital Twin Mold Simulation Investment | Computational fluid dynamics integration reduces prototype iterations for Japanese OEM qualification. |
| Long-term Supply Agreement with OEMs | Direct specification authority through Toyota and Honda keiretsu structures bypasses Tier-1 intermediaries. |
Study Parameters
Multi-period observation of coating-mold integration trials, regulatory disclosure filings, and automotive qualification timelines anchored the trend analysis, supplemented by interviews with resin synthesis engineers, Tier-1 automotive procurement leads, mold equipment specialists, and ECHA regulatory affairs directors. Secondary validation drew from customs trade data, SEC chemical company filings, automotive production databases, and REACH substance restriction announcements. Bottom-up segment sizing triangulated against top-down automotive plastics consumption estimates.
Input-output matrices mapped aliphatic isocyanate feedstock availability to polyurethane formulation output across chemistry grade, application method, and end-use industry dimensions. CAGRs derived from regression analysis against automotive production forecasts and regulatory compliance deadline schedules. Forecast inputs included powder coating adoption curves, spray coating equipment installation lead times, and OEM unbundling of coating supply from molding contracts.
The model assumes a particular technology adoption path; alternative pathways for self-healing polyurethane formulations would alter the outlook if German OEM pilot programs achieve scale. Forecasts reflect assumptions around REACH enforcement intensity and EPA thermal oxidizer mandate thresholds. Practitioners should monitor EU Green Deal corporate sustainability reporting adoption rates and India automotive corridor investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Temperature Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Performance Coating Market
Coatings
FBE Coatings Market
Coatings
Acrylic Coating Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Global Anti Slip Coatings Market
Coatings
Batters and Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
US Protective Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Carpet Back Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Global Heat Resistant Coatings Market