
 South Korea Marine Coatings Market | 2026-2036
South Korea Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Marine Coatings Market Analytics
Water-based epoxy formulation technology is fragmenting the traditional solvent-based marine coatings stack in South Korean shipyards. Hempel A/S anchors its position through captive supply relationships with major Korean shipbuilders. KCC Corporation leverages domestic manufacturing scale to compete on delivery speed for naval refit contracts. PPG Industries differentiates through specialized anti-fouling systems designed for East Asian biofouling conditions.
Marine coatings are protective layers applied to submerged and atmospheric zones of vessels, typically comprising epoxy resins, zinc-rich primers, and biocide-loaded topcoats that prevent corrosion and biological attachment while reducing hull friction. Anti-fouling formulations dominate volume demand from commercial vessels operating on Korea-Japan and Korea-China routes, where biofouling accumulation drives frequent dry-dock cycles. Specialty coatings for naval ships command premium positioning due to signature-management requirements and extended interval specifications between maintenance events.
MFDS chemical substance registration, Ministry of Oceans and Fisheries VOC discharge permits, and KOSHA industrial safety standards collectively constrain coating formulation choices and application protocols in Korean yards. Compliance with these frameworks elevates R&D costs for foreign suppliers while creating regulatory shelter for domestic compounders with established certification pathways. Stakeholders must monitor pending amendments to the Clean Air Conservation Act that would further restrict solvent-based systems in coastal shipbuilding zones.
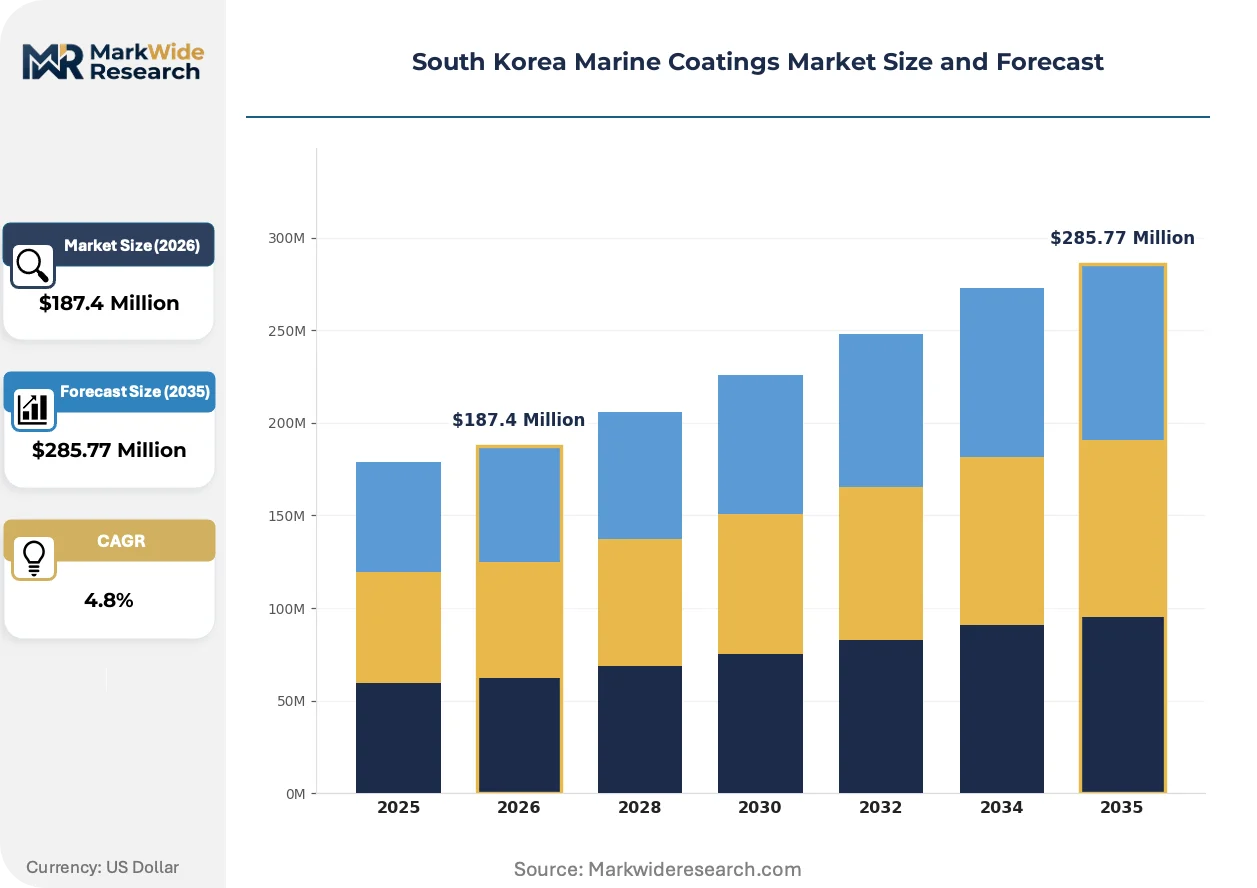
Market Dynamics
Water-based epoxy technology is fragmenting South Korea's solvent-dominated marine coatings stack, forcing dry-dock operators to retool application equipment and reformulate procurement specifications around VOC compliance.
Growth Catalysts
- Fleet refurbishment cycles:Commercial vessel operators across Busan and Ulsan port clusters are accelerating hull recoating programs to meet extended charter terms and fuel efficiency targets.
- MFDS chemical substance registration:The regulatory framework is consolidating formulation standards, creating certification shelter for domestic compounders with established compliance pathways.
- Anti-fouling biocide innovation:New copper-free and silicone-hybrid systems are extending dry-dock intervals for vessels operating Korea-Japan and Korea-China routes.
Market Restraints
- Epoxy resin input volatility:Petrochemical feedstock fluctuations compress margin buffers for coating formulators serving price-sensitive shipyard contracts.
- Supply concentration in Gyeongsang coast:Hyundai Heavy Industries and Samsung Heavy Industries yards control disproportionate volume allocation, creating dependency risk for specialty coating suppliers.
- Clean Air Conservation Act amendments:Pending solvent restrictions in coastal shipbuilding zones threaten stranded asset risk for traditional formulation capacity.
Strategic Opportunities
- Naval signature-management coatings:Republic of Korea Navy fleet modernization is opening premium positioning for radar-absorbent and infrared-suppressive formulations with extended maintenance intervals.
- KOSHA industrial safety alignment:Stricter yard safety protocols are creating pull for low-flashpoint, waterborne systems that reduce fire risk during enclosed-space application.
- East Asian biofouling specialization:Regional fouling organism profiles differ from Atlantic and Mediterranean basins, enabling formulation customization for local operating conditions.
Industry Challenges
- Applicator skill transition:Water-based system spray characteristics differ substantially from solvent-borne formulations, requiring retraining of certified coating inspectors across Ulsan and Geoje yard workforces.
- Multi-certification timeline compression:Suppliers must secure concurrent MFDS registration, Ministry of Oceans and Fisheries discharge permits, and shipyard-specific qualification protocols to bid on major refit contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Marine Coatings Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Anti-fouling, Anti-corrosion, Heavy-duty, Specialty Application: Commercial Vessels, Yacht, Fishing Boats, Naval Ships End User: Shipbuilders, Fleet Operators, Maintenance Providers, Marine Service Companies Technology: Water-based, Solvent-based, Powder Coating, Epoxy |
| Companies Covered | Hempel A/S, KCC Corporation, AkzoNobel NV, Nippon Paint Holdings, Chugoku Marine Paints, Jotun, PPG Industries, Kansai Paint, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Marine Coatings Market Evolving Landscape
Formulation chemistry and regulatory enforcement are converging to compress the solvent-borne coating lifecycle while elevating performance specifications for extended dry-dock intervals.
Silicone-hybrid anti-fouling technology is hybridizing the traditional biocide-loaded topcoat segment by combining fouling-release surface properties with mechanical durability suited to high-speed commercial routes. Korean shipbuilders operating Busan-Ulsan corridors are piloting these systems on container vessels and LNG carriers. The technology is hybridizing competitive positioning by enabling suppliers to command premium pricing against conventional copper-based formulations while meeting tightening discharge standards.
Ministry of Oceans and Fisheries VOC discharge permits are tightening application protocols in coastal shipbuilding zones, mandating enclosed spray booth capture systems and real-time emission monitoring. Dry-dock operators face capital expenditure requirements for exhaust treatment infrastructure. Naval refit facilities in Jinhae and Pyeongtaek are most affected, accelerating migration to water-borne primers and intermediate coats.
Shipyard procurement specifications are consolidating around lifecycle cost models rather than unit price metrics, compressing supplier evaluation cycles and elevating technical service requirements. Korean container line operators now require coating system warranties spanning five-year dry-dock intervals. The shift is most visible in Gyeongsang coast newbuild contracts, where performance guarantees influence award decisions ahead of initial material cost.
South Korea Marine Coatings Market Segmentation
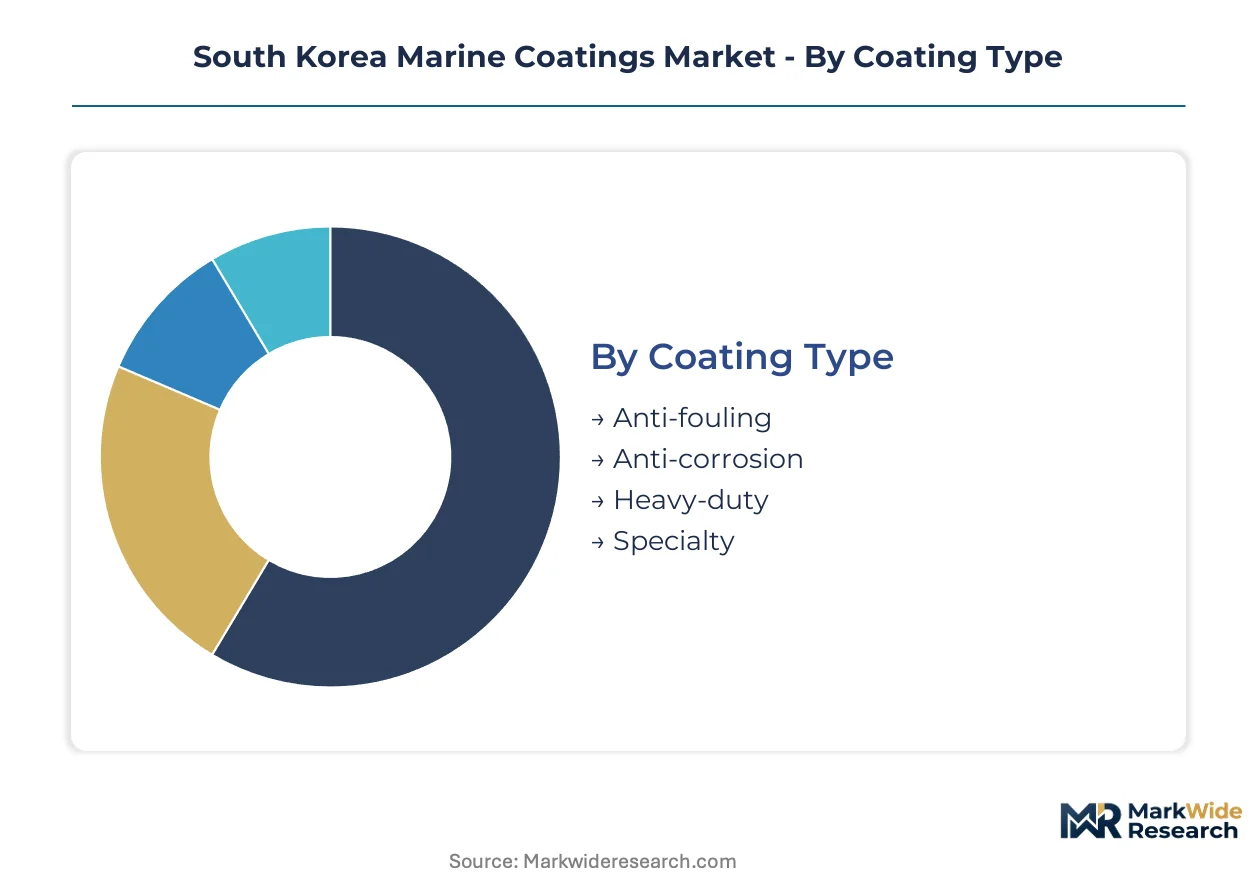
Segmentation in South Korea's marine coatings market reveals how dry-dock cycle frequency, regulatory compliance burden, and vessel operating profiles fragment demand across formulation types and customer channels. Understanding these divides exposes where margin concentrates and where volume turns over fastest.
Coating Type:
Anti-fouling formulations turn over fastest with 2-3 year dry-dock intervals, while specialty coatings stretch to 7-10 year cycles, creating divergent revenue recognition patterns for suppliers.
- Anti-fouling:Biocide-loaded topcoats prevent biological attachment on hulls operating Korea-Japan and Korea-China routes. Container lines at Busan port cluster drive demand for copper-free and silicone-hybrid systems that extend intervals between underwater cleaning.
- Anti-corrosion:Zinc-rich primers and epoxy barrier coats protect steel substrates in submerged and splash zones. Hyundai Heavy Industries and Samsung Heavy Industries yards specify these systems for newbuilds requiring 25-year hull integrity guarantees.
- Heavy-duty:High-build epoxy and polyurethane systems withstand mechanical abrasion in cargo holds and deck areas. Demand concentrates from bulk carriers loading coal and iron ore at Gwangyang and Pohang terminals.
- Specialty:Radar-absorbent and infrared-suppressive formulations serve Republic of Korea Navy signature-management requirements. Jinhae naval base refit facilities specify extended 10-year maintenance intervals for these premium systems.
Anti-corrosion anchors the volume base while anti-fouling gains share at the steepest rate as biofouling regulations tighten.
Application:
Commercial vessel operators prioritize fuel efficiency through hull smoothness, while naval specifications emphasize signature suppression and extended maintenance windows.
- Commercial Vessels:Container ships, bulk carriers, and tankers dominate tonnage demand. Operators across Busan and Ulsan corridors specify coatings that reduce hull friction for IMO carbon intensity compliance.
- Naval Ships:Republic of Korea Navy destroyers and submarines require stealth-optimized formulations. Pyeongtaek and Jinhae facilities drive premium positioning through low-observable specification requirements.
- Yacht:Recreational craft at Geoje and Tongyeong marinas demand aesthetic finishes with UV stability. Fleet size remains limited compared to commercial and naval segments.
- Fishing Boats:Small-scale operators along Jeolla and Gyeongsang coasts prioritize cost over performance. Local maintenance yards serve this price-sensitive channel with basic anti-corrosion systems.
Commercial vessels anchor the volume base while naval ships gain share at the steepest rate through fleet modernization programs.
End User:
Shipbuilders consolidate procurement through long-term supply agreements, while maintenance providers fragment across regional dry-dock clusters with varying technical capabilities.
- Shipbuilders:Hyundai Heavy Industries, Samsung Heavy Industries, and Daewoo Shipbuilding & Marine Engineering specify coatings during newbuild construction. These customers demand system warranties and technical service support across 3-5 year construction cycles.
- Fleet Operators:Korean container lines and bulk carriers manage in-house recoating programs. HMM and Pan Ocean maintain approved vendor lists with lifecycle cost evaluation criteria.
- Maintenance Providers:Independent dry-dock operators at Busan, Ulsan, and Geoje serve third-party vessel owners. These customers prioritize delivery speed and MFDS compliance documentation.
- Marine Service Companies:Specialized contractors handle underwater hull cleaning and spot repair. Demand concentrates from operators seeking to extend intervals between full dry-dock events.
Shipbuilders anchor the volume base while fleet operators gain share at the steepest rate as vertical integration into coating procurement accelerates.
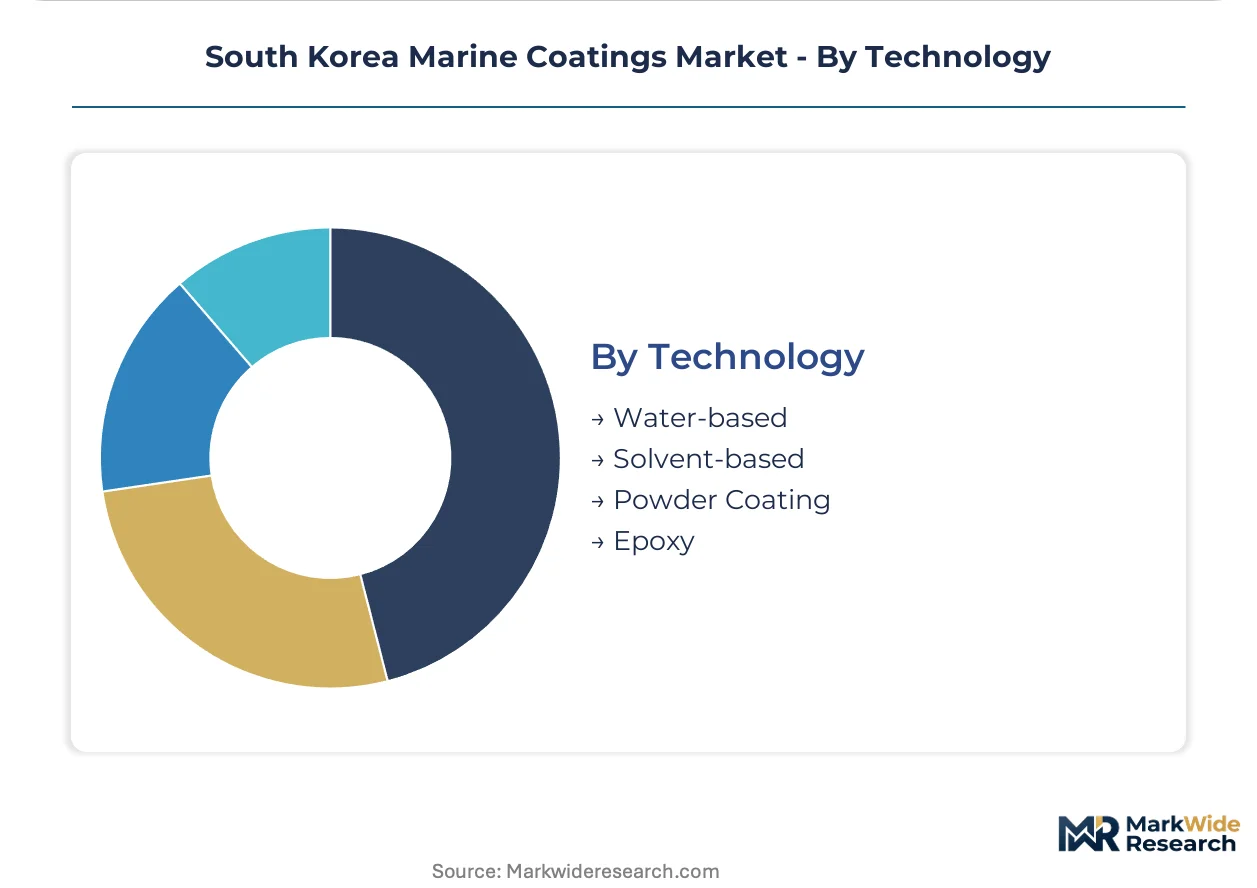
Technology:
Water-based systems displace solvent formulations as Ministry of Oceans and Fisheries VOC discharge permits tighten, forcing capital retooling across Ulsan and Geoje application facilities.
- Water-based:Epoxy and acrylic dispersions reduce volatile organic compound emissions during spray application. Korean yards are converting enclosed booths to capture systems compliant with Clean Air Conservation Act amendments.
- Solvent-based:Traditional high-solids epoxies and polyurethanes retain performance advantages in harsh marine environments. Share is compressing as regulatory pressure mounts in coastal shipbuilding zones.
- Epoxy:Two-component amine-cured systems dominate primer and intermediate coat specifications. These formulations balance chemical resistance with application window flexibility demanded by Korean yard schedules.
- Powder Coating:Thermoset epoxy and polyester powders serve superstructure and deck equipment applications. Limited use in hull coatings due to substrate size constraints and field repair complexity.
Epoxy anchors the volume base while water-based gains share at the steepest rate through regulatory-driven specification conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean marine coatings exports flow primarily to shipowners in Japan, China, and Southeast Asia, with Busan and Ulsan serving as the dominant formulation and application hubs for regional vessel refurbishment programs.
Busan-Ulsan Corridor
Container ship recoating drives demand along this southeastern coastal cluster, with HMM and Pan Ocean operating dedicated dry-dock facilities. Ministry of Oceans and Fisheries VOC discharge permits mandate enclosed spray booth retrofits across Ulsan yard complexes. Hyundai Heavy Industries and Samsung Heavy Industries anchor newbuild coating procurement through long-term supply agreements.
Geoje Island Complex
LNG carrier construction concentrates coating specifications for cryogenic cargo containment systems. Daewoo Shipbuilding & Marine Engineering specifications favor extended-interval anti-fouling systems for vessels operating Korea-Japan routes. The island's isolated geography complicates raw material logistics, elevating inventory carrying costs for formulators.
Jinhae Naval Base
Republic of Korea Navy destroyer and submarine refit programs command premium specialty coatings with signature-management requirements. MFDS chemical substance registration creates compliance barriers for foreign suppliers bidding on naval maintenance contracts. The base's restricted access limits competitive participation to pre-qualified domestic compounders.
Pyeongtaek Port Zone
Roll-on/roll-on vessel operators prioritize rapid turnaround coating systems to maintain schedule integrity on Korea-China ferry routes. KOSHA industrial safety standards enforce low-flashpoint formulation requirements for enclosed vehicle deck applications. Independent dry-dock operators compete on delivery speed against larger yard complexes.
Seoul Capital Area
Coating formulator headquarters and R&D laboratories cluster in Seongnam and Pangyo technology corridors. MFDS registration documentation and shipyard qualification protocols are administered from central government offices. Technical service teams dispatch from this region to support application troubleshooting at distant yard locations.
South Korea Marine Coatings Market Competitive Landscape
On the supply side, the industry is consolidating around formulation specialists with established regulatory certification pathways and captive relationships with major Korean shipbuilders. European and Japanese multinationals compete against domestic compounders through differentiated technology portfolios. Two strategic archetypes dominate: global coating houses leveraging R&D scale, and regional specialists optimizing for local regulatory compliance. M&A activity targets water-based formulation capabilities, while strategic partnerships secure shipyard qualification protocols.
Among European-based multinationals, Hempel A/S and AkzoNobel NV exemplify the global technology archetype, occupying positions that emphasize formulation innovation and cross-regional service networks. Japanese specialists Chugoku Marine Paints and Nippon Paint Holdings represent the Asia-Pacific regional focus, anchoring competitive positioning through proximity to Korean shipyard clusters and alignment with East Asian biofouling conditions. Domestic compounder KCC Corporation sits within the local regulatory compliance tier, leveraging established MFDS registration pathways to defend position in naval and commercial refit segments.
| Leading Market Players |
|---|
| Hempel A/S |
| KCC Corporation |
| AkzoNobel NV |
| Nippon Paint Holdings |
| Chugoku Marine Paints |
| Jotun |
| PPG Industries |
| Kansai Paint |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Ulsan yard complexes concentrate formulation capacity for solvent-based epoxies, concentrating pricing power among domestic compounders with captive supply relationships while forcing foreign suppliers to absorb logistics premiums for water-based system conversions.
Pricing Analysis
Solvent-to-water formulation pricing gaps separate incumbent premium tiers from emerging standard positions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with naval signature-management coatings commanding the highest positioning. Cost compression in standard tiers is intensifying because shipyard procurement teams consolidate vendor lists around lifecycle cost models. Fleet operators at Busan and Ulsan corridors show least price sensitivity for extended-interval systems, while fishing boat maintenance yards along Jeolla coast represent the most price-sensitive channel.
Supply Chain Analysis
Epoxy resin feedstock supply draws from South Korea, China, and Japan, with petrochemical complexes in Yeosu and Daesan anchoring domestic base chemical production. Zinc pigment, biocide actives, and silicone intermediates constitute critical input dependencies. Single-source vulnerability concentrates around copper-free biocide precursors subject to MFDS import documentation requirements. Distribution runs through shipbuilder-integrated procurement platforms and independent dry-dock operators with divergent technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based epoxy substitution threatens solvent-borne incumbents with stranded formulation capacity unless regulatory compliance moats are constructed ahead of Clean Air Conservation Act enforcement tightening.
For Market Incumbents: Build regulatory certification moats by accelerating MFDS registration for silicone-hybrid anti-fouling systems ahead of competitor filings. Secure backward integration into waterborne resin production to capture margin from petrochemical feedstock volatility. KOSHA industrial safety alignment creates channel control opportunities at Jinhae and Pyeongtaek facilities where foreign suppliers face qualification barriers. For New Entrants and Emerging Players: Build out technical service capabilities targeting independent dry-dock operators at Busan and Geoje with rapid-turnaround water-based system support. Naval signature-management coatings present the most penetrable premium segment given extended maintenance interval specifications and limited qualified domestic competition. Position through specialized East Asian biofouling formulation expertise rather than commodity anti-corrosion volume plays. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory shelter play because domestic compounders with established MFDS pathways capture disproportionate naval and commercial refit share as enforcement tightens. Target acquisition archetypes: mid-scale waterborne formulation specialists with shipyard qualification protocols already secured. Watch Clean Air Conservation Act amendment passage as inflection signal for accelerated solvent-based displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Conversion | Captures compliance premium as Ministry of Oceans and Fisheries VOC permits tighten across Ulsan and Geoje yards. |
| Naval Certification Investment | Secures Republic of Korea Navy refit access at Jinhae where MFDS registration barriers limit foreign participation. |
| Silicone-Hybrid Anti-Fouling Development | Extends dry-dock intervals for container lines operating Korea-Japan routes while meeting copper discharge restrictions. |
| Technical Service Network Expansion | Supports shipbuilder procurement consolidation around lifecycle cost evaluation and five-year warranty requirements. |
| Feedstock Integration | Reduces margin exposure to epoxy resin volatility from Yeosu and Daesan petrochemical complex pricing. |
Research Methodology
Desk research of customs trade databases, Ministry of Oceans and Fisheries regulatory filings, and shipyard procurement specifications preceded structured interviews with coating formulator R&D directors, dry-dock facility managers, naval maintenance procurement officers, and MFDS registration consultants. Secondary validation drew from Korea Shipowners' Association fleet data, Korean Register of Shipping classification records, and KOSHA industrial safety guidelines. Bottom-up vessel coating demand estimates triangulated against top-down marine coatings trade flow analysis.
Assumptions held fixed include regulatory enforcement timelines for Clean Air Conservation Act amendments and shipyard capacity utilization at Hyundai Heavy Industries and Samsung Heavy Industries complexes. Variables included water-based system adoption rates across commercial versus naval segments, biocide innovation cycles, and raw material cost trajectories. Segmentation modeling covered coating type, application, end user, and technology dimensions. CAGRs derived from regression analysis of historical dry-dock cycle frequencies and fleet age profiles. Forecast inputs incorporated IMO carbon intensity compliance deadlines and Republic of Korea Navy fleet modernization program scope.
Sensitivities concentrate around Clean Air Conservation Act amendment timing, epoxy resin feedstock price volatility, and shipyard consolidation effects on procurement leverage. Cross-checking against Korean Register of Shipping dry-dock inspection frequency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Silicone Coating Market
Coatings
United States Floor Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Solvent Borne Coatings Market
Coatings
Fillers and Coating Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Global Sputter Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Industrial Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
PU Coatings Market