
 Antifouling Coatings Market | 2026-2036
Antifouling Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Antifouling Coatings Market Analysis
Consolidation among container line operators and bulk fleet managers is repositioning procurement power toward fewer buyers with stricter hull-performance specifications. PPG Industries Inc. leverages its marine distribution network across North American and Asian ports to sustain long-term supply agreements with major fleet operators. Chugoku Marine Paints, Ltd. anchors its competitive stance in Japanese and Southeast Asian shipyard channels, while AkzoNobel N.V. differentiates through specialized fouling-control systems for deep-water vessels.
Antifouling coatings are protective surface treatments formulated with biocidal or non-biocidal active ingredients—typically copper-based compounds, silicone elastomers, or hybrid polymer matrices—applied to submerged marine structures to prevent biofilm, barnacle, and algal accumulation that increases drag and fuel consumption. Hard coatings and conventional coatings dominate current tonnage application due to their proven cost structure and compatibility with dry-dock schedules, though non-biocidal coatings are gaining structural share as environmental compliance tightens and self-cleaning polymer technologies mature. Marine vessels and offshore structures represent the primary application channels, with polymer-based and hybrid systems capturing expanding margin pools from operators seeking extended docking intervals.
The U.S. EPA regulates antifouling coating registration under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU enforces biocide restrictions through the Biocidal Products Regulation and REACH frameworks, collectively narrowing permissible active ingredient portfolios and elevating R&D barriers for new entrants. China's Ministry of Ecology and Environment enforces national discharge standards that align with IMO conventions, shaping formulation requirements for coatings supplied to domestic shipyards. Stakeholders must monitor evolving active-substance approval timelines across these jurisdictions to align product pipelines with compliance windows and avoid stranded inventory positions.
Market Dynamics
Shipowner procurement consolidation across container and bulk fleets is compressing supplier margins while elevating performance guarantees for hull coatings. Fleet operators now demand multi-year fuel-efficiency warranties that tie coating performance to documented voyage data, forcing reformulation investments and long-term service commitments from manufacturers.
Growth Catalysts
- IMO Antifouling Systems Convention compliance deadlines:Vessel operators face mandatory dry-dock inspections that accelerate replacement of legacy organotin-based systems with compliant copper-reduced or biocide-free alternatives.
- Silicone elastomer fouling-release coatings:Japanese and South Korean shipyards specify these low-friction systems for newbuild LNG carriers and cruise vessels seeking extended docking intervals.
- China's state-owned shipyard expansion:Independent bulk carriers and coastal tanker operators in Dalian, Shanghai, and Guangzhou drive volume demand for high-performance hull coatings with localized technical service support.
Market Restraints
- Copper price volatility and supply concentration:Chilean and Peruvian mining output disruptions transmit directly to coating raw material costs, compressing formulation margins for copper-based systems still dominating existing fleet maintenance.
- REACH authorization timelines for biocidal active substances:ECHA's prolonged substance-by-substance review creates regulatory uncertainty that freezes R&D pipelines and extends time-to-market for new antifouling chemistries.
- Technical performance gaps in non-biocidal alternatives:Silicone and fluoropolymer fouling-release coatings demonstrate inconsistent performance in static harbor conditions and tropical biofouling zones, limiting addressable vessel segments.
Strategic Opportunities
- Offshore wind foundation protection:Monopile and jacket structures in North Sea and Baltic Sea installations require specialized coating systems for splash-zone and submerged corrosion-fouling protection, opening marine infrastructure channels beyond vessel applications.
- EU Green Deal maritime decarbonization incentives:FuelEU Maritime and Emissions Trading System compliance create demand for hull coatings validated through ISO 19030 performance monitoring protocols that document verified fuel savings.
- Hybrid polymer-biocide systems:Convergence of controlled-release copper chemistry with self-polishing acrylic binders enables formulation platforms that bridge regulatory compliance and cost-performance requirements for mid-size fleet operators.
Industry Challenges
- Marine coatings chemist and application specialist shortages:Dry-dock facilities in Hamburg, Rotterdam, and Singapore compete for certified inspectors capable of verifying film thickness and surface preparation to manufacturer warranty standards.
- Active substance approval synchronization across EPA FIFRA, REACH, and MEE frameworks:Divergent data requirements and review timelines force parallel regulatory dossier investments that strain mid-size manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antifouling Coatings Market |
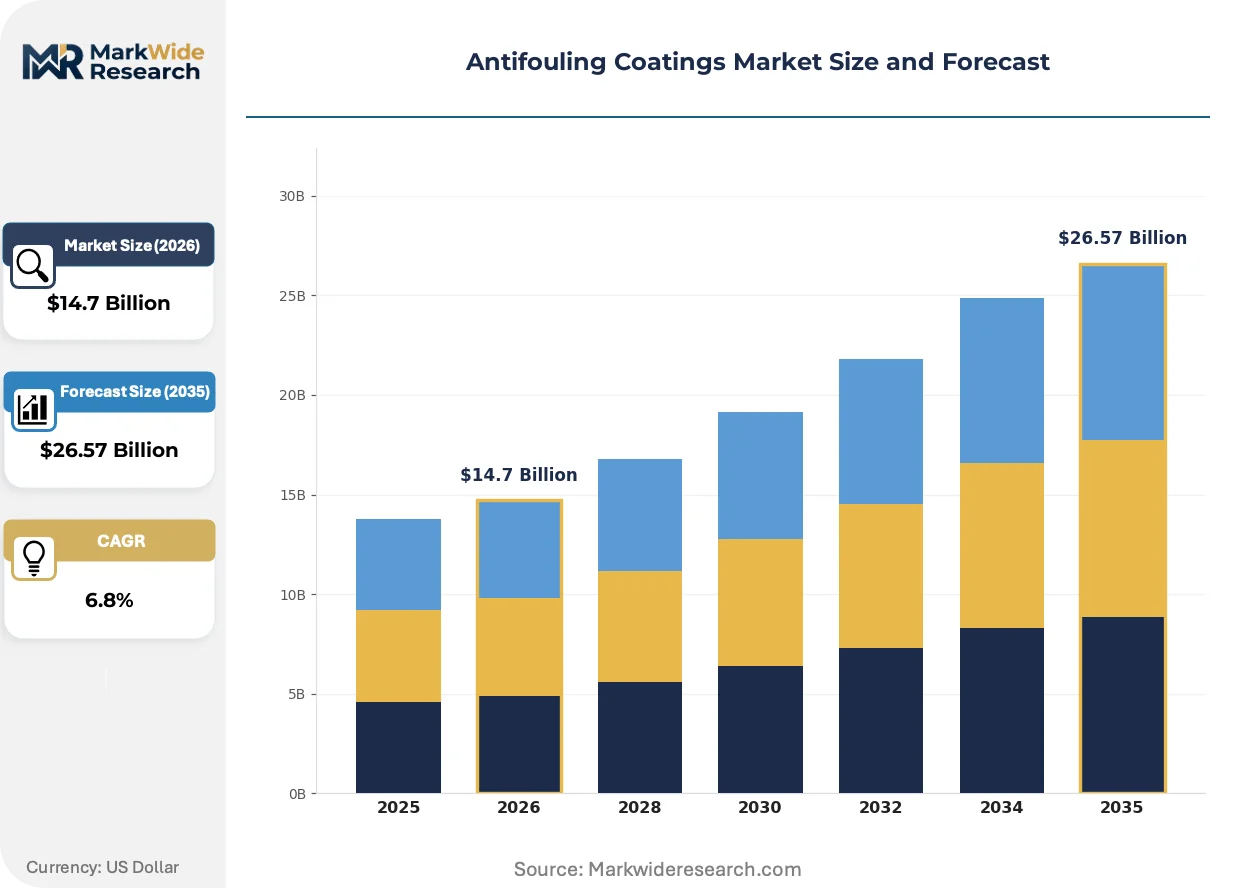
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Coatings, Conventional Coatings, Biocidal Coatings, Non-Biocidal Coatings Application: Marine Vessels, Offshore Structures, Shipbuilding, Water Treatment End User: Aerospace, Agriculture, Shipping, Oil & Gas Technology: Self-Cleaning, Biocide Release, Polymer-Based, Hybrid Systems |
| Companies Covered | PPG Industries Inc., Chugoku Marine Paints, Ltd., AkzoNobel N.V., BASF SE, Nippon Paint Marine Coatings Co., Hempel A/S, The Sherwin-Williams Company, Kansai Paint Co., Ltd., Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antifouling Coatings Market Emerging Trajectories
Formulation science is pivoting toward predictive biofouling management systems that integrate real-time hull monitoring with adaptive coating selection. This convergence of materials engineering and digital vessel operations is compressing traditional specification cycles.
Silicone-hydrogel fouling-release coatings are electrifying vessel performance benchmarking by enabling measurable fuel consumption reductions that shipowners document through satellite-verified voyage analytics. Container lines operating Asia-Europe strings adopt these systems at accelerated dry-dock frequencies. The technology is electrifying competitive positioning among coating suppliers capable of underwriting performance guarantees with third-party validation.
EPA's revised FIFRA data requirements for copper-based antifouling products are narrowing permissible efficacy claims and extending registration renewal timelines. Coating manufacturers must submit expanded environmental fate studies that elevate dossier preparation costs. The rule change most affects suppliers serving recreational and coastal commercial fleets in US waters, where alternatives face higher price-performance hurdles.
Fleet procurement offices now bundle coating selection with multi-year technical service agreements that include hull performance monitoring and predictive maintenance scheduling. This integrated contracting model displaces spot purchasing through shipyard intermediaries. The shift is most visible among German and Greek-controlled bulk carriers operating Capesize and Panamax vessels on long-haul iron ore and coal routes.
Antifouling Coatings Market Segmentation
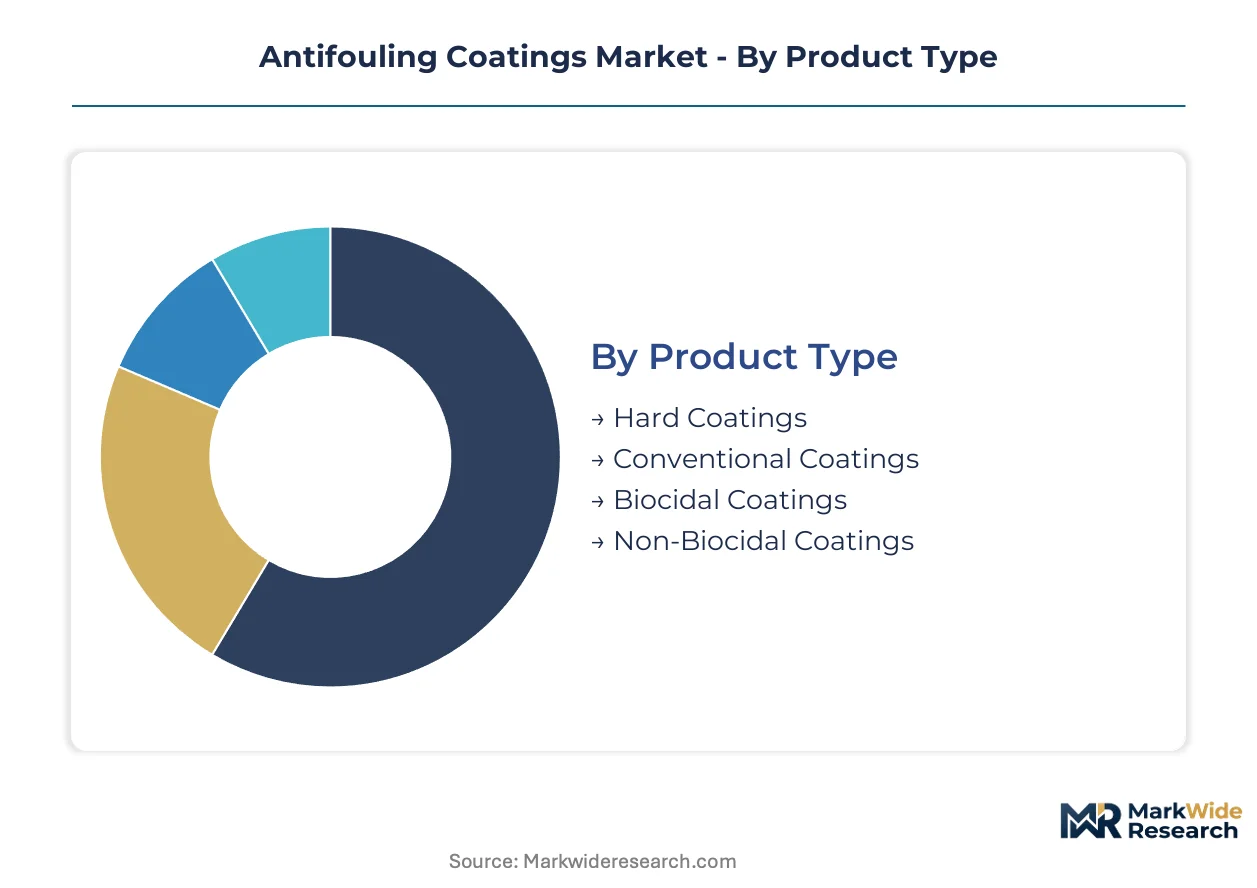
Antifouling coatings serve divergent operational profiles across vessel classes, infrastructure types, and regulatory environments. Segmentation reveals where formulation investments concentrate and which customer groups drive specification changes.
Product Type:
Upgrade cycles vary sharply by coating chemistry, with dry-dock intervals and regulatory compliance windows forcing replacement decisions.
- Hard Coatings:These epoxy-based systems form dense, abrasion-resistant films suitable for high-speed vessels and ice-class operations. Container lines operating Asia-Europe routes specify hard coatings for bulbous bows and flat bottom sections where mechanical wear peaks.
- Non-Biocidal Coatings:Silicone elastomer and fluoropolymer fouling-release systems eliminate active substance regulatory exposure. Japanese shipyards specify these for LNG carriers seeking five-year docking intervals under MEE discharge standards.
- Conventional Coatings:Self-polishing copolymer formulations with controlled copper release dominate existing fleet maintenance.
- Biocidal Coatings:Broad-spectrum systems incorporating zinc pyrithione or zineb face tightening REACH authorization timelines.
Hard coatings sit at the top of the volume ranking, with non-biocidal coatings climbing the fastest.
Application:
Surface preparation standards and environmental exposure profiles create distinct margin structures across installation environments.
- Marine Vessels:Hull coatings for container ships, bulk carriers, and tankers constitute the core revenue pool. Fleet operators in Hamburg and Singapore now bundle coating procurement with multi-year performance monitoring agreements.
- Offshore Structures:Splash-zone and submerged protection for monopile foundations demands specialized epoxy-urethane systems. North Sea wind installations drive specification of 25-year corrosion-fouling protection systems.
- Shipbuilding:Newbuild specifications favor low-friction systems validated through ISO 19030 protocols.
- Water Treatment:Intake structure and pipeline applications require copper-free formulations meeting potable water contact standards.
Marine vessels command the largest application share, while offshore structures are expanding most quickly.
End User:
Procurement sophistication varies dramatically across customer categories, with warranty terms and technical service bundling distinguishing premium relationships.
- Shipping:Container lines and bulk fleet managers consolidate purchasing across Capesize and Panamax tonnage. Greek and German-controlled operators now demand fuel-efficiency guarantees tied to satellite-verified voyage data.
- Oil & Gas:Offshore production platforms and FPSO units require coating systems validated for static immersion and tropical biofouling conditions. Brazilian pre-salt field operators specify extended-life systems reducing helicopter-assisted maintenance.
- Aerospace:Seaplane hulls and marine evacuation systems need lightweight, hydrodynamic coatings.
- Agriculture:Aquaculture net pens and intake structures use copper-reduced formulations.
Shipping dominates end-user demand, with oil and gas posting the steepest expansion trajectory.
Technology:
R&D pipelines concentrate on hybrid architectures that bridge regulatory compliance with cost-performance thresholds for mid-size operators.
- Hybrid Systems:Convergence of controlled-release copper chemistry with self-polishing acrylic binders enables platforms satisfying both IMO convention requirements and fuel-efficiency targets. South Korean shipyards specify these for mid-range tankers.
- Self-Cleaning:Silicone-hydrogel surfaces reduce adhesive strength of biofouling organisms through surface energy manipulation. Cruise operators adopt these for reduced port turnaround cleaning requirements.
- Biocide Release:Traditional copper-based controlled-release systems face narrowing active substance approvals under EPA FIFRA and REACH frameworks.
- Polymer-Based:Purely physical barrier coatings without biocidal content serve recreational and coastal commercial fleets.
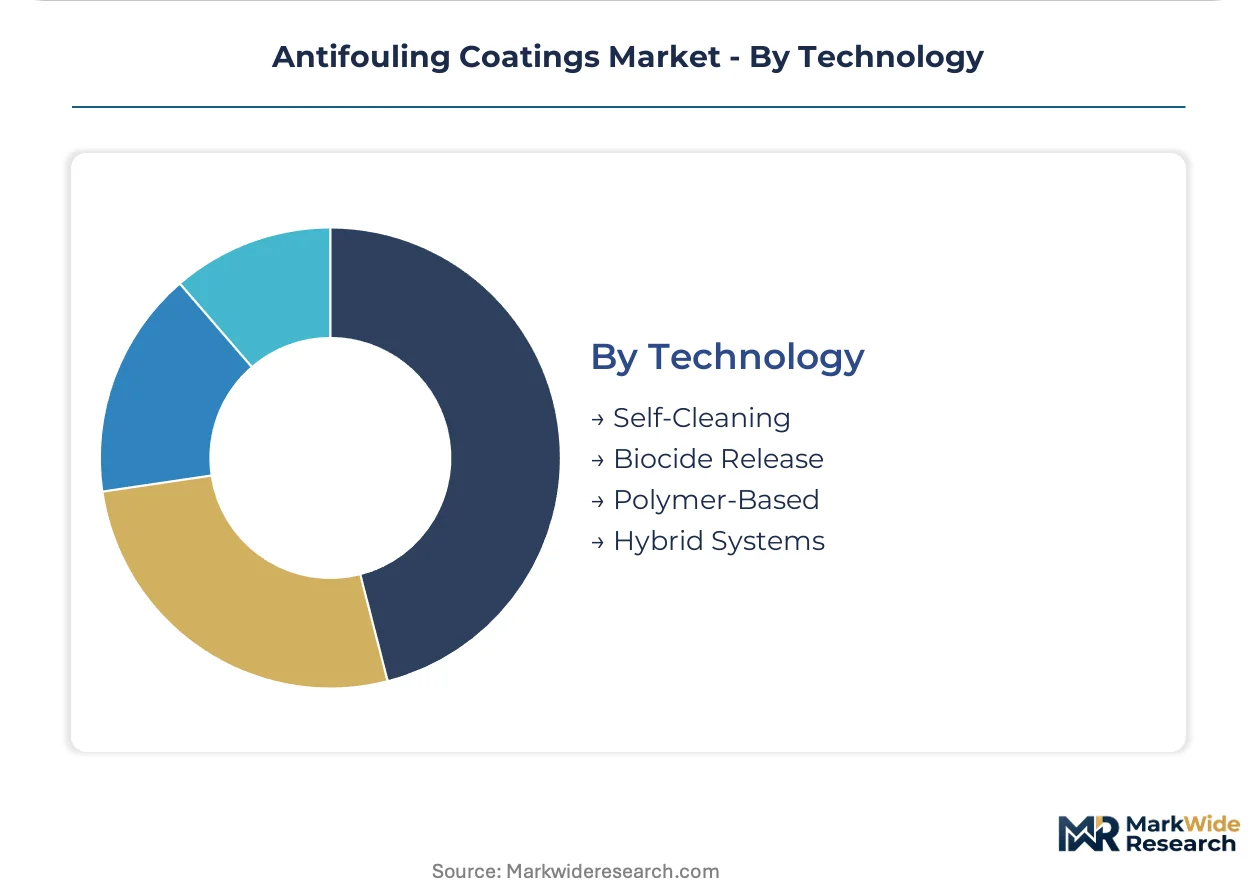
Hybrid systems lead technology deployment by volume, with self-cleaning coatings gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-owned shipyards generate coating demand volumes that dwarf Japan's specialized LNG newbuild segment, yet both markets face converging pressure from IMO environmental compliance deadlines and fleet procurement consolidation.
China
Independent bulk carriers and coastal tanker operators in Dalian, Shanghai, and Guangzhou drive volume demand for high-performance hull coatings. The Ministry of Ecology and Environment enforces national discharge standards that align with IMO conventions, shaping formulation requirements for domestic shipyard supply. State-owned shipyard expansion in the Yangtze River Delta concentrates procurement power among fewer buyers demanding localized technical service support.
Japan
Japanese shipyards specify silicone elastomer fouling-release systems for newbuild LNG carriers and cruise vessels seeking extended docking intervals. METI oversees industrial standards that accelerate adoption of low-friction coating technologies. Nagoya and Kobe maritime clusters anchor R&D investment in self-polishing polymer systems for deep-water vessel applications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries specify hybrid polymer-biocide systems for mid-range tankers and container ships. The Korean Register of Shipping validates coating performance under ISO 19030 protocols. Busan-Ulsan shipbuilding corridors concentrate demand for formulations balancing regulatory compliance with fuel-efficiency guarantees.
Germany
German-controlled bulk carriers operating Capesize and Panamax vessels now demand fuel-efficiency warranties tied to satellite-verified voyage data. ECHA's REACH authorization timelines for biocidal active substances create regulatory uncertainty that freezes some R&D pipelines. Hamburg dry-dock facilities compete for certified inspectors capable of verifying film thickness to manufacturer warranty standards.
United States
The EPA regulates antifouling coating registration under FIFRA, with revised data requirements narrowing permissible efficacy claims for copper-based products. Recreational and coastal commercial fleets in Florida and California face higher price-performance hurdles for compliant alternatives. Gulf Coast shipyards service offshore supply vessels requiring specialized splash-zone protection systems.
Antifouling Coatings Market Vendor Landscape
North American producers anchor one tier; Japanese and European specialists hold differentiated positions in premium formulation segments. The supplier base concentrates around integrated chemical conglomerates with captive resin production and dedicated marine distribution networks. Three archetypes dominate: diversified coating multinationals with port-based technical service infrastructure, regional specialists focused on shipyard channel relationships, and industrial chemical groups leveraging backward integration into biocide active ingredients. Competitive dynamics center on long-term supply agreement negotiations with consolidated fleet operators and technology licensing partnerships for silicone-hydrogel fouling-release systems.
Within the diversified multinational tier, PPG Industries Inc. and AkzoNobel N.V. exemplify port-based technical service models that sustain relationships with major fleet operators across multiple jurisdictions. Chugoku Marine Paints, Ltd. occupies a specialist position anchored in Japanese and Southeast Asian shipyard channels. These three entities represent distinct geographic and strategic orientations within a market where procurement consolidation increasingly favors suppliers capable of underwriting multi-year performance guarantees with third-party validation protocols.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Chugoku Marine Paints, Ltd. |
| AkzoNobel N.V. |
| BASF SE |
| Nippon Paint Marine Coatings Co. |
| Hempel A/S |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| Jotun |
| Others |
Supply Flow & Price Mechanics
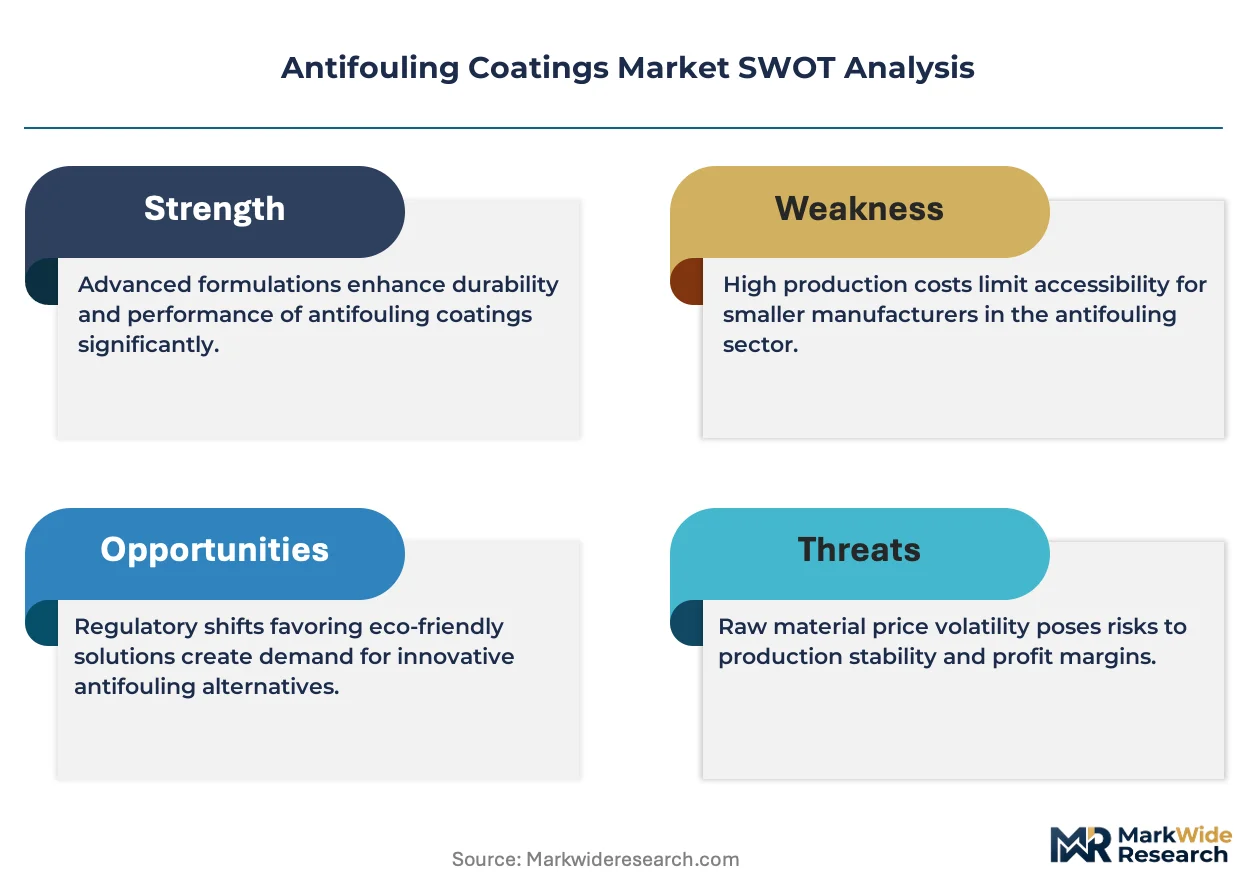
Fleet procurement consolidation across Capesize and Panamax operators is forcing coating manufacturers to absorb extended warranty costs and technical service investments, compressing formulation margins and redistributing pricing power toward volume buyers with multi-year supply agreements.
Pricing Analysis
Capacity additions in South Korean and Chinese resin production are reshaping price floors for self-polishing copolymer systems. Three-tier pricing structure across premium silicone-hydrogel, standard hybrid polymer-biocide, and economy conventional coatings separates ISO 19030-validated performance tiers from basic compliance-grade products. Cost compression in mid-tier formulations is intensifying because Chilean copper concentrate supply disruptions elevate raw material volatility. Coastal tanker operators in China exhibit highest price sensitivity, while Japanese LNG newbuild specifications demonstrate lowest elasticity due to extended-docking-interval requirements.
Supply Chain Analysis
Biocide active ingredient supply rests on German and Swiss specialty chemical producers, with silicone elastomer feedstock concentrated among Japanese petrochemical complexes. Copper oxide sourcing draws from Chilean and Peruvian mining operations, while acrylic resin production clusters in South Korea and coastal China. Single-source vulnerability in zineb and zinc pyrithione active substances under REACH authorization timelines threatens formulation continuity. Distribution runs through port-based technical service networks anchored in Rotterdam, Singapore, and Shanghai, with shipyard channel partnerships controlling last-mile specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antifouling coatings market functions as a stable compounder, with mandatory IMO compliance deadlines and fleet fuel-efficiency mandates generating replacement demand that persists across shipping cycle volatility.
For Market Incumbents: Acquire specialized silicone-hydrogel formulation capabilities to offset margin erosion from copper price volatility. Deepen backward integration into controlled-release polymer resin production in South Korea. Secure multi-year technical service agreements with Greek and German-controlled bulk carriers before emerging Asian suppliers establish port-based presence. Certification investment in ISO 19030 performance monitoring protocols represents critical defensive positioning against non-biocidal coating specialists. For New Entrants and Emerging Players: The premium-to-economy price gap in hybrid polymer-biocide systems creates entry space for mid-tier formulations targeting independent Chinese bulk carriers. Focus white-space capture on Dalian and Guangzhou shipyard channels underserved by incumbent technical service density. Aquaculture net pen applications in Norway and Chile offer penetrable segments with lower regulatory barriers than marine vessel specifications. Direct contracting with coastal tanker operators bypasses consolidated fleet procurement offices. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid coating specialists possessing captive resin production and validated ISO 19030 performance databases. Five-to-ten year viability rests on regulatory compliance positioning rather than commodity cost cycles. Target acquisition archetype: mid-scale manufacturers with established Japanese or South Korean shipyard relationships and pending REACH-compliant active substance portfolios. Watch ECHA authorization timelines for copper-reduced biocides as inflection indicator for formulation platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | South Korean and Chinese acrylic supply captivity insulates margins from petrochemical feedstock volatility. |
| ISO 19030 Performance Validation Investment | Third-party fuel-efficiency documentation secures premium positioning with German container line procurement offices. |
| Long-term Supply Agreement with Fleet Operators | Multi-year contracts with Greek bulk carriers displace spot purchasing through Rotterdam shipyard intermediaries. |
| Joint Venture for Silicone-Hydrogel Technology | Japanese petrochemical partnerships accelerate fouling-release coating access for LNG newbuild specifications. |
| Green Manufacturing Transition | Biocide-free formulation platforms align with EU Green Deal maritime decarbonization incentives and MEE discharge standards. |
Methodological Framework
Coverage spans China, Japan, South Korea, Germany, and the United States, with primary inputs from each regional cluster. The research combines structured interviews with marine coatings chemists, fleet procurement managers at container lines and bulk operators, shipyard technical specification leads, and dry-dock facility inspectors with secondary validation through IMO convention documentation, ECHA REACH authorization databases, EPA FIFRA registration filings, and customs trade data for copper oxide and acrylic resin flows. Bottom-up vessel fleet analysis and top-down chemical industry revenue triangulation anchor volume and value estimates.
Granularity-level modeling extends to coating chemistry type, vessel class specification, dry-dock interval timing, and regional regulatory compliance tier. Segmentation dimensions include product type, application environment, end-user procurement sophistication, and technology platform across the projection horizon. CAGRs derive from replacement cycle analysis tied to IMO inspection mandates and fleet fuel-efficiency upgrade patterns. Forecast inputs incorporate shipyard orderbook data from Lloyd's Register and Clarksons, plus active substance approval timelines from ECHA and EPA.
Caveats apply where copper price volatility, REACH authorization delays, or silicone-hydrogel performance gaps in tropical biofouling zones could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and fleet operator willingness to absorb premium coating costs for documented fuel savings. A small set of triggers—ECHA copper biocide restriction decisions, Chinese state-owned shipyard consolidation pace, and Japanese LNG carrier orderbook acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Extrusion Coating Market
Coatings
Electrically Conductive Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
Glass Coatings Market
Coatings
US Industrial Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Fillers and Coating Market
Coatings
Electrical Appliance Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Glazes Market
Coatings
Polymer Modified Cementitious Coatings Market